
 Vascular Guidewires Market | 2026-2036
Vascular Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Guidewires Market Outlook
Ambulatory surgical centers is unwinding the historical hospital-centric procurement model for vascular guidewires as outpatient peripheral interventions expand. Boston Scientific Corporation leverages its integrated electrophysiology and interventional cardiology platforms to sustain catheter lab loyalty. Medtronic PLC anchors its position through deep R&D investment in steerable guidewire architectures. Abbott Laboratories differentiates via specialty coronary guidewires optimized for complex lesion navigation.
Vascular guidewires are steerable, flexible wires typically constructed from nitinol, stainless steel, or hybrid cores with hydrophilic or hydrophobic polymer coatings, designed to navigate tortuous vasculature and deliver interventional devices to target lesions. Coated guidewires command premium positioning due to reduced friction coefficients that enable subtotal occlusion crossing, while nitinol's superelasticity dominates peripheral applications where kink resistance proves critical. Specialty guidewires concentrate margin pools in chronic total occlusion interventions, whereas conventional guidewires face commoditization pressure across high-volume diagnostic catheterization labs.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for nitinol-based devices entering interventional markets. Japan's PMDA and China's NMPA impose additional biocompatibility and sterilization validation standards that filter market access for non-dominant manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient peripheral vascular procedures and the material science trajectory of next-generation hybrid core constructions.
Market Dynamics
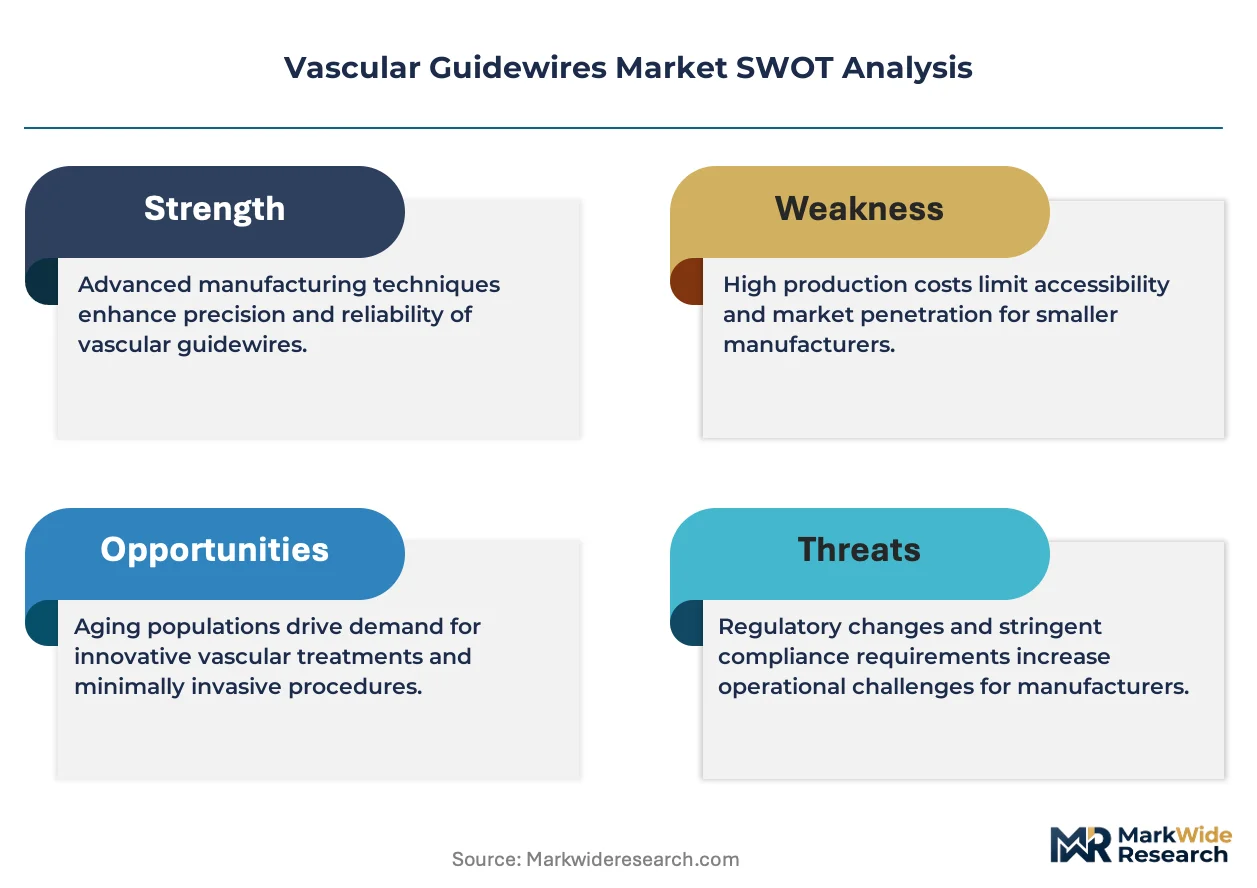
EU MDR material traceability mandates are compressing development timelines for nitinol-based guidewire manufacturers while ambulatory surgical centers accelerate the shift from hospital-centric procurement toward decentralized outpatient intervention networks.
Growth Catalysts
- EU MDR Conformity Assessment:Tightened biocompatibility documentation requirements for nitinol devices are filtering out marginal competitors and consolidating procurement toward qualified suppliers with validated sterilization protocols.
- Ambulatory Surgical Center Expansion:Outpatient peripheral vascular procedures in the United States are unwinding historical hospital catheter lab dominance through same-day discharge protocols and dedicated vascular suites.
- Hydrophilic Coating Penetration:Subtotal occlusion crossing capabilities enabled by polymer surface treatments are expanding addressable lesion complexity in interventional cardiology suites across Germany and Japan.
Market Restraints
- Nitinol Raw Material Concentration:Superelastic alloy supply chains concentrate among limited specialty metallurgical suppliers, creating input cost volatility and qualification timeline risk for device manufacturers.
- EU MDR Clinical Evidence Burden:Expanded post-market surveillance requirements for legacy guidewire portfolios are extending recertification cycles and compressing margin profiles for mid-tier manufacturers.
- Conventional Guidewire Commoditization:Diagnostic catheterization lab procurement is driving price compression on uncoated stainless steel platforms, squeezing profitability in high-volume, low-complexity segments.
Strategic Opportunities
- Chronic Total Occlusion Specialization:Complex lesion navigation capabilities command premium positioning in interventional suites performing high-risk revascularization procedures with extended procedure times.
- Hybrid Core Architecture Development:Convergence of nitinol superelasticity with stainless steel torque response is enabling next-generation steerability for tortuous peripheral anatomy.
- Japan PMDA Pathway Optimization:Streamlined biocompatibility validation frameworks for coating technologies are accelerating market access for innovative surface treatment platforms.
Industry Challenges
- Polymer Coating Validation Expertise:Hydrophilic surface treatment qualification requires specialized tribology and hemocompatibility testing capabilities that concentrate among limited contract research organizations.
- Legacy Sterilization Requalification:Ethylene oxide residual limits under EU MDR Annex I are forcing facility upgrades and process revalidation for established manufacturing lines.
- Cross-Functional Integration Complexity:Electrophysiology and interventional cardiology platform convergence demands guidewire architectures compatible with multiple imaging modalities and energy delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Guidewires Market |
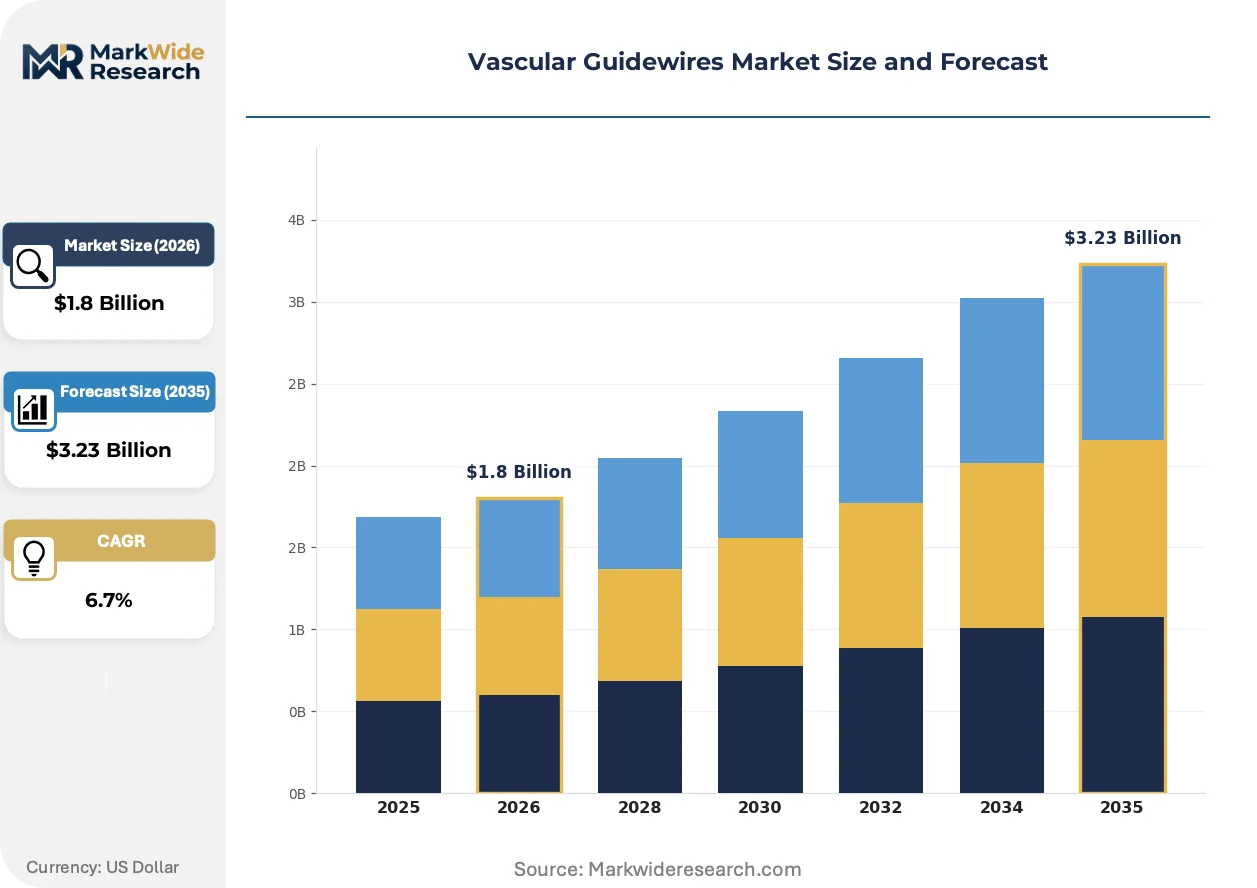
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Guidewires, Uncoated Guidewires, Conventional Guidewires, Specialty Guidewires Material: Nitinol, Stainless Steel, Polymer, Hybrid Materials Application: Cardiology, Interventional Radiology, Peripheral Vascular Intervention, Neurology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Boston Scientific Corporation, Medtronic PLC, Abbott Laboratories, Terumo Corporation, Stryker Corporation, B. Braun Melsungen AG, Cook Medical, Inc., Asahi Intecc Co., Ltd, Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Guidewires Market Strategic Shifts
Material science advances in hybrid core constructions and surface engineering are fragmenting traditional performance trade-offs between torque response and kink resistance, while regulatory documentation requirements reshape competitive qualification barriers.
Hybrid core guidewire architectures combining nitinol distal segments with stainless steel proximal shafts are fragmenting the historical segmentation between coronary and peripheral applications. Interventional suites in Germany and Japan are adopting these platforms at accelerated pace for translesional procedures spanning multiple vascular territories. The technology is fragmenting procurement patterns as single-platform versatility reduces specialty inventory requirements.
EU MDR Annex XIV post-market clinical follow-up obligations are extending evidence generation timelines for coated guidewire portfolios. Manufacturers must now maintain active surveillance registries for hydrophilic polymer performance in chronic total occlusion interventions. Peripheral vascular segments face the steepest compliance cost escalation as lesion-specific outcome documentation becomes mandatory for continued market authorization.
Catheter lab procurement committees are consolidating vendor relationships around integrated platform suppliers capable of spanning diagnostic, interventional, and electrophysiology workflows. Hospital purchasing in the United States is displacing standalone guidewire negotiations with bundled catheter lab contracts covering multiple device categories. This concentration is most visible in integrated delivery networks consolidating cardiovascular service lines under single-source agreements.
Vascular Guidewires Market Segmentation
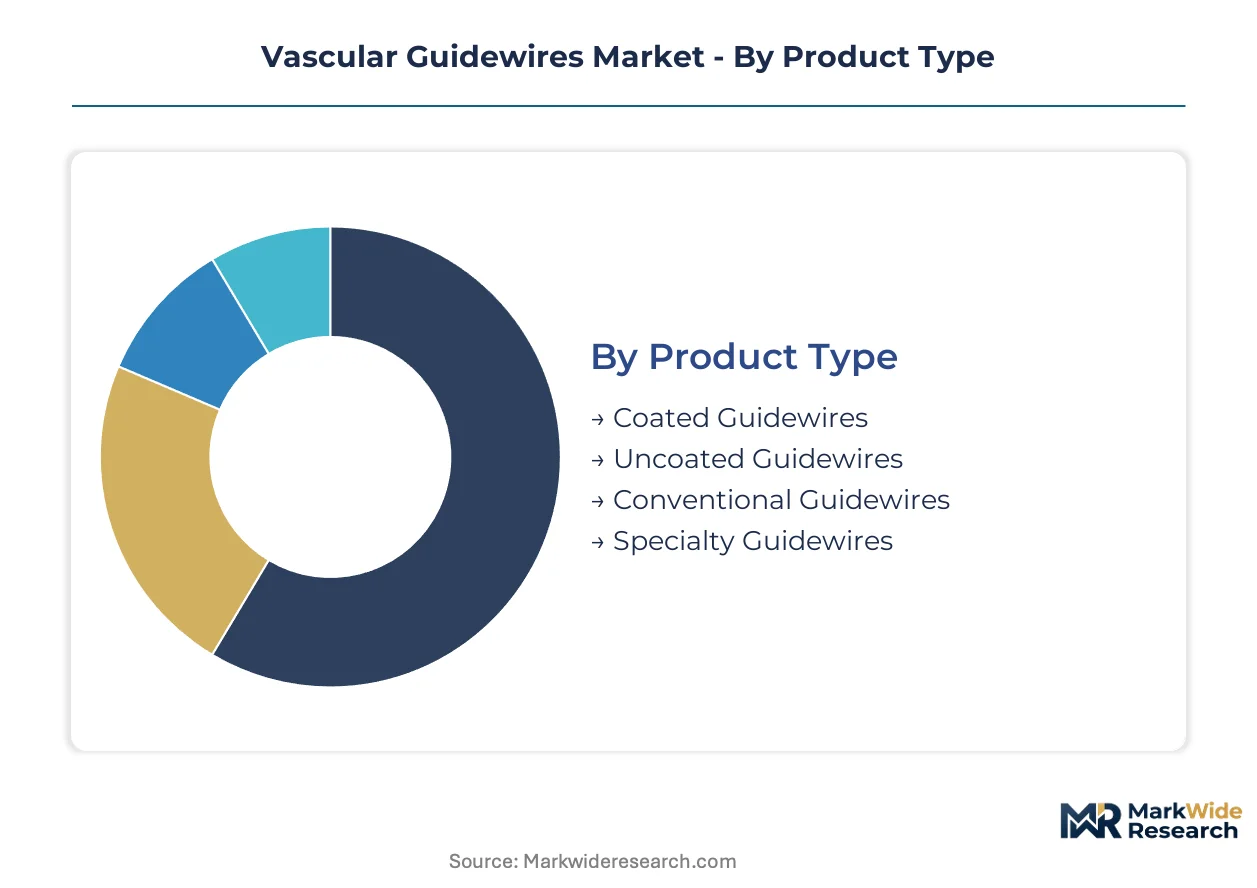
Guidewire segmentation reflects divergent technical requirements across lesion complexity and anatomical territory. Procurement patterns fragment between high-volume diagnostic suites and specialized intervention centers. Material selection and surface engineering create tiered margin structures that reshape competitive positioning.
Product Type:
Domestic demand concentrates in coated and specialty platforms for complex interventions, while uncoated and conventional segments serve export markets with cost-sensitive procurement frameworks.
- Coated Guidewires:Hydrophilic polymer surface treatments reduce friction coefficients to enable subtotal occlusion crossing. Demand clusters in interventional cardiology suites across Germany and Japan where chronic total occlusion procedures command premium positioning. FDA 510(k) pathways and EU MDR conformity assessments filter market access for coating technologies.
- Specialty Guidewires:Complex lesion navigation architectures incorporate hybrid core constructions with steerable distal segments. Peripheral vascular intervention networks in the United States are adopting these platforms for tortuous anatomy procedures with extended fluoroscopy times. Japan's PMDA imposes additional biocompatibility validation standards.
- Uncoated Guidewires:Stainless steel platforms serve diagnostic catheterization labs with standardized torque response specifications.
- Conventional Guidewires:Established nitinol or stainless steel cores address high-volume screening procedures with minimal surface modification.
Coated guidewires command the established base. The steepest expansion runs through specialty guidewires.
Material:
Cost tier differentiation separates superelastic alloys from commodity stainless steel, with hybrid constructions capturing mid-premium positioning.
- Nitinol:Nickel-titanium superelasticity delivers kink resistance critical for peripheral vascular navigation through tortuous iliac and femoral anatomy. EU MDR material traceability mandates compress development timelines for nitinol-based manufacturers. Supply chains concentrate among limited specialty metallurgical suppliers.
- Hybrid Materials:Convergence of nitinol distal segments with stainless steel proximal shafts fragments historical segmentation between coronary and peripheral applications. Interventional suites in Germany are adopting these platforms for translesional procedures spanning multiple vascular territories. The technology reduces specialty inventory requirements.
- Stainless Steel:Standardized torque transmission serves diagnostic and low-complexity interventional procedures.
- Polymer:Specialized coating substrates and jacket materials enable surface engineering for lesion-specific performance.
Nitinol commands the established base. Hybrid materials are climbing the fastest.
Application:
Volume concentration varies by procedure reimbursement and cath lab infrastructure density.
- Cardiology:Coronary intervention suites drive coated guidewire penetration for complex lesion subsets. Hydrophilic surface treatments expand addressable complexity in chronic total occlusion revascularization. Germany and Japan anchor demand for specialty coronary platforms.
- Peripheral Vascular Intervention:Ambulatory surgical centers in the United States are accelerating same-day discharge protocols for peripheral procedures. Nitinol superelasticity dominates femoropopliteal and below-the-knee applications where kink resistance proves critical.
- Interventional Radiology:Cross-specialty procedures span oncologic embolization and dialysis access maintenance.
- Neurology:Neurovascular navigation demands ultra-distal flexibility for intracranial access.
Cardiology commands the established base. Peripheral vascular intervention is gaining share fastest.
End User:
Customer type determines procurement centralization versus decentralized purchasing authority.
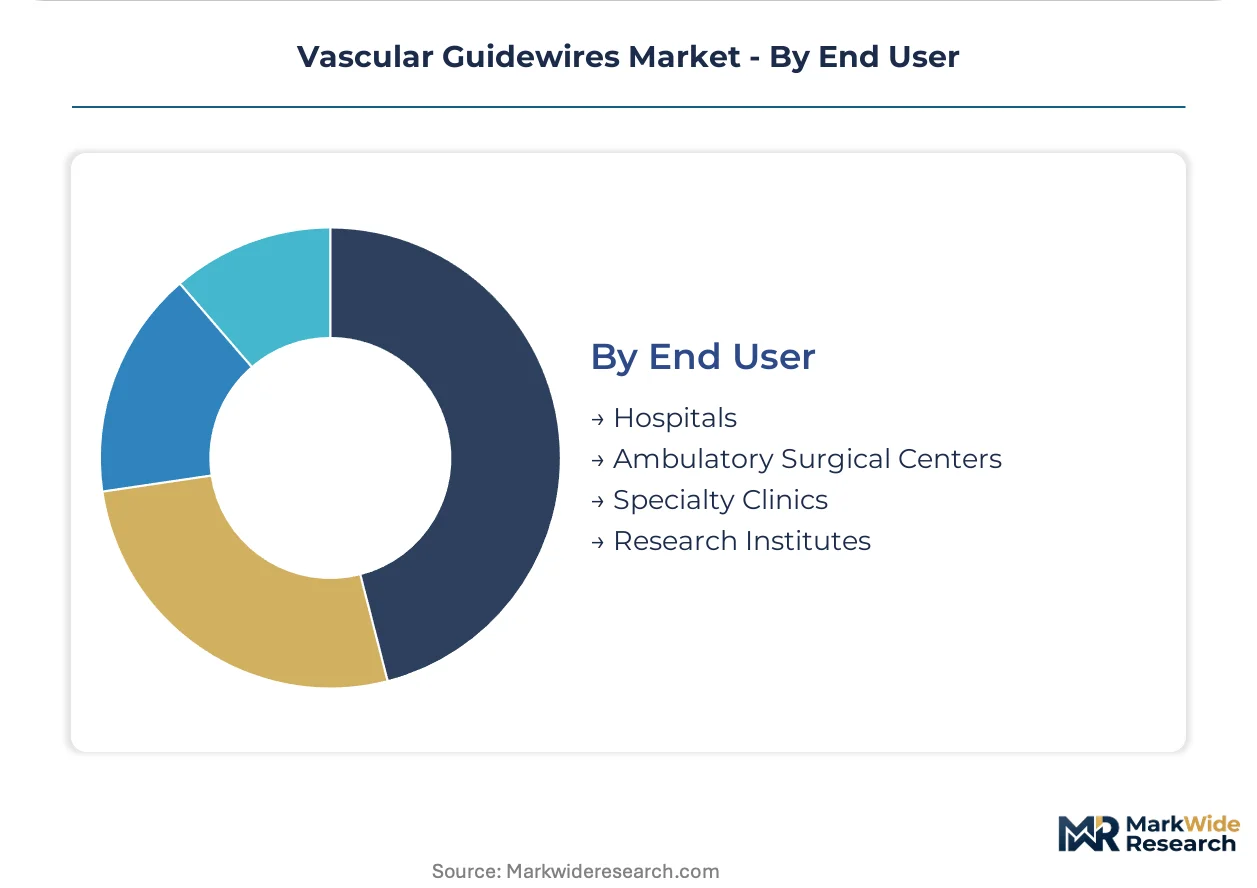
- Ambulatory Surgical Centers:Outpatient peripheral vascular procedures unwind historical hospital catheter lab dominance through dedicated vascular suites. Same-day discharge protocols reshape device selection toward single-platform versatility. United States reimbursement thresholds favor ambulatory migration.
- Hospitals:Integrated delivery networks consolidate cardiovascular service lines under bundled catheter lab contracts. Procurement committees displace standalone guidewire negotiations with multi-category vendor relationships spanning diagnostic, interventional, and electrophysiology workflows.
- Specialty Clinics:Focused intervention centers concentrate high-complexity caseloads with specialized inventory requirements.
- Research Institutes:Preclinical and clinical trial support drives demand for investigational device configurations.
Hospitals command the established base. Ambulatory surgical centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty metallurgical suppliers for nitinol superelastic alloys concentrate in Germany, Japan, and the United States, creating regional supply dependencies that reshape procurement networks for device manufacturers. FDA, EU MDR, and Japan PMDA regulatory pathways filter market access through divergent biocompatibility and sterilization validation standards. Interventional cardiology suites in Munich, Tokyo, and Minneapolis anchor demand for complex lesion navigation platforms.
United States
Ambulatory surgical centers in Texas and Florida are accelerating same-day discharge protocols for peripheral vascular procedures, unwinding historical hospital catheter lab dominance. FDA 510(k) clearance pathways for nitinol-based devices impose material traceability requirements that compress development timelines. Minneapolis-St. Paul hosts concentrated guidewire R&D operations serving integrated electrophysiology and interventional cardiology platforms.
Germany
Interventional suites in Bavaria and North Rhine-Westphalia drive coated guidewire penetration for chronic total occlusion revascularization with extended fluoroscopy times. EU MDR conformity assessment mandates expanded post-market surveillance registries for hydrophilic polymer performance. Frankfurt's cardiovascular device cluster anchors sterilization validation expertise for ethylene oxide residual compliance.
Japan
PMDA biocompatibility frameworks for coating technologies are accelerating market access for innovative surface treatment platforms in Tokyo and Osaka metropolitan areas. Specialty coronary guidewires optimized for complex lesion navigation command premium positioning in Kansai region intervention centers. Nagoya's medical device manufacturing corridor concentrates hybrid core architecture production for tortuous peripheral anatomy applications.
China
NMPA sterilization validation standards are filtering market access for non-dominant manufacturers seeking entry into Shanghai and Beijing interventional cardiology networks. Domestic demand concentrates in coated platforms for complex interventions while uncoated segments serve cost-sensitive procurement frameworks. Shenzhen's precision manufacturing ecosystem is developing nitinol processing capabilities for regional supply chain localization.
Switzerland
Swissmedic oversight of legacy guidewire portfolios extends recertification cycles for manufacturers maintaining European market authorization. Geneva and Basel cardiovascular research institutes drive preclinical demand for investigational device configurations in hybrid core development. Zürich's medical technology cluster anchors specialized tribology and hemocompatibility testing capabilities for polymer coating validation.
Vascular Guidewires Market Competitive Environment
Concentration sits with diversified cardiovascular platform suppliers and specialty interventional device manufacturers that span diagnostic, interventional, and electrophysiology workflows. The vendor base separates into three archetypes: integrated platform suppliers with catheter lab loyalty programs, specialty guidewire developers focused on chronic total occlusion navigation, and regional manufacturers serving cost-sensitive procurement frameworks. Competitive moves center on bundled catheter lab contracts displacing standalone guidewire negotiations, and strategic partnerships with specialty metallurgical suppliers for nitinol alloy qualification.
Within the integrated platform tier, Boston Scientific Corporation and Medtronic PLC exemplify archetypes leveraging electrophysiology and interventional cardiology convergence to sustain multi-category vendor relationships. Abbott Laboratories occupies a position among specialty coronary developers optimized for complex lesion subsets. Terumo Corporation represents Japanese-based manufacturers navigating PMDA and NMPA regulatory pathways for coating technology market access.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| Terumo Corporation |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Cook Medical, Inc. |
| Asahi Intecc Co., Ltd |
| Cardinal Health, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between nitinol alloy processors and device manufacturers lock in supply access while anchoring price visibility for superelastic wire feedstock across multi-year procurement cycles. These contractual structures insulate qualified suppliers from spot-market volatility in nickel-titanium alloys while compressing margin flexibility for mid-tier competitors lacking backward integration into metallurgical supply.
Pricing Analysis
Volume-discount tiering structures separate integrated delivery network contracts from standalone ambulatory surgical center purchases across the vascular guidewire market. Three-tier pricing stratification across premium specialty platforms, mid-range coated devices, and economy conventional wires reflects FDA 510(k) certification grade and hydrophilic coating complexity. Cost compression in uncoated stainless steel segments is intensifying as diagnostic catheterization labs consolidate procurement around bundled catheter lab contracts. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge reimbursement constraints, while specialized chronic total occlusion intervention centers accept premium positioning for complex lesion navigation capabilities.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors are elevating landed costs for nitinol feedstock sourced from German and Japanese specialty metallurgical suppliers. Superelastic alloy production concentrates in Germany, Japan, and the United States, with downstream guidewire assembly tethered to FDA-registered and EU MDR-notified manufacturing facilities in Minnesota, Bavaria, and Aichi Prefecture. Single-source vulnerability in nickel-titanium alloy qualification timelines poses structural risk as EU MDR material traceability mandates extend vendor requalification cycles. Distribution runs through integrated catheter lab vendor-managed inventory programs and GPO-contracted distribution networks serving hospital systems and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized tribology capabilities for hydrophilic polymer validation represent the critical skill gap separating qualified guidewire manufacturers from market access failures, concentrating competitive advantage among limited contract research organizations with hemocompatibility testing infrastructure.
For Market Incumbents: Secure captive supply agreements with specialty nitinol alloy processors to defend against raw material concentration risk as EU MDR traceability mandates compress vendor qualification timelines. Invest in ethylene oxide sterilization facility upgrades to preempt Swissmedic and EU MDR Annex I residual limit enforcement that threatens legacy portfolio recertification. For New Entrants and Emerging Players: Anchor in Japan's PMDA streamlined coating validation pathway to accelerate market access for innovative hydrophilic surface treatments ahead of entrenched competitors. Target China's NMPA-regulated peripheral vascular intervention segment through domestic manufacturing partnerships in Shenzhen's precision device ecosystem, leveraging cost-sensitive procurement frameworks for uncoated guidewire platforms. For Investors and Strategic Acquirers: Specialty guidewire developers with validated chronic total occlusion navigation platforms and active EU MDR surveillance registries represent the highest-conviction acquisition archetype for cardiovascular platform consolidation. Monitor FDA 510(k) clearance velocity for hybrid core architectures as the inflection signal distinguishing R&D-efficient targets from legacy technology stranded by material science fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Surveillance Registry Establishment | Post-market clinical follow-up obligations for hydrophilic polymer performance secure continued market authorization across chronic total occlusion portfolios. |
| Hybrid Core Architecture R&D Partnership | Convergence of nitinol superelasticity with stainless steel torque response enables next-generation steerability for tortuous peripheral anatomy navigation. |
| Ambulatory Surgical Center Distribution Agreement | Same-day discharge protocol alignment in Texas and Florida vascular suites captures outpatient peripheral intervention migration from hospital catheter labs. |
| Nitinol Alloy Backward Integration | Captive supply of superelastic wire feedstock insulates against specialty metallurgical supplier concentration and EU MDR material traceability compliance costs. |
| Japan PMDA Coating Technology Submission | Streamlined biocompatibility validation frameworks accelerate market access for innovative hydrophilic surface treatments in Tokyo and Osaka metropolitan areas. |
Study Parameters
A spread of perspectives from interventional cardiologists, hospital purchasing committee directors, biomedical engineers specializing in catheter lab equipment, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body conformity assessments, Japan PMDA submission records, and hospital procurement contract disclosures. Bottom-up demand modeling across coated, specialty, uncoated, and conventional guidewire segments triangulated with top-down cardiovascular device market sizing from trade data and industry association reports.
Segmentation dimensions modeled include product type, material composition, application territory, and end-user facility category across the projection horizon. CAGRs were derived from procedure volume elasticity to device utilization rates, reimbursement trajectory analysis for outpatient peripheral vascular interventions, and material science adoption curves for hybrid core architectures. Forecast inputs incorporated EU MDR recertification timeline assumptions, ambulatory surgical center capacity expansion plans, and nitinol alloy supply constraint scenarios.
Material uncertainties — regulatory enforcement intensity for ethylene oxide sterilization residuals, nickel-titanium alloy supply disruptions, and reimbursement threshold revisions for same-day discharge protocols — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding PMDA pathway efficiency and integrated delivery network vendor consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Ablation Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Portable OT Light Market
Medical Devices
Facial Pumps Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
External Pacemakers Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Nebuliser Market
Medical Devices
Brazil Angioplasty Devices Market