
 Hypodermic Syringes Market | 2026-2036
Hypodermic Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Hypodermic Syringes Market Outlook
Chinese polypropylene resin suppliers is realigning global raw material flows for disposable medical plastics. Becton, Dickinson and Company leverages backward integration into precision molding to protect margin structures on safety-engineered devices. Terumo Corporation anchors its competitive stance through proprietary siliconization technology for reduced plunger-force syringes. Nipro Corporation specializes in glass-barrel hypodermics for biologic drug delivery where extractables control matters.
A hypodermic syringe comprises a cylindrical barrel, plunger, and needle assembly designed to deliver measured fluid doses through subcutaneous, intramuscular, or intravenous routes; polypropylene barrels dominate volume production due to dimensional stability, chemical inertness, and compatibility with gamma sterilization cycles. Safety syringes now command premium positioning as OSHA bloodborne pathogen compliance mandates drive hospital procurement specifications toward retractable and shielded needle designs. Pre-filled syringes represent the fastest-expanding product category as biopharma companies seek to reduce medication errors and extend drug stability through integrated primary packaging.
The FDA enforces sharps injury prevention requirements under the Needlestick Safety and Prevention Act, while the EU MDR imposes stricter clinical evidence thresholds for Class IIa medical devices including conventional and safety syringes sold across European markets. India's CDSCO aligns with ISO 7886 standards for sterile single-use syringes as domestic production scales under the PLI scheme for medical devices. Stakeholders must monitor regulatory divergence between US OSHA enforcement trends and EU MDR transition timelines when allocating manufacturing footprint and certification budgets.
Market Dynamics
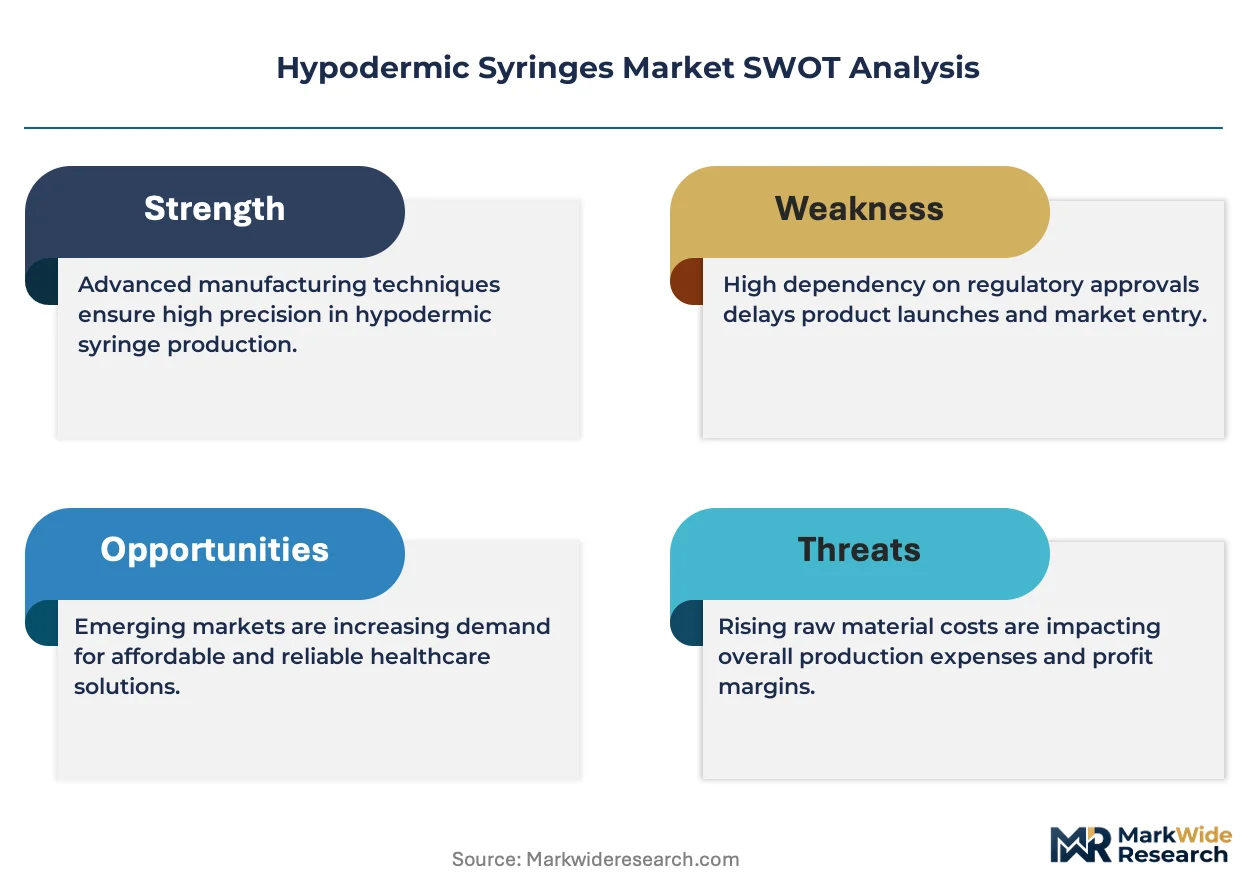
The transition from conventional to safety-engineered hypodermic syringes is compressing manufacturing margins while elevating technical barriers for suppliers lacking precision molding capabilities or integrated needle shielding expertise.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US hospital procurement committees now mandate retractable or shielded needle designs for needlestick injury prevention, creating specification lock-in for safety syringe vendors.
- Biopharma Pre-fill Integration:Drug manufacturers are specifying syringes as primary drug containers rather than secondary delivery tools, extending syringe functional requirements into stability and extractables control.
- India PLI Medical Devices Scheme:Domestic manufacturers are expanding sterile single-use syringe capacity under production-linked incentives, redirecting supply chain gravity toward Indian export hubs.
Market Restraints
- Polypropylene Resin Concentration:Chinese petrochemical suppliers control critical feedstock for disposable barrel production, exposing converters to input cost volatility and geopolitical supply disruption.
- EU MDR Clinical Evidence Thresholds:Stricter documentation requirements for Class IIa device re-certification are extending timeline-to-market and concentrating compliance capabilities among larger manufacturers.
- Glass Barrel Substitution Ceiling:Biologic drug compatibility requirements prevent full polymer displacement in high-value applications, fragmenting production scale economies across material platforms.
Strategic Opportunities
- Home Healthcare Self-Administration:Diabetes and auto-immune therapeutic categories are driving demand for user-centric syringe designs with reduced plunger force and integrated needle safety.
- Gamma Sterilization Compatibility:Polypropylene formulations tolerant of irradiation cycles without yellowing or embrittlement are capturing preference from ethylene oxide-dependent alternatives facing residual gas regulations.
- Siliconization Process Control:Proprietary lubrication technologies that minimize protein aggregation in biologic delivery are creating differentiation moats in pre-filled syringe contract manufacturing.
Industry Challenges
- Multi-Site Regulatory Audit Burden:Manufacturers serving both FDA and EMA jurisdictions face overlapping inspection schedules and divergent quality system documentation requirements.
- Precision Molding Talent Scarcity:Safety mechanism integration demands micron-level tolerance control that outstrips conventional medical plastics processing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypodermic Syringes Market |
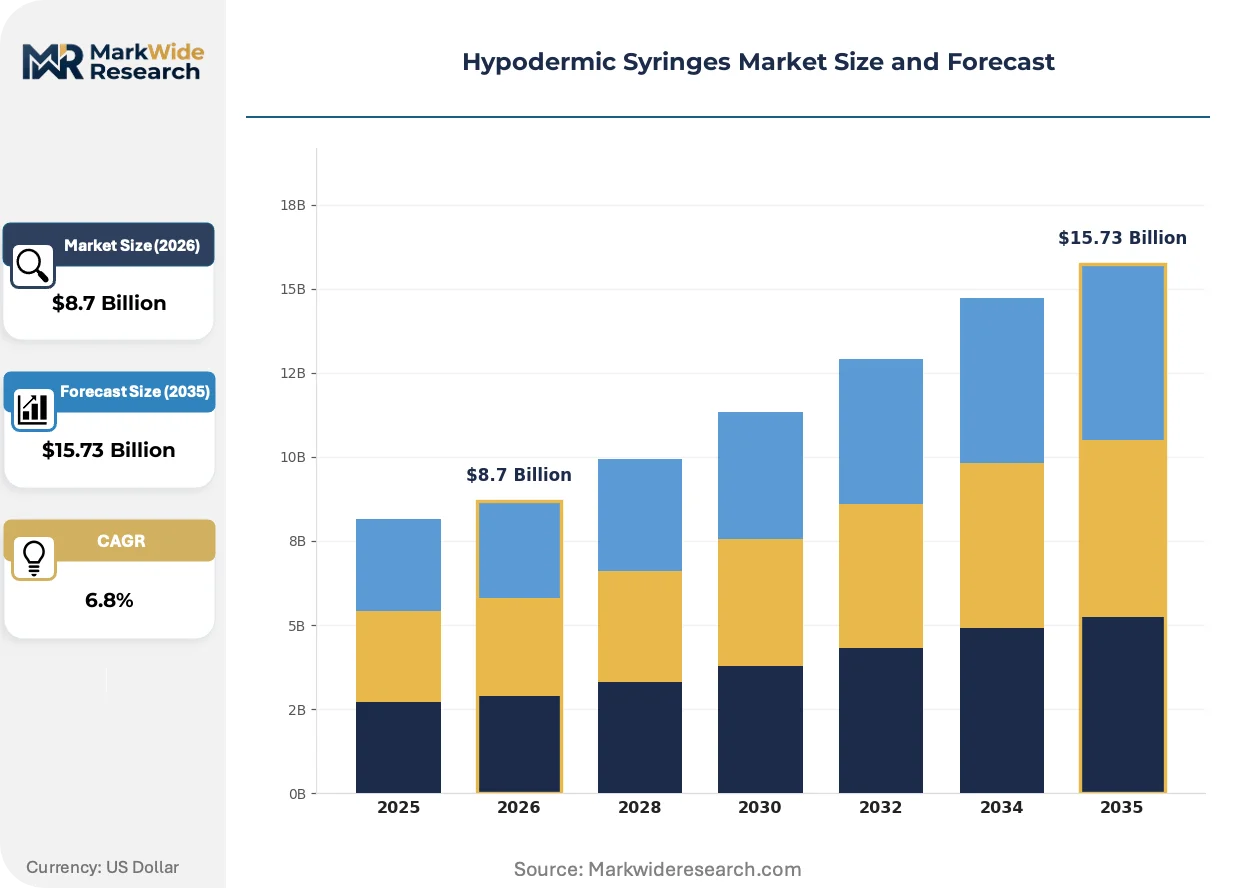
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Syringes, Conventional Syringes, Pre-filled Syringes, Insulin Syringes End User: Hospitals, Clinics, Homecare Settings, Pharmacies Material: Polypropylene, Glass, Rubber, Latex Capacity: 1ml, 5ml, 10ml, 20ml |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, Nipro Corporation, B. Braun Melsungen AG, Cardinal Health, Hindustan Syringes & Medical Devices, Medline Industries, Gerresheimer AG, Retractable Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypodermic Syringes Market Strategic Shifts
Safety mechanism integration is unifying previously separate device engineering disciplines, while regulatory convergence pressures and end-use vertical specialization are fragmenting standardized product platforms into indication-specific configurations.
Passive safety syringe technology is unifying needlestick prevention with user workflow efficiency. Hospital systems in the United States are specifying devices that activate automatically upon plunger completion, eliminating manual shielding steps that compliance audits show are frequently skipped. This unification is compressing market share for conventional active-safety designs requiring deliberate secondary manipulation.
EU MDR transition timelines are compressing notified body capacity and extending certification queues for legacy syringe product lines. Manufacturers with MDR technical documentation prepared are securing competitive shelf space as competitors face stock-out risks during recertification gaps. Pre-filled syringe categories face the steepest compliance burden due to combined device-drug regulatory interfaces.
Self-administration training protocols are reshaping procurement specifications toward intuitive device designs. Rheumatology and endocrinology clinics are rejecting syringes requiring complex handling sequences that elevate patient error rates during home injection. Germany and the United Kingdom exhibit the most advanced preference shift toward single-step activation mechanisms in outpatient therapeutic categories.
Hypodermic Syringes Market Segmentation
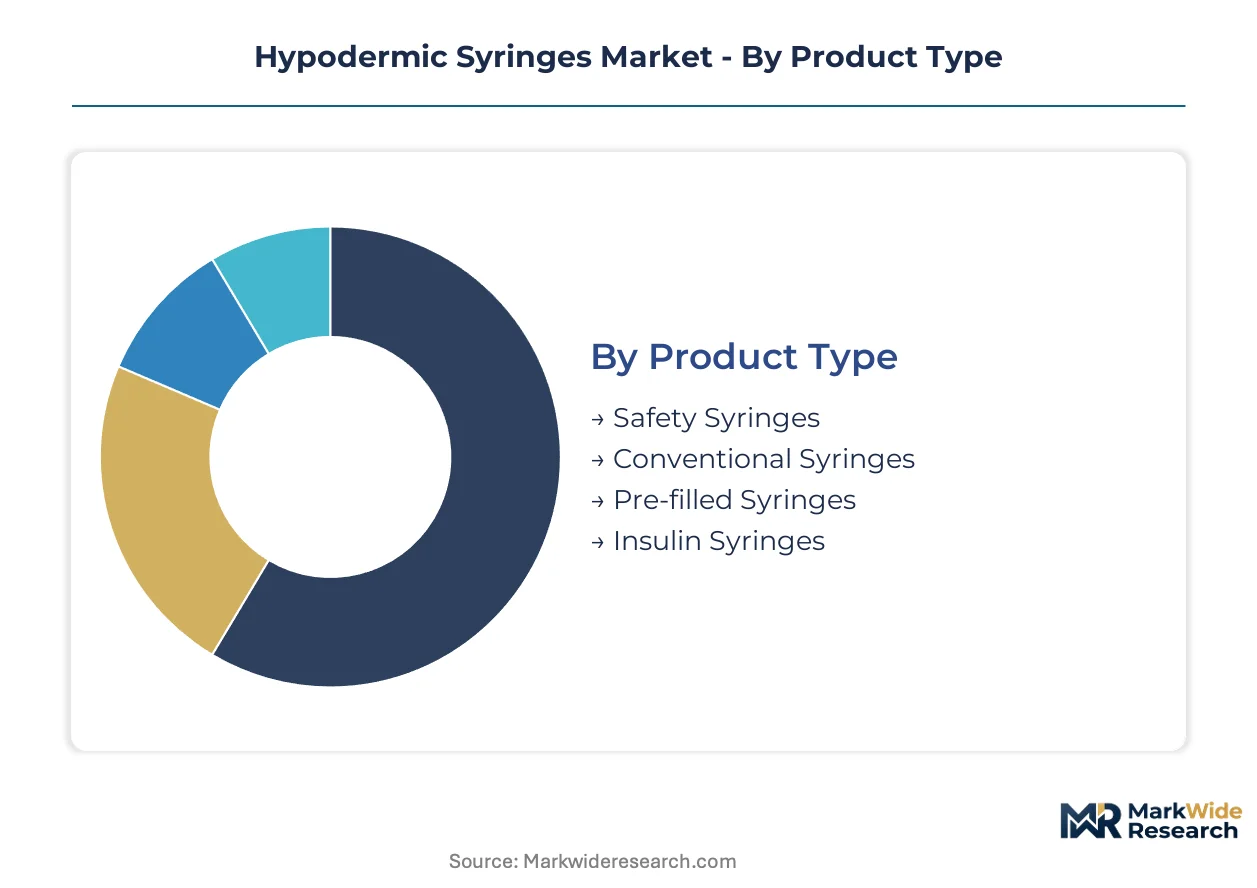
Hypodermic syringe procurement specifications diverge sharply across clinical settings, with regulatory mandates and drug compatibility requirements fragmenting what once was a commoditized product category into distinct technical tiers.
Product Type:
FDA Needlestick Safety and Prevention Act compliance and EU MDR Class IIa certification burdens fall unevenly across product architectures, with safety-engineered designs demanding extensive clinical evidence packages that conventional formats escape.
- Safety Syringes:Retractable and shielded needle mechanisms integrate passive or active injury prevention into the barrel-plunger assembly. US hospital procurement committees now mandate these designs under OSHA bloodborne pathogen standards, compressing market share for conventional alternatives despite 15-25% unit cost premiums.
- Pre-filled Syringes:Biopharma companies specify these as primary drug containers rather than secondary delivery tools, extending functional requirements into extractables control and stability validation. This segment climbs fastest as injectable biologics expand and medication error reduction becomes a formulary priority.
- Conventional Syringes:Unshielded designs persist in cost-sensitive bulk procurement for immunization campaigns and veterinary applications where regulatory enforcement is less stringent.
- Insulin Syringes:Unit-dose calibrated barrels with permanently attached fine-gauge needles serve diabetes self-administration protocols, with demand concentrated in homecare channels.
Leading the category by volume: Conventional Syringes. Growing fastest: Pre-filled Syringes.
End User:
Procurement authority and specification complexity escalate from retail channels through institutional settings, with hospitals exercising the most stringent safety and quality documentation requirements.
- Hospitals:Infection control committees mandate safety-engineered devices and maintain approved vendor lists requiring ISO 13485 quality system certification. Bulk purchasing contracts concentrate volume among suppliers with MDR technical documentation prepared.
- Homecare Settings:Self-administration training protocols favor intuitive single-step activation mechanisms. Rheumatology and endocrinology clinics in Germany and the United Kingdom are rejecting complex handling sequences that elevate patient error rates.
- Clinics:Outpatient surgical and infusion centers balance OSHA compliance against procedure-specific volume requirements, often maintaining dual inventory of safety and conventional formats.
- Pharmacies:Retail dispensing focuses on unit-of-use packaging and patient counseling support materials, with less stringent device engineering specifications than institutional channels.
Highest specification burden: Hospitals. Fastest preference shift toward safety designs: Homecare Settings.
Material:
Gamma sterilization compatibility and biologic drug stability requirements are fragmenting material selection across application tiers, with polymer formulations displacing glass in volume segments while extractables-sensitive biologics preserve glass-barrel demand.
- Polypropylene:Dimensional stability and chemical inertness under irradiation cycles make this the dominant barrel material for disposable production. Chinese petrochemical suppliers control critical feedstock, exposing converters to input cost volatility.
- Glass:Borosilicate barrels remain mandatory for high-value biologic delivery where protein aggregation and extractables control override cost considerations. Nipro Corporation specializes in this niche.
- Rubber:Elastomer plunger tips and needle shields require silicone oil lubrication that must be controlled to prevent drug interaction.
- Latex:Declining share due to allergen concerns, with synthetic polyisoprene substitutes capturing preference in sensitive patient populations.
Dominant by production volume: Polypropylene. Most constrained by supply concentration: Polypropylene.
Capacity:
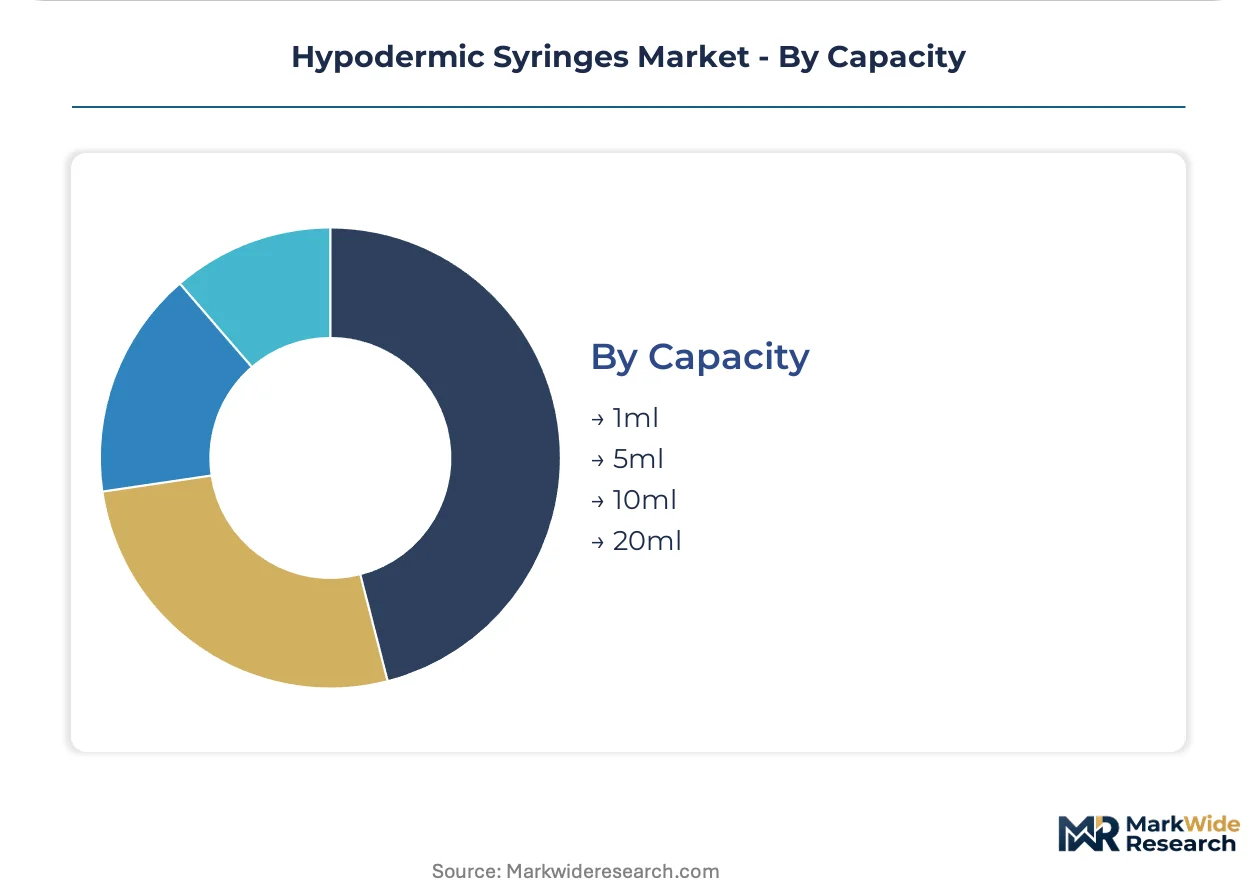
Dose precision requirements and injection route specifications determine capacity selection, with subcutaneous self-administration favoring small formats and intramuscular institutional delivery requiring larger volumes.
- 1ml:Tuberculin and pediatric dosing applications demand graduated precision to hundredth-milliliter increments. Insulin and heparin protocols drive consistent demand.
- 5ml:Standard immunization and antibiotic administration volume, with the broadest cross-application utility.
- 10ml:Contrast media and large-volume parenteral nutrition applications.
- 20ml:Irrigation and aspiration procedures where precise dosing is secondary to volume delivery.
Highest unit volume: 5ml. Most specialized precision requirements: 1ml.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese polypropylene resin suppliers anchor raw material flows for disposable barrel production, while finished device manufacturing concentrates across three distinct regulatory jurisdictions with divergent compliance timelines.
United States
OSHA bloodborne pathogen enforcement drives hospital procurement toward retractable needle designs. The FDA's Needlestick Safety and Prevention Act mandates engineering controls in healthcare settings. New Jersey and Illinois host precision molding clusters where safety mechanism integration commands micron-level tolerance expertise.
Germany
Outpatient rheumatology and endocrinology clinics are rejecting complex handling sequences for self-administration devices. The EU MDR transition compresses notified body capacity and extends certification queues for legacy product lines. Baden-Württemberg's medical technology corridor concentrates contract manufacturing for pre-filled syringe assembly.
India
Domestic manufacturers expand sterile single-use syringe capacity under the PLI scheme for medical devices. CDSCO alignment with ISO 7886 standards streamlines export qualification pathways. Haryana and Gujarat production hubs are redirecting supply chain gravity toward Indian export platforms serving African and Southeast Asian markets.
Japan
PMDA quality system inspections emphasize siliconization process validation for biologic drug compatibility. Aging demographics accelerate home healthcare self-administration demand for reduced plunger-force designs. The Kansai region maintains specialized glass-barrel fabrication for extractables-sensitive therapeutic categories.
Brazil
ANVISA import substitution policies favor local assembly of immunization campaign volumes. Public procurement through the Ministry of Health concentrates demand for conventional formats in cost-sensitive bulk purchasing. São Paulo state's plastics processing base supplies barrel components to regional device finishers.
Hypodermic Syringes Market Competitive Environment
Global majors compete with regional champions across regulatory certification capabilities, with market structure consolidating around three tiers differentiated by MDR documentation preparedness and precision molding scale. Tier-one positions are occupied by manufacturers with backward integration into resin conversion and captive needle fabrication. Tier-two regional champions leverage domestic regulatory relationships and public procurement access. Tier-three specialists concentrate on indication-specific configurations for biologic delivery. Competitive moves center on MDR technical dossier acceleration and gamma-sterilization-compatible polypropylene formulation partnerships.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Terumo Corporation exemplify integrated precision molding capabilities, while Nipro Corporation occupies a specialist position in glass-barrel configurations for extractables-critical applications. These three anchors represent distinct strategic postures: full-line safety engineering, proprietary lubrication technology, and material-specific niche dominance respectively.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| B. Braun Melsungen AG |
| Cardinal Health |
| Hindustan Syringes & Medical Devices |
| Medline Industries |
| Gerresheimer AG |
| Retractable Technologies |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin spot indices in East Asia cascade through three-tier pricing structures across premium, standard, and economy levels, with gamma-sterilization-compatible formulations commanding 12-18% premiums over commodity grades and Chinese petrochemical concentration amplifying volatility pass-through to finished device converters.
Pricing Analysis
Service bundling separates premium safety syringe vendors offering MDR technical dossier support and hospital GPO contract management from unbundled commodity suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and precision molding capability. Cost compression in conventional syringe segments intensifies as Indian PLI-supported capacity expands export volumes. Government immunization programs exhibit highest price sensitivity; biopharma pre-fill partnerships demonstrate lowest sensitivity due to extractables validation requirements.
Supply Chain Analysis
ISO 7886 and EU MDR certification gating concentrates qualified barrel production in China, India, and Germany, with notified body audit queues extending qualification timelines for new entrants. Raw material flows draw from Saudi petrochemical feedstocks, Korean specialty resin compounding, and Japanese siliconization chemistry. Single-source vulnerability concentrates in Chinese polypropylene resin supply, exposing converters to geopolitical disruption. Distribution runs through hospital GPOs in developed markets and Ministry of Health procurement in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Safety mechanism integration is displacing conventional syringe architectures, with passive retractable needle technology replacing active-shield designs in hospital procurement specifications.
For Market Incumbents: Hedge against margin compression by securing captive polypropylene resin conversion capacity in India or Germany, insulating against Chinese supply volatility. Accelerate MDR technical documentation for pre-filled syringe lines before notified body capacity constraints deepen. Invest in siliconization process control patents to defend biopharma contract manufacturing relationships against emerging lubrication technology entrants.
For New Entrants and Emerging Players: OSHA bloodborne pathogen standard enforcement in the United States opens a window for safety syringe specialists with retractable needle IP to penetrate hospital GPO contracts bypassed by incumbents facing recertification gaps. Target Indian PLI scheme beneficiaries seeking technology licensing partnerships for export market qualification. Pursue white-label manufacturing for European biopharma companies requiring MDR-compliant pre-filled assembly capacity.
For Investors and Strategic Acquirers: The window for entry favors precision molding specialists with ISO 13485 certification and existing medical device customer relationships. Long-term viability rests on vertical integration into resin conversion or needle fabrication, not assembly-only models. Monitor EU MDR notified body capacity expansion as the inflection signal for M&A timing; queue compression will elevate target valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Conversion | Captive polypropylene supply from Reliance or SABIC insulates margin structures from petrochemical volatility. |
| MDR Technical Dossier Acceleration | Prepared documentation secures shelf space as competitors face stock-out risks during recertification gaps. |
| Gamma Sterilization Formulation Partnership | Collaboration with LyondellBasell or Borealis on irradiation-stable grades captures preference from ethylene oxide alternatives. |
| Siliconization Process Patent Expansion | Proprietary lubrication control from Dow Corning or Wacker Chemie minimizes protein aggregation in biologic delivery. |
| Hospital GPO Contract Consolidation | Premier and Vizient purchasing concentration rewards suppliers with comprehensive safety syringe portfolios. |
Study Parameters
Multi-period observation of OSHA enforcement trends, EU MDR transition timelines, and Indian PLI scheme disbursement rates anchored the trend analysis, supplemented by interviews with hospital infection control officers, biomedical engineers, GPO contracts managers, and biopharma device development leads. Secondary validation drew from FDA 510(k) filings, EMDR database entries, CDSCO manufacturing license records, and customs trade data for polypropylene resin flows. Bottom-up capacity modeling triangulated against top-down expenditure estimates from national immunization program budgets.
Segment-weighting across product type, end user, material, capacity, and regional regulatory cluster shaped volume and value allocation throughout the forecast period. CAGRs were derived from trend extrapolation of safety syringe penetration rates, pre-filled syringe biopharma adoption curves, and conventional syringe displacement patterns. Industry-specific inputs included OSHA compliance audit frequency, notified body certification queue lengths, and biologic drug pipeline administration route specifications.
The model assumes a particular technology adoption path; alternative pathways for passive safety mechanism designs would alter the outlook if manual activation protocols retain procurement preference. Forecasts reflect assumptions regarding regulatory enforcement continuity and resin supply chain stability. A model refresh is warranted upon material change in EU MDR notified body capacity or Chinese petrochemical export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Lactate Meter Market
Medical Devices
Pectus Bar System Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Pharmaceutical Filtration Devices Market