
 Global Electrophysiology Devices Market | 2026-2036
Global Electrophysiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrophysiology Devices Market Foresight
Aftermarket service revenue from mapping system upgrades and catheter refurbishment programs is reconfiguring profitability models across the competitive landscape. Medtronic plc leverages its integrated hardware-software ecosystem to sustain recurring revenue streams from installed base maintenance. Johnson & Johnson anchors its position through deep catheter portfolio breadth spanning diagnostic and therapeutic applications. Abbott Laboratories differentiates via contact-force sensing technology leadership in radiofrequency ablation segments.
Electrophysiology devices comprise specialized instruments for cardiac electrical signal detection, mapping, and therapeutic modification, typically operating at 460-500 kHz radiofrequency or sub-zero cryogenic temperatures to create controlled myocardial lesions. These systems serve the clinical purpose of diagnosing and treating arrhythmias through minimally invasive transvenous access. Ablation catheters capture the largest margin pool due to single-use economics and premium pricing for advanced energy modalities. Cardiac mapping systems represent the fastest-growing technology segment as three-dimensional electroanatomic platforms displace conventional fluoroscopy-guided procedures. Diagnostic equipment maintains steady replacement demand tied to hospital capital budget cycles rather than procedural volume fluctuations.
FDA premarket approval pathways and MDR conformity assessments in Europe impose substantial clinical evidence requirements that filter market access for novel ablation technologies. ISO 13485 quality management standards and IEC 60601 electrical safety specifications govern manufacturing consistency across multinational supply chains. Stakeholders must monitor reimbursement determinations from CMS and Germany's G-BA, as these decisions directly shape physician adoption thresholds and hospital procurement priorities for next-generation platforms.
Market Dynamics
Three-dimensional electroanatomic mapping systems are compressing fluoroscopy exposure and procedural times, restructuring capital allocation toward integrated hardware-software platforms over standalone catheter purchases.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for novel mapping technologies accelerate commercialization timelines and reduce evidence-generation costs for innovators.
- Catheter-based ablation as first-line therapy:Hospital electrophysiology labs in aging markets expand procedural volumes as guidelines elevate ablation ahead of antiarrhythmic pharmacology.
- Reimbursement clarity in Germany and Japan:Determinations from G-BA and METI coverage policies reduce physician adoption thresholds and stabilize hospital procurement cycles.
Market Restraints
- MDR conformity assessments:Europe's tightened clinical evidence requirements for novel ablation technologies filter market access and extend time-to-revenue for mid-tier entrants.
- Single-use catheter economics:Premium pricing for advanced energy modalities concentrates margin capture among integrated manufacturers, squeezing standalone catheter suppliers.
- Capital budget cyclicality:Diagnostic equipment demand ties to hospital replacement cycles rather than procedural volume, creating revenue predictability gaps for mapping system vendors.
Strategic Opportunities
- Aftermarket service unbundling:Mapping system upgrades and catheter refurbishment programs in the United States generate recurring revenue streams independent of new capital sales.
- Contact-force sensing convergence:Integration of pressure-feedback mechanisms with radiofrequency delivery platforms opens differentiation in high-complexity ablation segments.
- Cryogenic energy modality expansion:Sub-zero temperature lesion creation addresses anatomical challenges where thermal ablation risks collateral damage, capturing premium positioning.
Industry Challenges
- Electrophysiologist training pipeline:Procedural complexity and extended fellowship requirements constrain specialist supply relative to expanding lab capacity.
- ISO 13485 quality system maintenance:Multinational manufacturing consistency demands impose compliance overhead across distributed supply chains.
- Legacy system integration friction:Hospital IT infrastructure and existing catheter inventories complicate platform migration to next-generation mapping architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrophysiology Devices Market |
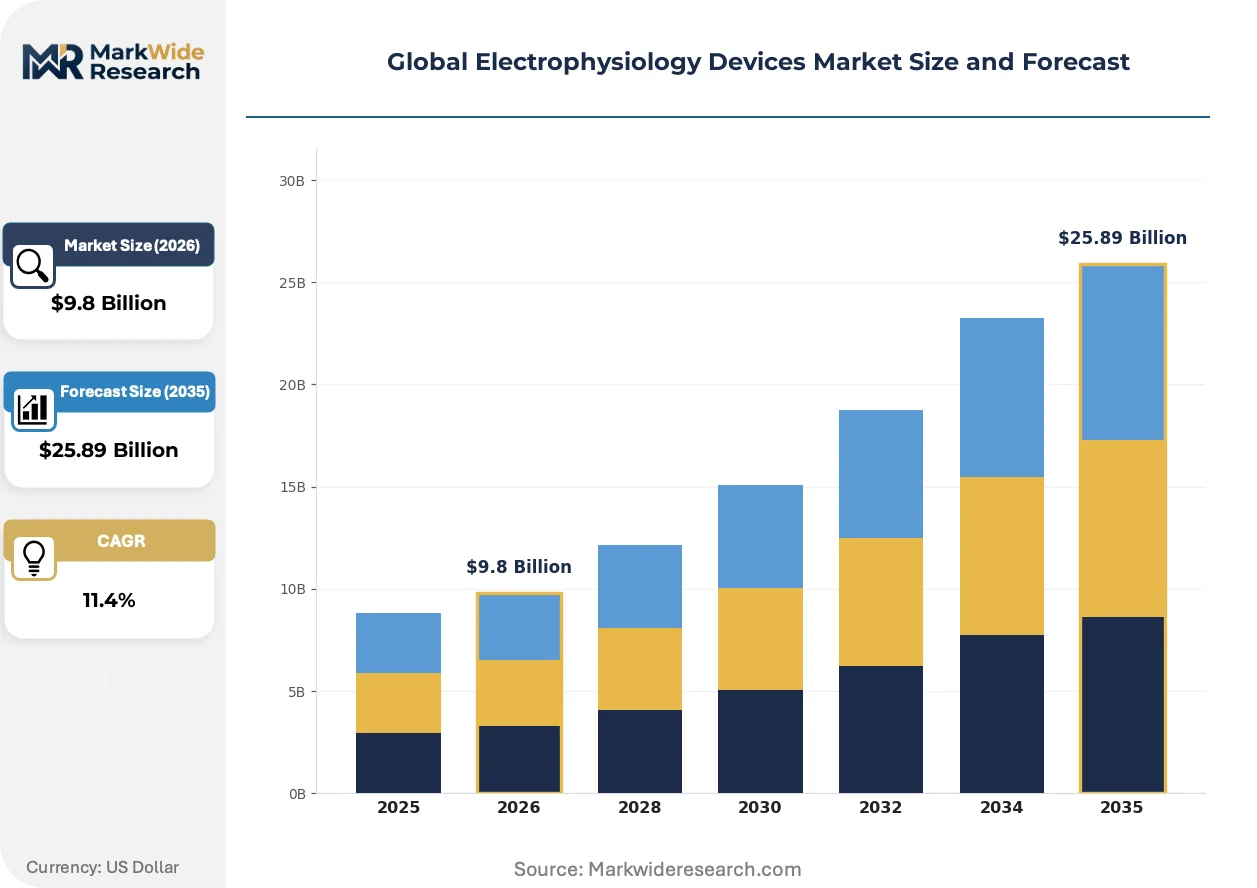
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroanalyzers, Signal Amplifiers, Cardiac Mapping Systems, Ablation Catheters, Diagnostic Equipment Technology: Radiofrequency, Cryoablation, Laser Ablation, Ultrasound, Electromagnetic Navigation Application: Atrial Fibrillation, Ventricular Tachycardia, Supraventricular Tachycardia, Wolf-Parkinson-White Syndrome, Bradycardia End User: Cardiology Centers, Specialized Clinics, Diagnostic Laboratories, Research Institutes, Electrophysiology Labs |
| Companies Covered | Medtronic plc, Koninklijke Philips N.V., Johnson & Johnson, AtriCure, Inc., Siemens Healthineers, Boston Scientific Corporation, Biotronik SE & Co. KG, MicroPort Scientific Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrophysiology Devices Market Shifts & Advancements
Digital twin reconstruction of cardiac chambers is eliminating fluoroscopic dependency while artificial intelligence integration compresses mapping acquisition times. These shifts are reconfiguring competitive advantage toward software-enabled procedural efficiency.
High-density electrode arrays with automated signal annotation are virtualizing the electrophysiologist's interpretive workflow. Academic medical centers in the United States and Germany deploy these systems to reduce manual point-by-point mapping. This virtualization enables less experienced operators to achieve comparable procedural outcomes, expanding addressable operator pools beyond traditional fellowship-trained specialists.
Europe's MDR implementation imposes stricter post-market surveillance and clinical follow-up obligations on ablation catheter manufacturers. Device sponsors must maintain active registries and periodic safety reporting that exceeds predecessor MDD requirements. Small-to-mid tier manufacturers without established quality infrastructure face disproportionate compliance burdens, accelerating consolidation toward integrated platform vendors with captive clinical affairs capabilities.
Hospital purchasing committees now unbundle capital equipment from disposable commitments, negotiating multi-year service contracts separate from catheter supply agreements. This disintermediation of traditional bundled pricing is most visible in United States integrated delivery networks, where procurement centralization demands transparent cost-per-procedure modeling. Vendors respond with outcome-guaranteed performance contracts that shift risk toward manufacturers while locking installed base maintenance revenue.
Global Electrophysiology Devices Market Segmentation
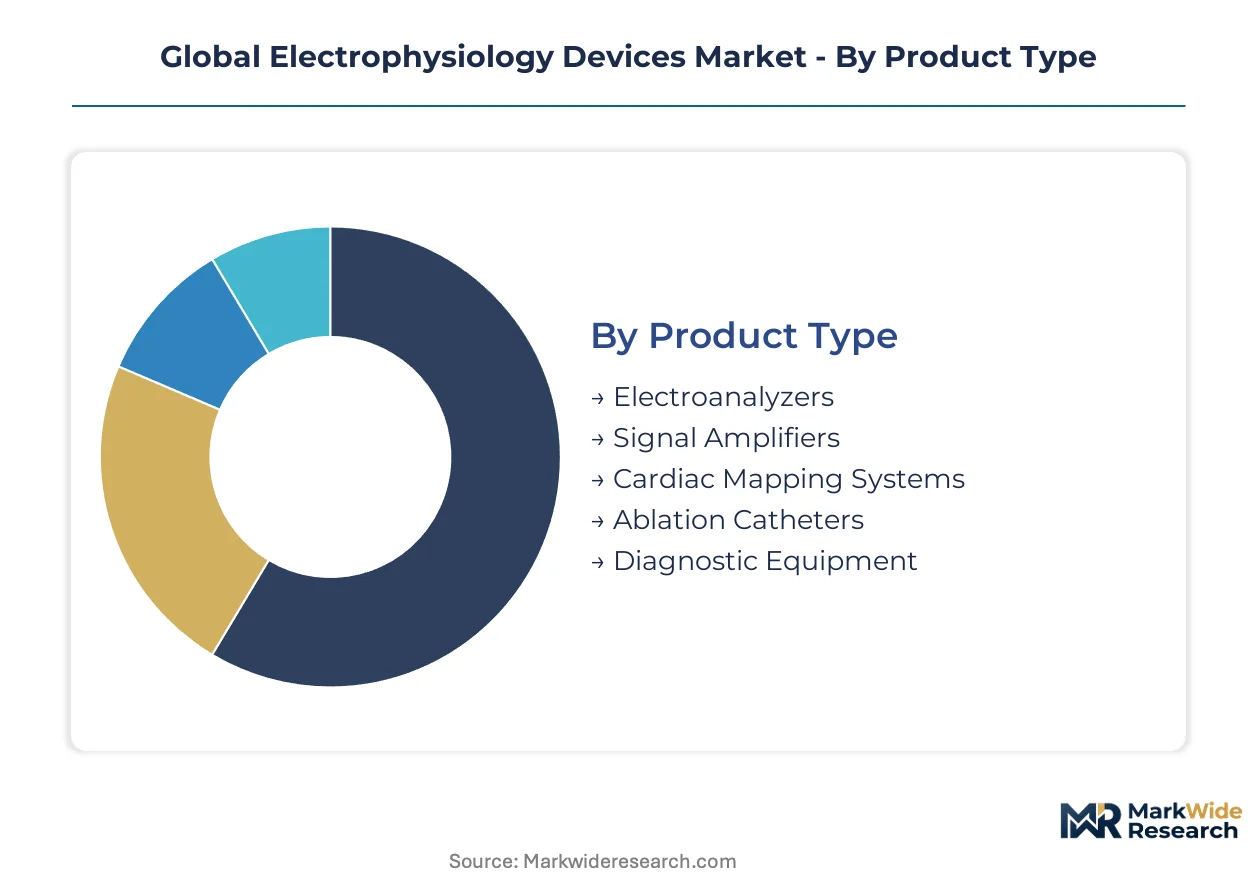
Segmentation in electrophysiology devices reflects divergent clinical workflows and capital intensity. Product portfolios span single-use disposables with recurring revenue profiles to multi-year capital installations with extended replacement cycles.
Product Type:
Use-case spectrum spans diagnostic signal acquisition through therapeutic lesion delivery, with hardware-software integration determining account stickiness.
- Ablation Catheters:Single-use instruments delivering radiofrequency or cryogenic energy at 460-500 kHz or sub-zero temperatures to create controlled myocardial lesions. Demand concentrates in United States hospital electrophysiology labs expanding catheter-based ablation programs as first-line therapy for atrial fibrillation, with premium pricing for advanced energy modalities capturing the largest margin pool.
- Cardiac Mapping Systems:Three-dimensional electroanatomic platforms integrating hardware-software ecosystems to displace conventional fluoroscopy-guided procedures. Adoption accelerates in Germany and Japan where aging demographics and reimbursement clarity from G-BA and METI support procedural volume expansion, representing the fastest-growing technology segment.
- Diagnostic Equipment:Steady replacement demand tied to hospital capital budget cycles rather than procedural volume fluctuations.
- Electroanalyzers:Signal processing instruments for cardiac electrical activity interpretation in laboratory settings.
- Signal Amplifiers:Hardware components enhancing electrogram resolution for precise arrhythmia localization.
Established volume favors ablation catheters; emerging adoption favors cardiac mapping systems.
Technology:
Cost tier stratification separates premium integrated platforms from standalone energy delivery mechanisms.
- Radiofrequency:Thermal lesion creation at 460-500 kHz remains the dominant energy modality with extensive clinical evidence supporting reimbursement pathways.
- Cryoablation:Sub-zero temperature lesion creation addresses anatomical challenges where thermal ablation risks collateral damage, capturing premium positioning in high-complexity procedures.
- Laser Ablation:Optical energy delivery enabling precise tissue modification with reduced thermal spread.
- Ultrasound:Mechanical energy ablation with potential for deeper tissue penetration in specific anatomical substrates.
- Electromagnetic Navigation:Sensor-based catheter tracking integrated with mapping architectures for enhanced procedural efficiency.
Volume concentration sits with radiofrequency; steepest expansion trajectory belongs to cryoablation.
Application:
Procedure complexity and reimbursement weighting differentiate arrhythmia indications.
- Atrial Fibrillation:The most prevalent sustained arrhythmia driving procedural volume expansion as guidelines elevate catheter ablation ahead of antiarrhythmic pharmacology in United States and German electrophysiology labs.
- Ventricular Tachycardia:Life-threatening arrhythmia requiring sophisticated mapping and ablation approaches in tertiary referral centers with advanced substrate characterization capabilities.
- Supraventricular Tachycardia:Established ablation target with favorable acute success rates and streamlined procedural protocols.
- Wolf-Parkinson-White Syndrome:Accessory pathway ablation with high cure rates supporting early invasive management.
- Bradycardia:Pacing-dependent indication with distinct device requirements separate from ablation technologies.
Procedural volume concentrates in atrial fibrillation; technical complexity peaks in ventricular tachycardia.
End User:
Customer type determines procurement authority and capital allocation flexibility.
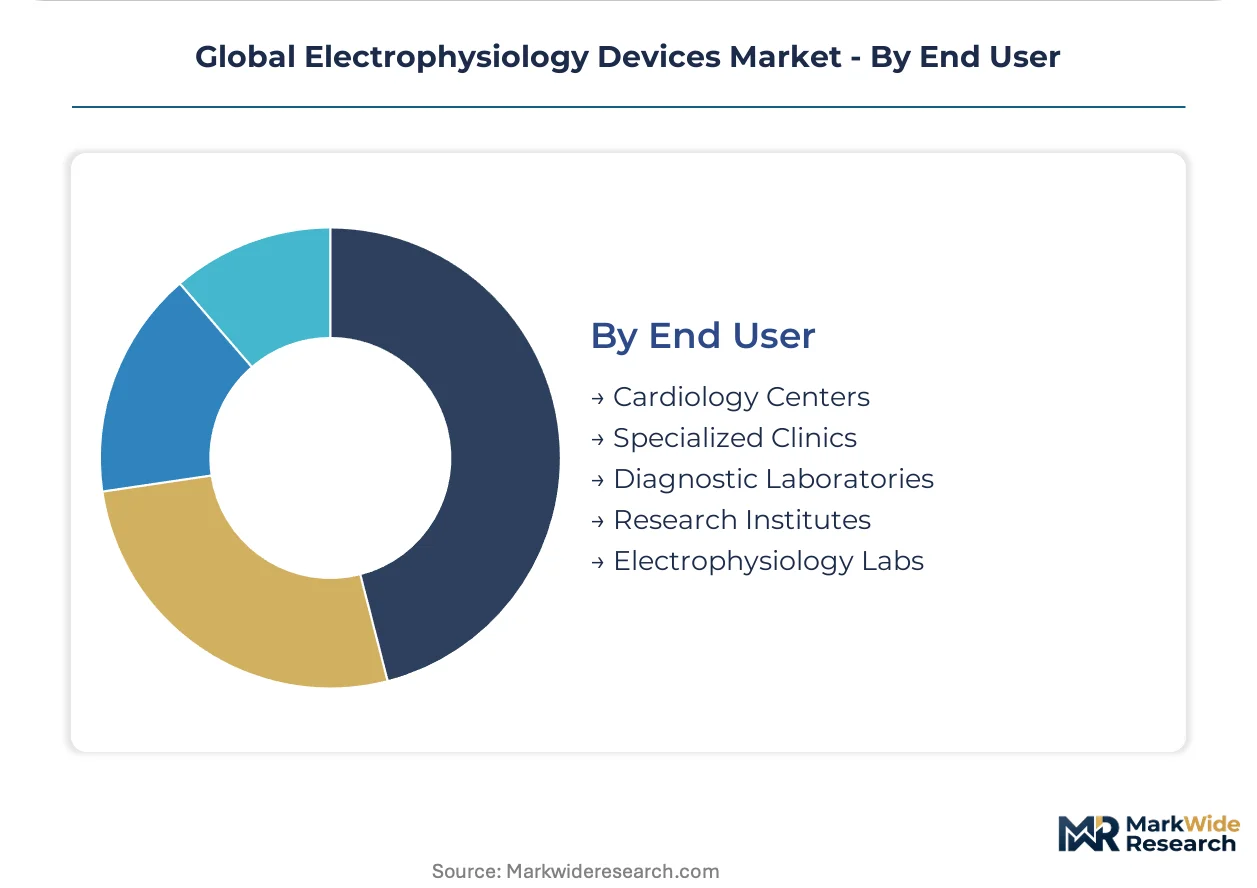
- Electrophysiology Labs:Dedicated procedural suites within hospital systems driving integrated platform adoption and multi-year service contract negotiations in United States integrated delivery networks.
- Cardiology Centers:High-volume specialized facilities concentrating advanced mapping system installations and fellowship-trained specialist staffing.
- Specialized Clinics:Outpatient-focused settings with selective diagnostic equipment procurement tied to referral patterns.
- Diagnostic Laboratories:Signal analysis and testing facilities with equipment replacement cycles governed by capital budget timelines.
- Research Institutes:Academic medical centers in Germany and the United States deploying high-density electrode arrays with automated signal annotation for workflow virtualization studies.
Capital authority rests with electrophysiology labs; research-driven innovation originates in academic institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany demonstrate the lowest price elasticity, while integrated delivery networks in the United States negotiate aggressively on capital equipment bundles. Japan occupies the middle ground, with METI reimbursement clarity stabilizing volumes despite premium pricing for advanced mapping platforms.
United States
Integrated delivery networks in the United States centralize purchasing authority, demanding transparent cost-per-procedure modeling from mapping system vendors. FDA breakthrough device designations for novel ablation technologies compress commercialization timelines, reducing evidence-generation burdens for innovators. The Cleveland Clinic and Mayo Clinic anchor electrophysiology innovation clusters, deploying high-density electrode arrays with automated signal annotation to virtualize operator workflows.
Germany
German hospital electrophysiology labs expand catheter-based ablation programs as first-line therapy for atrial fibrillation, supported by favorable G-BA reimbursement determinations. MDR conformity assessments impose stricter post-market surveillance obligations than predecessor MDD requirements, filtering market access for mid-tier entrants. The Rhine-Ruhr metropolitan region concentrates advanced procedural volume, with university hospitals in Düsseldorf and Cologne driving adoption of three-dimensional electroanatomic platforms.
Japan
Aging demographics in Japan sustain procedural volume expansion as guidelines elevate ablation ahead of antiarrhythmic pharmacology. METI coverage policies provide reimbursement clarity that reduces physician adoption thresholds for next-generation platforms. Tokyo and Osaka medical centers anchor the national electrophysiology infrastructure, with academic hospitals pioneering contact-force sensing integration in radiofrequency ablation segments.
China
Domestic manufacturers in China scale production of diagnostic equipment tied to hospital capital budget cycles, competing on replacement cost rather than premium feature sets. NMPA regulatory pathways for Class III medical devices impose clinical evidence requirements that extend time-to-market for novel energy modalities. The Yangtze River Delta cluster, centered on Shanghai and Suzhou, concentrates catheter manufacturing capacity and electrophysiology lab expansion.
Switzerland
Swiss precision engineering capabilities support component supply for multinational electrophysiology device manufacturers, particularly in sensor technology and catheter miniaturization. Swissmedic maintains alignment with EU MDR standards, ensuring seamless market access for CE-marked products. The Zurich-Geneva corridor hosts research institutes collaborating with industry on cryogenic energy modality development for high-complexity anatomical challenges.
Global Electrophysiology Devices Market Competitive Landscape
Integrated platform vendors and standalone catheter specialists split the market along capital intensity lines. The vendor base concentrates among multinational conglomerates with captive clinical affairs capabilities, while mid-tier manufacturers face disproportionate compliance burdens under Europe's MDR framework. Three archetypes dominate: hardware-software ecosystem integrators, contact-force sensing technology leaders, and cryoablation modality specialists. Competitive moves center on multi-year service contract unbundling and outcome-guaranteed performance agreements that shift risk toward manufacturers.
Within the integrated platform tier, Medtronic plc and Johnson & Johnson occupy positions defined by installed base maintenance revenue and deep catheter portfolio breadth. Abbott Laboratories exemplifies the sensing-technology archetype, anchoring differentiation in radiofrequency ablation segments. Koninklijke Philips N.V. represents the imaging-hardware convergence strategy, leveraging diagnostic equipment replacement cycles to secure mapping system placements.
| Leading Market Players |
|---|
| Medtronic plc |
| Koninklijke Philips N.V. |
| Johnson & Johnson |
| AtriCure, Inc. |
| Siemens Healthineers |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta cluster centered on Shanghai and Suzhou concentrates catheter manufacturing capacity for multinational electrophysiology device vendors, translating upstream scale into downstream pricing power across integrated delivery networks in the United States. Contract-manufacturing scale in this hub compresses unit economics for single-use ablation catheters while premium mapping system pricing in Germany and Japan reflects supply scarcity for three-dimensional electroanatomic platforms.
Pricing Analysis
Aftermarket service revenue from mapping system upgrades and catheter refurbishment programs drives lifetime value capture for integrated platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates contact-force sensing catheters from conventional radiofrequency instruments from refurbished diagnostic equipment. Cost compression in standard-tier catheters is intensifying because domestic manufacturers in China scale production of diagnostic equipment tied to hospital capital budget cycles. Hospital purchasing committees in integrated delivery networks demonstrate highest price sensitivity, while German electrophysiology labs show lowest elasticity due to G-BA reimbursement clarity.
Supply Chain Analysis
Contract-manufacturing concentration rests with precision engineering specialists in Switzerland and high-volume catheter producers in China and Ireland. Raw material dependencies draw from medical-grade polymers, platinum-iridium electrode alloys, and cryogenic gas supply chains. Single-source vulnerability concentrates in sensor technology for contact-force sensing platforms where Swiss component suppliers hold specialized capacity. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct tender processes in Germany, and regional medical device distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network centralization in the United States and hospital procurement committee consolidation in Germany, fragmenting vendor negotiation leverage across standalone catheter suppliers.
For Market Incumbents: Build installed base moats through multi-year service contracts that lock mapping system maintenance revenue independent of new capital sales. Defend against mid-tier entrants facing disproportionate MDR compliance burdens by accelerating software-enabled procedural efficiency investments. Prioritize backward integration into sensor technology for contact-force sensing platforms to secure component supply. For New Entrants and Emerging Players: Pursue white-space opportunities in cryogenic energy modality expansion for anatomical challenges where thermal ablation risks collateral damage. Target diagnostic equipment replacement demand in Chinese hospital systems competing on replacement cost rather than premium feature sets. Deploy direct tender participation in German university hospitals as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because aftermarket service unbundling reconfigures profitability models toward installed base maintenance. Acquisition targets should emphasize clinical affairs capabilities for MDR conformity assessments and captive quality infrastructure. Watch FDA breakthrough device designation velocity as the signal for platform commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessments filter market access for novel ablation technologies in European electrophysiology labs. |
| Hospital System Partnership | Integrated delivery networks in the United States demand transparent cost-per-procedure modeling from mapping system vendors. |
| Software Companion Development | Artificial intelligence integration compresses mapping acquisition times for three-dimensional electroanatomic platforms. |
| Reimbursement Strategy | G-BA and METI coverage determinations directly shape physician adoption thresholds in Germany and Japan. |
| Backward Integration | Upstream control over sensor technology secures supply for contact-force sensing catheter miniaturization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval filings, CE marking databases, hospital procurement records, and CMS reimbursement determinations. Conversations with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed procedural workflow and capital allocation dynamics. Secondary validation drew from ISO 13485 quality system audits, IEC 60601 electrical safety specifications, and trade data for medical device components. Bottom-up catheter volume estimates triangulated against top-down mapping system installation forecasts.
Forecast inputs incorporate procedural volume expansion tied to aging demographics, reimbursement clarity from CMS and G-BA, and technology substitution rates for three-dimensional electroanatomic platforms displacing fluoroscopy-guided procedures. Segmentation dimensions span product type, energy modality, arrhythmia indication, and end-user facility tier across the analysis window. CAGRs derive from installed base growth, replacement cycle timing, and premium pricing persistence for advanced energy modalities. Cryogenic energy modality adoption curves and contact-force sensing penetration rates inform scenario-weighted projections.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device tariff regimes, or electrophysiologist training pipeline output would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement determination continuity. Quarterly review of FDA breakthrough device designation grants, MDR conformity assessment completion rates, and integrated delivery network procurement centralization metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Global Medical Devices Market
Medical Devices
Pectus Bar Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Ehealth Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
North America Pen Needles Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
US Nurse Call Systems Market