
 Pediatric Home-Use Medical Devices Market | 2026-2036
Pediatric Home-Use Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Home-Use Medical Devices Market Outlook
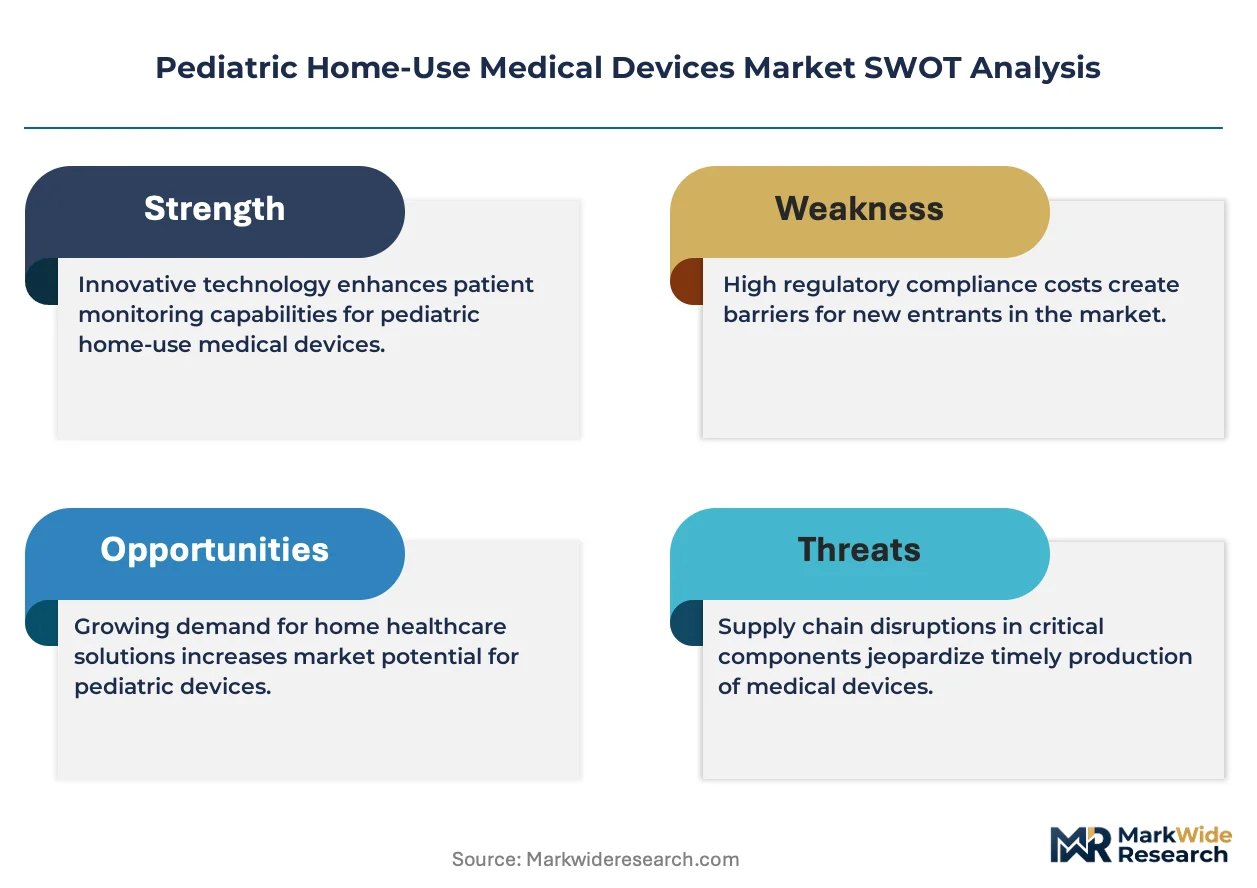
The EU MDR's heightened clinical-evidence thresholds for pediatric home-use devices is pivoting manufacturer investment toward wearable form factors with embedded biosensors. Koninklijke Philips N.V. anchors its position through hospital-at-home partnerships that extend clinical-grade monitoring into domestic settings. Medela specializes in neonatal respiratory support systems that navigate stringent premarket submission requirements across multiple jurisdictions. Owlet leverages direct-to-parent channel control to sustain premium positioning for its sock-based vital sign monitors.
Pediatric home-use medical devices encompass FDA-cleared and CE-marked instruments designed for non-clinical environments, typically operating within battery-powered, wireless-enabled architectures with weight thresholds under five kilograms and skin-contact biocompatibility per ISO 10993. These devices serve the industrial purpose of reducing preventable hospital readmissions while enabling real-time data transmission to pediatric specialists. Monitoring Devices dominate current revenue pools due to recurring sensor consumables and subscription telemetry services, while Telehealth Solutions represent the fastest-expanding technology segment as health systems deploy integrated platforms combining wearable inputs with video triage. Digital Sensors concentrate margin capture through proprietary algorithm development and FDA 510(k) exclusivity periods.
FDA's pediatric device consortia program and the EU MDR's Article 52 clinical-evaluation requirements shape market access timelines and predicate-device selection strategies for manufacturers. The Centers for Medicare & Medicaid Services' evolving remote therapeutic monitoring codes in the United States further determine reimbursement feasibility for home-based pediatric interventions. Stakeholders must monitor pending FDA guidance on artificial-intelligence-enabled pediatric diagnostics and state-level Medicaid telehealth parity legislation to anticipate coverage expansion or contraction for connected home devices.
Market Dynamics
The EU MDR's Article 52 clinical-evaluation mandates are compressing development timelines for pediatric wearables while simultaneously elevating predicate-device requirements. Manufacturers must now generate pediatric-specific safety data rather than extrapolating from adult studies, fundamentally restructuring R&D resource allocation.
Growth Catalysts
- Medicaid Home Health Expansion:State-level telehealth parity legislation in the United States is unlocking reimbursement for remote pediatric monitoring. This creates sustainable revenue streams for device manufacturers serving chronic respiratory populations.
- ISO 10993 Biocompatibility Standards:Harmonized international testing protocols for skin-contact materials are reducing redundant certification costs across multiple jurisdictions. Manufacturers leverage shared toxicology data to accelerate multi-market launches.
- Neonatal Intensive Care Discharge Protocols:Hospital-at-home programs are extending continuous monitoring into domestic settings for premature infants. This shift generates demand for portable respiratory support and vital sign surveillance systems.
Market Restraints
- Lithium-Ion Battery Supply Concentration:East Asian cell manufacturers control critical supply chains for wearable power systems. Geopolitical friction and raw material cost volatility threaten production continuity for battery-dependent devices.
- FDA Pediatric Device Consortia Funding Gaps:Limited federal grant availability constrains small manufacturers from conducting required premarket clinical trials. This creates structural barriers to entry independent of technical capability.
- Smartphone-App Dependency:Caregivers without reliable iOS or Android device access face exclusion from connected monitoring ecosystems. This technical prerequisite limits addressable market penetration in lower-income demographics.
Strategic Opportunities
- Behavioral Health Integration:Convergence of physiological sensors with AI-enabled mood and sleep pattern detection opens pediatric anxiety and ADHD management applications. This expands addressable conditions beyond traditional cardiopulmonary monitoring.
- Subscription Telemetry Services:Recurring revenue models for data transmission and clinical alert management are displacing one-time hardware sales. Health systems in Germany and the United Kingdom are piloting per-patient-month reimbursement structures.
- India PLI Scheme for Medical Electronics:Production-linked incentives for domestic manufacturing reduce import dependency and create regional supply hubs for South Asian markets. Local assembly capabilities lower landed costs for price-sensitive segments.
Industry Challenges
- Pediatric Clinical Trial Recruitment:Ethical review board complexity and parental consent requirements extend study timelines. This compresses effective patent exclusivity periods for novel sensor algorithms.
- Legacy Hospital IT Integration:Home-use devices must interface with diverse electronic health record systems lacking standardized APIs. Engineering teams absorb significant customization costs for each health system deployment.
- Post-Market Surveillance Infrastructure:Manufacturers face escalating FDA MDR (Medical Device Reporting) obligations for real-world adverse event tracking. This demands dedicated pharmacovigilance staffing that strains mid-cap organizational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Home-Use Medical Devices Market |
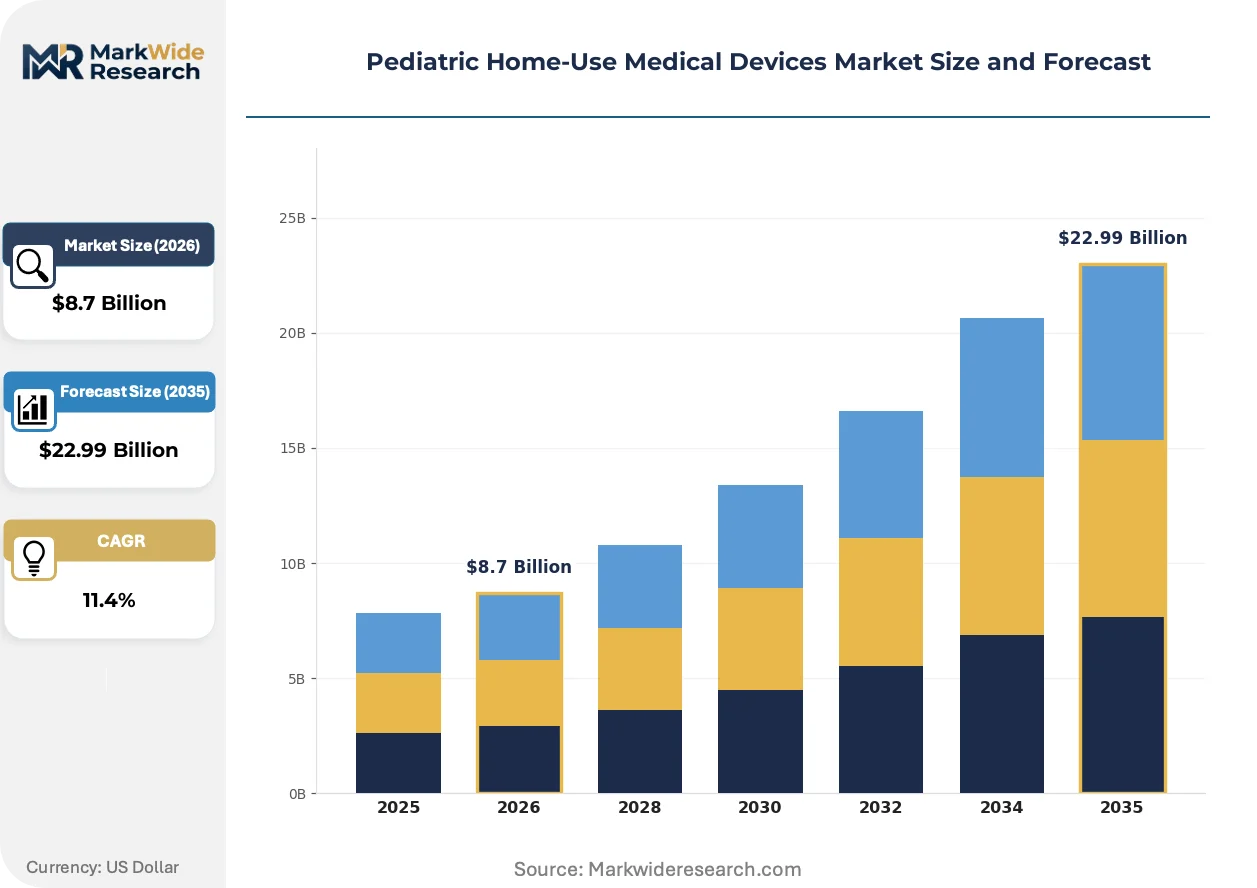
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Therapeutic Devices, Diagnostic Devices, Assistive Devices Technology: Wearable Technology, Telehealth Solutions, Mobile Applications, Digital Sensors End User: Parents, Caregivers, Pediatric Patients, Health Professionals Application: Chronic Disease Management, Rehabilitation, Wellness Monitoring, Emergency Care |
| Companies Covered | Blue Spark Technologies, Inc., Medela, Owlet, Bempu Health, Koninklijke Philips N.V., Ventec Life Systems, DIMA ITALIA, Drager, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Home-Use Medical Devices Market Strategic Shifts
Artificial intelligence is embedding directly into edge-computing sensors, enabling real-time anomaly detection without cloud dependency. This architectural shift reduces latency for critical pediatric alerts while addressing parental data privacy concerns.
Photoplethysmography arrays with multi-wavelength LED configurations are absorbing market share from traditional pulse oximetry in neonatal applications. NICU discharge planners specify these advanced sensors for home monitoring of premature infants with chronic lung disease. The technology is absorbing margin from conventional SpO2 probes by bundling respiratory rate and perfusion index into single disposable units.
REACH Annex XVII restrictions on skin-contact substances are forcing reformulation of adhesive materials in wearable patches. European manufacturers are accelerating biocompatible silicone alternatives through notified body review. Pediatric dermatology claims represent the fastest-growing product liability exposure, driving substitution toward hypoallergenic attachment systems.
Direct-to-parent e-commerce channels are capturing volume previously routed through durable medical equipment suppliers. Amazon and specialized pediatric health platforms now handle fulfillment for pulse oximeters and nebulizer systems. This disintermediation concentrates in the United States where out-of-pocket payment tolerance remains highest for non-reimbursed monitoring accessories.
Pediatric Home-Use Medical Devices Market Segmentation
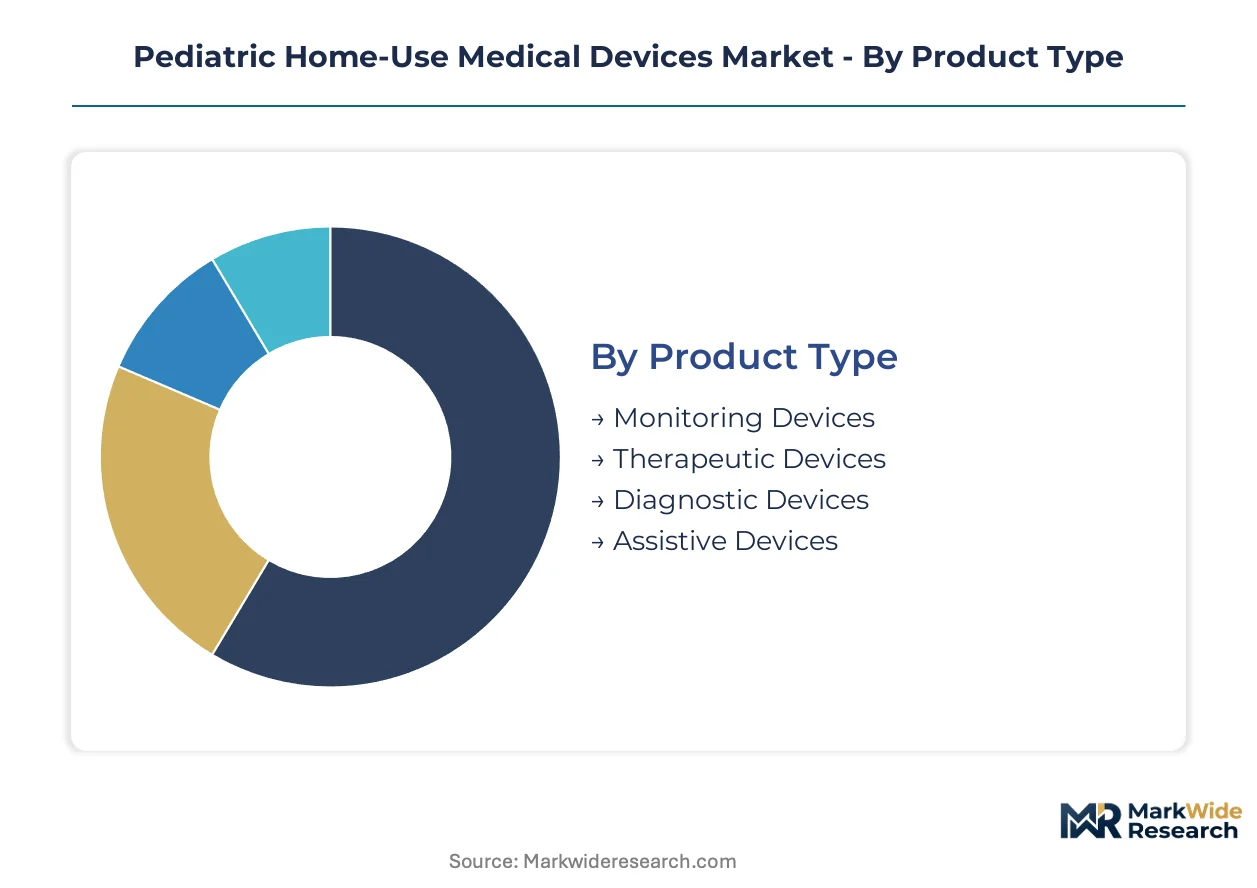
Segmentation in pediatric home-use medical devices reveals how technical specifications, user workflows, and reimbursement pathways intersect to determine commercial viability. Manufacturers must align form factor decisions with the specific constraints of domestic care environments and the clinical oversight models that govern them.
Product Type:
Form factor and regulatory classification define how devices navigate FDA 510(k) pathways and Medicaid reimbursement codes.
- Monitoring Devices:Battery-powered units with wireless telemetry for vital signs, respiratory rate, and oxygen saturation. Demand concentrates among parents of children with congenital heart defects in states with expanded Medicaid home health benefits. Recurring sensor consumables and subscription data services sustain margin pools.
- Therapeutic Devices:Portable nebulizers, respiratory support systems, and medication delivery platforms operating under ISO 13485 quality systems. NICU discharge planners in hospital-at-home programs specify these for premature infants with chronic lung disease, driving volume through clinical procurement channels.
- Diagnostic Devices:Point-of-care testing kits for glucose, infection markers, and metabolic panels.
- Assistive Devices:Mobility supports and adaptive equipment for neuromuscular conditions.
Monitoring Devices lead on scale; Therapeutic Devices lead on momentum.
Technology:
Architecture choices determine data latency, parental usability, and integration complexity with hospital EHR systems.
- Wearable Technology:Skin-contact biosensors in sock, patch, or band formats with embedded edge computing. Parents of children with epilepsy and sleep apnea in Germany and the United Kingdom drive adoption through direct-to-consumer channels, though FDA clearance requirements constrain US market entry timelines.
- Telehealth Solutions:Integrated platforms combining video triage, asynchronous messaging, and device data dashboards. Health systems in the United States deploy these under remote patient monitoring reimbursement codes, with per-patient-month billing models displacing hardware-only transactions.
- Mobile Applications:iOS and Android software for device configuration, data visualization, and alert management.
- Digital Sensors:Discrete photoplethysmography and accelerometer components with proprietary algorithms.
Wearable Technology captures installed base concentration; Telehealth Solutions capture revenue expansion velocity.
End User:
Decision-making authority and technical literacy shape interface design requirements and customer acquisition costs.
- Parents:Primary purchasers for wellness monitoring and chronic condition oversight. Direct-to-parent e-commerce through Amazon and specialized pediatric platforms concentrates in the United States where out-of-pocket tolerance for non-reimbursed accessories remains highest.
- Caregivers:Extended family members and home health aides operating under nursing supervision. Medicaid-funded home care programs in California and New York generate institutional procurement volume for training-intensive therapeutic devices.
- Pediatric Patients:Adolescents with diabetes or asthma managing self-care protocols.
- Health Professionals:Pediatricians and nurse practitioners prescribing and monitoring home-use regimens.
Parents dominate transaction volume; Caregivers represent the expanding addressable pool under home health benefit expansion.
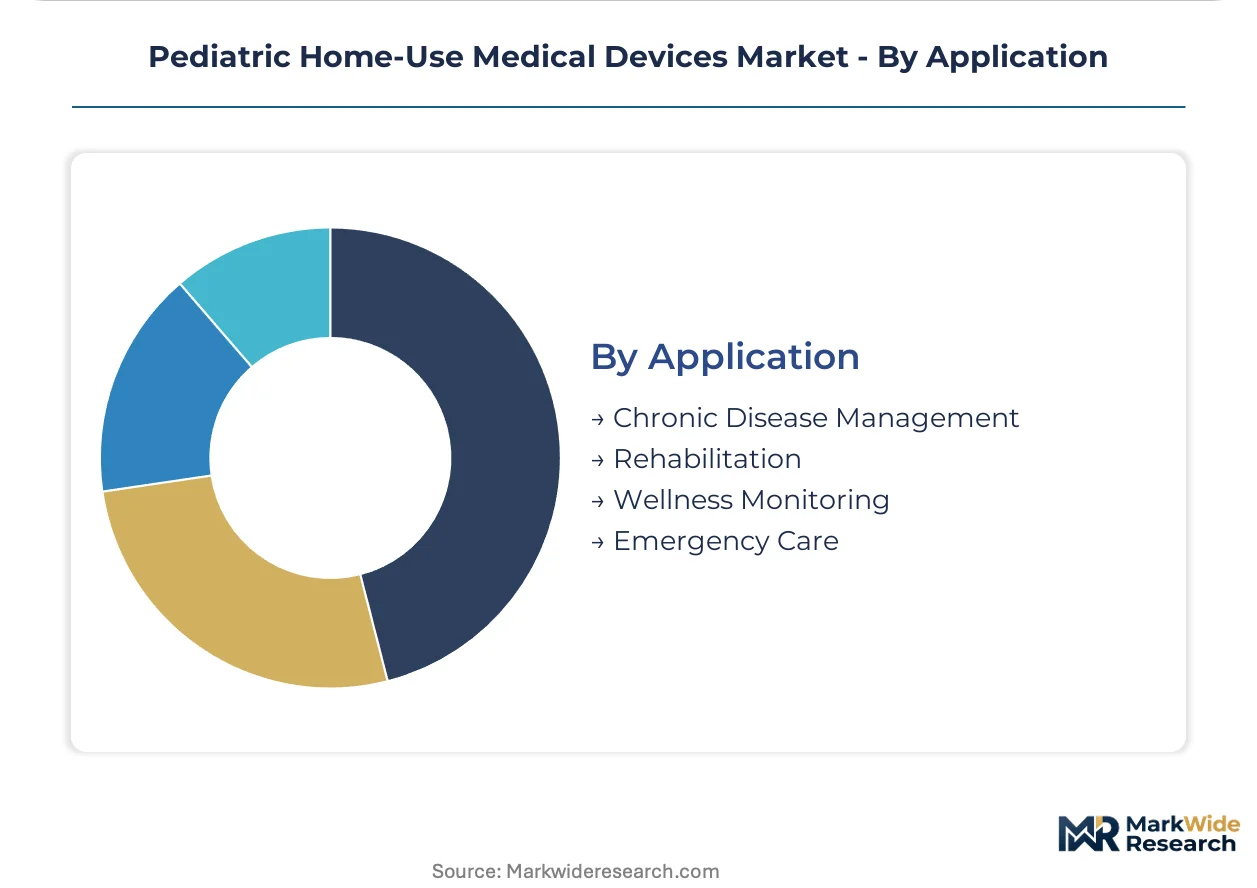
Application:
Clinical indication determines sensor specification, alert threshold calibration, and specialist oversight intensity.
- Chronic Disease Management:Continuous monitoring for asthma, congenital heart disease, and type 1 diabetes. Demand clusters in the United States where CMS remote therapeutic monitoring codes reimburse for home-based physiologic data collection and analysis.
- Wellness Monitoring:Sleep quality, activity tracking, and developmental milestone surveillance for healthy infants. Direct-to-parent marketing and premium pricing sustain margin despite absence of insurance coverage.
- Rehabilitation:Post-surgical and post-injury recovery protocols with prescribed device usage.
- Emergency Care:Acute event detection and automated alert escalation systems.
Chronic Disease Management anchors revenue stability; Wellness Monitoring climbs the fastest through consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pediatric home-use medical device industry traces its commercial origins to post-war American hospital discharge programs, with European regulatory harmonization and Asian manufacturing scale subsequently redistributing production and demand across three continents.
United States
Medicaid home health benefit expansions in California and New York drive procurement volume for respiratory monitoring systems. CMS remote therapeutic monitoring reimbursement codes enable per-patient-month billing models that sustain subscription telemetry services. The Boston-Cambridge corridor concentrates algorithm development for FDA-cleared pediatric wearables.
Germany
Hospital-at-home programs for premature infants generate institutional demand for portable vital sign surveillance. EU MDR Article 52 clinical-evaluation requirements compress development timelines while elevating predicate-device standards. The Munich-Stuttgart industrial axis hosts notified body review capacity and biocompatible adhesive material suppliers.
United Kingdom
NHS pilot programs for per-patient-month reimbursement structures accelerate telehealth platform deployment. MHRA alignment with EU MDR post-Brexit maintains stringent pediatric-specific safety data requirements. London health technology clusters integrate wearable inputs with video triage systems for chronic respiratory populations.
India
Production-linked incentive schemes for medical electronics reduce import dependency for South Asian markets. CDSCO streamlined pathways for Class A and B devices accelerate market entry for low-risk monitoring accessories. Karnataka and Telangana host emerging domestic assembly capabilities for price-sensitive segments.
Japan
Aging demographics and declining birth rates concentrate demand on neonatal intensive care discharge protocols. PMDA consultation procedures for pediatric devices align with ISO 14155 clinical investigation standards. The Kansai region maintains precision manufacturing clusters for miniaturized sensor components.
Pediatric Home-Use Medical Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in pediatric home-use medical devices. The market structure consolidates around diversified health technology conglomerates with hospital-at-home partnerships, while mid-cap specialists occupy niche therapeutic segments. Three archetypes dominate: integrated health systems vendors, direct-to-parent consumer brands, and neonatal respiratory specialists. Competitive maneuvering concentrates on M&A for telemetry platform capabilities and strategic partnerships with Medicaid managed care organizations.
Within the integrated systems tier, Koninklijke Philips N.V. and Drager occupy positions anchored by hospital procurement relationships and regulatory compliance infrastructure. Among direct-to-consumer specialists, Owlet exemplifies asset-light channel control through e-commerce fulfillment. Medela represents the neonatal respiratory archetype with concentrated expertise in premarket submission navigation across FDA and EU MDR jurisdictions.
| Leading Market Players |
|---|
| Blue Spark Technologies, Inc. |
| Medela |
| Owlet |
| Bempu Health |
| Koninklijke Philips N.V. |
| Ventec Life Systems |
| DIMA ITALIA |
| Drager |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
Captive integration into biocompatible adhesive manufacturing anchors margin control for wearable patch producers navigating REACH Annex XVII compliance. This upstream positioning shields European notified body submissions from raw material reformulation delays while preserving premium pricing power for ISO 10993-certified skin-contact devices.
Pricing Analysis
Subscription telemetry models with per-patient-month billing displace one-time hardware transactions across hospital-at-home programs. Price differentiation separates FDA-cleared devices with 510(k) exclusivity from CE-marked equivalents lacking predicate-device advantages, with certification tier commanding premium positioning. Pricing pressure stems from direct-to-parent e-commerce channels capturing volume previously routed through durable medical equipment suppliers. Medicaid-funded procurement exhibits highest price sensitivity, while private-pay wellness monitoring segments absorb premium positioning for non-reimbursed accessories.
Supply Chain Analysis
Workforce availability constraints in precision sensor assembly concentrate production gravity across China's Yangtze River Delta, South Korea's Gyeonggi Province, and Japan's Kansai industrial corridor. Component sourcing draws from East Asian lithium-ion cell manufacturers for wearable power systems, Taiwanese photoplethysmography foundries for multi-wavelength LED arrays, and German silicone suppliers for hypoallergenic adhesives. Single-source vulnerability in rare earth magnet supply for miniaturized motors threatens production continuity. Distribution runs through Amazon fulfillment centers and specialized pediatric health platforms for direct-to-consumer segments, with GPO contracts anchoring hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric home-use medical device market functions as a regulatory compounder, with EU MDR Article 52 clinical-evaluation mandates and FDA pediatric device consortia funding structures accelerating consolidation around compliance-capable incumbents.
For Market Incumbents: Anticipate margin compression from direct-to-parent e-commerce disintermediation by deepening hospital-at-home partnership exclusivity. Secure backward integration into biocompatible adhesive manufacturing to deflect REACH Annex XVII reformulation costs. Prioritize telemetry platform acquisitions that bundle wearable inputs with video triage capabilities for health system stickiness. For New Entrants and Emerging Players: CDSCO streamlined pathways for Class A and B devices in India open a window for low-risk monitoring accessories targeting price-sensitive South Asian segments. White-space concentrates in behavioral health applications converging physiological sensors with AI-enabled mood detection for pediatric anxiety management. Pursue per-patient-month reimbursement pilot participation in NHS programs to establish institutional credibility before FDA submission. For Investors and Strategic Acquirers: Roll-up economics work for telemetry platform specialists because health system procurement consolidation demands integrated data dashboards over point-solution hardware. Five-to-ten year viability hinges on algorithm exclusivity periods and predicate-device libraries. Monitor FDA guidance publication timelines on artificial-intelligence-enabled pediatric diagnostics as inflection signal for coverage expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 52 compliance accelerates multi-market launch velocity for wearable form factors. |
| Hospital System Partnership | NICU discharge protocol integration secures institutional procurement channels for respiratory monitoring. |
| Software Companion Development | Edge-computing AI embedding addresses parental data privacy concerns while reducing cloud latency. |
| Reimbursement Strategy | CMS remote therapeutic monitoring code alignment enables per-patient-month billing model sustainability. |
| Backward Integration | In-house biocompatible adhesive production shields margins from REACH Annex XVII reformulation mandates. |
Study Parameters
Multiple input streams — regulatory filing databases, hospital procurement records, and direct stakeholder consultation — were reconciled through bottom-up and top-down triangulation. Primary interviews with pediatricians, biomedical engineers, GPO contracts managers, and Medicaid policy specialists informed demand-side validation. Secondary sources encompassed FDA 510(k) clearances, EU MDR notified body opinions, CMS reimbursement code updates, and ISO 10993 biocompatibility testing registries.
Data-stream reconciliation across product type, technology architecture, end-user decision authority, and clinical application indication generated segmented volume and value outputs across the projection horizon. CAGRs were derived from install-base growth rates and replacement cycle analysis for sensor consumables. Forecast inputs incorporated Medicaid home health benefit expansion trajectories, EU MDR implementation phase-in schedules, and production-linked incentive scheme uptake in Indian medical electronics.
Revisions become necessary when FDA pediatric AI guidance materializes, EU MDR notified body capacity constraints intensify, or lithium-ion supply chain disruptions propagate. Forecasts reflect documented assumptions regarding reimbursement code stability and predicate-device availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ventilator Accessories Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Global Bowel Management System Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Gastric Bands Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Pulse Lavage Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
EEG and EMG Equipment Market