
 Global Neurology Ultrasonic Aspirators Market | 2026-2036
Global Neurology Ultrasonic Aspirators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurology Ultrasonic Aspirators Market Intelligence
Expanding medical device manufacturing capabilities in China is rewriting the competitive positioning for component sourcing. Stryker leverages its established presence in academic medical centers across the United States to drive sales of integrated surgical systems. Söring GmbH differentiates through its focus on piezoelectric transducer innovations, while Integra LifeSciences sustains its market share via a broad neurosurgical portfolio.
Neurology ultrasonic aspirators are surgical devices that use low-frequency ultrasonic vibrations, typically between 20-60 kHz, to fragment soft tissue. Their primary function is the selective removal of pathological tissue, such as brain tumors, while preserving adjacent healthy structures. Integrated surgical systems command the highest value, but handheld aspirators represent the largest volume segment due to their versatility and lower cost. Within applications, tumor resection remains the dominant use case, driving the majority of procedural volume.
Device approval and market access are governed by stringent regulations from bodies like the US FDA, Europe's EMA under the Medical Device Regulation (MDR), and China's NMPA. These frameworks mandate extensive clinical data on safety and efficacy, which directly influences product development timelines and R&D investment. Future device differentiation will increasingly depend on integrating advanced imaging and real-time navigation capabilities to improve surgical precision and patient outcomes.
Market Dynamics
The central dynamic shaping the market is the intensified push for greater surgical precision, driven by advancements in piezoelectric transducers and real-time navigation. This technological momentum is reinforced by stringent regulatory frameworks from bodies like the FDA and EMA demanding demonstrable improvements in patient safety.
Growth Catalysts
- Piezoelectric Transducer Technology:Continued innovation in transducer design enhances the efficiency and selectivity of tissue fragmentation. This allows for safer removal of tumors near critical neural and vascular structures, expanding procedural eligibility for patients with complex cases.
- Rising Procedural Volumes:An aging global population and improved diagnostic imaging are increasing the rate of brain tumor diagnoses. This directly fuels procedural volume in specialized neurosurgery departments, sustaining demand for ultrasonic aspirators.
- Healthcare Infrastructure Investment:Governments in several emerging economies are channeling funds into developing centers of excellence for neurology and oncology. This creates new installation opportunities for integrated surgical systems in previously underserved markets.
Market Restraints
- High Capital Expenditure:The significant upfront cost of integrated ultrasonic aspirator systems, which often include neuronavigation and imaging, restricts their acquisition to well-funded, high-volume academic medical centers and large hospital systems.
- Stringent Regulatory Pathways:Extensive clinical data requirements mandated by Europe's Medical Device Regulation (MDR) and the US FDA create long development timelines and substantial compliance costs, acting as a barrier to new market entrants.
- Technical Limitations in Thermal Management:Despite improvements, managing heat generation at the surgical tip remains a critical challenge. This requires sophisticated irrigation and aspiration components and highly skilled operators to prevent thermal injury to adjacent healthy tissue.
Strategic Opportunities
- Integration with Robotic Platforms:Combining the precision of ultrasonic aspiration with the stability and control of robotic-assisted surgical systems presents a significant opportunity. This convergence can enhance surgeon ergonomics and enable more complex, minimally invasive procedures.
- Expansion into Spinal Neurosurgery:Adapting ultrasonic aspirator technology for the precise debulking of spinal cord tumors and calcified intervertebral discs represents a key growth vector. This application is less penetrated than cranial surgery and offers substantial upside.
- Penetration of Ambulatory Surgery Centers:The development of more compact, lower-cost handheld aspirators creates an opportunity to serve the growing number of outpatient neurosurgery procedures performed in ambulatory surgery centers, particularly in the United States.
Industry Challenges
- Specialized Surgeon Training Gap:The effective and safe operation of advanced ultrasonic aspirators necessitates extensive, device-specific training. A shortage of comprehensive training programs and certified instructors can slow the adoption rate of new technologies in hospitals.
- System Interoperability:Ensuring seamless data communication between ultrasonic aspirators, third-party neuronavigation systems, and hospital electronic health record (EHR) platforms remains a persistent technical hurdle, complicating workflow integration in the operating room.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurology Ultrasonic Aspirators Market |
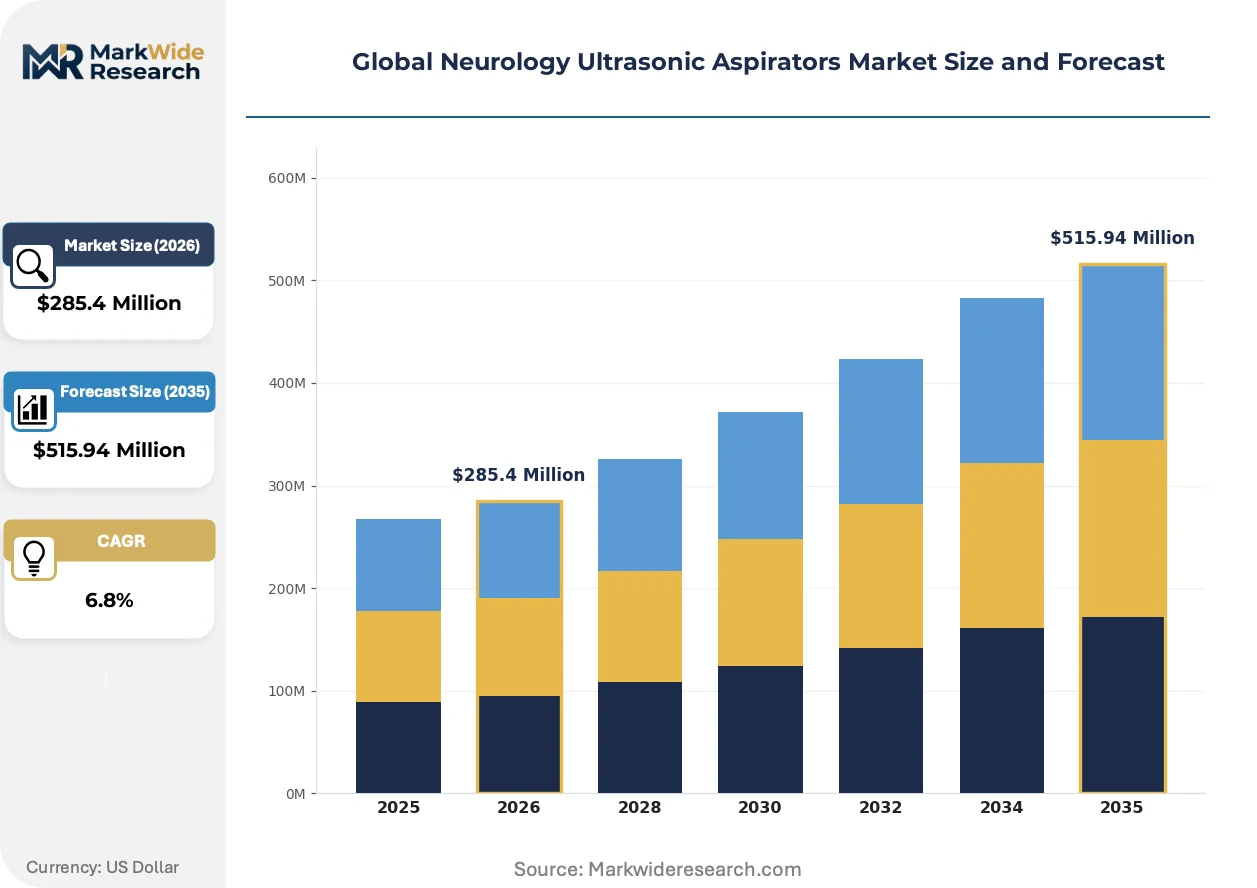
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Aspirators, Tabletop Units, Integrated Surgical Systems, Portable Devices Technology: Ultrasound Frequency Modulation, Piezoelectric Transducers, Pulsed Ultrasonics, High-Intensity Focused Ultrasound Application: Tumor Resection, Vascular Surgery, Neurodegenerative Therapy, Epilepsy Treatment, Traumatic Injury Repair End User: Specialized Neurosurgeons, Academic Medical Centers, Private Clinics, Research Institutions |
| Companies Covered | Stryker, Integra LifeSciences, Olympus Corporation, Söring GmbH, Bioventus, Xcellance Medical Technologies, Cybersonics, Meta Dynamic, Innosurge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurology Ultrasonic Aspirators Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of advanced sensor technology, data analytics, and minimally invasive surgical techniques. This synthesis is creating intelligent platforms that augment surgeon capabilities, aiming to standardize procedural outcomes in complex neuro-oncology cases across different hospital settings.
AI-driven tissue recognition software is a pivotal innovation, using algorithms to analyze ultrasonic feedback signals in real time. Specialized neuro-oncology centers are the primary adopters, seeking to improve the accuracy of tumor margin identification during resection. This integration of artificial intelligence is virtualizing the surgeon's tactile sense, creating a digital feedback layer that provides objective characterization of tissue consistency.
Data governance frameworks, including HIPAA in the United States and GDPR in Europe, are imposing strict requirements on the security and privacy of patient information generated by connected surgical devices. This regulatory pressure compels manufacturers to embed robust cybersecurity measures and standardized data protocols into their integrated systems. The neurology device segment is particularly affected, needing to re-engineer software to ensure full compliance.
A shift toward flexible, usage-based acquisition models is gaining traction over traditional upfront capital equipment sales. Hospitals are increasingly interested in per-procedure pricing for handpieces and consumables, which aligns costs with surgical volume and converts capital expenditures to operational expenses. This trend is most visible within large hospital networks in North America and Western Europe.
Global Neurology Ultrasonic Aspirators Market Segmentation
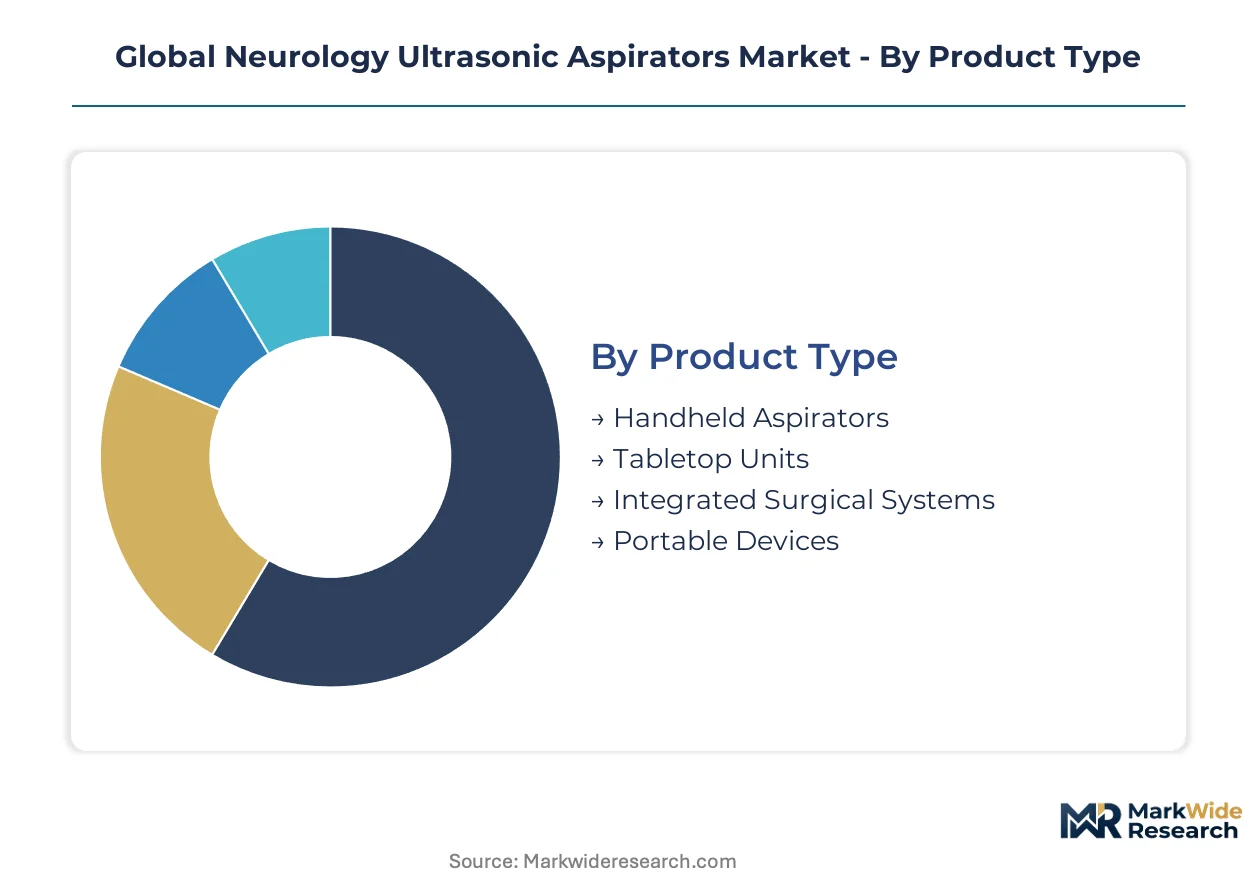
The global neurology ultrasonic aspirators market differentiates across several key dimensions, reflecting the diverse technological needs and clinical applications within neurosurgery. Understanding these segments is critical for manufacturers to align product development with evolving surgical practices and healthcare infrastructure capabilities.
Product Type:
The volume and complexity of procedures dictate the preference for specific aspirator product types, influencing procurement decisions across surgical settings.
- Integrated Surgical Systems:These comprehensive platforms combine ultrasonic aspiration with advanced neuronavigation, real-time imaging, and robotic assistance. Such systems are acquired by major academic medical centers in Germany and large hospital networks in the United States for complex tumor resections.
- Handheld Aspirators:Compact and versatile, these devices offer cost-effective solutions for a broad range of neurosurgical procedures, particularly in smaller clinics and ambulatory surgery centers. Their portability supports diverse clinical environments.
- Tabletop Units:These devices provide a balance between the advanced features of integrated systems and the portability of handheld units, often found in specialized neurosurgery departments. They typically include a console for power and irrigation management.
- Portable Devices:Designed for flexibility, these aspirators cater to settings requiring mobility or where space is constrained, offering essential ultrasonic fragmentation capabilities.
Handheld Aspirators holds installed capacity. Integrated Surgical Systems is rotating up the share rankings.
Technology:
Technological maturity and precision define the competitive landscape within neurology ultrasonic aspirator systems, driving continuous innovation in tissue selectivity.
- Piezoelectric Transducers:These core components convert electrical energy into precise mechanical vibrations, enabling highly selective tissue fragmentation and minimizing damage to surrounding healthy neural structures. Innovations in these transducers enhance surgical safety and efficacy.
- High-Intensity Focused Ultrasound:This non-invasive or minimally invasive technology delivers concentrated ultrasonic energy to ablate target tissue without incisions. Research institutions in Japan and the US explore its potential for deep brain lesion treatment.
- Ultrasound Frequency Modulation:This technique allows for dynamic adjustment of ultrasonic frequencies during surgery, optimizing tissue removal based on tissue density and consistency. It enhances adaptability for varied pathological tissues.
- Pulsed Ultrasonics:Delivering ultrasonic energy in short bursts reduces thermal buildup at the surgical tip, providing improved thermal management and reducing the risk of adjacent tissue injury.
Advancements in Piezoelectric Transducers drive performance gains. High-Intensity Focused Ultrasound exhibits a steep expansion trajectory.
Application:
The impact on patient outcomes and the prevalence of specific neurological conditions shape the demand for ultrasonic aspirators across various clinical applications.
- Tumor Resection:This remains the primary application, leveraging ultrasonic aspirators for precise debulking of brain and spinal tumors while preserving critical neural pathways. Specialized neuro-oncology centers rely on these devices for improved surgical margins.
- Epilepsy Treatment:Ultrasonic aspirators facilitate the removal of epileptogenic foci in the brain, offering a targeted approach to reduce seizure frequency in refractory cases. This application requires extreme precision near eloquent brain areas.
- Vascular Surgery:These devices assist in the removal of calcified plaques or other obstructions in cerebral vasculature, requiring delicate tissue manipulation.
- Neurodegenerative Therapy:Research explores the use of ultrasonic aspiration for targeted tissue removal in conditions like Parkinson's disease, though clinical adoption is emerging.
- Traumatic Injury Repair:In cases of severe head trauma, ultrasonic aspirators can aid in the removal of hematomas or damaged tissue to alleviate pressure and facilitate recovery.
Tumor Resection accounts for the largest procedural volume. Epilepsy Treatment is gaining share fastest.
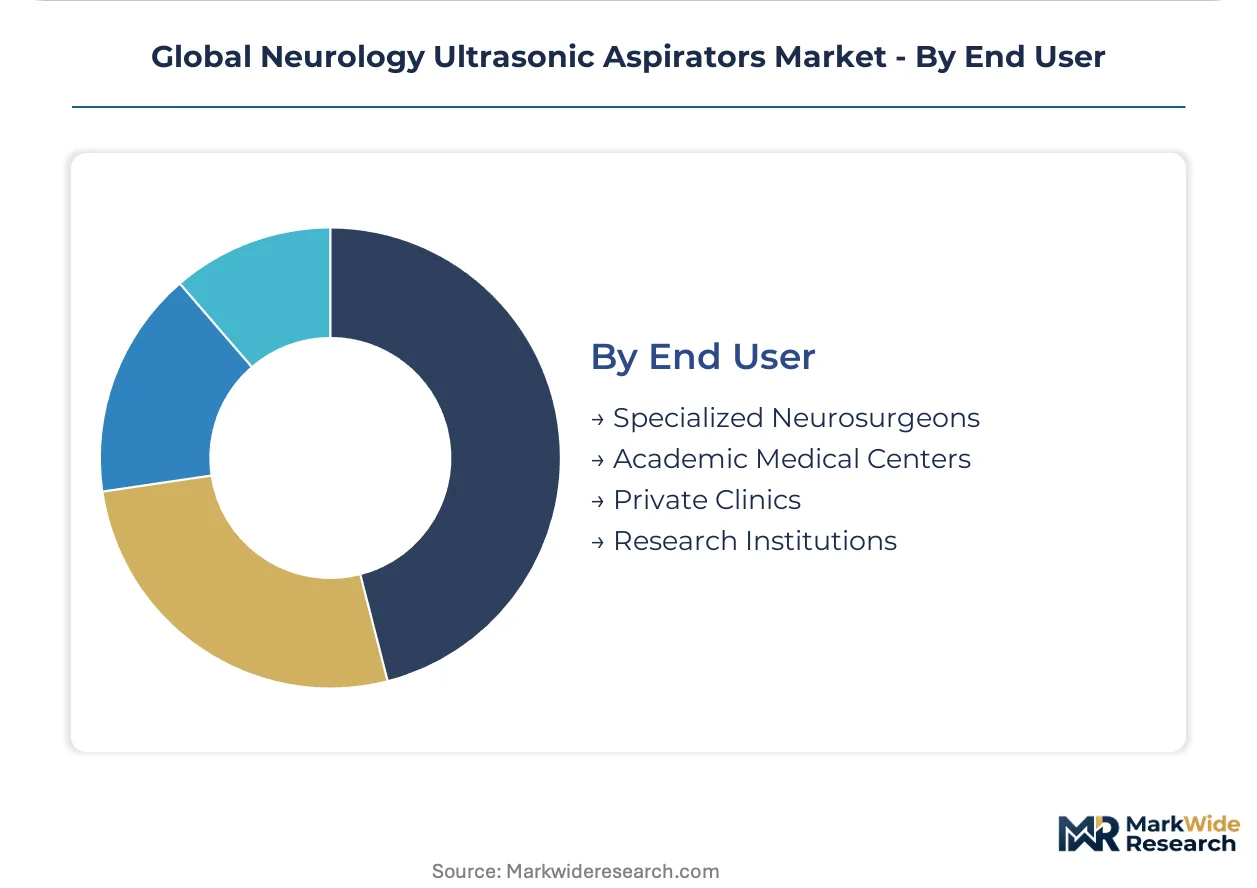
End User:
The resource allocation and specialized expertise available at different healthcare facilities dictate the adoption patterns for neurology ultrasonic aspirators.
- Academic Medical Centers:These institutions serve as primary adopters of advanced integrated surgical systems due to their high patient volumes, research mandates, and significant capital budgets. They drive innovation in surgical techniques.
- Specialized Neurosurgeons:Individual neurosurgeons, whether in private practice or hospital settings, are the direct operators and decision-makers for device selection based on their training and procedural needs. Device-specific training is paramount.
- Private Clinics:Smaller clinics often opt for more cost-effective handheld aspirators, focusing on less complex procedures or as supplementary tools to their existing surgical armamentarium. These clinics prioritize operational efficiency.
- Research Institutions:These entities utilize ultrasonic aspirators for experimental procedures, device development, and preclinical studies, contributing to future technological advancements and application expansion.
Academic Medical Centers lead in integrated system procurement. Specialized Neurosurgeons are central to adoption decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of specialized manufacturing capabilities in key regions influences the global neurology ultrasonic aspirators market. Developed healthcare systems drive demand for advanced integrated surgical systems. This global market sees innovation and adoption patterns shaped by regional regulatory landscapes and investment in neurosurgical infrastructure.
United States
High procedural volumes for tumor resection and the presence of numerous academic medical centers drive demand for advanced ultrasonic aspirators. The US FDA mandates extensive clinical data for device approval, influencing product development timelines. Major medical technology clusters in Boston and California foster innovation in integrated surgical systems and advanced imaging.
Germany
Academic medical centers in Germany are primary adopters of integrated surgical systems, focusing on precision neurosurgery. Compliance with Europe's Medical Device Regulation (MDR) ensures high safety and efficacy standards for devices. Bavaria and North Rhine-Westphalia serve as significant hubs for medical device manufacturing and neurosurgical research.
Japan
Japan's research institutions and an aging population contribute to the demand for advanced neurology ultrasonic aspirators, particularly for brain tumor diagnoses. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for new medical technologies. Tokyo and Osaka regions are centers for medical device R&D and specialized neurosurgical care.
China
Expanding medical device manufacturing capabilities and significant healthcare infrastructure investment are boosting the market for neurology ultrasonic aspirators in China. The National Medical Products Administration (NMPA) regulates device market access and quality standards. The Yangtze River Delta region is a key area for medical device production and distribution.
France
France's advanced neurosurgical units and public health investments support the adoption of high-precision ultrasonic aspirators. Devices must comply with the European Medical Device Regulation (MDR) and the national regulatory oversight of ANSM. The Paris region is a hub for clinical research and the development of medical technologies for neuro-oncology.
Global Neurology Ultrasonic Aspirators Market Key Industry Players
Established medical device giants and specialized neurosurgical innovators split the market for neurology ultrasonic aspirators. The market exhibits a tiered structure, with a few large multinational corporations dominating the integrated systems segment and numerous smaller players offering handheld devices. Strategic archetypes include diversified healthcare conglomerates and niche technology specialists. Companies engage in portfolio diversification and strategic partnerships to strengthen their market positions.
Within the diversified healthcare conglomerate archetype, Stryker, an American multinational, and Integra LifeSciences, a US-based medical technology company, maintain expansive neurosurgical portfolios. Söring GmbH, a German medical technology firm, exemplifies the niche technology specialist, focusing on innovations in piezoelectric transducer technology. These companies anchor different segments of the market, from high-value integrated systems to specialized component advancements.
| Leading Market Players |
|---|
| Stryker |
| Integra LifeSciences |
| Olympus Corporation |
| Söring GmbH |
| Bioventus |
| Xcellance Medical Technologies |
| Cybersonics |
| Meta Dynamic |
| Innosurge |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding medical device manufacturing capabilities directly influence global component pricing for neurology ultrasonic aspirators. This concentrated production capacity, particularly for specialized electronics and precision mechanical parts, creates both cost efficiencies and potential single-source vulnerabilities across the supply chain.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure for integrated surgical systems, emphasizing value-based pricing linked to clinical outcomes and safety data. Price differentiation stems from the level of integration with advanced imaging and neuronavigation systems, alongside the device's CE marking and FDA approval status. Pricing pressure stems from the increasing availability of lower-cost handheld aspirators, particularly impacting procurement decisions in private clinics. Academic medical centers, prioritizing advanced features and patient outcomes, exhibit lower price sensitivity compared to smaller ambulatory surgery centers focused on operational efficiency.
Supply Chain Analysis
Export controls on dual-use technologies, particularly advanced piezoelectric ceramics and high-frequency transducers, limit their unrestricted flow and impact the supply chain. Geographic supply concentration for critical components centers on specialized manufacturers in China, Germany, and Japan. The market relies heavily on high-purity piezoelectric materials and specialized polymers for device construction. Logistics chokepoints for these precision components represent a structural risk, potentially delaying product delivery. Distribution runs through a combination of direct sales forces for integrated systems and specialized medical device distributors for handheld and tabletop aspirators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, as the growing demand for minimally invasive neurosurgical procedures creates distinct niches for specialized devices and integrated solutions.
For Market Incumbents: Harden market leadership by investing in advanced imaging integration and AI-driven tissue recognition software. Strategic acquisitions of specialized component manufacturers, particularly those innovating in piezoelectric transducer technology, can mitigate supply chain risks. This reinforces channel control within high-volume academic medical centers against emerging compact device manufacturers.
For New Entrants and Emerging Players: Pursue market entry by developing compact, cost-effective handheld aspirators tailored for ambulatory surgery centers and underserved emerging economies. Spinal neurosurgery represents a penetrable application segment with substantial upside. A go-to-market angle focusing on flexible, per-procedure acquisition models can attract budget-conscious healthcare providers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core neurosurgical assets. The long-term viability of this market is strong, driven by an aging population and advancements in neuro-oncology. Specialized software developers focusing on real-time navigation and AI integration represent attractive acquisition archetypes. The signal to watch is the approval rate of new AI-integrated devices by regulatory bodies like the US FDA and Europe's EMA.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Driven Imaging Integration | This enhances surgical precision and patient outcomes, differentiating advanced systems in neuro-oncology centers. |
| Develop Compact Handheld Devices | These devices expand market access to ambulatory surgery centers and cost-sensitive healthcare environments. |
| Form Strategic Partnerships with Robotics Firms | Such collaborations combine ultrasonic aspiration with robotic stability, enabling more complex procedures. |
| Pursue Targeted Acquisitions of Transducer Innovators | This secures critical component supply and accelerates technological advancements for core device performance. |
| Expand into Spinal Neurosurgery Applications | This unlocks a less-penetrated growth vector, diversifying revenue streams beyond cranial procedures. |
Research Approach
The analysis maps neurology ultrasonic aspirator sub-sectors, including product types, technologies, applications, and end-users, each validated through extensive primary interviews with neurosurgeons, hospital procurement specialists, medical device engineers, and regulatory experts. Secondary validation draws from medical journals, FDA filings, EMA guidelines, and company annual reports, ensuring comprehensive data coverage. This approach utilizes both bottom-up market sizing and top-down validation to ensure accuracy.
Assumptions regarding global healthcare expenditure trends and neurosurgical procedural growth were held fixed across the analysis window, while variations in regional regulatory frameworks and technological adoption rates were modeled. The segmentation dimensions modeled include product type, technology, application, end-user, and geographic region. Compound Annual Growth Rates (CAGRs) were derived through a rigorous analysis of historical market data and projected demand drivers, accounting for market specificities. Key forecast inputs include brain tumor incidence rates and healthcare infrastructure investment levels.
Sensitivities concentrate around shifts in regulatory approvals for new device technologies and the pace of healthcare infrastructure development in emerging economies. Forecasts reflect assumptions based on current market dynamics and expected technological trajectories. Material shifts in major regulatory frameworks or the adoption rate of robotic surgical platforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Medical Devices Market
Medical Devices
Morcellators Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Spectacle Lens Market
Medical Devices
Knee Walkers Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Bathroom and Toilet Assist Devices Market