
 Skin Cancer Drugs Market | 2026-2036
Skin Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Cancer Drugs Market Insights
The gap between premium biologic therapies and conventional chemotherapy is broadening as payers tighten access controls on high-cost immunotherapies while generic pressure erodes older cytotoxic margins. Bristol-Myers Squibb Company leverages its PD-1 franchise to sustain leadership in checkpoint inhibition. Merck & Co., Inc. anchors the melanoma segment with pembrolizumab-based protocols across major oncology centers. Novartis AG differentiates through targeted BRAF/MEK combination platforms that occupy a distinct niche in BRAF-mutant disease.
Skin cancer drugs comprise pharmaceutical agents designed to inhibit, destroy, or modulate immune responses against malignant keratinocyte and melanocyte proliferation, spanning monoclonal antibodies, kinase inhibitors, alkylating agents, and cytokine therapies administered via intravenous infusion, subcutaneous injection, oral tablet, or topical formulation. These agents function to extend progression-free survival, achieve complete response, or render unresectable lesions amenable to surgical intervention in clinical and ambulatory settings. Immunotherapy now leads clinical preference for advanced melanoma as anti-PD-1 and anti-CTLA-4 classes capture the fastest-growing share of new prescriptions. Targeted therapy retains concentrated margin pools in BRAF-mutant populations where combination BRAF/MEK inhibition commands premium positioning against standard of care.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines and shape payer negotiations for novel skin cancer agents entering the U.S. and European markets. The EPA and OSHA frameworks govern manufacturing facility standards for cytotoxic drug production, directly affecting capacity location decisions and compliance costs for suppliers serving North American demand. Stakeholders must monitor evolving HTA body assessments in Germany and France where early access schemes increasingly determine commercial launch sequencing for pipeline assets.
Market Dynamics
Checkpoint inhibitor immunotherapy is compressing development timelines and redrawing competitive boundaries as Bristol-Myers Squibb and Merck & Co. battle for dominance in anti-PD-1 melanoma protocols across major oncology centers.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses Phase II-to-launch timelines for novel skin cancer agents, enabling earlier commercialization of checkpoint inhibitors and targeted kinase combinations.
- Biomarker-Driven Patient Stratification:BRAF mutation testing now guides therapy selection in melanoma centers, expanding addressable populations for combination BRAF/MEK inhibition protocols.
- Japan's Reimbursement Framework:Japan's Ministry of Health, Labour and Welfare maintains favorable pricing for novel oncology biologics, accelerating adoption of immunotherapy in Tokyo and Osaka cancer institutes.
Market Restraints
- Platinum-Based API Supply Concentration:Cytotoxic manufacturing depends on concentrated platinum refining capacity in South Africa and Russia, exposing carboplatin and cisplatin production to geopolitical supply shocks.
- EMA HTA Divergence:France's Haute Autorité de Santé applies stricter cost-effectiveness thresholds than Germany's IQWiG, fragmenting pricing power and delaying launches in Paris versus Berlin.
- Topical Generic Erosion:Imiquimod and 5-fluorouracil face accelerating commoditization as Indian and Chinese manufacturers flood European and North American markets with low-cost alternatives.
Strategic Opportunities
- Neoadjuvant Immunotherapy Expansion:Anti-PD-1 protocols in resectable Stage III melanoma represent underpenetrated demand, with Memorial Sloan Kettering and MD Anderson piloting pre-surgical combination regimens.
- AI-Enabled Dermatology Screening:Machine learning diagnostic tools in primary care settings are identifying high-risk lesions earlier, expanding referral volumes to academic medical centers for systemic therapy evaluation.
- EU Early Access Schemes:France's ATU and Germany's AMNOG early benefit assessment create regulatory tailwinds for pipeline assets targeting rare skin cancer subtypes with unmet need.
Industry Challenges
- Immuno-Oncology Talent Scarcity:Clinical trial design for combination checkpoint protocols requires specialized biostatisticians and translational medicine expertise concentrated at MD Anderson, Dana-Farber, and Memorial Sloan Kettering.
- Cold Chain Complexity:Biologic stability requirements for anti-CTLA-4 and anti-PD-1 antibodies demand validated 2-8°C distribution networks, raising capex intensity for regional distribution hubs serving community oncology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Cancer Drugs Market |
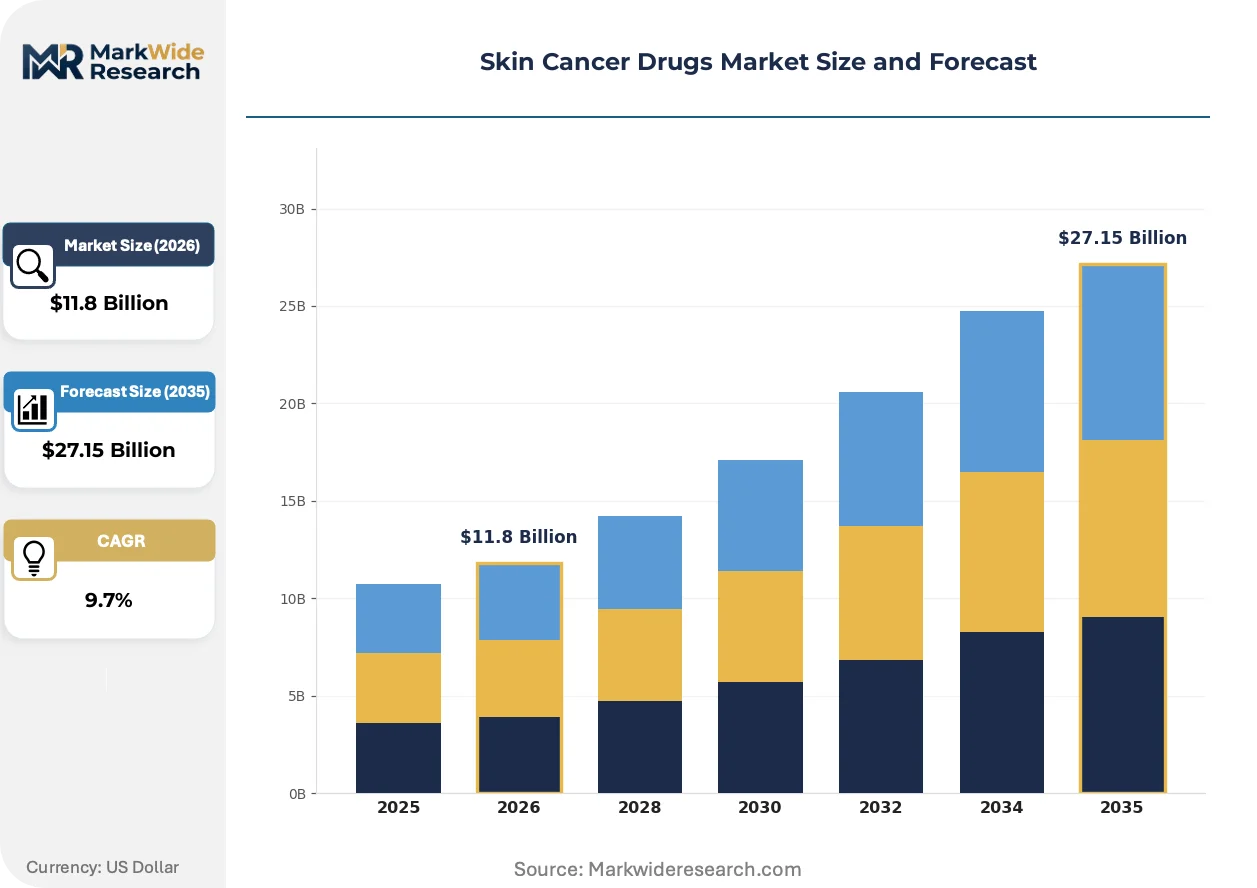
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $27.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy, Targeted Therapy, Immunotherapy End User: Hospitals, Specialty Clinics, Outpatient Facilities, Research Laboratories Administration Route: Intravenous, Subcutaneous, Oral, Topical Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Novartis AG, Bristol-Myers Squibb Company, Amgen Inc., F. Hoffmann-La Roche Ltd, Regeneron Pharmaceuticals Inc., GlaxoSmithKline plc, Iovance Biotherapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Cancer Drugs Market Trends and Innovations
Immunotherapy protocol evolution is fragmenting treatment pathways as academic medical centers pioneer combination regimens ahead of formal label expansion, compressing the window between clinical evidence and community adoption.
Fixed-duration combination immunotherapy is unifying previously sequential treatment paradigms. Anti-PD-1 plus anti-CTLA-4 blockade administered over twelve weeks is displacing indefinite monotherapy in Stage IV melanoma. Memorial Sloan Kettering and Gustave Roussy are piloting these compressed protocols, enabling treatment-free intervals that reduce cumulative toxicity while preserving durable response rates.
EMA's PRIME eligibility scheme is accelerating conditional marketing authorization for novel skin cancer agents. The pathway compresses scientific advice timelines and enables parallel EMA-payer dialogue, reshaping launch sequencing for pipeline assets. German and French manufacturers are prioritizing PRIME-tracked development programs to secure early European market presence before FDA approval.
Hospital procurement consolidation is reshaping vendor relationships as integrated delivery networks centralize oncology pharmacy formulary decisions. US-based systems like Kaiser Permanente and Intermountain Healthcare are negotiating multi-year immunotherapy contracts directly with manufacturers, displacing traditional distributor-mediated purchasing. This concentration is most visible in California and Utah, where single-contract coverage decisions affect thousands of melanoma patients annually.
Skin Cancer Drugs Market Segmentation
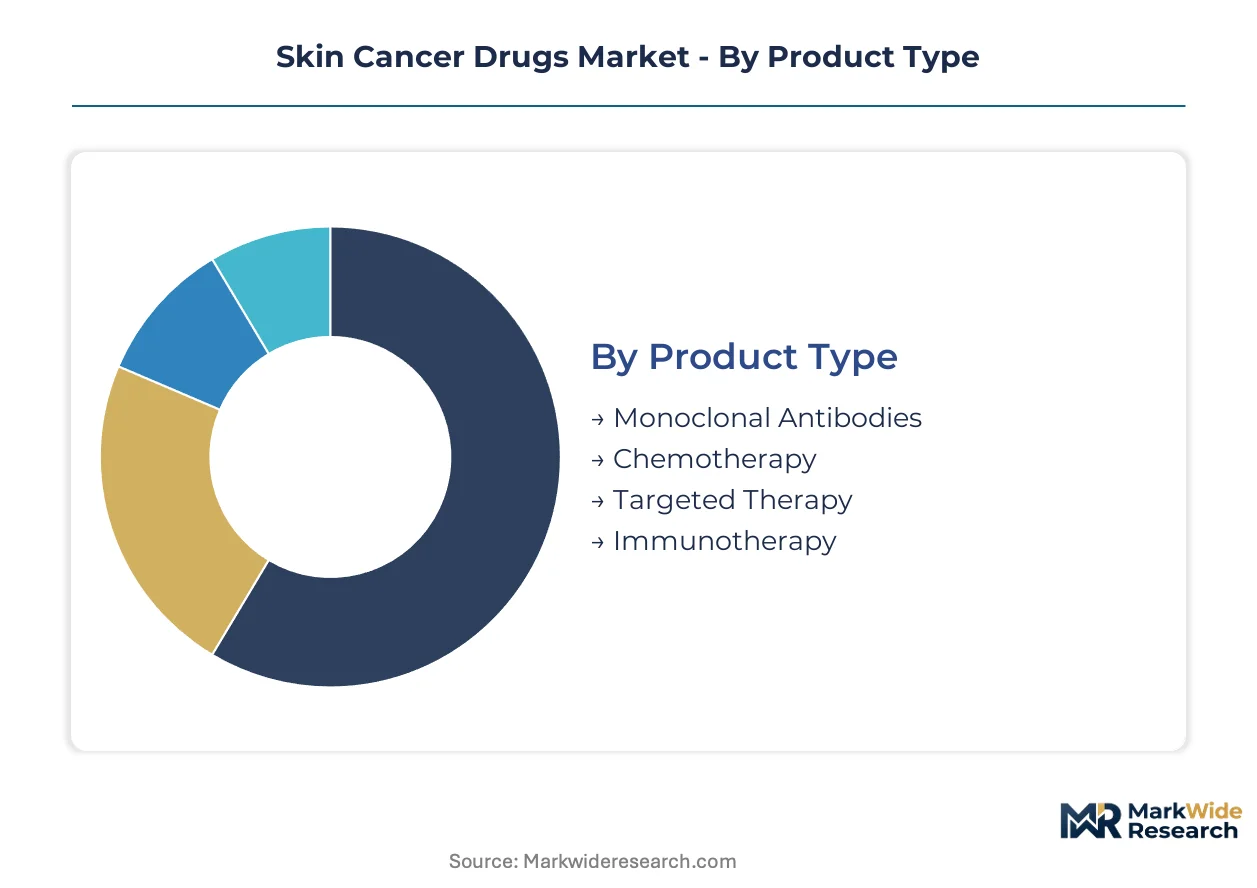
Skin cancer drug segmentation reveals divergent margin profiles across therapeutic modalities and care settings. Therapy selection hinges on mutational status, disease stage, and reimbursement access, fragmenting commercial pathways across intravenous biologics and oral small molecules.
Product Type:
Monoclonal antibodies command premium pricing against commoditized cytotoxic agents, with volume concentration shifting toward checkpoint inhibitors.
- Monoclonal Antibodies:Engineered immunoglobulins targeting PD-1, PD-L1, or CTLA-4 checkpoints deliver durable responses in metastatic melanoma. Demand clusters at Memorial Sloan Kettering, MD Anderson, and Dana-Farber where academic protocols drive adoption ahead of label expansion.
- Targeted Therapy:Oral BRAF and MEK kinase inhibitors occupy a defined niche in BRAF-mutant disease. Novartis AG and Roche Holding AG dominate combination prescribing in German melanoma centers where biomarker testing rates exceed North American benchmarks.
- Immunotherapy:Checkpoint inhibitor class extending beyond anti-PD-1 into novel co-stimulatory targets. Japanese oncology institutes in Tokyo and Osaka pilot IL-2 variant protocols under PMDA accelerated review frameworks.
- Chemotherapy:Platinum-based alkylating agents and taxanes retain utility in rare non-melanoma subtypes and salvage settings. Indian and Chinese API suppliers exert pricing pressure on carboplatin and cisplatin formulations.
Mature deployment sits with Chemotherapy. Newer deployment is concentrated in Monoclonal Antibodies.
End User:
Care setting determines protocol complexity and reimbursement capture, with integrated delivery networks centralizing high-cost immunotherapy administration.
- Hospitals:Academic medical centers and community hospital systems administer intravenous biologics under Medicare Part B buy-and-bill arrangements. Kaiser Permanente and Intermountain Healthcare negotiate direct manufacturer contracts, bypassing traditional wholesale distribution.
- Specialty Clinics:Dedicated dermatologic oncology practices in Florida and Arizona manage high patient volumes with focused infusion capacity. These sites optimize throughput for anti-PD-1 maintenance regimens.
- Outpatient Facilities:Ambulatory infusion centers attached to hospital systems capture shifting site-of-care economics. United States reimbursement differentials between hospital outpatient and freestanding settings reshape patient routing decisions.
- Research Laboratories:Clinical trial sites at Gustave Roussy and University of Texas Southwestern generate real-world evidence for regulatory submission. Early-phase units command premium investigator fees from sponsors pursuing breakthrough therapy designation.
Volume concentration sits with Hospitals. Margin expansion is concentrated in Specialty Clinics.
Administration Route:
Route selection governs cold chain requirements, patient compliance, and prescriber training intensity across the therapeutic spectrum.
- Intravenous:Infusion-dependent biologics require validated 2-8°C distribution networks and oncology nursing infrastructure. Memorial Sloan Kettering and MD Anderson maintain dedicated infusion pharmacy capacity for combination checkpoint protocols.
- Oral:Small molecule kinase inhibitors enable patient-managed dosing with periodic monitoring. BRAF/MEK combinations from Novartis AG and Roche Holding AG dominate this route in German and French outpatient settings.
- Subcutaneous:Emerging delivery format for select immunotherapy agents reducing infusion chair time. Japanese regulators at PMDA evaluate subcutaneous anti-PD-1 variants for outpatient self-administration potential.
- Topical:Imiquimod and 5-fluorouracil formulations for superficial basal cell and actinic keratosis. Indian and Chinese generic manufacturers compress pricing in European retail pharmacy channels.
Established volume sits with Intravenous. Steepest expansion trajectory is concentrated in Subcutaneous.
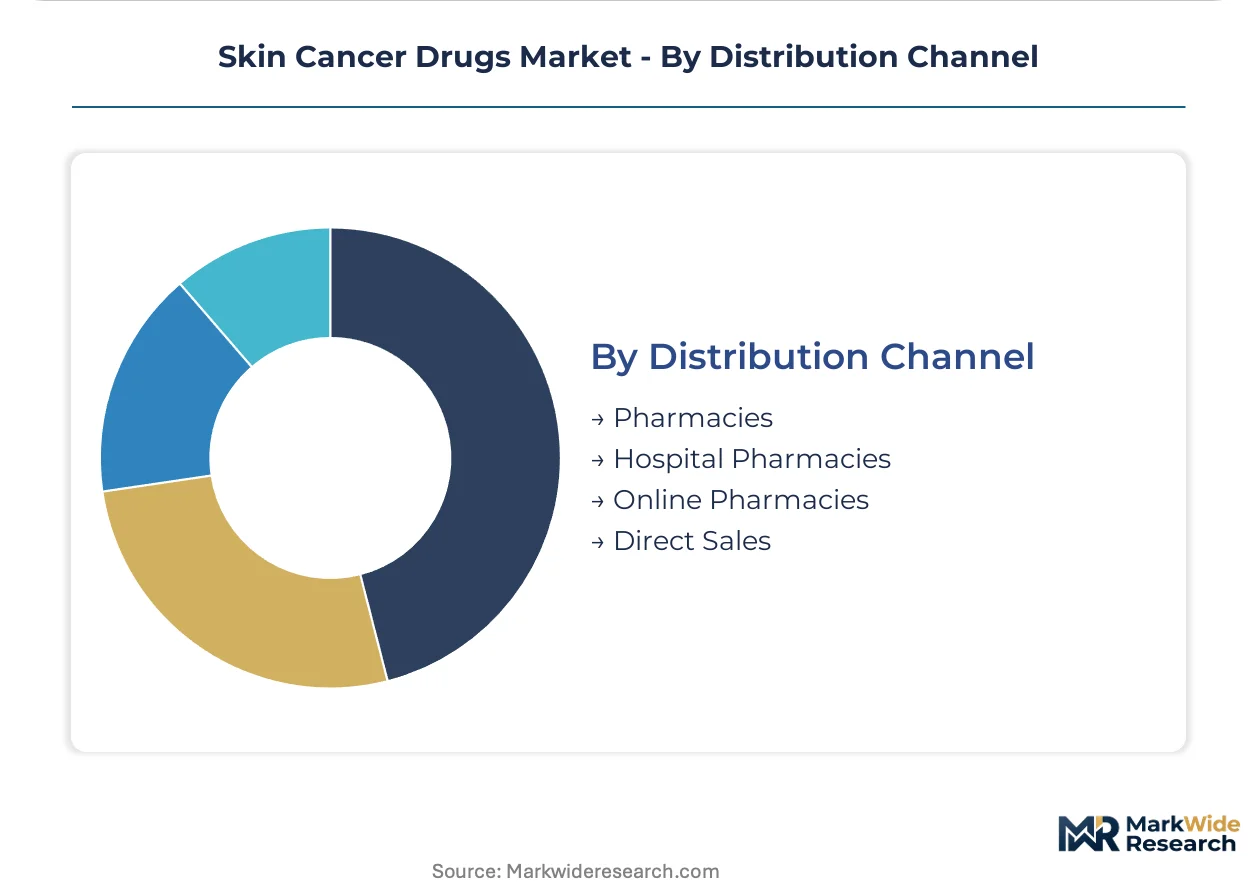
Distribution Channel:
Channel selection reflects therapy cost tier, cold chain sensitivity, and payer prior authorization complexity.
- Hospital Pharmacies:Captures buy-and-bill oncology biologics under Medicare and commercial risk contracts. Integrated delivery networks in California and Utah centralize formulary decisions affecting thousands of melanoma patients.
- Pharmacies:Retail and specialty pharmacy channels dispense oral targeted therapies and supportive care agents. CVS Health and Walgreens Boots Alliance maintain limited distribution networks for high-cost oral oncolytics.
- Direct Sales:Manufacturer-to-provider contracting for institutional accounts with committed volume thresholds. Bristol-Myers Squibb and Merck deploy dedicated account teams to major oncology centers.
- Online Pharmacies:Emerging channel for oral generic chemotherapies and supportive care medications. Regulatory scrutiny from FDA and state boards of pharmacy limits expansion in controlled substance categories.
Revenue concentration sits with Hospital Pharmacies. Channel experimentation is concentrated in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors melanoma clinical research density, with Dana-Farber Cancer Institute and Massachusetts General Hospital generating protocol adoption that diffuses to community oncology networks nationwide.
United States
Medicare Part B buy-and-bill arrangements sustain infusion center economics for checkpoint inhibitors. FDA breakthrough therapy designation compresses Phase II-to-commercial timelines, accelerating pembrolizumab and nivolumab access. Memorial Sloan Kettering and MD Anderson in Houston pilot neoadjuvant combination regimens that reshape community standards.
Germany
IQWiG early benefit assessments under AMNOG framework determine pricing corridors for novel biologics entering statutory health insurance. EMA centralized procedures enable simultaneous market access across federal states. Heidelberg and Essen university hospitals maintain Europe's highest BRAF mutation testing rates, directing targeted therapy prescribing.
Japan
PMDA accelerated review pathways for oncology drugs compress regulatory lag versus Western markets. Ministry of Health, Labour and Welfare pricing methodology preserves premium reimbursement for immunotherapy biologics. Tokyo Cancer Institute and Osaka National Hospital anchor melanoma protocol development for Asia-Pacific diffusion.
United Kingdom
NICE technology appraisals gate NHS England access to high-cost immunotherapies, creating distinct commercial sequencing versus continental Europe. Cancer Drugs Fund provides managed access arrangements for pipeline assets pending final cost-effectiveness verdicts. Royal Marsden NHS Foundation Trust in London generates real-world evidence that influences NICE deliberations.
France
Haute Autorité de Santé applies stricter cost-effectiveness thresholds than neighboring Germany, fragmenting pricing power across the Rhine. ANSM operates ATU early access schemes for unmet need indications in rare skin cancer subtypes. Gustave Roussy in Villejuif leads European adoption of fixed-duration combination immunotherapy protocols.
Skin Cancer Drugs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across therapy modality, with checkpoint inhibitor developers commanding pricing power against generic cytotoxic manufacturers facing API cost compression. The vendor base concentrates among integrated pharmaceutical conglomerates with oncology franchises, while biotech specialists occupy targeted therapy niches. Three archetypes dominate: PD-1 franchise holders, BRAF/MEK combination specialists, and cell therapy developers. Competitive moves center on direct-to-provider contracting and biomarker companion diagnostic alliances.
Within the checkpoint inhibition tier, Bristol-Myers Squibb Company and Merck & Co., Inc. anchor anti-PD-1 melanoma positioning through academic medical center relationships. Novartis AG occupies the targeted therapy vector with BRAF/MEK combination platforms. These three exemplify divergent margin architectures: biologic infusion dependence versus oral small molecule convenience.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Regeneron Pharmaceuticals Inc. |
| GlaxoSmithKline plc |
| Iovance Biotherapeutics Inc. |
| Others |
Pricing and Supply Chain Analysis
Oncology biostatisticians and translational medicine specialists concentrated at Memorial Sloan Kettering, Dana-Farber, and MD Anderson command premium compensation that feeds directly into clinical trial cost structures, widening spreads between premium immunotherapy protocols and commoditized cytotoxic regimens.
Pricing Analysis
Value-based pricing anchored to progression-free survival endpoints governs checkpoint inhibitor contracting, with Bristol-Myers Squibb and Merck negotiating outcomes-based arrangements with Kaiser Permanente and Intermountain Healthcare. Price differentiation separates FDA breakthrough-designated biologics from EMA PRIME-tracked competitors based on label breadth and companion diagnostic bundling. Pricing pressure stems from IQWiG cost-effectiveness thresholds in Germany that compress reimbursement corridors for novel agents. Community oncology practices exhibit highest price sensitivity due to Medicare Part B margin compression, while academic medical centers maintain lowest sensitivity given research funding offsets.
Supply Chain Analysis
Reverse-logistics networks for temperature-compromised biologics remain underdeveloped, forcing destruction of anti-PD-1 and anti-CTLA-4 batches exposed to cold chain excursions rather than refurbishment. Active pharmaceutical ingredient production for platinum-based alkylating agents concentrates in South Africa and Russia, drawing from concentrated platinum refining capacity. Supply chain risk centers on single-source vulnerability for carboplatin and cisplatin precursors given geopolitical exposure. Distribution runs through validated 2-8°C regional hubs serving hospital pharmacies and specialty infusion centers, with direct manufacturer-to-provider contracting displacing wholesale intermediation for high-volume institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
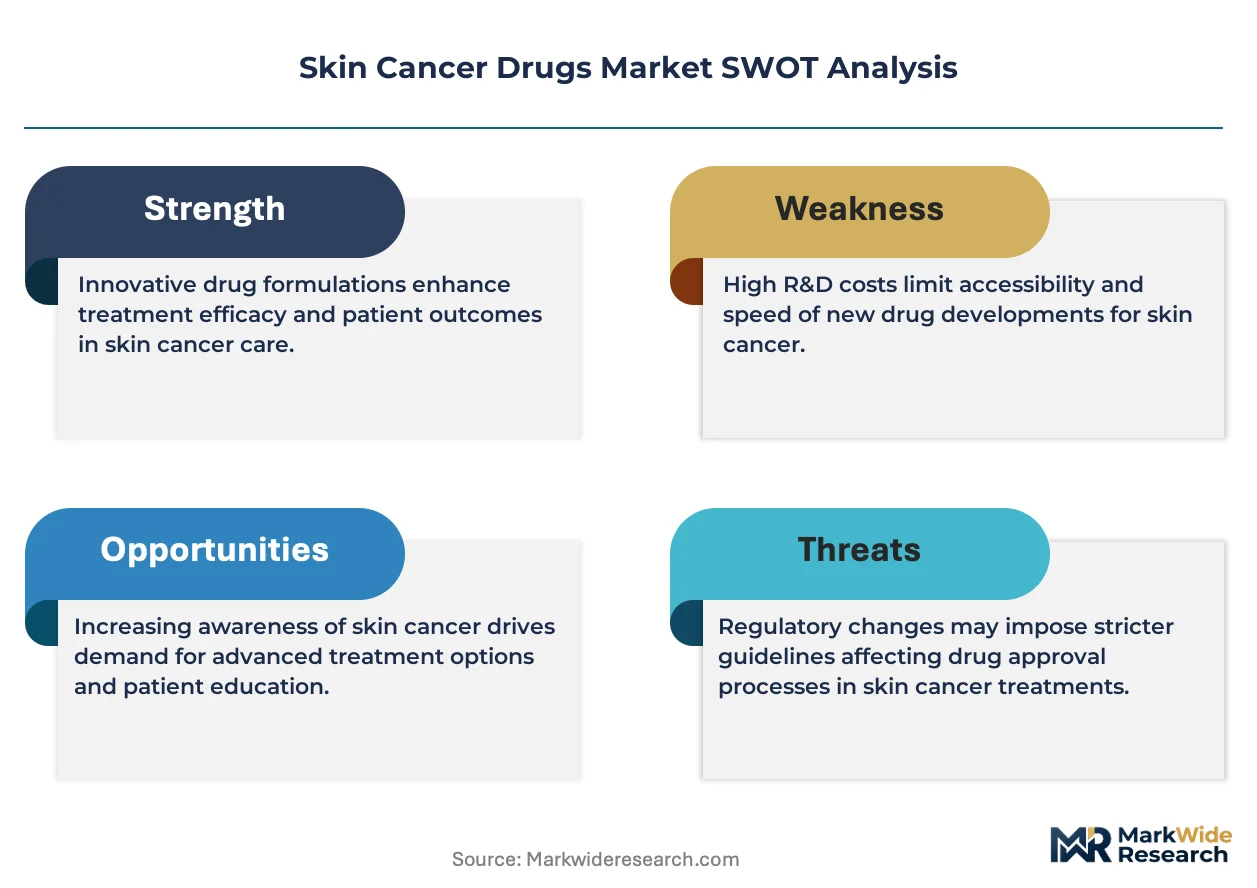
Vertical integration into companion diagnostic development and biomarker testing infrastructure is emerging as the decisive competitive lever, with players racing to capture patient stratification data that locks in protocol selection ahead of formulary decisions.
For Market Incumbents: Anticipate biosimilar entry into anti-PD-1 maintenance regimens by securing exclusive real-world evidence generation contracts with Memorial Sloan Kettering and MD Anderson. Deepen backward integration into cold chain distribution infrastructure to defend margin position against site-of-care shifts toward ambulatory infusion centers. Counter emerging subcutaneous formulation developers by accelerating fixed-duration combination protocol adoption through academic medical center relationships. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for neoadjuvant Stage III melanoma indications currently underpenetrated by established checkpoint inhibitors. Target specialty clinics in Florida and Arizona with streamlined prior authorization support and rapid infusion scheduling to capture patient volumes from hospital outpatient departments. Pursue Japanese PMDA accelerated review pathways for IL-2 variant protocols given favorable Ministry of Health, Labour and Welfare pricing methodology. For Investors and Strategic Acquirers: Re-rating potential sits with cell therapy developers possessing autologous tumor-infiltrating lymphocyte manufacturing capabilities given Iovance Biotherapeutics' regulatory validation of the modality. Long-term viability hinges on securing durable response data in metastatic melanoma that supports premium pricing against combination checkpoint protocols. Monitor EMA HTA divergence between France's Haute Autorité de Santé and Germany's IQWiG as early indicator of European pricing power compression for pipeline assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Neoadjuvant immunotherapy protocols at Memorial Sloan Kettering reshape community oncology standards ahead of label expansion. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses scientific advice timelines and enables parallel payer dialogue for European market entry. |
| Manufacturing Scale-Up | Cold chain capacity expansion addresses biologic stability requirements for anti-CTLA-4 and anti-PD-1 antibody distribution. |
| Pipeline Diversification | BRAF/MEK combination platforms from Novartis and Roche occupy distinct mutation-positive niches resistant to immunotherapy displacement. |
| Reimbursement Strategy | Medicare Part B buy-and-bill arrangements sustain infusion center economics for checkpoint inhibitors in community settings. |
Research Methodology
Multi-period observation of FDA approval timelines, EMA HTA assessments, and formulary adoption rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation converged on segment-level estimates across therapeutic modalities and administration routes.
Segment-weighting approaches applied differential growth assumptions to checkpoint inhibitors, targeted kinase combinations, and cytotoxic agents based on biomarker penetration rates and reimbursement access evolution across the analysis window. Treatment line, administration route, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from fitted growth curves incorporating patient incidence projections, protocol duration assumptions, and pricing trajectory scenarios specific to immunotherapy and targeted therapy modalities.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous immunotherapy administration or AI-enabled diagnostic referral would alter the outlook for infusion center volume concentration. Forecasts reflect assumptions regarding FDA breakthrough therapy designation velocity and EMA HTA convergence patterns. Practitioners should monitor PMDA review timeline compression and Japan's reimbursement methodology adjustments for early signals of Asia-Pacific pricing paradigm shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Oral Vaccines Market