
 Organ Transport Devices Market | 2026-2036
Organ Transport Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Transport Devices Market Analytics
Normothermic perfusion standards are redrawing competitive boundaries in organ transport. TransMedics leverages its integrated organ care platform to dominate heart and lung transport segments. Paragonix Technologies anchors its position through specialized hypothermic preservation devices with real-time monitoring capabilities. XVIVO Perfusion AB differentiates via extended clinical validation of its ex-vivo perfusion protocols across European transplant networks.
Organ transport devices comprise engineered containment and perfusion systems designed to maintain viable metabolic conditions for excised organs during transit, typically employing temperature regulation between 4°C and 37°C with active oxygenation and nutrient delivery. Their primary purpose centers on extending preservation duration while reducing ischemia-reperfusion injury prior to transplantation. Dynamic preservation devices command premium positioning as normothermic machine perfusion technology demonstrates superior graft survival metrics versus static cold storage. Hypothermic machine perfusion retains substantial volume in kidney transplantation, where cost-effectiveness and established clinical workflows sustain deployment. Electronic temperature controllers represent a concentrated margin pool, given their integration across multiple device platforms and recurring calibration service revenue.
The FDA enforces stringent biocompatibility and sterility standards under 21 CFR requirements for devices contacting human organs, while the European Medicines Agency coordinates with notified bodies under the Medical Device Regulation for CE-marked transport systems. ISO 14155 governs clinical investigation protocols, directly shaping product validation timelines and market entry pathways. Stakeholders must monitor evolving CMS reimbursement determinations for machine perfusion procedures, as coverage expansion would fundamentally alter procurement economics for transplant centers and organ procurement organizations weighing capital investments against per-procedure costs.
Market Dynamics
The transition from static cold storage to active machine perfusion is compressing procurement cycles at transplant centers, forcing rapid capital redeployment toward integrated preservation platforms that extend viable ischemia windows.
Growth Catalysts
- FDA 21 CFR biocompatibility mandates:Stringent sterility requirements for devices contacting human organs are accelerating hospital upgrades of legacy transport containers toward certified next-generation systems.
- Normothermic perfusion protocols:Clinical validation of warm oxygenated preservation is expanding addressable transplant volumes by enabling procurement from extended-criteria donors previously deemed non-viable.
- United States OPTN allocation optimization:The national organ matching system's efficiency pressures are driving investment in cold-chain logistics infrastructure to minimize cold ischemia time across donor-recipient pairs.
Market Restraints
- Capital intensity of perfusion platforms:Single-use disposable circuits and specialized cannula sets impose per-procedure costs that strain organ procurement organization budgets relative to static storage.
- Supply concentration in electronic temperature controllers:Precision calibration services and proprietary sensor modules create vendor lock-in, limiting transplant center negotiating leverage.
- Technical limitation in multi-organ portability:Current device footprints and power requirements restrict simultaneous heart-lung-liver transport, forcing sequential procurement logistics.
Strategic Opportunities
- Underpenetrated European transplant networks:EMA-coordinated CE-marking harmonization under Medical Device Regulation is streamlining cross-border device deployment across national procurement organizations.
- Regulatory tailwind from CMS reimbursement expansion:Pending coverage determinations for machine perfusion procedures would fundamentally alter procurement economics for hospital capital planning.
- Technology convergence of biosensors and cloud telemetry:Real-time graft metabolic monitoring combined with predictive analytics platforms is enabling remote surgeon consultation during transport.
Industry Challenges
- Perfusionist training pipeline constraints:Specialized expertise in ex-vivo organ management remains concentrated at major academic medical centers, limiting deployment scalability.
- ISO 14155 clinical investigation timelines:Extended validation protocols for novel preservation devices delay market entry and compress competitive windows for first-mover advantages.
- Integration complexity with existing donor management software:Proprietary data formats from transport devices create interoperability friction with UNOS allocation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Transport Devices Market |
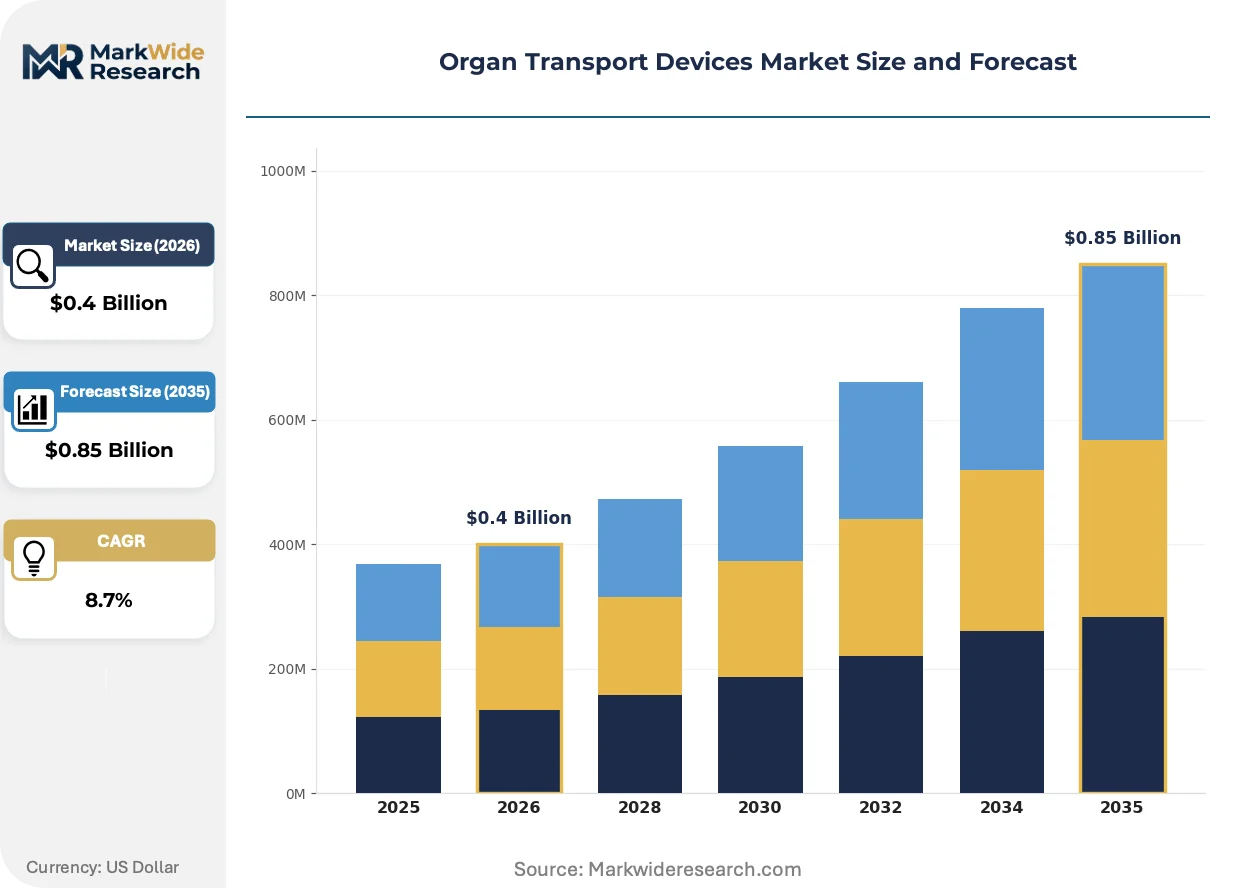
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $0.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Preservation Devices, Dynamic Preservation Devices, Refrigeration Systems, Transport Boxes Technology: Hypothermic Machine Perfusion, Normothermic Machine Perfusion, Electronic Temperature Controllers, Biochemical Sensors End User: Hospitals, Organ Procurement Organizations, Research Institutions, Transplant Centers Application: Heart Transplantation, Liver Transplantation, Kidney Transplantation, Lung Transplantation |
| Companies Covered | TransMedics, XVIVO Perfusion AB, Paragonix Technologies, OrganOx, Bridge to Life, Medtronic, Organ Recovery Systems, Terumo Corporation, Dr. Franz Köhler Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Transport Devices Market Evolving Landscape
Active preservation technology is migrating from centralized transplant hubs toward distributed procurement networks, compressing the geographic radius within which viable organs can be matched to recipients.
Portable normothermic perfusion circuits are miniaturizing. These battery-powered systems maintain physiologic temperature and oxygenation without stationary infrastructure. Organ procurement organizations in high-traffic corridors are piloting helicopter-compatible units. This technology is miniaturizing the physical footprint required for warm perfusion, enabling point-of-procurement organ assessment rather than transport to assessment centers.
EMA's Medical Device Regulation enforcement is tightening post-market surveillance for CE-marked transport systems. Notified bodies now mandate real-world performance data collection across European transplant networks. Kidney preservation device manufacturers face accelerated clinical follow-up obligations, prompting investment in automated outcome registry integration.
Hospital purchasing committees are unbundling device procurement from disposable supply agreements. Transplant centers now negotiate hardware acquisition and per-procedure consumables through separate vendor relationships. This shift is most visible in United States academic medical centers seeking to optimize total cost of ownership across competing perfusion platforms.
Organ Transport Devices Market Segmentation
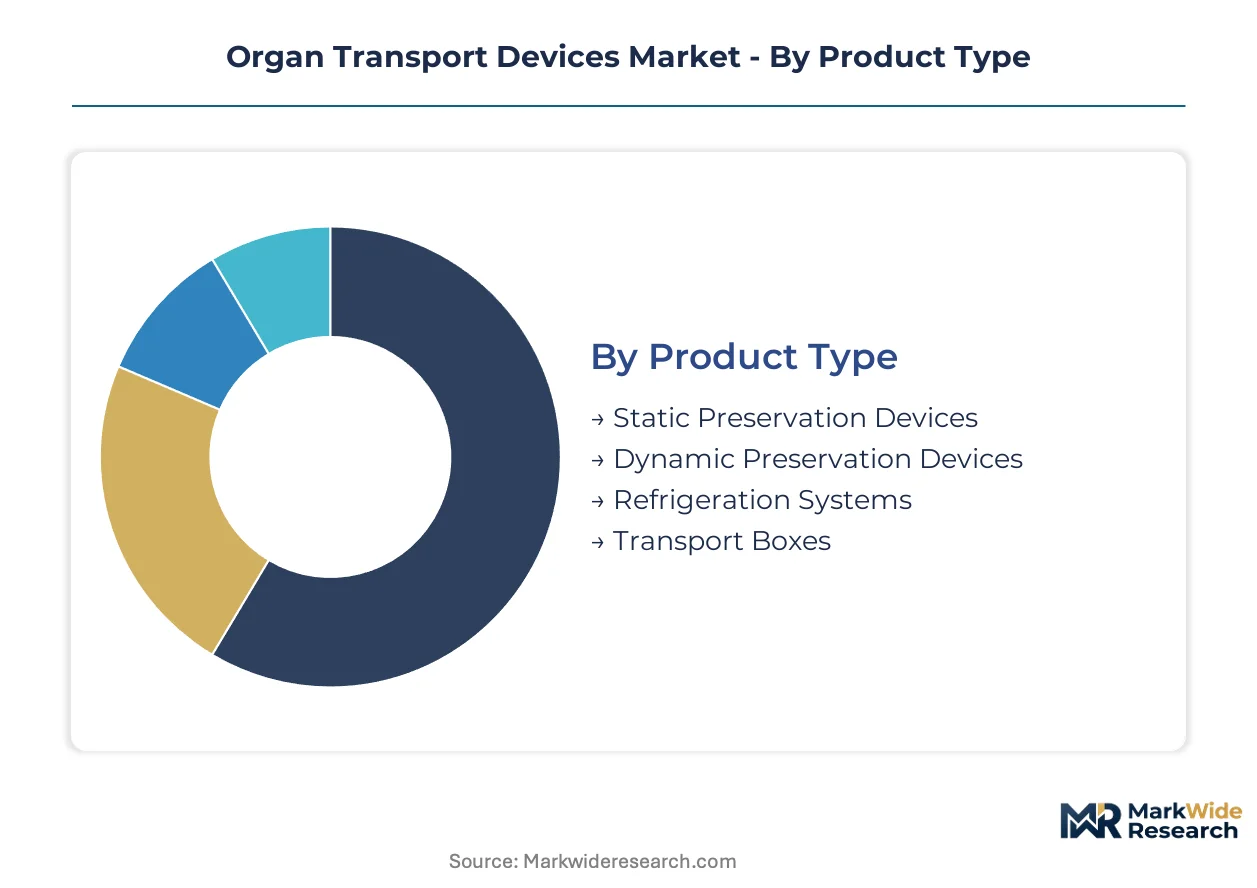
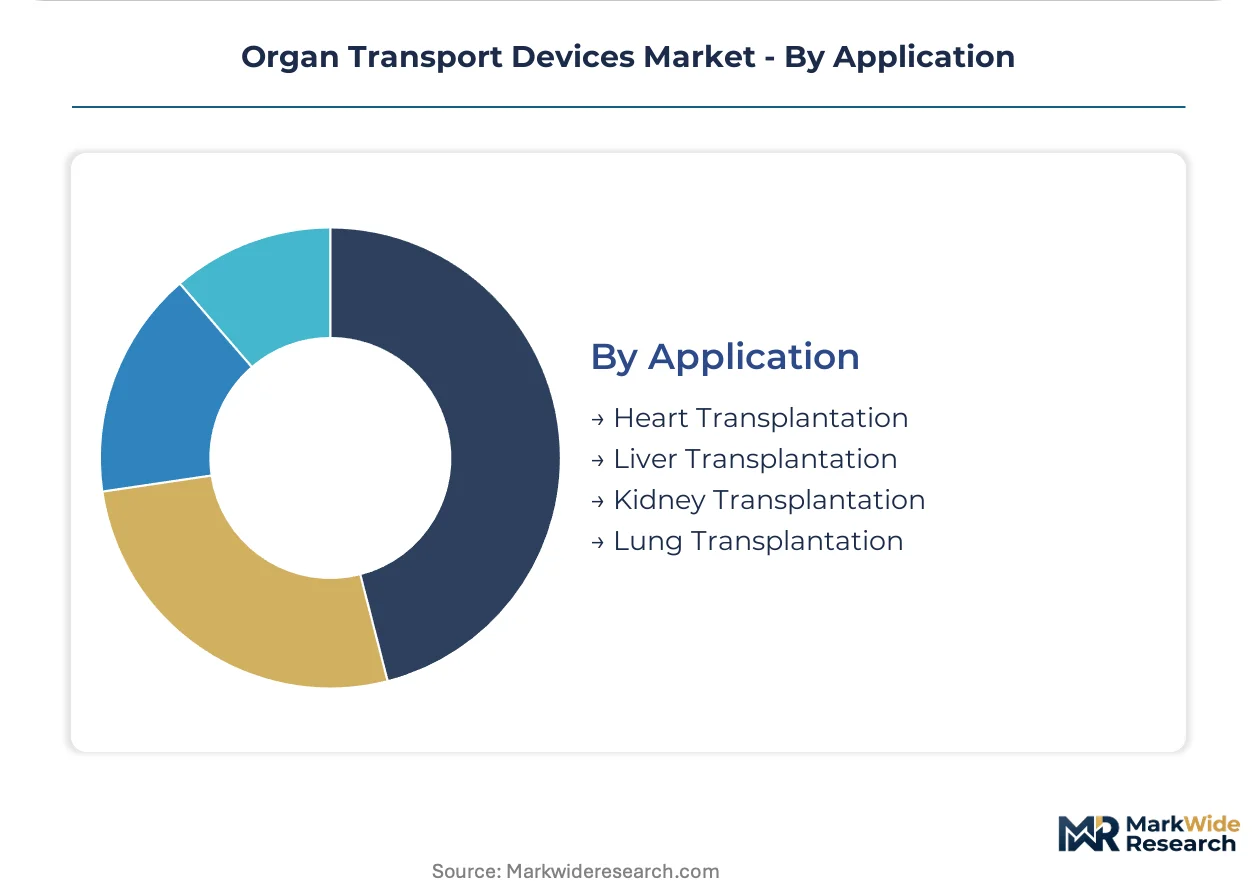
Segmentation in organ transport devices maps directly to procurement authority and reimbursement pathways. Product type determines capital allocation cycles, while technology choices lock transplant centers into specific regulatory compliance frameworks.
Product Type:
FDA 21 CFR biocompatibility requirements apply differentially across device categories, with dynamic systems facing sterility validation that static containers avoid.
- Static Preservation Devices:Passive cooling containers maintain 4°C through ice-based or phase-change materials without active power. Demand concentrates in organ procurement organization ground transport fleets where cost-per-procedure constraints dominate procurement decisions.
- Dynamic Preservation Devices:Active perfusion systems integrate pumps, oxygenators, and temperature regulation to maintain physiologic metabolic states. Transplant centers in the United States anchor demand as OPTN pressure to extend preservation windows drives capital redeployment toward integrated platforms.
- Refrigeration Systems:Compressor-based cooling units designed for multi-organ storage during extended logistics chains.
- Transport Boxes:Insulated containment vessels with integrated monitoring for temperature excursion alerts.
Dynamic preservation devices handle the majority of throughput; static preservation devices are expanding most quickly in emerging procurement networks.
Technology:
Cost tiering separates premium normothermic platforms from established hypothermic workflows, with electronic controllers capturing recurring service revenue across both categories.
- Hypothermic Machine Perfusion:Cold oxygenated perfusion at 4-10°C reduces metabolic demand while maintaining microcirculatory patency. Kidney transplantation programs in the United States sustain volume leadership given established clinical protocols and favorable CMS reimbursement positioning.
- Normothermic Machine Perfusion:Warm perfusion at physiologic temperature with active oxygenation and nutrient delivery. Heart and lung transplant centers drive demand acceleration as graft survival metrics justify premium per-procedure costs against static storage benchmarks.
- Electronic Temperature Controllers:Precision sensor modules with calibration-dependent accuracy specifications.
- Biochemical Sensors:Real-time lactate, pH, and oxygen tension monitoring for graft metabolic assessment.
Hypothermic machine perfusion handles the majority of throughput; normothermic machine perfusion is gaining share fastest in thoracic organ segments.
End User:
Customer type determines purchasing committee composition and capital availability, with hospitals and transplant centers operating under distinct budget authorities.
- Hospitals:General acute care facilities with emergency departments serving as initial recipient sites for organ offers.
- Organ Procurement Organizations:Federally designated entities coordinating donor identification, family consent, and organ recovery logistics. United States OPOs anchor procurement volume as UNOS contract requirements mandate specific device certification tiers.
- Research Institutions:Academic medical centers and university laboratories conducting ex-vivo organ perfusion studies.
- Transplant Centers:Specialized surgical programs performing implantation procedures with dedicated perfusionist staffing.
Transplant centers handle the majority of throughput; organ procurement organizations are climbing the fastest on capital investment share.
Application:
Organ-specific ischemia tolerance windows dictate device specification requirements, with thoracic organs demanding normothermic solutions that abdominal organs may not require.
- Heart Transplantation:Normothermic perfusion dominates as cold ischemia tolerance restricts viable transport to four hours. United States heart transplant programs anchor demand for portable warm perfusion platforms given geographic dispersion of donor and recipient pools.
- Liver Transplantation:Hypothermic and normothermic systems compete based on donor criteria and transport distance.
- Kidney Transplantation:Hypothermic machine perfusion retains substantial deployment given 24-36 hour cold ischemia tolerance and established cost-effectiveness.
- Lung Transplantation:Ex-vivo lung perfusion systems enable assessment and rehabilitation of marginal donor organs.
Kidney transplantation handles the majority of throughput; heart transplantation shows the steepest expansion trajectory for normothermic platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export intensity in perfusion systems runs highest from German and Swiss manufacturers serving transplant networks across the Middle East and Asia-Pacific. Import dependence concentrates in emerging procurement organizations seeking CE-marked devices ahead of local regulatory maturity. Cross-border organ allocation protocols are synchronizing device certification requirements across national boundaries.
United States
The OPTN allocation system drives capital deployment toward integrated perfusion platforms at major academic transplant centers. FDA 21 CFR biocompatibility mandates are accelerating hospital upgrades of legacy transport containers. The Cleveland Clinic and Mayo Clinic anchor procurement volume for normothermic heart-lung systems.
Germany
EMA-coordinated CE-marking harmonization under Medical Device Regulation is streamlining device deployment across European transplant networks. The country's national pharmaceutical regulator enforces stringent post-market surveillance for transport systems contacting human organs. Berlin and Heidelberg anchor clinical validation studies for extended-criteria donor protocols.
United Kingdom
NHS Blood and Transplant procurement frameworks are standardizing hypothermic machine perfusion for kidney programs nationwide. The Medicines and Healthcare products Regulatory Agency coordinates with notified bodies on transport device sterility validation. Cambridge and Oxford anchor research commercialization partnerships between university laboratories and device manufacturers.
Japan
PMDA regulatory pathways for novel preservation devices are compressing market entry timelines for European and North American manufacturers. The Pharmaceuticals and Medical Devices Agency prioritizes clinical data from domestic transplant networks in approval decisions. Tokyo and Osaka anchor demand concentration as heart transplantation volumes expand under revised brain death criteria.
Australia
TGA registration requirements for organ transport systems are aligning with ISO 14155 clinical investigation standards to accelerate device access. The Therapeutic Goods Administration mandates biocompatibility documentation equivalent to FDA 21 CFR benchmarks. Melbourne and Sydney anchor pilot programs for portable normothermic perfusion in helicopter-based procurement logistics.
Organ Transport Devices Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and geographic reach dimensions. The vendor base stratifies into three tiers: integrated platform developers commanding premium positioning, specialized preservation device manufacturers occupying mid-market niches, and regional distributors capturing service revenue through calibration contracts. Dominant competitive moves include strategic partnerships between device developers and organ procurement organizations, plus portfolio diversification into disposable circuits and cannula sets.
Within the integrated platform tier, TransMedics and Paragonix Technologies occupy positions exemplifying divergent technological approaches—normothermic warm perfusion versus hypothermic preservation with telemetry integration. XVIVO Perfusion AB represents the European specialist archetype, anchoring clinical validation networks across national transplant systems. These three entities collectively illustrate how geographic origin and regulatory pathway choices shape competitive positioning in device markets governed by FDA and EMA coordination.
| Leading Market Players |
|---|
| TransMedics |
| XVIVO Perfusion AB |
| Paragonix Technologies |
| OrganOx |
| Bridge to Life |
| Medtronic |
| Organ Recovery Systems |
| Terumo Corporation |
| Dr. Franz Köhler Chemie GmbH |
| Others |
Value Network & Pricing Analysis
Single-use disposable circuits replacing reusable perfusion components are redrawing procurement economics while shifting manufacturing concentration toward medical device clusters in the United States and Germany. This substitution dynamic compresses per-procedure costs for transplant centers but amplifies dependency on calibrated sensor suppliers with proprietary lock-in.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure combining capital equipment sales with recurring disposable revenue streams. Price differentiation separates FDA-validated platforms from CE-marked alternatives, with after-sales calibration services commanding sustained premiums. Cost compression in mid-tier hypothermic systems is intensifying because organ procurement organizations face budget constraints against normothermic platform upgrades. Academic medical centers exhibit lowest price sensitivity given research funding access, while regional transplant networks remain most cost-conscious.
Supply Chain Analysis
The United States and Germany anchor precision manufacturing for electronic temperature controllers and biocompatible perfusion circuits. Component sourcing draws from Japanese sensor module suppliers and Swiss medical-grade polymer producers. Single-source vulnerability concentrates in proprietary calibration chipsets, creating procurement bottlenecks when transplant centers require rapid replacement. Distribution runs through specialized medical device distributors serving organ procurement organizations and hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as normothermic perfusion protocols penetrate thoracic transplant programs previously limited to static cold storage. FDA reimbursement tailwinds and extended-criteria donor validation are accelerating adoption beyond academic centers into regional networks.
For Market Incumbents: Secure disposable supply agreements with organ procurement organizations to lock in recurring revenue against emerging platform competitors. Invest in backward integration into sensor calibration services to defend margin position from specialized component suppliers. Prioritize FDA 510(k) pathway expansion for multi-organ transport configurations before regulatory windows compress. For New Entrants and Emerging Players: Differentiate on portable normothermic systems compatible with helicopter-based procurement logistics, a segment where device footprints and power requirements remain unresolved. Target European transplant networks under EMA Medical Device Regulation harmonization, where CE-marking streamlines cross-border deployment. Pursue hospital system partnerships for pilot programs demonstrating total cost of ownership against static storage benchmarks. For Investors and Strategic Acquirers: The market sits at a technology-validation phase that favors platforms with demonstrated graft survival metrics and established reimbursement pathways. Long-term viability hinges on CMS coverage expansion for machine perfusion procedures, which would transform procurement economics across transplant center capital planning. Watch FDA quality standard evolution for organ transport containers as the inflection signal for accelerated device replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market entry for novel perfusion platforms under 21 CFR biocompatibility mandates. |
| CE Marking Pathway | Enables cross-border deployment across EMA-coordinated European transplant networks. |
| Hospital System Partnership | Secures pilot program validation for total cost of ownership against static storage alternatives. |
| Software Companion Development | Integrates real-time graft metabolic monitoring with UNOS allocation system interoperability. |
| Reimbursement Strategy | Aligns CMS coverage determinations with machine perfusion procedure economics for transplant centers. |
Research Methodology
Initial hypotheses were tested against primary input from transplant surgeons, organ procurement organization executives, biomedical engineers, and hospital purchasing committee members and refined through secondary validation. Sources included FDA 510(k) filings, EMA Medical Device Regulation submissions, CMS reimbursement determinations, and hospital procurement databases. Bottom-up demand modeling across transplant center capital expenditure cycles was triangulated with top-down market sizing from device manufacturer revenue disclosures.
Variance decomposition across product type, technology tier, end-user category, and organ-specific application segments shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by throughput volumes. Forecast inputs incorporated OPTN allocation efficiency pressures, FDA quality standard evolution timelines, and EMA post-market surveillance obligations for CE-marked transport systems.
Material uncertainties — CMS reimbursement expansion timing, ISO 14155 clinical investigation completion rates, perfusionist training pipeline scaling — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and transplant center capital availability. Recalibration cycles align with material shifts in FDA device quality mandates and EMA harmonization enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Electric Handpiece Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Retinal Implant Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Eye Drop Dispenser Market