
 Focused Ultrasound System Market | 2026-2036
Focused Ultrasound System Market Size, Share, and Industry Trends Forecast 2026-2036
Focused Ultrasound System Market Analysis
High-intensity focused ultrasound certification tiers are rotating toward MR-guided platforms that demand real-time thermometry integration and tissue-specific dosing protocols. Insightec Ltd. dominates the neurology ablation segment with its Exablate system cleared for essential tremor. Profound Medical leverages its TULSA-PRO platform to compete in prostate tissue ablation with robotic precision delivery. EDAP TMS S.A. anchors the urology channel in Europe with established reimbursement for HIFU procedures.
Focused ultrasound systems employ acoustic energy convergence to generate localized thermal or mechanical tissue effects without incision, typically operating at frequencies between 0.5 and 4 MHz with focal intensities exceeding 1000 W/cm² for therapeutic ablation. Therapeutic devices command the largest revenue share as hospitals replace legacy surgical suites with image-guided ablation workstations. Neurology applications represent the fastest-expanding segment, driven by expanding indications beyond essential tremor into Parkinson's disease and neuropathic pain where magnetic resonance imaging guidance enables sub-millimeter targeting accuracy.
FDA breakthrough device designations and the EU Medical Device Regulation reshape clinical evidence requirements for new focused ultrasound indications, extending validation timelines but raising barriers to commoditized entrants. The European Medicines Agency coordinates with notified bodies on post-market surveillance for implanted transducers, while China's National Medical Products Administration accelerates domestic innovation through priority review channels for oncology devices. Stakeholders must monitor reimbursement decisions by Germany's Federal Joint Committee and CMS national coverage determinations, as these gatekeepers determine whether hospital capital budgets shift toward focused ultrasound or preserve conventional surgical robotics.
Market Dynamics
Histotripsy's mechanical tissue destruction mechanism is displacing thermal ablation modalities in oncology, forcing capital planners to choose between upgrading existing MR-guided HIFU suites or awaiting next-generation cavitation-based platforms with expanded indication sets.
Growth Catalysts
- EU MDR breakthrough pathway:CE marking accelerations for histotripsy devices compress clinical validation timelines, enabling faster commercial deployment across German and French university hospitals.
- Neurology indication expansion:Essential tremor approvals are extending into Parkinson's disease and neuropathic pain, broadening addressable patient populations in academic medical centers.
- China NMPA priority review:Domestic oncology device innovation receives regulatory fast-tracking, stimulating hospital procurement of focused ultrasound systems in tier-one cities.
Market Restraints
- Transducer supply concentration:Piezoelectric ceramic sourcing clusters in East Asian manufacturing hubs create vulnerability to export control disruptions.
- Capital intensity barriers:MR-guided platform installation requires dedicated shielded suites costing multiples of conventional surgical robotics, limiting community hospital access.
- FDA evidence thresholds:Breakthrough device designations demand extensive post-market surveillance, extending payback periods for novel indication development.
Strategic Opportunities
- Underpenetrated urology clinics:Prostate tissue ablation remains below saturation in US ambulatory surgical centers, creating whitespace for robotic precision delivery systems.
- Histotripsy-immunotherapy convergence:Mechanical tumor disruption protocols are pairing with checkpoint inhibitors, opening combination therapy protocols in immuno-oncology departments.
- Germany reimbursement expansion:Federal Joint Committee decisions on procedure codes for non-invasive ablation are shifting hospital budget allocation toward focused ultrasound capital equipment.
Industry Challenges
- MR thermometry integration complexity:Real-time temperature mapping requires specialized physicist staffing that academic medical centers struggle to recruit and retain.
- Legacy surgical workflow disruption:Operating room scheduling and sterile processing protocols require reconfiguration to accommodate image-guided ablation workstations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Focused Ultrasound System Market |
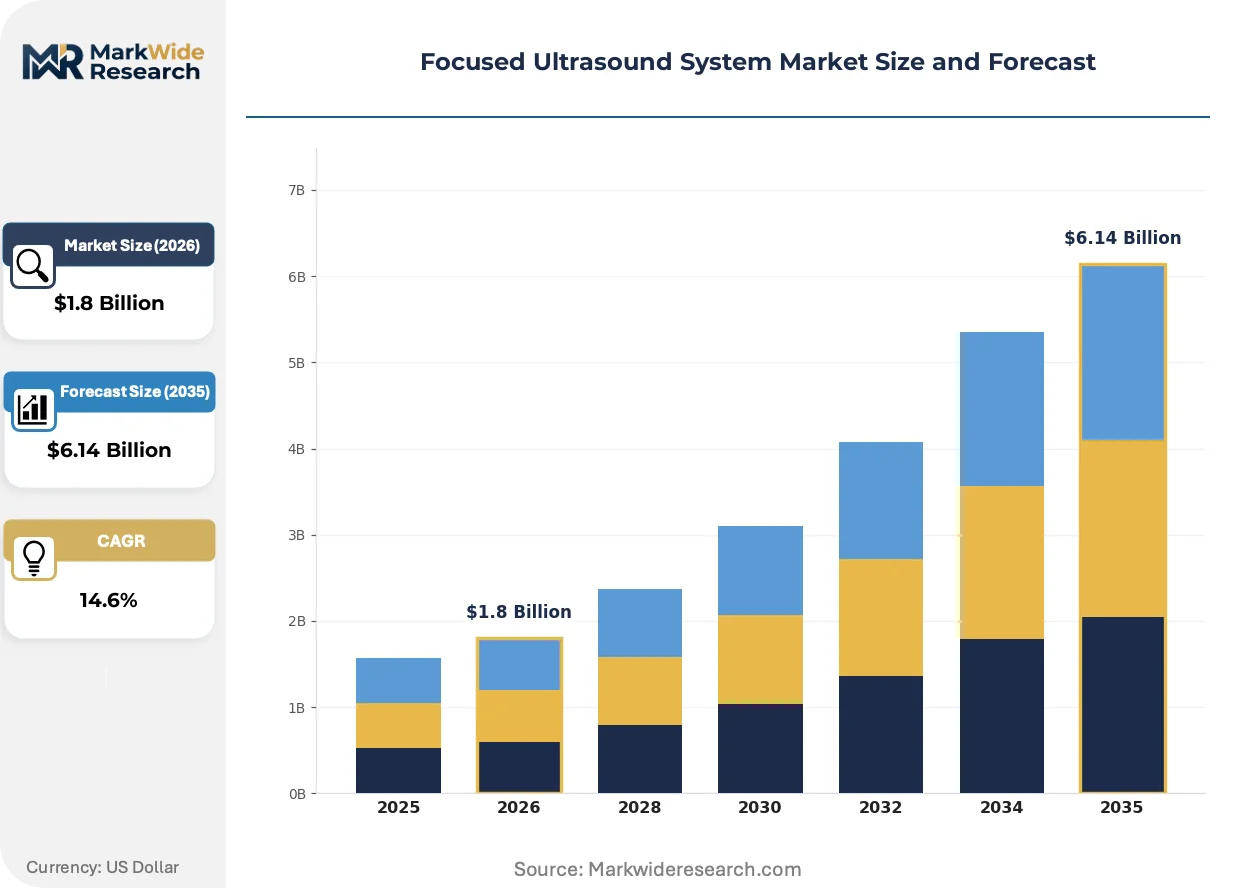
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Devices, Diagnostic Devices, Research Instruments, Imaging Equipment Application: Oncology, Neurology, Cardiology, Pain Management End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Technology: Ultrasound Imaging, Magnetic Resonance Imaging, Electromagnetic Navigation, Software Solutions |
| Companies Covered | Profound Medical, Theraclion S.A., Insightec Ltd., Philips Healthcare, Alpinion Medical Systems, EDAP TMS S.A., SonaCare Medical, GE Healthcare, Chongqing Haifu Medical Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Focused Ultrasound System Market Emerging Trajectories
Acoustic energy delivery mechanisms are fragmenting across thermal, mechanical, and immunomodulatory tissue effect categories, compelling manufacturers to place parallel bets on platform architectures rather than converging on single-modality dominance.
Histotripsy systems employing controlled cavitation for mechanical tissue liquefaction without thermal damage are bifurcating the oncology ablation landscape. Hepatocellular carcinoma treatment protocols at US academic medical centers are adopting these platforms for focal tumor destruction. The technology is bifurcating capital planning decisions between immediate HIFU suite upgrades and deferred procurement awaiting expanded histotripsy indication clearances.
EU MDR post-market surveillance requirements for implanted transducers are extending clinical evidence obligations across the device lifecycle. Notified bodies now coordinate with EMA on longitudinal safety monitoring, elevating documentation burdens. European urology device manufacturers are responding by consolidating regulatory affairs functions and pre-submission engagement strategies.
Hospital procurement committees are unbundling capital acquisition from service contracts, demanding transparent lifecycle cost modeling. Third-party maintenance providers are displacing OEM service monopolies in German and Chinese installed bases. This purchasing pattern shift concentrates in markets with mature reimbursement frameworks where total cost of ownership scrutiny exceeds initial capital outlay sensitivity.
Focused Ultrasound System Market Segmentation
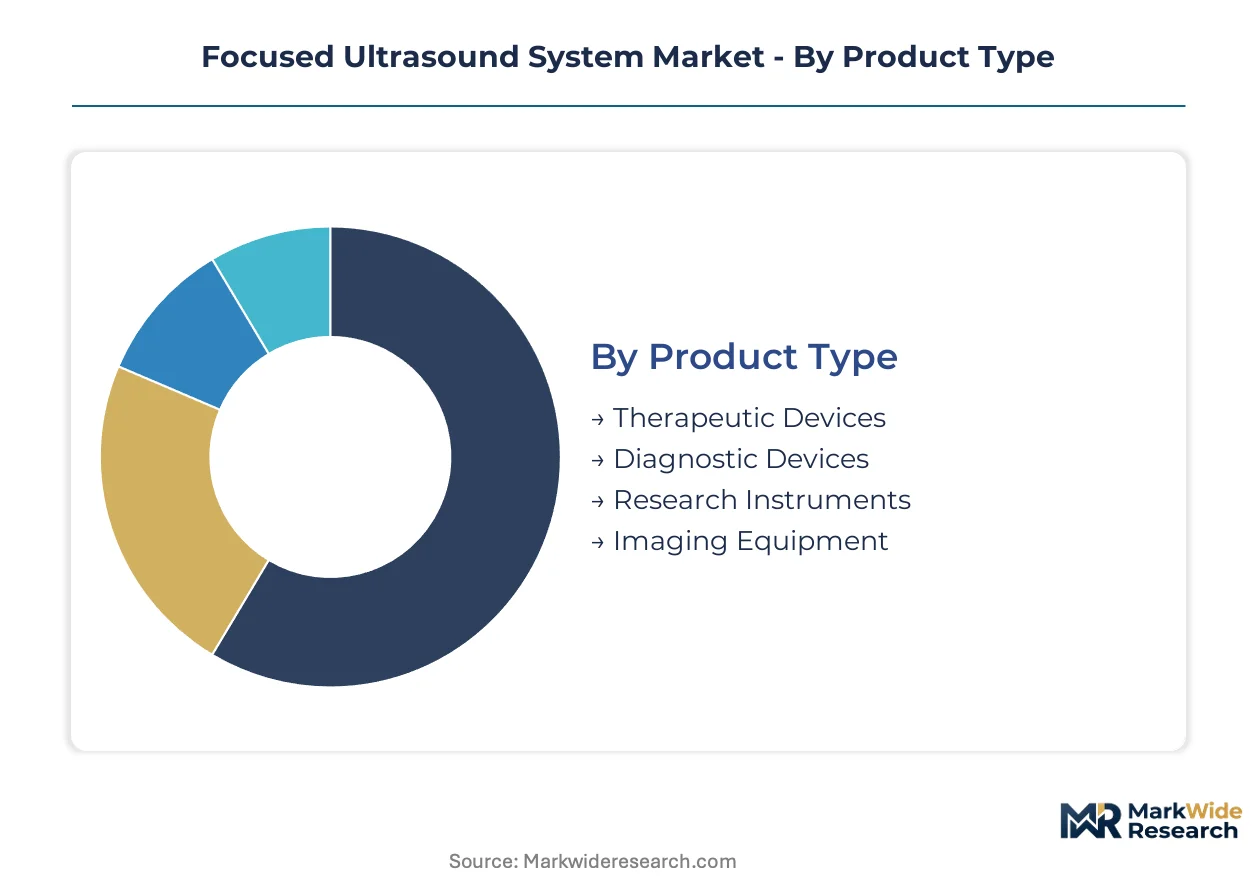
Focused ultrasound systems fragment across four dimensions that determine procurement priorities and clinical adoption timelines. Product type and application segmentation reveal where capital budgets concentrate versus where emerging indications disrupt established modalities. Technology and end-user splits expose the tension between research-driven innovation and reimbursable clinical deployment.
Product Type:
Therapeutic devices face intensifying substitution pressure from histotripsy platforms that bypass thermal ablation entirely, while diagnostic and imaging equipment contend with conventional ultrasound and MRI system incumbency.
- Therapeutic Devices:High-intensity focused ultrasound systems generate localized thermal or mechanical tissue destruction at focal intensities exceeding 1000 W/cm², typically operating between 0.5 and 4 MHz. Hospital capital budgets in the United States, Germany, and China concentrate procurement here as oncology departments replace legacy surgical suites with image-guided ablation workstations. MR-guided platforms with real-time thermometry integration command premium positioning.
- Diagnostic Devices:Conventional ultrasound imaging systems with focused beam capabilities support screening and monitoring functions without therapeutic intervention. Demand clusters in community hospitals and ambulatory clinics where capital constraints preclude full MR-guided therapeutic suites, particularly in German outpatient networks seeking CE-marked alternatives.
- Research Instruments:Experimental platforms enable preclinical validation of novel acoustic energy protocols and tissue effect mechanisms.
- Imaging Equipment:Specialized visualization systems integrate with therapeutic workstations to enable targeting verification and treatment monitoring.
Therapeutic devices anchor the volume base while histotripsy-enabled mechanical ablation platforms gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive neurology installations from reimbursable oncology procedures and emerging pain management protocols.
- Oncology:Tumor ablation applications span hepatocellular carcinoma, prostate tissue, and soft tissue malignancies using thermal or mechanical destruction protocols. Academic medical centers in the United States and China drive adoption as FDA breakthrough designations and NMPA priority review channels accelerate clinical validation timelines for histotripsy indications.
- Neurology:Essential tremor treatment via thalamic ablation extends into Parkinson's disease and neuropathic pain indications where magnetic resonance imaging guidance enables sub-millimeter targeting accuracy. German university hospitals and US academic centers concentrate demand as reimbursement frameworks mature for non-invasive functional neurosurgery.
- Cardiology:Cardiac tissue ablation and valve repair applications remain in earlier clinical validation stages with limited commercial deployment.
- Pain Management:Peripheral nerve modulation and bone metastasis palliation represent emerging indications with variable reimbursement coverage.
Oncology procedures anchor the volume base while neurology applications expand most quickly as indication sets broaden beyond essential tremor.
End User:
Customer type determines procurement authority complexity, with hospitals navigating capital committees and research institutions operating under grant funding cycles.
- Hospitals:Academic medical centers and tertiary care facilities command procurement of MR-guided therapeutic platforms requiring dedicated shielded suites and specialized physicist staffing. The United States and Germany concentrate installed base growth where Federal Joint Committee and CMS coverage decisions determine capital allocation between focused ultrasound and surgical robotics.
- Clinics:Ambulatory surgical centers and urology specialty clinics seek compact HIFU systems for prostate ablation with established reimbursement codes. Underpenetration in US outpatient settings creates whitespace for robotic precision delivery platforms.
- Research Institutions:University laboratories and contract research organizations validate novel tissue effect mechanisms and combination therapy protocols.
- Rehabilitation Centers:Pain management and neuromodulation applications serve chronic condition populations with varying payer coverage.
Hospitals anchor the volume base while clinics gain share at the steepest rate as reimbursement codes expand for outpatient ablation procedures.
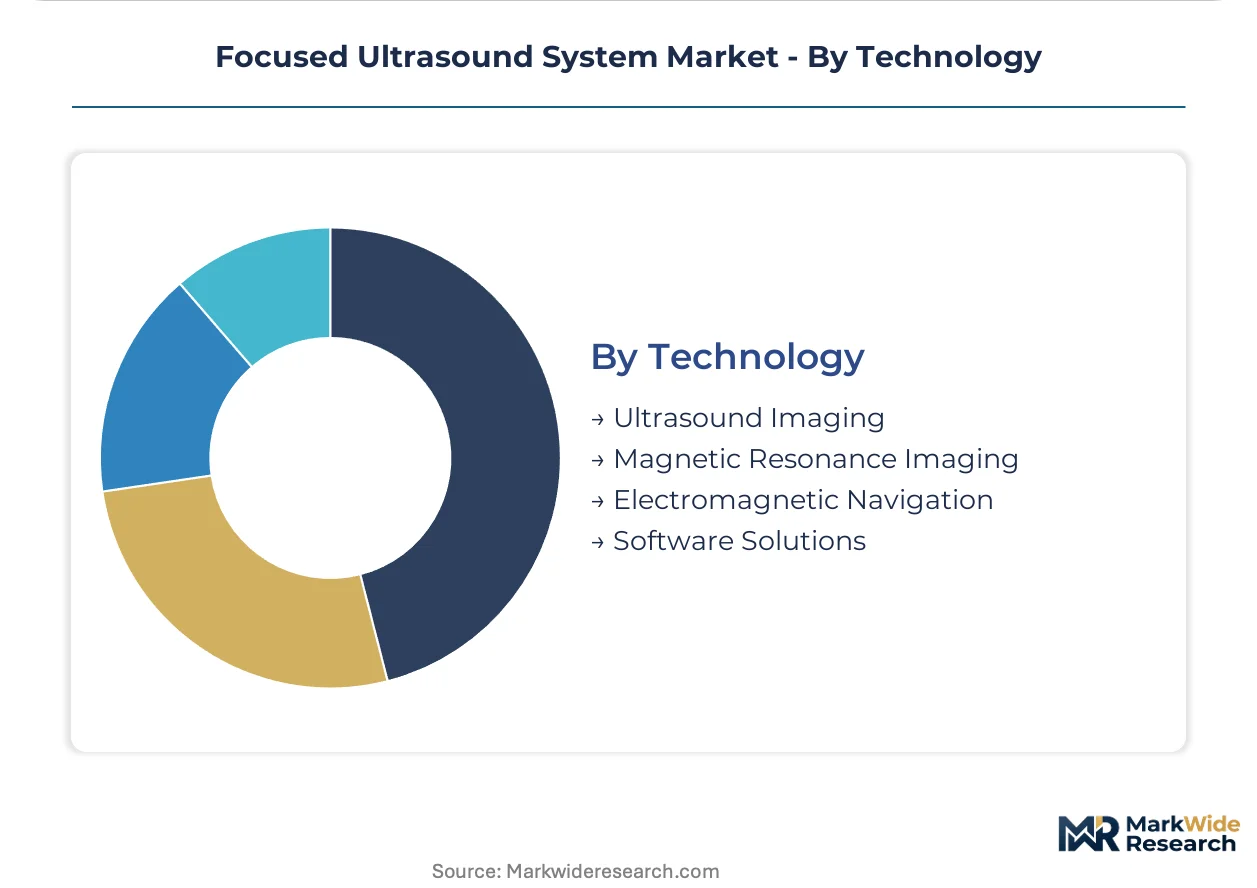
Technology:
Supply concentration in piezoelectric ceramic sourcing and MR thermometry integration complexity differentiate platform architectures.
- Ultrasound Imaging:Real-time B-mode and Doppler visualization enables targeting and monitoring without magnetic resonance infrastructure. Cost-sensitive clinics and community hospitals in China and Germany prioritize this modality where capital constraints preclude full MR suite installation.
- Magnetic Resonance Imaging:MR thermometry integration provides real-time temperature mapping for thermal dose control and tissue-specific protocols. Academic medical centers demand this capability for neurology applications where sub-millimeter accuracy determines clinical outcomes.
- Electromagnetic Navigation:Tracking systems enable spatial registration between patient anatomy and treatment planning coordinates.
- Software Solutions:Treatment planning algorithms and dose simulation tools support protocol standardization across clinical sites.
Ultrasound imaging anchors the volume base while magnetic resonance imaging gains share at the steepest rate as thermometry integration becomes standard for precision ablation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in focused ultrasound systems tilt toward net importing in Western markets while China builds domestic manufacturing capacity for piezoelectric transducer assemblies. Germany and the United States absorb the highest unit volumes of MR-guided therapeutic platforms, though both rely on East Asian component sourcing for critical acoustic arrays.
United States
FDA breakthrough device designations for histotripsy applications accelerate clinical validation timelines at academic medical centers in Boston and Stanford. CMS national coverage determinations for essential tremor ablation procedures determine whether hospital capital committees prioritize focused ultrasound over surgical robotics. The Mayo Clinic in Rochester anchors a concentration of neurology-focused installation sites.
Germany
The Federal Joint Committee's reimbursement decisions for non-invasive prostate ablation procedures shape hospital procurement patterns across Bavaria and North Rhine-Westphalia. EU MDR post-market surveillance requirements extend clinical evidence obligations for implanted transducers throughout the device lifecycle. Heidelberg University Hospital hosts a dedicated center of excellence for MR-guided functional neurosurgery.
China
NMPA priority review channels accelerate domestic oncology device approvals, stimulating procurement in tier-one cities including Beijing and Shanghai. Chongqing and Shenzhen cluster manufacturing capabilities for high-intensity transducer assemblies serving both domestic and export markets. The country's dual carbon goals incentivize energy-efficient ablation modalities in public hospital procurement frameworks.
Japan
PMDA regulatory frameworks emphasize longitudinal safety monitoring for therapeutic ultrasound devices, extending validation timelines for novel indications. METI industrial policy supports precision medical device manufacturing in the Nagoya and Osaka industrial corridors. University hospitals in Tokyo concentrate clinical adoption of neurology applications beyond essential tremor.
France
ANSM coordination with notified bodies on CE marking pathways accelerates histotripsy commercial deployment in Paris and Lyon university hospitals. The country's national health insurance fund evaluates procedure code expansion for outpatient ablation settings. Toulouse hosts a research cluster pairing acoustic energy protocols with immuno-oncology combination therapies.
Focused Ultrasound System Market Vendor Landscape
Concentration sits with integrated platform developers that combine therapeutic hardware with proprietary software planning systems and service contract bundling. The vendor base stratifies across three tiers: multinational imaging conglomerates with diversified medical device portfolios, mid-cap specialists focused exclusively on therapeutic ultrasound, and emerging histotripsy platform developers seeking first-mover indication clearances. Dominant competitive moves include strategic partnerships between acoustic technology developers and MRI manufacturers for thermometry integration, plus geographic expansion through distributor networks in underpenetrated urology clinic segments.
Among Israel-based platform developers, Insightec Ltd. and Profound Medical exemplify the specialist archetype with concentrated neurology and urology positioning respectively. EDAP TMS S.A. anchors the European urology channel as a France-based S.A. with established reimbursement relationships. These three occupy positions that illustrate the tension between single-modality depth and multi-application platform breadth in capital equipment markets.
| Leading Market Players |
|---|
| Profound Medical |
| Theraclion S.A. |
| Insightec Ltd. |
| Philips Healthcare |
| Alpinion Medical Systems |
| EDAP TMS S.A. |
| SonaCare Medical |
| GE Healthcare |
| Chongqing Haifu Medical Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for piezoelectric ceramic arrays concentrate procurement leverage among East Asian suppliers, translating directly into tiered pricing power for MR-guided platform manufacturers while forcing Western system integrators to absorb cost volatility or pass through to hospital capital committees.
Pricing Analysis
Hospital capital committees anchor pricing negotiations for therapeutic platforms, with three-tier pricing structure across premium, standard, and economy levels differentiated by thermometry integration depth and service contract bundling. Price differentiation stems from FDA breakthrough designation status and dedicated physicist staffing requirements. Cost compression in mid-tier installations is intensifying because third-party maintenance providers are displacing OEM service monopolies. Community hospitals exhibit highest price sensitivity, while academic medical centers prioritize thermometry accuracy over capital outlay.
Supply Chain Analysis
Strategic stockpiling of piezoelectric ceramics dominates inventory strategy among tier-one manufacturers, contrasting with just-in-time preferences for software and imaging subsystems. Component sourcing draws from China, Japan, and South Korea for transducer assemblies, with Germany and the United States contributing precision machining and MR integration hardware. Raw material dependencies include lead zirconate titanate ceramics, rare earth magnet alloys, and specialized acoustic coupling gels. Single-source vulnerability concentrates in high-intensity transducer fabrication. Distribution runs through direct hospital sales teams in developed markets and distributor networks in emerging procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Histotripsy platforms threaten thermal ablation incumbents with mechanical tissue destruction protocols that bypass legacy HIFU suite investments, forcing substitution defense across capital planning cycles.
For Market Incumbents: Compound defensive moats by deepening backward integration into transducer manufacturing to offset East Asian supply concentration, while accelerating CE marking pathways for next-generation cavitation platforms to preempt histotripsy entrants. Channel control through exclusive hospital system partnerships protects installed base revenue against robotic precision delivery competitors. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks compress clinical validation timelines for neurology indication expansion beyond essential tremor, opening whitespace in Parkinson's disease protocols at US academic medical centers. Target underpenetrated urology clinics in ambulatory surgical centers where reimbursement code expansion lags capital equipment deployment. Go-to-market leverage rests on robotic precision delivery differentiation against legacy manual probe systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MR-guided platform development as real-time thermometry integration demands specialized physicist staffing and shielded suite infrastructure. Long-term viability favors mid-cap specialists with concentrated neurology or urology positioning over diversified imaging conglomerates with fragmented therapeutic focus. Acquisition targets should demonstrate established reimbursement relationships in Germany or CMS coverage determinations. The signal to watch is Federal Joint Committee procedure code decisions for non-invasive ablation modalities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Accelerates clinical validation timelines for histotripsy oncology indications at academic medical centers. |
| CE Marking Under EU MDR | Compresses commercial deployment timelines across German and French university hospital procurement cycles. |
| Hospital System Partnership | Secures preferred vendor status for MR-guided platform installations against surgical robotics competitors. |
| Software Companion Development | Enables real-time thermometry integration with proprietary treatment planning algorithms. |
| Reimbursement Strategy | Aligns procedure code expansion with Federal Joint Committee and CMS coverage determination timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA device registration databases, and hospital procurement records across German, US, and Chinese institutions. Clinicians, hospital purchasing committee chairs, biomedical engineers specializing in MR thermometry, and GPO contracts managers provided structured input. Secondary validation drew from CMS national coverage determinations, NMPA priority review announcements, and EU MDR notified body documentation. Bottom-up unit economics and top-down macroeconomic indicators triangulate market sizing.
Segmentation dimensions modeled span product type, application, technology, and end user across the projection horizon. Therapeutic device revenue trajectories incorporate capital replacement cycles for legacy surgical suites and histotripsy platform adoption curves. Neurology application growth reflects indication expansion beyond essential tremor into Parkinson's disease protocols. CAGRs derive from weighted average of historical procurement patterns and scenario-adjusted adoption assumptions. Industry-specific inputs include reimbursement code expansion timelines and transducer supply lead time volatility.
Decision-makers should treat outputs as directional under assumptions of stable NMPA priority review throughput and continued EU MDR post-market surveillance enforcement; material deviation would warrant model refresh. Revision becomes warranted when Federal Joint Committee reimbursement decisions or CMS national coverage determinations cross thresholds that reallocate hospital capital budgets between focused ultrasound and surgical robotics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Contact Thermometer Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Lactate Meter Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Global Smart Implants Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Global Extremities Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Global Prosthetics Market