
 Airotar Handpiece Market | 2026-2036
Airotar Handpiece Market Size, Share, and Industry Trends Forecast 2026-2036
Airotar Handpiece Market Outlook
ISO 13485 certification for medical device quality management is collapsing the vendor landscape, forcing smaller manufacturers to surrender market access or absorb compliance costs. Dentsply Sirona leverages its vertically integrated manufacturing footprint across Switzerland and the United States to sustain bulk supply contracts with national dental distributors. NSK Ltd. anchors its position through proprietary air turbine engineering that dominates high-speed airotar specifications in Japanese and European clinics. KaVo Dental differentiates via precision-machined head geometries that reduce vibration fatigue during extended surgical applications.
An airotar handpiece is a pneumatically or electrically powered rotary dental instrument engineered to operate at rotational speeds typically exceeding 300,000 RPM, utilizing tungsten carbide or diamond-coated burs for hard-tissue cutting and finishing. Its primary commercial purpose is to deliver controlled, high-torque mechanical action for cavity preparation, crown adjustment, and prosthetic modification in clinical settings. Air turbine technology occupies the dominant share of installed base units globally, though electric handpieces are displacing legacy pneumatic systems in premium practices seeking torque consistency and reduced aerosol generation. Laboratories represent a concentrated demand pocket for hybrid handpieces that switch between speed modes, as dental prosthesis fabrication requires both aggressive grinding and fine contouring in sequential workflows.
The FDA Center for Devices and Radiological Health classifies airotar handpieces as Class II medical devices, mandating 510(k) premarket notification for substantial equivalence to legally marketed predicates. The EU MDR requires notified body involvement for all reusable surgical instruments, elevating documentation burdens and clinical evaluation standards for manufacturers seeking CE marking. Japan's PMDA enforces JIS T 0601 electrical safety standards that complicate market entry for non-domestic electric handpiece suppliers. Stakeholders must monitor regulatory divergence between FDA predicate pathways and MDR technical documentation requirements, as dual compliance strategies will determine which manufacturers retain shelf space across the Atlantic and Pacific corridors.
Market Dynamics
ISO 13485 certification requirements are compressing the vendor base, forcing smaller manufacturers to absorb compliance costs or surrender market access while vertically integrated suppliers capture procurement contracts from national dental distributors.
Growth Catalysts
- EU MDR sterility mandates:Tightened biocompatibility requirements for reusable dental instruments are accelerating replacement cycles in German and French dental clinics.
- High-speed air turbine adoption:Restorative procedure volumes in fee-for-service dentistry sustain premium equipment procurement in the United States and Switzerland.
- Electric handpiece torque consistency:Premium practices are displacing legacy pneumatic systems to reduce aerosol generation and improve cutting precision.
Market Restraints
- Tungsten carbide bur supply concentration:Sourcing dependency on limited specialty carbide producers creates input cost volatility for handpiece manufacturers.
- Japan PMDA electrical safety barriers:JIS T 0601 standards complicate market entry for non-domestic electric handpiece suppliers.
- Air turbine technical ceiling:Rotational speed limitations and torque decay under load constrain performance in extended surgical applications.
Strategic Opportunities
- Hybrid handpiece laboratory segment:Dental prosthesis fabrication workflows require speed-switching capabilities for grinding and contouring.
- US FDA 510(k) predicate pathway:Substantial equivalence frameworks offer faster clearance timelines for iterative product improvements.
- Swiss precision manufacturing clusters:Vertically integrated production footprints enable bulk supply contract capture from national distributors.
Industry Challenges
- Dual compliance documentation burdens:Manufacturers must reconcile FDA predicate pathways with EU MDR technical documentation requirements for transatlantic shelf retention.
- Aerosol mitigation capex:Clinic infrastructure upgrades for high-speed handpiece suction systems require capital deployment alongside equipment procurement.
- ISO 13485 audit timelines:Certification maintenance cycles compress product development schedules for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airotar Handpiece Market |
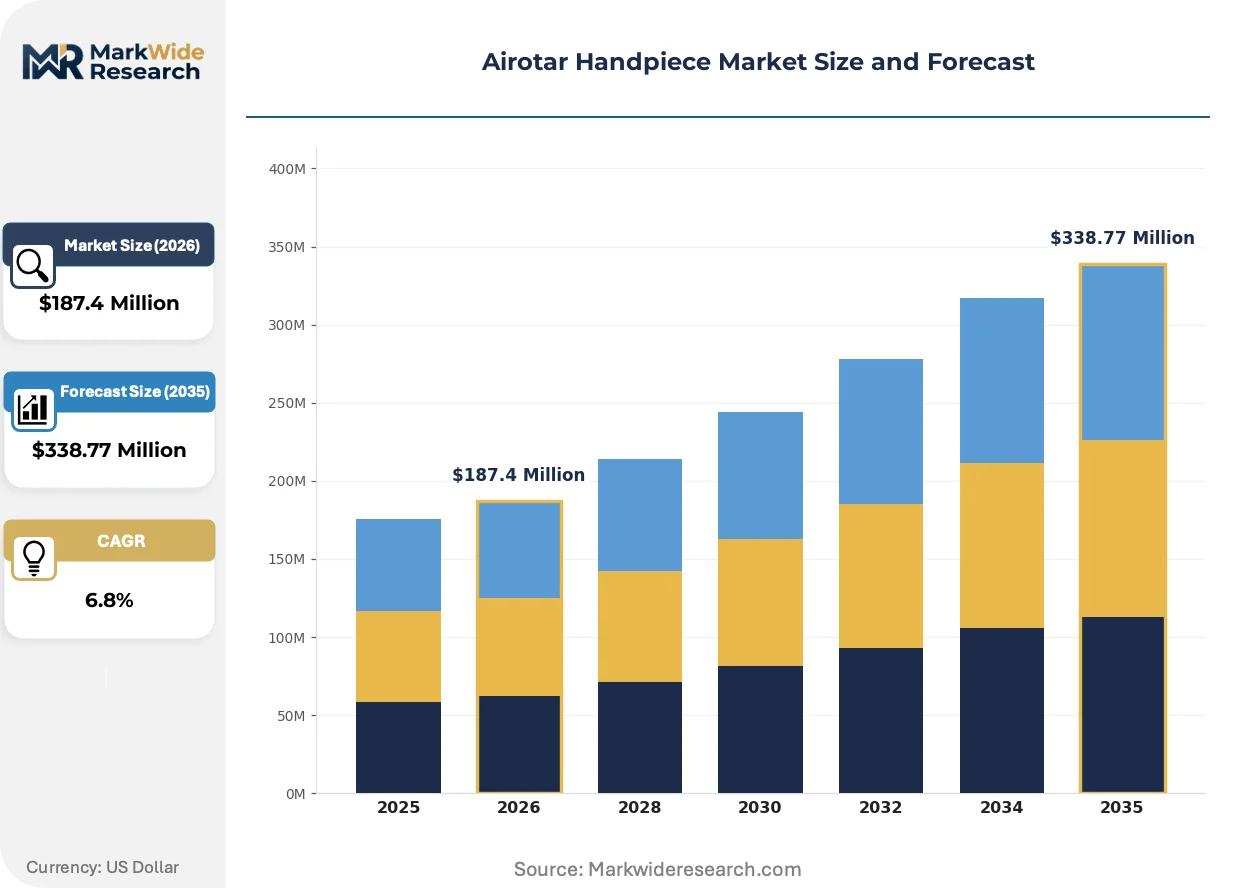
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Handpieces, Air Driven Handpieces, Battery Operated Handpieces, Hybrid Handpieces End User: Dentists, Oral Surgeons, Clinics, Laboratories Application: Restorative Dentistry, Cosmetic Procedures, Surgical Applications, Preventive Care Technology: Micromotor Technology, Air Turbine Technology, Piezo Technology, Laser Technology |
| Companies Covered | Dentsply Sirona, Being Foshan Medical Equipment, Foshan Gladent Medical Instrument Co., Ltd., Komet Dental, NSK Ltd., KaVo Dental, Lares Research, Sinol Dental, W&H Dentalwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airotar Handpiece Market Strategic Shifts
Active differentiation in airotar handpieces centers on torque delivery architectures, regulatory compliance automation, and procurement model restructuring as manufacturers respond to compressed replacement cycles and elevated sterility standards.
Brushless electric motor technology is fragmenting the installed base hierarchy. These systems deliver sustained torque across load variations without the RPM decay characteristic of air turbines. Japanese and German premium clinics are adopting electric platforms for implantology and crown preparation workflows. The technology is fragmenting vendor market share by compressing pneumatic system replacement demand into specialized high-speed niche applications.
EU MDR clinical evaluation standards are elevating documentation intensity for reusable surgical instruments. Notified body involvement now extends to technical file reviews that previously required only self-certification. Swiss and German manufacturers with established quality management systems are capturing procurement preference as distributors seek supply chain liability insulation.
Service-unbundled procurement is altering distributor economics. National dental supply houses are separating handpiece unit sales from maintenance contracts and bur replenishment programs. This pattern is most visible in United States fee-for-service practices where equipment financing and after-sales service are sourced through distinct vendor relationships.
Airotar Handpiece Market Segmentation
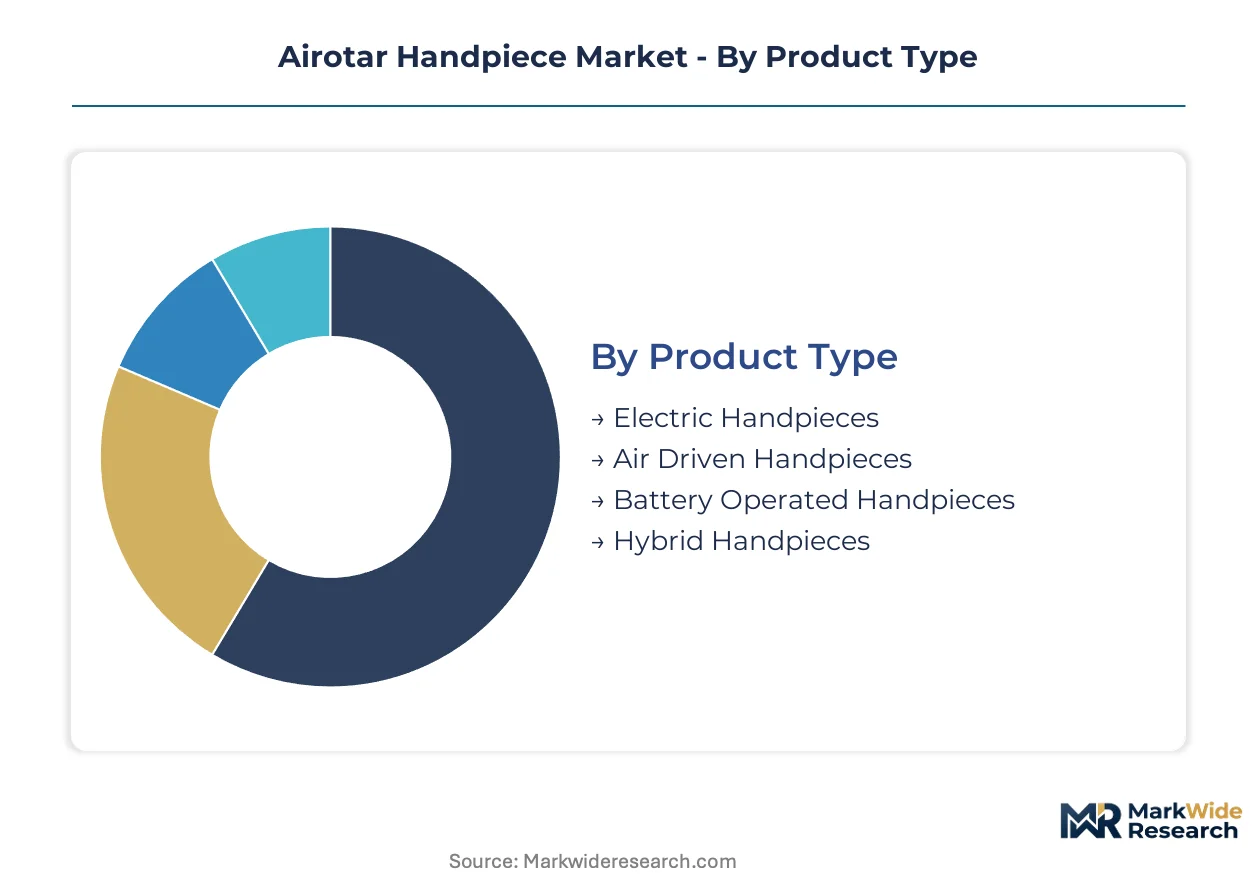
Airotar handpiece segmentation reveals divergent margin architectures across pneumatic and electric platforms, with procurement patterns shifting toward torque-consistent systems in premium clinical settings. Technology and end-user categories exhibit the steepest pricing stratification, driven by regulatory compliance burdens and procedural specialization requirements.
Product Type:
Margin pools concentrate in electric and hybrid configurations where precision engineering commands procurement premiums from implantology-focused practices.
- Electric Handpieces:Brushless motor architectures deliver sustained torque across load variations without RPM decay characteristic of pneumatic systems. Demand concentrates in German and Japanese premium clinics performing implantology and crown preparation workflows, driven by aerosol reduction mandates and cutting precision requirements.
- Air Driven Handpieces:Traditional air turbine systems operate at rotational speeds exceeding 300,000 RPM using compressed air delivery. Procurement remains concentrated in United States fee-for-service dentistry where replacement cycles for restorative procedures sustain bulk supply contracts with national distributors.
- Battery Operated Handpieces:Cordless lithium-ion powered units enable mobility in field dentistry and temporary clinic setups.
- Hybrid Handpieces:Multi-mode systems switch between speed configurations for sequential grinding and contouring workflows in dental laboratories.
Air driven handpieces hold installed capacity. Electric handpieces are rotating up the share rankings.
End User:
Volume concentration sits with general dentistry practices, though margin capture favors specialized surgical operators facing extended procedure demands.
- Dentists:General practitioners constitute the core procurement base for standard-speed air turbine units in routine cavity preparation and prosthetic adjustment. United States and Swiss fee-for-service practices drive replacement cycle velocity through equipment financing programs.
- Oral Surgeons:Specialized operators require high-torque electric platforms for extended osteotomy and implant placement procedures. EU MDR sterility mandates are accelerating upgrade timelines in French and German surgical centers seeking liability insulation.
- Clinics:Multi-chair group practices optimize capital deployment through service-unbundled procurement separating unit sales from maintenance contracts.
- Laboratories:Prosthesis fabrication facilities demand speed-switching capabilities for aggressive grinding followed by fine contouring in sequential workflows.
Dentists maintain procurement volume leadership. Oral surgeons are climbing the fastest on margin contribution metrics.
Application:
Technology differentiation generates widest pricing spreads in surgical and cosmetic segments where precision tolerances justify premium platform investment.
- Restorative Dentistry:Cavity preparation and crown adjustment procedures dominate air turbine utilization across standard clinical workflows. German dental clinics are expanding procurement of high-speed units as EU MDR tightens sterility requirements for reusable instruments.
- Surgical Applications:Implantology and osteotomy procedures demand sustained torque delivery achievable only through electric micromotor platforms. Japanese PMDA electrical safety standards create compliance barriers favoring domestic and established European suppliers.
- Cosmetic Procedures:Veneer preparation and aesthetic contouring require vibration-minimized precision machining.
- Preventive Care:Prophylaxis and minor enamel modification utilize entry-speed pneumatic systems with shorter operational lifespans.
Restorative applications anchor installed base volumes. Surgical applications are expanding most quickly in revenue per unit terms.
Technology:
Supply concentration in air turbine manufacturing contrasts with fragmented electric motor sourcing, creating divergent margin protection dynamics.
- Air Turbine Technology:Compressed air-driven rotational systems dominate global installed base through mechanical simplicity and rapid RPM achievement. Swiss precision manufacturing clusters sustain bulk supply contract capture from national distributors seeking quality management certification.
- Micromotor Technology:Electric motor platforms with electronic speed control enable torque consistency across variable load conditions. Premium practices in Japan and Germany are displacing legacy pneumatic systems to reduce aerosol generation and improve cutting precision.
- Piezo Technology:Ultrasonic vibration systems enable selective hard-tissue cutting with minimal thermal generation.
- Laser Technology:Photonic ablation systems serve niche soft-tissue applications outside core airotar functionality.
Air turbine technology commands installed capacity. Micromotor technology is gaining share fastest among new procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR sterility mandates are accelerating equipment replacement cycles in Western European dental clinics. Fee-for-service dentistry in the United States and Switzerland sustains premium procurement velocity. Japanese regulatory barriers favor domestic suppliers in electric handpiece segments.
United States
FDA 510(k) predicate pathways enable faster clearance timelines for iterative product improvements. Fee-for-service dentistry practices in Texas and California drive replacement cycle velocity through equipment financing programs. The Southeast corridor sees expanding group practice consolidation optimizing capital deployment through service-unbundled procurement models.
Germany
EU MDR tightened biocompatibility requirements for reusable dental instruments accelerate upgrade timelines in Bavarian and North Rhine-Westphalian dental clinics. German national health reimbursement structures sustain restorative procedure volumes. The Stuttgart precision manufacturing cluster anchors vertically integrated production footprints capturing bulk supply contracts.
Switzerland
Swissmedic certification requirements elevate quality management documentation burdens for reusable surgical instruments. Zurich and Basel dental clinics prioritize high-speed air turbine procurement for crown preparation workflows. The Swiss Romandie region concentrates precision-machined head geometry manufacturing reducing vibration fatigue specifications.
Japan
PMDA JIS T 0601 electrical safety standards complicate market entry for non-domestic electric handpiece suppliers. Tokyo and Osaka premium clinics adopt brushless micromotor platforms for implantology procedures. The Chubu region around Nagoya anchors proprietary air turbine engineering dominating high-speed specifications.
France
ANSM oversight of reusable surgical instruments elevates clinical evaluation standards for CE marking renewals. Paris and Lyon surgical centers seek liability insulation through ISO 13485-certified supplier relationships. The Auvergne-Rhône-Alpes region hosts dental distributor consolidation capturing national procurement contracts.
Airotar Handpiece Market Competitive Environment
Player mix skews toward vertically integrated precision manufacturers with established quality management certifications. ISO 13485 compliance requirements compress the vendor base, forcing smaller manufacturers to absorb certification costs or surrender market access. Three archetypes dominate: Swiss-German precision engineering specialists, Japanese air turbine technology leaders, and diversified dental equipment conglomerates with captive distribution. Competitive moves center on M&A for regulatory capability acquisition and strategic partnerships for dual-compliance documentation.
Among diversified dental equipment conglomerates, Dentsply Sirona and KaVo Dental occupy positions exemplifying vertically integrated manufacturing strategies. NSK Ltd. anchors the Japanese specialist archetype with proprietary engineering heritage. These three represent the tier capturing procurement preference from national distributors seeking supply chain liability insulation under EU MDR and FDA dual compliance requirements.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Being Foshan Medical Equipment |
| Foshan Gladent Medical Instrument Co., Ltd. |
| Komet Dental |
| NSK Ltd. |
| KaVo Dental |
| Lares Research |
| Sinol Dental |
| W&H Dentalwerk |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supply qualification and price differentiation in airotar handpiece procurement, compressing vendor margins for uncertified manufacturers while enabling Swiss and German producers to command procurement premiums from liability-averse distributors.
Pricing Analysis
Cost-plus contracts with tungsten carbide bur indexation dominate procurement between handpiece manufacturers and national dental distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling. Pricing pressure stems from EU MDR documentation burdens forcing mid-tier manufacturers to absorb compliance costs or exit. General dentistry practices exhibit highest price sensitivity, while oral surgery centers prioritize torque consistency over unit cost.
Supply Chain Analysis
Inventory cycles for precision-machined head geometries extend lead times for custom turbine specifications ordered by Japanese and German clinics. Manufacturing concentrates in Switzerland, Germany, and Japan, with tungsten carbide burs, brushless micromotors, and lithium-ion battery cells as critical inputs. Single-source vulnerability in specialty carbide producers creates input cost volatility. Distribution runs through national dental supply houses unbundling unit sales from maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of dual FDA-MDR regulatory capability concentrates competitive advantage among vertically integrated precision manufacturers, forcing strategic choices around certification investment versus niche retreat.
For Market Incumbents: Compound ISO 13485 audit automation investments to compress certification maintenance cycles and defend procurement relationships against emerging electric handpiece specialists. Deepen backward integration into tungsten carbide bur supply through captive production or long-term offtake agreements with Stuttgart and Nagoya precision machining clusters. Anchor market position by acquiring notified body relationships for streamlined EU MDR technical documentation. For New Entrants and Emerging Players: Anchor in battery-operated handpiece segments serving field dentistry and temporary clinic setups where regulatory barriers remain lowest. Target dental laboratories in France and the United States with hybrid speed-switching platforms for prosthesis fabrication workflows. Pursue service-unbundled go-to-market models separating hardware sales from consumable replenishment programs. For Investors and Strategic Acquirers: EU MDR sterility mandate implementation reshapes the acquisition landscape toward ISO 13485-certified manufacturers with established notified body relationships. Long-term viability favors precision engineering specialists with vertically integrated production footprints spanning Switzerland and Germany. Monitor FDA 510(k) clearance velocity for electric handpiece predicates as inflection indicator for technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Automation | Compresses audit timelines for mid-tier manufacturers seeking EU MDR compliance. |
| Backward Integration into Carbide Supply | Secures tungsten carbide bur sourcing against specialty producer concentration. |
| Electric Platform Development | Captures torque-consistent demand from Japanese and German implantology clinics. |
| Notified Body Relationship Acquisition | Accelerates CE marking pathways for reusable surgical instrument portfolios. |
| Service-Unbundled Procurement Launch | Aligns distributor economics with United States fee-for-service practice financing. |
Study Parameters
A standing panel of dental equipment procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts managers, and aftermarket service heads provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up unit demand modeling triangulated against top-down manufacturer shipment estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and technology platform. CAGRs derived from iterative regression against procedure volume trajectories and equipment replacement cycle data. Forecast inputs incorporated EU MDR implementation timelines and Japanese PMDA electrical safety standard evolution.
Material uncertainties — regulatory divergence between FDA predicate pathways and MDR clinical evaluation standards, tungsten carbide supply disruptions, aerosol mitigation infrastructure deployment rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
EEG Electrodes Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Knee Braces Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Global Vessel Sealing Devices Market