
 Nitinol-Based Guide Wire Market | 2026-2036
Nitinol-Based Guide Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Nitinol-Based Guide Wire Market Insights
The EU Medical Device Regulation is decoupling low-traceability suppliers from European procurement channels. Boston Scientific Corporation leverages its vertically integrated nitinol wire-drawing capabilities to sustain compliance advantages. Medtronic plc anchors its position through captive superelastic alloy foundries in Ireland. Abbott Laboratories differentiates via proprietary surface-polishing protocols that reduce thrombogenicity risks.
Nitinol-based guide wires are nickel-titanium alloy instruments exhibiting superelasticity and kink resistance at body temperature, manufactured through vacuum arc remelting and cold drawing to achieve Af transformation temperatures between 15°C and 35°C for intravascular navigation. The coronary product type occupies the largest revenue pool due to procedural volume, while the neurovascular category records the fastest expansion as flow-diversion and thrombectomy techniques diffuse. Single-use delivery mode dominates hospital purchasing through infection-control protocols, though customizable configurations command premium positioning in academic medical centers.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for nitinol guide wire manufacturers. ISO 5832-11 standards for surgical implant alloys constrain raw material sourcing, while Japan's PMDA enforces supplementary biocompatibility testing for nickel-leaching thresholds. Stakeholders must monitor evolving nickel-sensitivity litigation trends and superelastic alloy supply concentration before committing to capacity expansion or geographic diversification strategies.
Market Dynamics
Superelastic alloy supply concentration in a handful of specialized foundries is forcing device manufacturers to secure captive material streams or face EU MDR traceability disqualification. This structural bottleneck is reshaping competitive positioning across coronary and neurovascular catheter segments.
Growth Catalysts
- EU MDR material traceability mandates:The Medical Device Regulation's tightened documentation requirements for implantable nickel-titanium alloys are filtering out low-traceability suppliers and consolidating procurement toward vertically integrated manufacturers.
- Flow-diversion technique diffusion:Interventional neuroradiologists are expanding nitinol guide wire utilization for intracranial aneurysm treatment, driving procedural volume in academic medical centers.
- Germany's cardiovascular device cluster:Concentrated R&D activity around Aachen and Erlangen is accelerating product iteration cycles and specialist workforce development.
Market Restraints
- Nickel-titanium ingot supply concentration:Vacuum arc remelting capacity clusters in select North American and European superelastic alloy foundries, creating single-source vulnerability for wire-drawing operations.
- ISO 5832-11 raw material constraints:Surgical implant alloy standards limit sourcing flexibility and extend qualification timelines for new suppliers entering the supply base.
- Polymer-coated alternatives:Hydrophilic polymer-sheathed stainless steel guide wires compete on cost in less complex lesion subsets, pressuring nitinol pricing in standard coronary procedures.
Strategic Opportunities
- Japan's PMDA biocompatibility pathway:Supplementary nickel-leaching testing requirements create first-mover advantage for manufacturers with established toxicology dossiers.
- Customizable configuration demand:Academic medical centers are requesting patient-specific tip geometries and stiffness gradients, opening premium positioning above standard single-use SKUs.
- Robotic catheter system integration:Magnetic navigation and robotic-assisted PCI platforms require specialized nitinol wire mechanical properties, creating specification lock-in opportunities.
Industry Challenges
- Vacuum arc remelting metallurgist scarcity:The specialized skill set for Af temperature control and inclusion management in nickel-titanium ingots constrains foundry expansion.
- EU MDR conformity assessment timelines:Extended notified body review periods for Class III device recertification are compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitinol-Based Guide Wire Market |
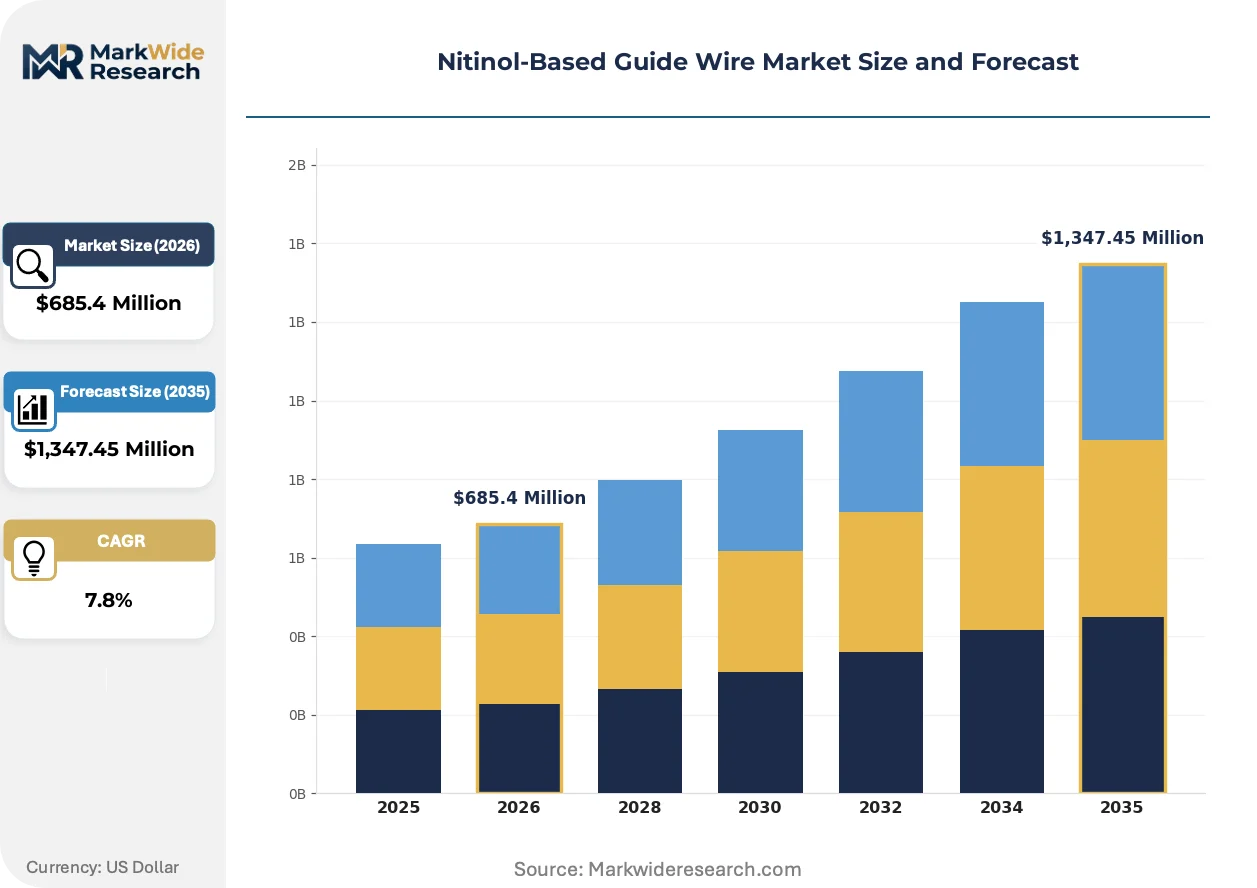
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary, Peripheral, Urological, Neurovascular Application: Cardiovascular Procedures, Urology Procedures, Neurology Procedures, Gastrointestinal Procedures Delivery Mode: Single Use, Reusable, Preloaded, Customizable End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Abbott Laboratories, Terumo Corporation, Cardinal Health, Cook Group, Stryker Corporation, Teleflex Incorporated, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitinol-Based Guide Wire Market Trends and Innovations
Surface engineering and manufacturing process control are converging to address thrombogenicity and mechanical performance simultaneously. Device developers are pursuing multi-functional wire architectures that reduce procedural steps.
Laser surface texturing combined with electropolishing protocols is unifying hemocompatibility and lubricity requirements in a single processing sequence. Interventional cardiologists in high-volume catheterization labs are adopting these surfaces for complex chronic total occlusion cases. The technology is compressing the competitive gap between specialty manufacturers and diversified device portfolios.
The EU MDR's Unique Device Identification and economic operator requirements are extending quality management system obligations through the entire supply chain. Wire-drawing subcontractors now face direct audit liability previously borne solely by finished device legal manufacturers. Coronary guide wire product lines with multi-tier supplier bases are experiencing the most significant compliance cost inflation.
Hospital value analysis committees are consolidating guide wire purchasing through single-source agreements with tiered performance specifications. Distributors are losing shelf-space access as IDNs centralize cardiac catheterization supply contracts. This concentration is most visible in Germany's university hospital networks, where procurement standardization across multi-site systems is displacing individual physician preference items.
Nitinol-Based Guide Wire Market Segmentation
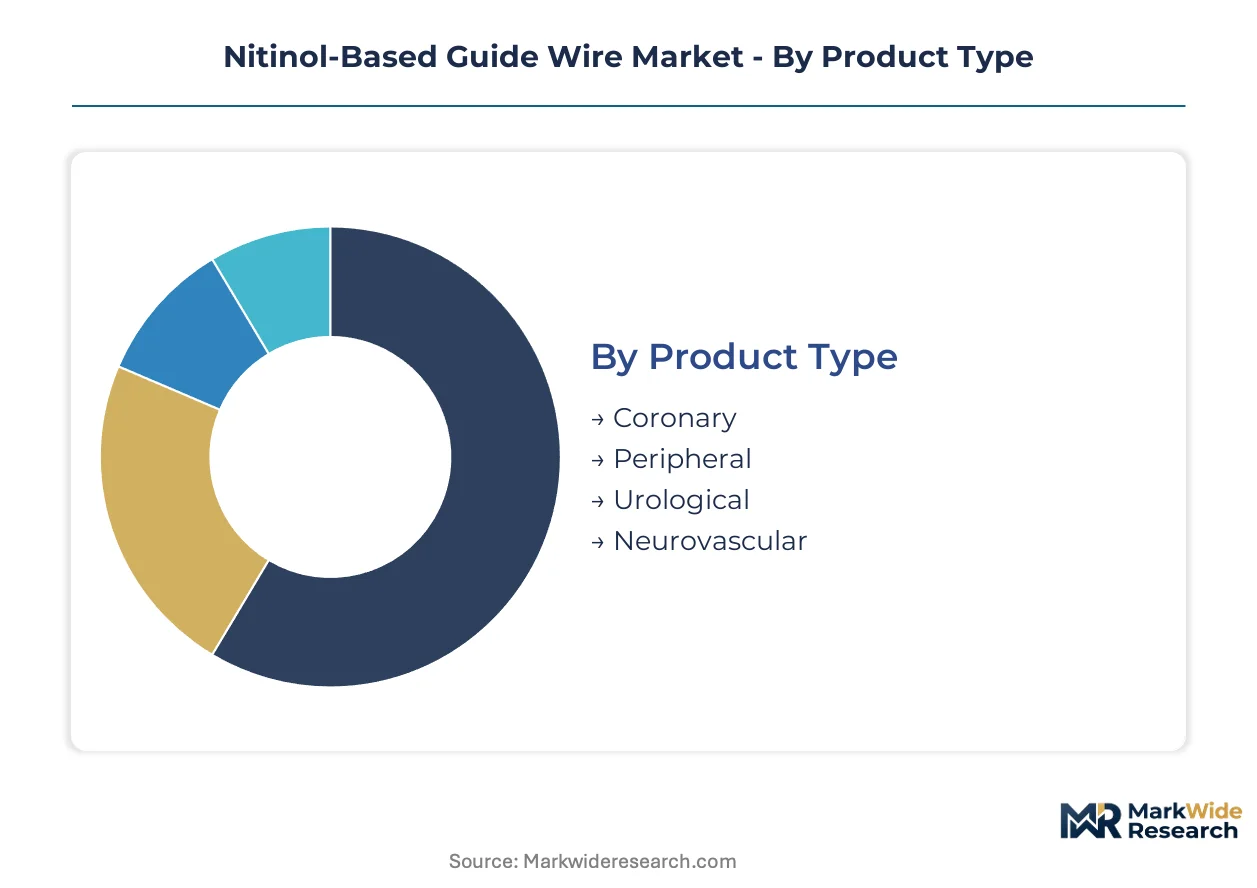
Nitinol guide wire procurement patterns diverge sharply across clinical settings, with infection-control protocols, procedural complexity, and capital equipment constraints driving distinct specification requirements. Manufacturers must align product architectures with these buyer archetypes to secure contract positioning.
Product Type:
Clinical indication determines mechanical specification requirements, with lesion complexity and vessel tortuosity dictating superelastic alloy grades and tip geometries.
- Coronary:High-torque construction with platinum-iridium radiopaque tips navigates calcified lesions and chronic total occlusions. Hospital catheterization labs in Germany's Aachen-Erlangen cluster drive specification refinement for multivessel disease cases.
- Neurovascular:Ultra-fine diameters below 0.014 inches with enhanced kink resistance enable intracranial aneurysm access via flow-diversion techniques. Academic medical centers in the United States and Japan are expanding procedural volumes for thrombectomy applications.
- Peripheral:Longer working lengths and enhanced pushability address femoropopliteal and below-the-knee interventions.
- Urological:Specialized coatings and stiffness profiles navigate ureteral strictures and renal access procedures.
Coronary leads volumes today; neurovascular is gaining share fastest.
Application:
Procedural reimbursement codes and clinical outcome data shape purchasing committee priorities across service line investments.
- Cardiovascular Procedures:Percutaneous coronary intervention and peripheral vascular intervention represent the established revenue base, with electrophysiology ablation procedures adding incremental demand for specialized torque response.
- Neurology Procedures:Ischemic stroke thrombectomy and aneurysm embolization procedures require distal flexibility combined with proximal pushability for tortuous intracranial anatomy.
- Urology Procedures:Ureteroscopy and percutaneous nephrolithotomy utilize hydrophilic-coated nitinol wires for stone access and stent placement.
- Gastrointestinal Procedures:ERCP and EUS-guided interventions employ guide wires for biliary drainage and fine-needle aspiration access.
Cardiovascular procedures dominate current utilization; neurology procedures show the steepest expansion trajectory.
Delivery Mode:
Capital intensity and inventory carrying costs separate institutional buyers from those prioritizing operational flexibility.
- Single Use:Pre-sterilized, individual packaging eliminates reprocessing infrastructure and aligns with EU MDR traceability requirements for implantable device contact. IDN procurement consolidation in Germany favors this mode for infection liability reduction.
- Customizable:Patient-specific tip shaping and stiffness gradients command premium positioning in academic medical centers performing complex anatomical cases. Robotic catheter platforms require proprietary mechanical specifications that lock in recurring purchases.
- Reusable:Limited adoption constrained by reprocessing validation costs and nickel-leaching biocompatibility concerns.
- Preloaded:Integrated delivery systems reduce procedural steps in high-volume catheterization labs.
Single use captures the majority of unit volume; customizable configurations extract the highest per-procedure revenue.
End User:
Procedure volume thresholds and purchasing authority centralization determine contract structure and specification complexity.
- Hospitals:Catheterization labs and hybrid operating rooms generate bulk purchasing power through value analysis committee standardization. University hospital networks in Germany are consolidating multi-site cardiac contracts, displacing individual physician preference items.
- Ambulatory Surgical Centers:Cost-containment priorities and limited inventory space favor streamlined SKUs with broad lesion applicability. Medicare reimbursement compression is accelerating site-of-service shift for peripheral interventions.
- Clinics:Office-based labs with lower procedural volumes rely on distributor relationships for just-in-time delivery.
- Research Institutions:Preclinical and clinical trial applications drive demand for investigational device configurations with enhanced documentation packages.
Hospitals anchor current procurement volume; ambulatory surgical centers are expanding most quickly as site-of-service migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgists for vacuum arc remelting cluster in Germany, Japan, and the United States, anchoring regional production capacity for superelastic alloy feedstock.
United States
Interventional cardiologists in Cleveland Clinic and Mayo Clinic catheterization labs drive specification refinement for chronic total occlusion cases. FDA 510(k) clearance pathways shape product development timelines and market access costs for nitinol guide wire manufacturers. Boston Scientific Corporation maintains vertically integrated nitinol wire-drawing capabilities in Massachusetts to sustain compliance advantages.
Germany
Hospital value analysis committees in university hospital networks consolidate multi-site cardiac contracts, displacing individual physician preference items. EU MDR material traceability mandates filter out low-traceability suppliers and consolidate procurement toward vertically integrated manufacturers. The Aachen-Erlangen cardiovascular device cluster accelerates product iteration cycles and specialist workforce development.
Japan
Academic medical centers in Tokyo and Osaka expand procedural volumes for thrombectomy applications using ultra-fine diameter nitinol guide wires. PMDA enforces supplementary biocompatibility testing for nickel-leaching thresholds, creating first-mover advantage for manufacturers with established toxicology dossiers. Terumo Corporation anchors domestic production through captive superelastic alloy processing capabilities.
Ireland
Medtronic plc operates captive superelastic alloy foundries to secure material streams and avoid EU MDR traceability disqualification. The national pharmaceutical regulator enforces ISO 5832-11 surgical implant alloy standards that constrain raw material sourcing flexibility. Dublin's medical technology corridor concentrates wire-drawing and finishing operations for European market access.
Switzerland
Swissmedic maintains stringent conformity assessment timelines for Class III device recertification, compressing product launch windows for manufacturers. Precision machining expertise in the Jura Arc supports specialized tip grinding and surface polishing operations. The country's private hospital networks prioritize premium customizable configurations for complex anatomical cases.
Nitinol-Based Guide Wire Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the nitinol guide wire landscape, with foundry ownership separating tier-one suppliers from contract-dependent assemblers. The vendor base concentrates around three strategic archetypes: vertically integrated alloy-to-device manufacturers, specialized wire-drawing subcontractors, and diversified cardiovascular portfolio holders. Competitive moves center on captive superelastic alloy foundry acquisitions and laser surface texturing technology licensing to secure specification lock-in with robotic catheter platforms.
Among diversified cardiovascular portfolio holders, Boston Scientific Corporation, Medtronic plc, and Abbott Laboratories exemplify contrasting approaches to material security and regulatory compliance. Boston Scientific Corporation represents the vertically integrated archetype with in-house nitinol wire-drawing capabilities. Medtronic plc anchors the captive foundry model through Irish superelastic alloy production. Abbott Laboratories occupies the surface-engineering differentiation position with proprietary polishing protocols.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Terumo Corporation |
| Cardinal Health |
| Cook Group |
| Stryker Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned superelastic alloy foundries in Germany and Japan anchor upstream supply discipline, translating vacuum arc remelting scarcity into sustained premium capture for compliant nitinol wire-drawing operations serving EU MDR-traceable device manufacturers.
Pricing Analysis
Bundled service contracts combining guide wire supply with technical training and reprocessing validation command premium positioning against unbundled transactional purchasing in cost-focused ambulatory surgical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 5832-11 certification grade and after-sales support intensity. Cost compression in standard coronary SKUs intensifies as polymer-coated stainless steel alternatives gain share in less complex lesion subsets. Academic medical centers exhibit lowest price sensitivity due to customizable configuration requirements, while ambulatory surgical centers drive hardest bargaining through consolidated GPO contracts.
Supply Chain Analysis
EU MDR domestic-content mandates and Japan's PMDA local-qualification pathways are reshaping sourcing patterns toward captive superelastic alloy foundries in Ireland and Massachusetts. Vacuum arc remelting capacity draws from Germany, Japan, and the United States, with nickel-titanium ingot production tethered to specialized metallurgist clusters in Aachen-Erlangen and Tokyo-Osaka corridors. Single-source vulnerability concentrates in North American vacuum arc remelting facilities serving multiple wire-drawing subcontractors. Distribution runs through hospital value analysis committees and integrated delivery network procurement offices, displacing traditional distributor shelf-space access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nitinol-based guide wire market functions as a stable compounder, with procedural volume expansion in chronic total occlusion and flow-diversion applications generating predictable recurring demand regardless of macroeconomic cyclicality.
For Market Incumbents: Extend specification lock-in with robotic catheter platforms through proprietary mechanical property development, while securing captive superelastic alloy foundry capacity to preempt EU MDR traceability disqualification. Polymer-coated stainless steel substitution in standard coronary procedures demands accelerated surface-engineering differentiation to defend margin position.
For New Entrants and Emerging Players: Begin with customizable configuration development for academic medical centers, where patient-specific tip geometries command premium positioning above commoditized single-use SKUs. Japan's PMDA biocompatibility pathway offers the most penetrable regulatory entry point for manufacturers with established nickel-leaching toxicology dossiers.
For Investors and Strategic Acquirers: Diversified cardiovascular device portfolios are the most active acquirer in this space, seeking laser surface texturing technology and vacuum arc remelting metallurgist teams to fill capability gaps. Target wire-drawing subcontractors facing direct EU MDR audit liability as quality management system obligations extend through supply chains. Watch nickel-sensitivity litigation trends as the signal indicating potential demand inflection for surface-engineered alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Superelastic Alloy Foundry Acquisition | Secures EU MDR traceability compliance and eliminates single-source vulnerability for nitinol ingot supply. |
| Laser Surface Texturing Technology Licensing | Unifies hemocompatibility and lubricity requirements for complex chronic total occlusion cases. |
| Robotic Catheter Platform Partnership | Creates specification lock-in through proprietary mechanical property requirements for magnetic navigation systems. |
| Japan PMDA Biocompatibility Dossier Development | Establishes first-mover advantage in supplementary nickel-leaching testing for Tokyo and Osaka academic centers. |
| Hospital Value Analysis Committee Direct Contracting | Bypasses distributor intermediaries as German university networks consolidate multi-site cardiac catheterization procurement. |
Research Methodology
Multiple input streams — primary interviews with interventional cardiologists, catheterization lab purchasing managers, and vacuum arc remelting metallurgists; secondary validation through FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database analysis — were reconciled through bottom-up and top-down triangulation across the analysis window.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning product type, application, delivery mode, and end-user facility tier throughout the forecast period. CAGRs were derived from procedural volume trajectories, reimbursement code stability, and superelastic alloy supply expansion constraints specific to coronary and neurovascular catheter segments.
Several conditions sit outside the modeled scope, including unforeseen nickel-sensitivity litigation outcomes, abrupt EU MDR notified body capacity constraints, and breakthrough polymer-coating technologies that could displace nitinol in standard lesion subsets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
ETCO2 Masks Market
Medical Devices
ADA Substitute Market
Medical Devices
Smart Bassinet Market
Medical Devices
Laryngoscopes Market
Medical Devices
Active Wheelchair Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Photopheresis Products Market
Medical Devices
Veterinary Ventilators Market