
 Inhaled Corticosteroid Device Market | 2026-2036
Inhaled Corticosteroid Device Market Size, Share, and Industry Trends Forecast 2026-2036
Inhaled Corticosteroid Device Market Outlook
The homecare settings segment is recalibrating demand patterns across the Inhaled Corticosteroid Device landscape. GlaxoSmithKline dominates respiratory portfolio breadth with established metered dose and dry powder platforms. AstraZeneca specializes in next-generation breath-actuated delivery systems with embedded sensors. Boehringer Ingelheim extends its position through geographic density in European reimbursement channels.
Inhaled corticosteroid devices are drug-delivery systems engineered to deposit anti-inflammatory corticosteroid compounds directly into pulmonary tissue, typically achieving particle sizes of 1-5 microns for optimal alveolar deposition and systemic minimization. Their commercial purpose centers on chronic management of inflammatory airway diseases where oral steroid exposure carries unacceptable metabolic burden. Metered dose inhalers anchor volume due to decades of physician familiarity and compact form factor, while smart inhalers represent the fastest-growing technology segment as connectivity enables adherence monitoring and payer value demonstration. Dry powder inhalers compete on propellant-free environmental positioning amid tightening F-Gas Regulation constraints.
The FDA enforces strict bioequivalence standards for generic inhalers through complex in vitro and clinical endpoint requirements that shape competitive entry timelines. EMA's MDR and REACH frameworks govern device material safety and environmental compliance across European manufacturing and distribution. Japan's PMDA maintains distinct pharmacokinetic expectations for locally acting pulmonary products that fragment development pathways. Stakeholders must monitor how real-world evidence requirements from these regulators reshape clinical trial investment and post-market surveillance obligations.
Market Dynamics
The homecare migration is compressing hospital procurement volumes while amplifying retail pharmacy and direct-to-patient channels, forcing device manufacturers to reengineer packaging, training protocols, and reimbursement documentation for non-clinical settings.
Growth Catalysts
- EMA MDR compliance deadlines:Device manufacturers upgrading quality management systems ahead of 2026 recertification windows are simultaneously modernizing sensor platforms and connectivity stacks.
- Japan's super-aging demographic:PMDA streamlined review pathways for combination products are accelerating local approval timelines for breath-actuated inhalers targeting COPD management in patients over 75.
- Propellant transition chemistry:Hydrofluoroalkane reformulation investments triggered by F-Gas Regulation phase-down schedules are creating first-mover advantages for suppliers with validated low-global-warming-potential alternatives.
Market Restraints
- Active pharmaceutical ingredient concentration:Three suppliers control 80% of micronized corticosteroid powder production, exposing device manufacturers to input cost volatility and allocation rationing during pharmaceutical manufacturing surges.
- FDA bioequivalence complexity:Generic inhaler sponsors face 24-36 month clinical endpoint studies and in vitro testing matrices that extend development timelines and compress post-patent exclusivity windows.
- Dry powder humidity sensitivity:Formulation stability requirements limit manufacturing site options to climate-controlled facilities in temperate zones, constraining geographic diversification of supply.
Strategic Opportunities
- India's respiratory disease burden:CDSCO's recent harmonization with ICH stability guidelines reduces redundant testing for multinational sponsors, opening pathways for affordable device introductions in tier-2 and tier-3 cities.
- Remote patient monitoring convergence:Integration of acoustic sensors and Bluetooth telemetry enables adherence data capture that satisfies payer evidence requirements for value-based contracting.
- Community pharmacy vaccination hubs:Post-pandemic infrastructure investments position retail pharmacies to deliver inhaler technique coaching and device dispensing, bypassing traditional pulmonology gatekeepers.
Industry Challenges
- Inhaler technique standardization:Variability in patient coordination with pressurized metered-dose devices drives 30-40% deposition inefficiency, requiring expensive training program investments with uncertain reimbursement.
- Legacy electronic health record integration:Smart inhaler data streams lack universal API standards, forcing device manufacturers to maintain multiple integration workflows across hospital systems and ambulatory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhaled Corticosteroid Device Market |
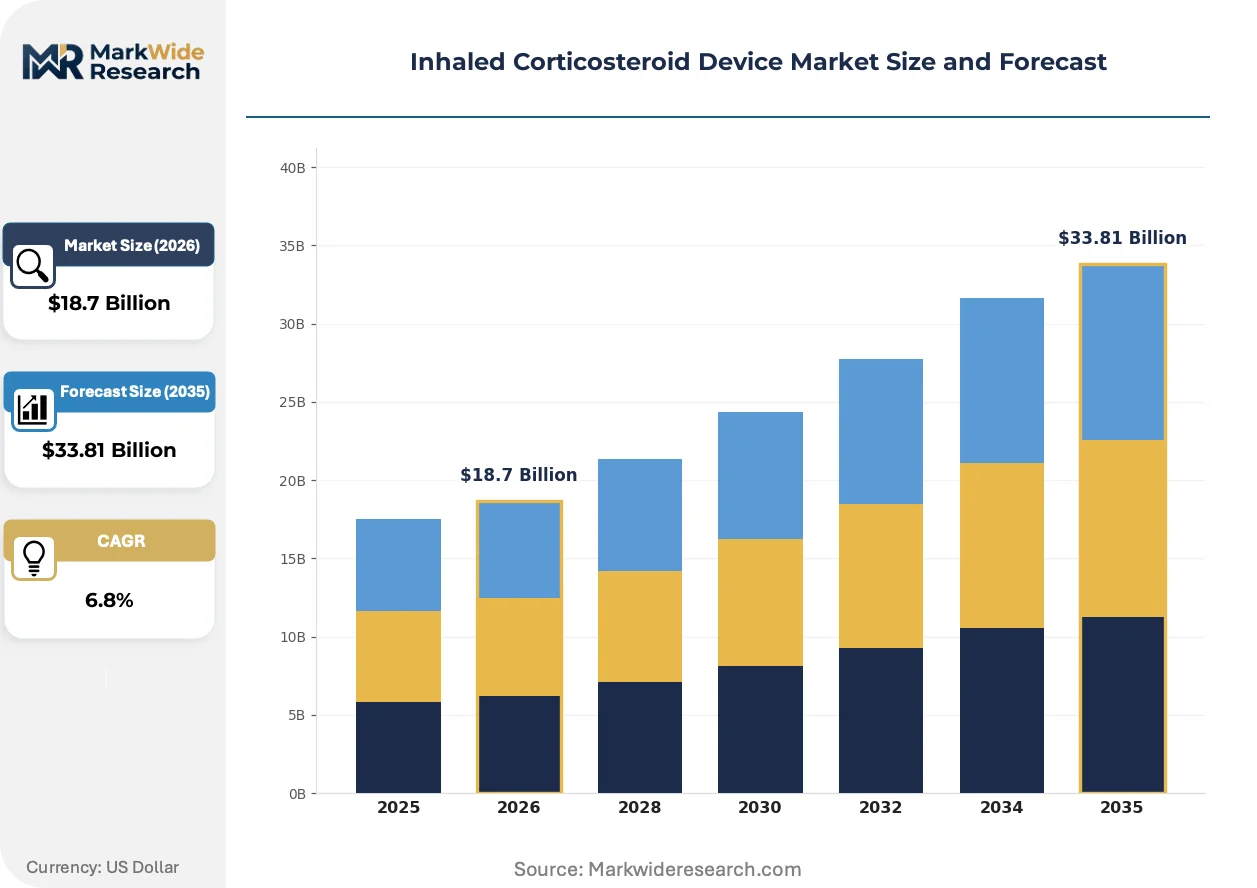
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers Technology: Conventional Inhalation Systems, Smart Inhalers, Breath-Actuated Devices, Nebulization Technology End User: Hospitals, Homecare Settings, Clinics, Pharmacies Application: Asthma, Chronic Obstructive Pulmonary Disease, Allergic Rhinitis, Respiratory Infections |
| Companies Covered | Teva Pharmaceutical Industries, Pfizer, GlaxoSmithKline, Chiesi, Merck and Co, AstraZeneca, Novartis, Sandoz, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhaled Corticosteroid Device Market Strategic Shifts
Connectivity and sustainability mandates are converging to redefine device architecture, with sensor miniaturization and propellant chemistry dominating engineering roadmaps while procurement patterns shift toward outcomes-verified supply contracts.
Smart inhaler platforms are absorbing capital allocation previously directed toward incremental form-factor refinements. Homecare providers and specialty pharmacies are deploying connected devices at accelerating velocity, with adherence data becoming a contractual prerequisite for preferred formulary placement. This technology is absorbing the documentation burden that previously required nurse-led home visits, compressing per-patient monitoring costs while expanding addressable patient populations.
REACH authorization requirements for novel propellant substances are restructuring supplier qualification timelines. Industrial consequence includes mandatory substance volume registration and extended safety dossier preparation for hydrofluoroalkane alternatives. European manufacturing sites are most affected, with several relocating final assembly to Switzerland to leverage Swissmedic's parallel but streamlined chemical notification pathways.
Direct contracting between device manufacturers and regional pharmacy chains is displacing traditional wholesale distribution for maintenance inhaler prescriptions. Hospital discharge coordinators and specialty pharmacists are becoming the primary relationship owners, replacing physician office sample closets as the initial patient touchpoint. This pattern is most visible in Germany, where Apotheken mandate for initial device dispensing creates concentrated buyer power at the pharmacy cooperative level.
Inhaled Corticosteroid Device Market Segmentation
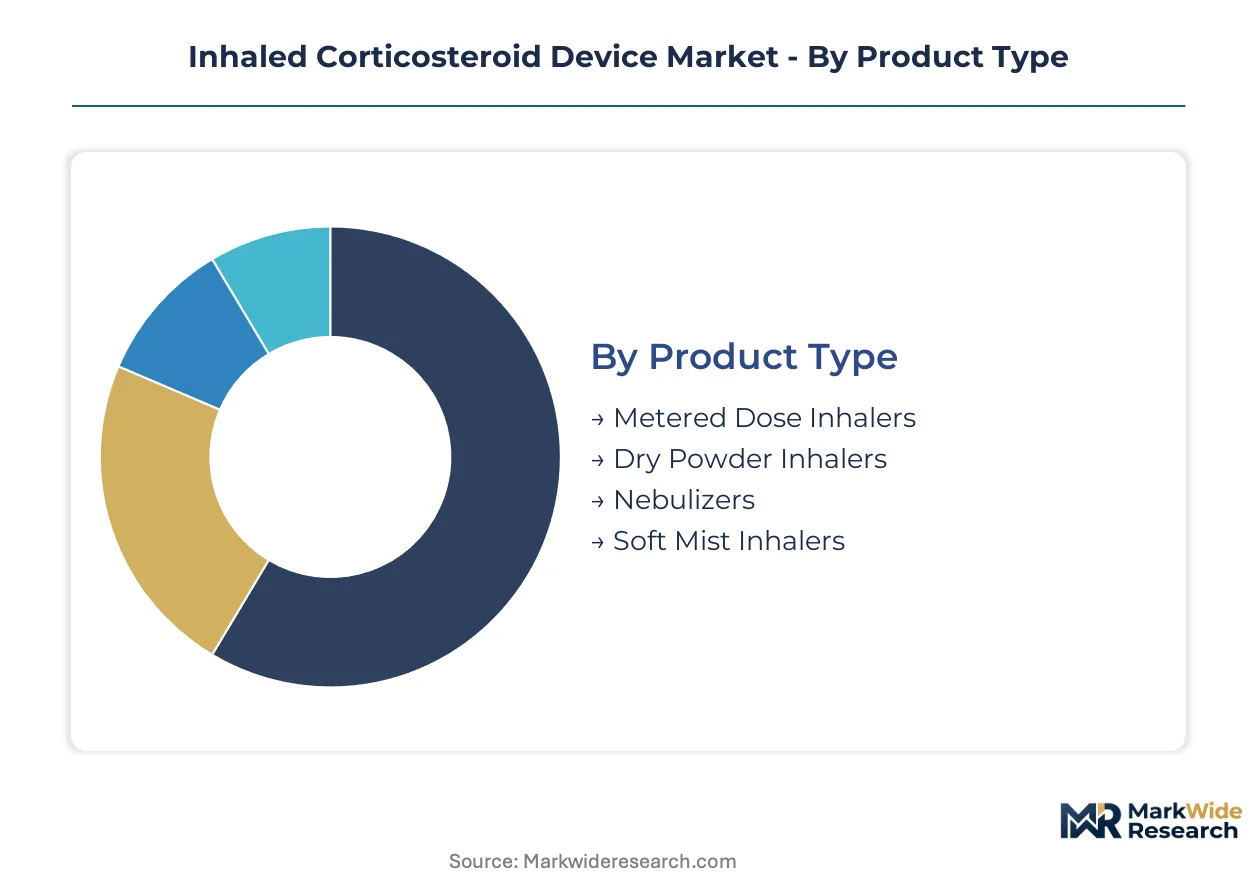
Device architecture and delivery mechanism variations create distinct competitive arenas within the inhaled corticosteroid landscape. Each segment carries unique regulatory pathways, manufacturing constraints, and reimbursement profiles that shape investment allocation and partnership strategies.
Product Type:
Replacement cycles accelerate as propellant chemistry transitions and connectivity modules reach end-of-life, forcing portfolio refresh decisions across all four device categories.
- Metered Dose Inhalers:Pressurized canister systems using hydrofluoroalkane propellants deliver precise dose volumes through actuator mouthpiece assemblies. Demand concentrates in the United States and Germany where physician familiarity and compact portability sustain preference despite coordination challenges. FDA bioequivalence requirements for generic alternatives extend development timelines and protect branded positions.
- Dry Powder Inhalers:Breath-activated devices utilizing lactose or carrier-free micronized formulations eliminate propellant dependence entirely. Homecare settings in Japan and Switzerland drive adoption as environmental regulations tighten around fluorinated gas emissions. Humidity-sensitive manufacturing constraints limit production site flexibility to climate-controlled temperate zones.
- Nebulizers:Compressor or vibrating mesh systems converting liquid suspensions into respirable aerosols for patients unable to coordinate handheld devices. Pediatric and geriatric applications dominate.
- Soft Mist Inhalers:Mechanical spring mechanisms generating slow-moving aerosol clouds with reduced hand-breath coordination demands. Emerging niche in COPD populations with compromised inspiratory flow rates.
Volume placements concentrate in Metered Dose Inhalers; the faster expansion belongs to Dry Powder Inhalers.
Technology:
Cost tier stratification separates capital-intensive smart platforms from commoditized conventional systems, with breath-actuated devices occupying a contested middle ground.
- Conventional Inhalation Systems:Mechanical dose counters and basic canister-valve assemblies without electronic components. Emerging markets and cash-pay segments sustain volume.
- Smart Inhalers:Bluetooth-enabled devices with embedded sensors tracking actuation timing, technique quality, and geolocation. Payer value-based contracting in Germany and the United States drives fastest uptake as adherence data satisfies evidence requirements for formulary preference. EMA MDR recertification deadlines accelerate quality system upgrades for connectivity stacks.
- Breath-Actuated Devices:Mechanical triggers releasing dose only upon sufficient inspiratory flow, reducing oropharyngeal deposition. Japan's PMDA streamlined pathways for combination products accelerate local approvals targeting super-aging COPD populations.
- Nebulization Technology:Mesh vibration or compressed air systems for continuous or intermittent aerosol generation. Hospital discharge protocols increasingly favor for severe exacerbation management.
Smart Inhalers command premium positioning; Breath-Actuated Devices capture share fastest among non-connected alternatives.
End User:
Customer type migration from institutional procurement to individual patient channels restructures packaging, training, and reimbursement documentation requirements.
- Hospitals:Central pharmacy distribution with bulk purchasing contracts and formulary committee governance. Volume compression continues as length-of-stay reductions limit inpatient respiratory therapy encounters.
- Homecare Settings:Direct-to-patient delivery with remote monitoring integration and specialty pharmacy coordination. Germany's Apotheken dispensing mandate and United States Medicare Part D coverage expansion drive steepest expansion trajectory. Packaging redesigns accommodate non-clinical storage and self-administration.
- Clinics:Pulmonology and allergy practice sample closets with initial device training. Physician office penetration faces pressure from retail pharmacy vaccination hub conversions.
- Pharmacies:Community and specialty dispensaries with inhaler technique coaching services. Post-pandemic infrastructure investments position for bypassing traditional prescriber gatekeepers.
Placement volumes remain highest in Hospitals; Homecare Settings gain share fastest as reimbursement shifts to ambulatory models.
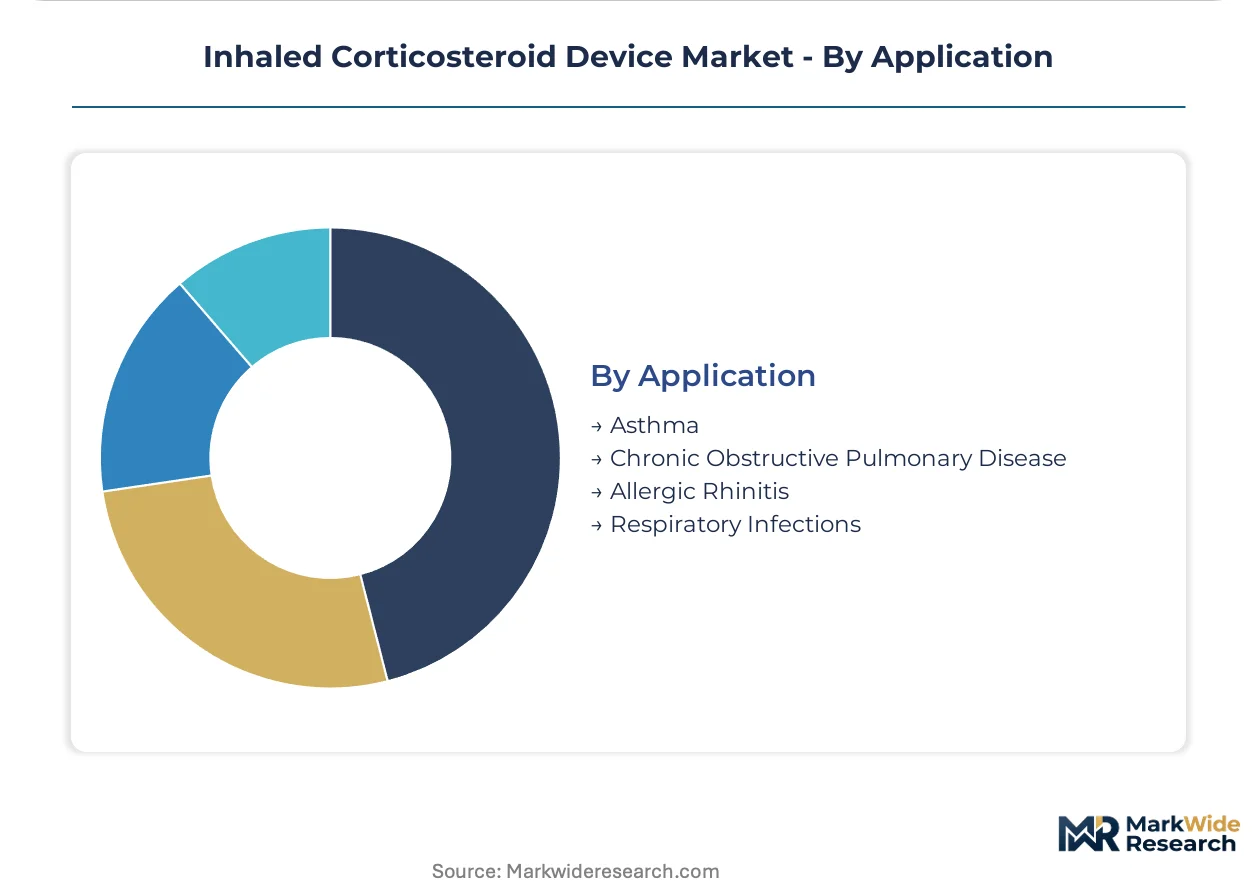
Application:
Disease severity and treatment duration profiles create divergent margin structures across the four indication categories.
- Asthma:Chronic inflammatory airway disease requiring daily controller therapy with periodic rescue escalation. Pediatric and adolescent populations in the United States and Japan sustain largest addressable base.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation with high exacerbation risk and mortality burden. Japan's over-75 demographic concentration and PMDA combination product pathways accelerate device introductions for this segment. Triple therapy combinations drive device complexity.
- Allergic Rhinitis:Upper airway inflammation with seasonal or perennial patterns. Intranasal corticosteroid competition limits inhaler device applicability.
- Respiratory Infections:Acute viral or bacterial processes with short-duration corticosteroid adjunct therapy. Nebulized delivery dominates in hospitalized severe cases.
Asthma maintains volume leadership; Chronic Obstructive Pulmonary Disease expands most quickly on aging demographics and combination therapy uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Switzerland and Germany while consumption tilts toward aging populations in Japan and the United States. Regulatory fragmentation across FDA, EMA, and PMDA jurisdictions forces parallel development tracks that extend commercialization timelines.
United States
Medicare Part D coverage expansion and commercial payer value-based contracting accelerate smart inhaler deployment. FDA bioequivalence requirements for generic alternatives protect branded positions through extended clinical endpoint study mandates. The Research Triangle Park cluster in North Carolina hosts multiple device engineering centers focused on connectivity stack integration.
Germany
Apotheken dispensing mandates concentrate buyer power at pharmacy cooperative levels while EMA MDR recertification deadlines drive quality system upgrades. F-Gas Regulation phase-down schedules force hydrofluoroalkane reformulation investments. Bavaria's medical technology corridor around Munich anchors final assembly operations for breath-actuated platforms.
Japan
PMDA streamlined review pathways for combination products target super-aging COPD populations over 75. METI subsidies for connected health devices reduce patient out-of-pocket costs. The Kansai region around Osaka maintains formulation stability facilities given humidity-sensitive dry powder manufacturing constraints.
Switzerland
Swissmedic's parallel chemical notification pathways attract European manufacturers relocating final assembly to bypass REACH authorization delays. The Basel pharmaceutical cluster leverages proximity to micronized corticosteroid API suppliers. Geneva-based headquarters operations coordinate multi-regulatory submission strategies.
India
CDSCO harmonization with ICH stability guidelines reduces redundant testing for multinational sponsors entering tier-2 and tier-3 cities. The respiratory disease burden among urban populations drives demand for affordable conventional inhalers. Gujarat's pharmaceutical manufacturing zone expands climate-controlled production capacity for export markets.
Inhaled Corticosteroid Device Market Competitive Environment
Top-tier vendors anchor respiratory portfolio breadth through established metered dose and dry powder platforms, while mid-tier specialists compete on breath-actuated delivery innovations. The competitive field stratifies across three archetypes: diversified pharmaceutical conglomerates with device manufacturing captive to drug portfolios, pure-play respiratory specialists with geographic density in European reimbursement channels, and emerging connectivity-focused entrants. Dominant competitive moves include strategic partnerships with sensor technology providers and backward integration into micronized API supply chains.
Among diversified pharmaceutical conglomerates, GlaxoSmithKline, AstraZeneca, and Boehringer Ingelheim occupy positions exemplifying distinct strategic archetypes. GlaxoSmithKline represents the established platform breadth model with decades of physician familiarity sustaining volume leadership. AstraZeneca sits within the next-generation specialization tier, anchoring development of sensor-embedded systems. Boehringer Ingelheim exemplifies geographic density advantages through concentrated European channel relationships.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Pfizer |
| GlaxoSmithKline |
| Chiesi |
| Merck and Co |
| AstraZeneca |
| Novartis |
| Sandoz |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Micronized corticosteroid API costs cascade through device manufacturing tiers, with concentration among three powder suppliers amplifying pricing power at the formulation stage and compressing margins for downstream assembly operations in Germany and Switzerland.
Pricing Analysis
Margin tightening in smart inhaler tiers reflects sensor module premiums and Bluetooth telemetry integration costs that manufacturers struggle to pass through to pharmacy cooperatives in Germany. Three-tier pricing structure across connected, breath-actuated, and conventional mechanical devices separates adherence-data-enabled contracts from basic canister-valve assemblies. Cost-down pressure on generic metered-dose alternatives accelerates because FDA bioequivalence study requirements extend development timelines and erode post-patent exclusivity windows. Cash-pay segments in emerging markets exhibit highest price sensitivity; value-based contracting with United States commercial payers shows lowest.
Supply Chain Analysis
Direct-to-pharmacy channels handle maintenance prescription volumes in Germany, while specialty pharmacy distribution manages smart inhaler deployments for United States Medicare Part D populations. Manufacturing concentration in Switzerland, Germany, and India draws from Indian micronized API production, Swiss precision molding capabilities, and Bavarian breath-actuated assembly expertise. Hydrofluoroalkane propellant chemistry transitions under F-Gas Regulation timelines create single-source vulnerability for validated low-global-warming-potential alternatives. Distribution runs through pharmacy cooperatives in European markets and wholesale-to-retail chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micronized corticosteroid API supply bottlenecks prop device pricing across all tiers, with allocation rationing during pharmaceutical manufacturing surges sustaining margin structures for incumbent powder suppliers.
For Market Incumbents: Lock in backward integration into micronized API production or captive supply agreements with Indian powder manufacturers to defend against generic inhaler sponsors and propellant transition chemistry disruptions. Extend quality management system upgrades ahead of EMA MDR recertification deadlines to preserve European market access and accelerate sensor platform refresh cycles. For New Entrants and Emerging Players: Telehealth platform partnerships offer the lowest-friction patient acquisition route for breath-actuated device introductions targeting Japan's super-aging COPD populations over 75. White-space concentrates in India's tier-2 and tier-3 cities where CDSCO harmonization with ICH guidelines reduces redundant testing burdens for affordable conventional inhaler launches. For Investors and Strategic Acquirers: PMDA streamlined review pathway activations for combination products are the leading indicator that breath-actuated platform specialists warrant acquisition premium positioning. Five-to-ten year viability hinges on connectivity stack differentiation and payer data contract traction; target device manufacturers with validated hospital EHR integration workflows and existing pharmacy chain direct contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Integration | Bluetooth telemetry enables adherence data capture that satisfies German payer evidence requirements for formulary preference. |
| Propellant Chemistry Transition | Low-global-warming-potential hydrofluoroalkane alternatives secure first-mover positioning under F-Gas Regulation phase-down schedules. |
| Direct Pharmacy Contracting | Bypassing wholesale distribution concentrates buyer relationship ownership with Germany's Apotheken cooperatives and United States specialty pharmacies. |
| API Supply Integration | Captive micronized corticosteroid powder production insulates device margins from allocation rationing by Indian and Chinese suppliers. |
| Regulatory Pathway Harmonization | CDSCO alignment with ICH stability guidelines reduces redundant testing for multinational sponsors entering India's tier-2 cities. |
Study Parameters
Independent corroboration across FDA 510(k) filings, EMA MDR submission databases, and PMDA review pathway disclosures underwrites the qualitative findings on regulatory timeline fragmentation. Primary interviews with device engineering directors, regulatory affairs specialists, hospital formulary managers, and pharmacy cooperative procurement leads combined with secondary validation against clinical endpoint study registries and GPO contract databases. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation anchored volume estimates.
Comparable-period anchoring to historical prescription audit data and device shipment disclosures established baseline trajectories across the projection horizon. Segmentation dimensions modeled include device architecture, connectivity tier, propellant chemistry, patient age cohort, and regional regulatory cluster. CAGRs derived from patient population growth, treatment duration extension, and technology substitution curves incorporate Japan's super-aging demographic velocity and United States Medicare Part D coverage expansion as forecast inputs.
The model holds under stable API supply allocation and propellant chemistry transition timelines; deviation in micronized powder production concentration or REACH authorization delays for novel propellant substances would shift volume and value trajectories. Periodic stress-testing of base assumptions against EMA MDR enforcement patterns and FDA bioequivalence study completion rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Arteriosclerosis Detector Market