
 Benign Prostatic Hyperplasia (BPH) Treatment Devices Market | 2026-2036
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
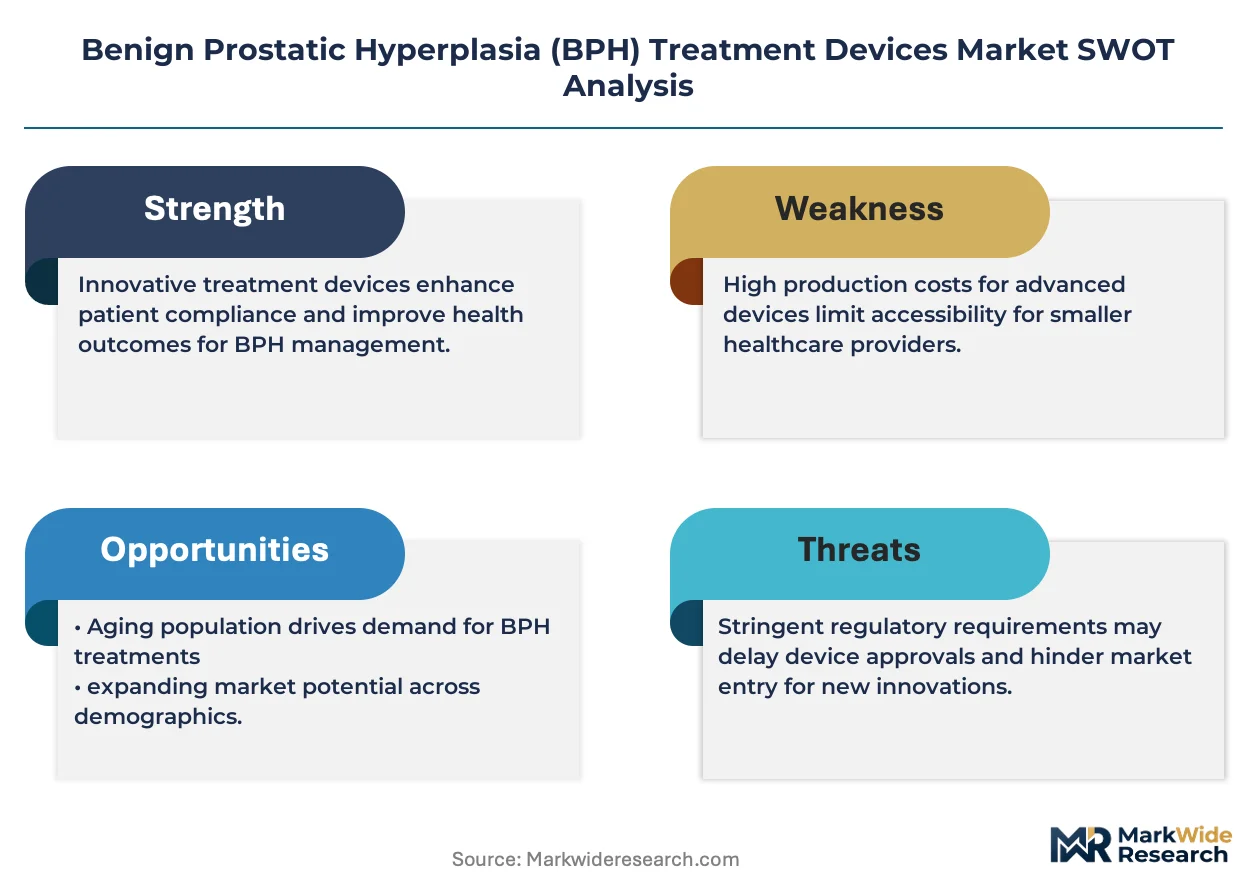
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market Outlook
MDR is expanding compliance burdens for BPH device manufacturers seeking European market access. Boston Scientific Corporation leverages its integrated urology portfolio to sustain reimbursement advantages across hospital networks. Olympus Corporation anchors its competitive position through rigid endoscope manufacturing scale and service infrastructure.
Benign Prostatic Hyperplasia (BPH) treatment devices encompass laser ablation systems, transurethral resection instruments, microwave thermal applicators, and prostatic stents designed to relieve bladder outlet obstruction through tissue removal, vaporization, or mechanical dilation. These instruments typically operate at wavelengths between 532 nm and 2100 nm for laser modalities, with power outputs calibrated to achieve hemostatic control during tissue interaction. Laser ablation dominates procedural volume in urology clinics where outpatient throughput demands rapid patient turnover, while transurethral resection retains margin concentration in hospital settings where capital equipment amortization aligns with higher reimbursement tiers. Microwave therapy occupies a narrowing niche as thermal therapy technology matures and minimally invasive alternatives displace older platforms.
FDA 510(k) clearance pathways shape United States market entry timelines, while MDR technical documentation requirements in Europe extend certification cycles for novel BPH devices. Japan's PMDA enforces Japan Industrial Standards for electromagnetic compatibility that constrain design specifications for imported microwave and laser systems. Stakeholders must monitor reimbursement coding divergence between outpatient surgical centers and hospital-based departments, as site-of-service payment differentials increasingly determine technology procurement decisions.
Market Dynamics
Laser ablation systems are compressing hospital revenue per procedure as outpatient urology clinics capture volume through faster patient turnover and lower facility fees.
Growth Catalysts
- Aging demographics in developed economies:The United States, Germany, and Japan are expanding the addressable patient pool for BPH interventions as median age rises above 45 years.
- FDA 510(k) clearance pathways:Streamlined premarket notification processes accelerate time-to-market for minimally invasive devices compared to PMA routes.
- Holmium laser technology:Wavelength precision at 2100 nm enables hemostatic tissue vaporization with reduced bleeding risk versus traditional transurethral resection.
Market Restraints
- MDR technical documentation requirements:European certification cycles for novel BPH devices extend 18-24 months beyond FDA timelines due to expanded clinical evidence demands.
- Laser fiber consumable costs:Single-use delivery systems represent 15-20% of per-procedure economics, constraining adoption in price-sensitive hospital systems.
- Microwave thermal therapy displacement:Transurethral needle ablation platforms face substitution pressure from laser modalities with superior hemostatic control.
Strategic Opportunities
- Ambulatory surgical center expansion:Site-of-service payment differentials in the United States favor outpatient settings where laser throughput exceeds resection efficiency.
- Photoselective vaporization convergence:532 nm green-light lasers paired with real-time endoscopic guidance reduce catheterization duration versus monopolar resection.
- Japan PMDA electromagnetic compatibility standards:Compliance with JIS C 61000 series creates barrier-protected market entry for certified microwave and laser system manufacturers.
Industry Challenges
- Urologist training bandwidth:Laser ablation proficiency requires 40-60 supervised cases, creating adoption friction in low-volume community practices.
- Reimbursement coding fragmentation:Divergent CPT and HCPCS classifications between hospital outpatient departments and freestanding surgical centers complicate procurement justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign Prostatic Hyperplasia (BPH) Treatment Devices Market |
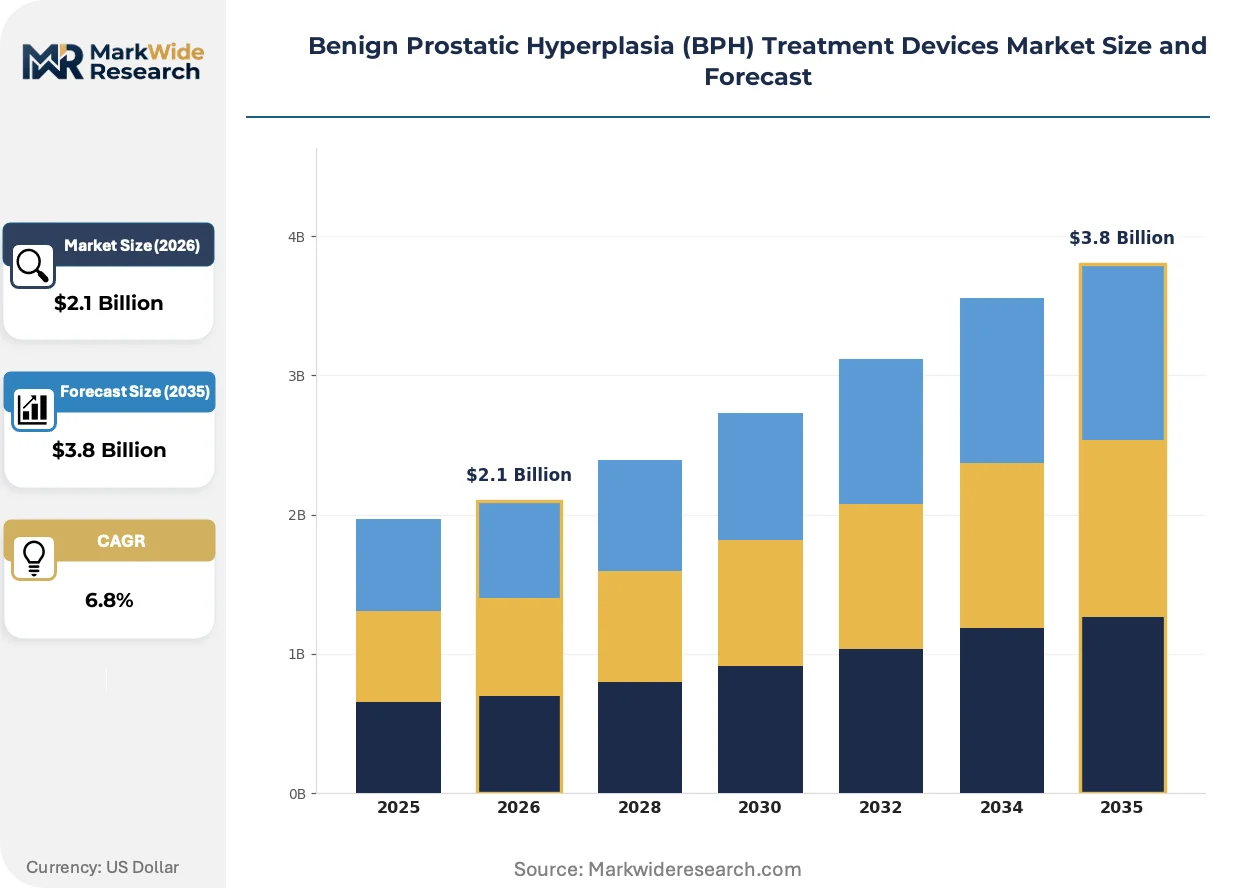
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Ablation, Transurethral Resection, Microwave Therapy, Prostatic Stent Application: Urology Clinics, Hospitals, Outpatient Facilities, Surgical Centers End User: Physicians, Medical Centers, Research Institutions, Home Care Providers Technology: Minimally Invasive, Thermal Therapy, Mechanical Intervention, Biopsy Tools |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Teleflex Incorporated, PROCEPT BioRobotics Corporation, KARL STORZ, biolitec AG, Coloplast Group, Dornier MedTech, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market Strategic Shifts
Device miniaturization and wavelength optimization are redefining procedural economics as manufacturers compete on throughput metrics rather than capital equipment scale alone.
Thulium fiber lasers operating at 1940 nm are electrifying tissue removal efficiency through enhanced water absorption coefficients that reduce vaporization time by 30-40% versus holmium platforms. Urology clinics in the United States are adopting these systems at replacement cycle compression rates of 18-24 months. This wavelength migration is electrifying outpatient capacity expansion as same-day discharge rates approach 95% for appropriately selected patients.
Europe's MDR is mandating post-market surveillance systems with annual safety update reports for all Class IIa and above urological devices. Manufacturers must maintain clinical data registries spanning 5-10 years, elevating compliance costs for smaller laser system producers. German notified bodies are experiencing 12-18 month backlog queues, forcing market entrants to prioritize FDA clearance sequences.
After-sales service unbundling is separating technical support contracts from capital equipment purchases in hospital procurement negotiations. Integrated delivery networks in the United States are demanding à la carte maintenance options with remote diagnostic capabilities replacing on-site engineer visits. This contractual fragmentation is most pronounced in Midwestern health systems where capital budget constraints favor operational expenditure models.
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market Segmentation
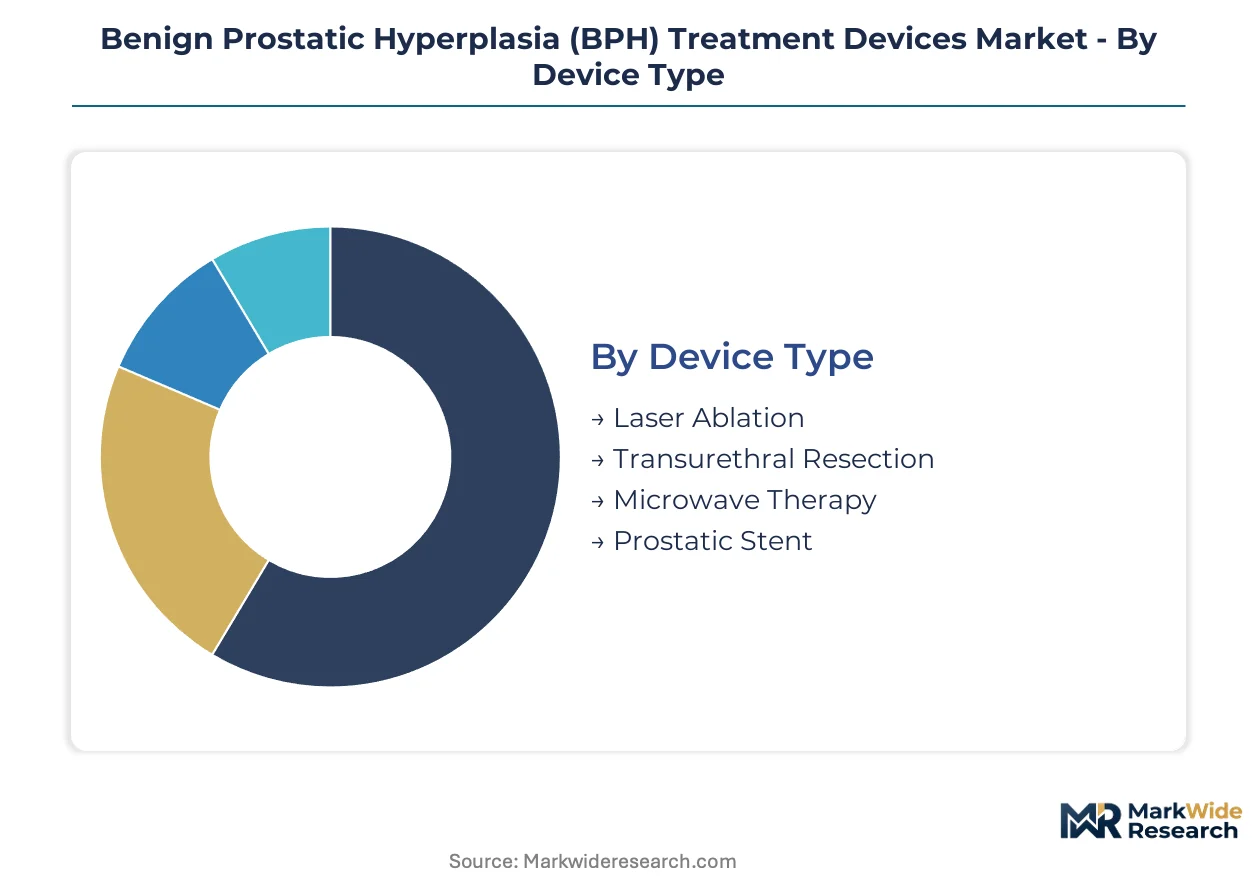
Device segmentation in BPH treatment determines reimbursement pathways and capital deployment cycles. Technology choices cascade through procurement decisions, training requirements, and site-of-service economics.
Device Type:
Laser ablation commands premium pricing while transurethral resection retains procedural volume leadership in hospital networks.
- Laser Ablation:Holmium and thulium fiber systems operate at 2100 nm and 1940 nm wavelengths respectively, enabling hemostatic tissue vaporization with reduced bleeding risk. Demand concentrates in United States urology clinics where outpatient throughput requirements favor rapid patient turnover and same-day discharge protocols.
- Transurethral Resection:Monopolar and bipolar electrosurgical platforms remain the reference standard for gland volumes exceeding 80 mL, leveraging existing capital equipment bases and established reimbursement codes. Hospital-based departments in Germany sustain procurement volumes through integrated service contracts and resident training program requirements.
- Microwave Therapy:Transurethral needle ablation systems deliver thermal energy at 915 MHz for coagulative necrosis in smaller prostates.
- Prostatic Stent:Temporary and permanent mesh devices provide mechanical dilation for patients unsuitable for tissue-removing interventions.
Mature deployment sits with transurethral resection. Newer deployment is concentrated in laser ablation.
Application:
Site-of-service payment differentials are fragmenting procurement authority between integrated delivery networks and independent specialty practices.
- Urology Clinics:Freestanding specialty practices prioritize laser platforms with 18-24 month replacement cycles, optimizing patient throughput through streamlined scheduling and reduced catheterization duration.
- Hospitals:Academic medical centers and community hospitals amortize capital equipment across diverse service lines, sustaining resection platform utilization through bundled payment contracts and emergency backup capacity requirements.
- Outpatient Facilities:Ambulatory surgery centers in United States metropolitan markets exploit site-of-service differentials for commercial payer populations.
- Surgical Centers:Multi-specialty facilities balance BPH case volume against orthopedic and ophthalmology scheduling priorities.
Volume leadership remains with hospitals. Margin expansion is climbing the fastest in urology clinics.
End User:
Procurement authority is decentralizing from hospital supply chains to physician-owned entities and specialty management companies.
- Physicians:Individual urologists and group practices exercise direct capital allocation for in-office laser systems, influenced by case volume thresholds and payer mix composition.
- Medical Centers:Integrated delivery networks standardize device portfolios across affiliated facilities, leveraging purchasing scale for service contract concessions.
- Research Institutions:Academic medical centers in Japan and Germany access investigational device exemptions for wavelength optimization studies and comparative effectiveness trials.
- Home Care Providers:Post-procedure catheter management and patient monitoring services interface with device selection through readmission risk protocols.
Procurement consolidation is advancing in medical centers. Autonomous purchasing is expanding most quickly among physician practices.
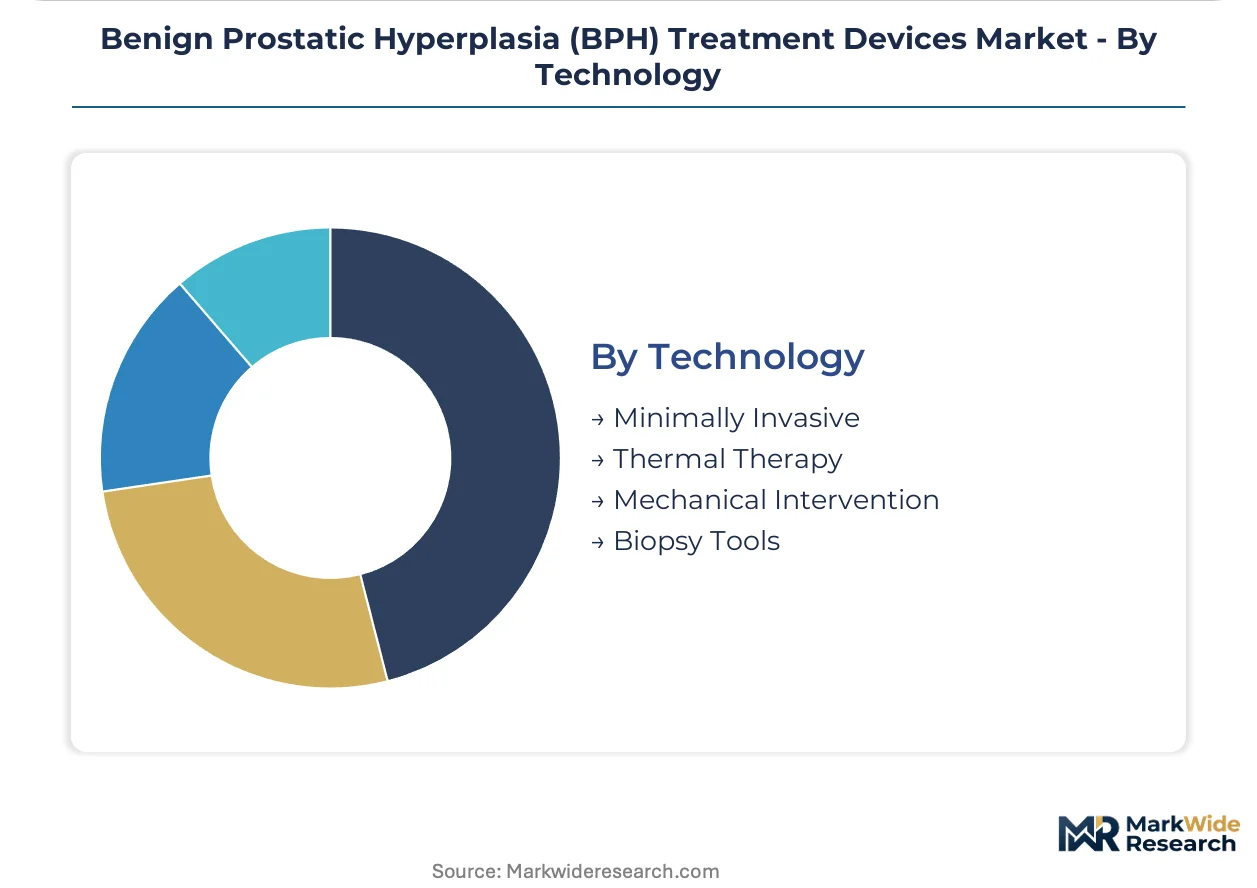
Technology:
Regulatory classification thresholds separate Class IIa from Class IIb pathways, shaping clinical evidence requirements and certification timelines.
- Minimally Invasive:Laser and microwave modalities reduce tissue trauma versus open surgery, aligning with outpatient migration trends and reduced anesthesia requirements.
- Thermal Therapy:Microwave and radiofrequency platforms deliver controlled energy deposition for coagulative tissue destruction, constrained by prostate volume limitations and retreatment rates.
- Mechanical Intervention:Stent deployment and tissue repositioning systems address obstruction without tissue removal, serving high-risk surgical candidates.
- Biopsy Tools:Transrectal ultrasound-guided instruments integrate with BPH diagnostic workflows, influencing downstream treatment device selection through pathology integration.
Technology maturation is complete in thermal therapy. Platform innovation is gaining share fastest in minimally invasive modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate North American manufacturing capacity for minimally invasive urology instruments. These zones attract laser system assembly operations through duty-free component import regimes and FDA-aligned quality infrastructure.
United States
Aging male demographics above 50 years and commercial payer site-of-service differentials drive outpatient clinic expansion. FDA 510(k) clearance pathways accelerate market entry for holmium and thulium laser platforms. Minneapolis-St. Paul anchors Midwestern distribution networks where integrated delivery networks consolidate procurement authority.
Germany
Hospital-based bundled payment contracts and resident training program requirements sustain transurethral resection platform demand. MDR technical documentation mandates and notified body backlogs extend certification cycles 18-24 months beyond FDA timelines. Tübingen and Erlangen host precision manufacturing clusters for rigid endoscope production.
Japan
Super-aging society demographics with median age above 48 years expand addressable patient pools for BPH interventions. PMDA enforces JIS C 61000 electromagnetic compatibility standards that constrain imported microwave and laser system specifications. Tokyo-Osaka corridor concentrates urology clinic networks adopting photoselective vaporization systems.
United Kingdom
NHS England referral-to-treatment targets pressure urology departments toward day-case procedure protocols. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements. Oxford and Cambridge medical technology corridors attract laser system R&D operations seeking proximity to academic medical centers.
China
Rising prostate disease awareness and expanding private hospital networks drive diagnostic and treatment device procurement. NMPA Class II medical device registration requirements mandate domestic clinical trials for imported laser platforms. Suzhou Industrial Park concentrates contract manufacturing for multinational urology device suppliers.
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across capital equipment and consumable segments. Market structure tilts toward consolidated procurement leverage in hospital networks versus fragmented physician-owned clinic purchasing. Three archetypes dominate: integrated surgical portfolio holders, laser technology specialists, and rigid endoscope manufacturers. Capacity expansion and strategic service contract unbundling represent the dominant competitive moves as procurement authority decentralizes.
Within the integrated portfolio tier, Boston Scientific Corporation and Olympus Corporation anchor competitive positioning through bundled urology service offerings and manufacturing scale respectively. KARL STORZ exemplifies the precision endoscope fabrication archetype with German GmbH structure. These three entities occupy positions spanning capital equipment, disposable consumables, and aftermarket technical support infrastructure.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Teleflex Incorporated |
| PROCEPT BioRobotics Corporation |
| KARL STORZ |
| biolitec AG |
| Coloplast Group |
| Dornier MedTech |
| Richard Wolf GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive laser fiber manufacturing in Germany and Japan anchors premium pricing power for integrated device manufacturers while constraining margin flexibility for assembly-only competitors in Mexico and Costa Rica. This vertical integration into single-use consumables allows Boston Scientific and Olympus to bundle service contracts with capital equipment, compressing third-party aftermarket margins across hospital procurement negotiations.
Pricing Analysis
Short lead-time premiums for holmium laser fibers command 12-15% markups over standard delivery schedules in United States urology clinics facing urgent replacement cycles. Contract-based long-term offtake agreements dominate hospital purchasing, with price differentiation resting on FDA 510(k) clearance tier and ISO 13485 certification status. Pricing pressure stems from ambulatory surgery center expansion demanding stripped-down service bundles without technical support. Physician-owned practices exhibit highest price sensitivity, while integrated delivery networks leverage volume scale for concession extraction.
Supply Chain Analysis
Direct-to-hospital channels handle capital equipment demand from academic medical centers, while distributor-mediated pathways serve community urology clinics. Manufacturing concentrates in Germany, Japan, and United States for precision laser resonator assemblies, drawing from specialized rare-earth element suppliers and polished sapphire crystal foundries. Single-source vulnerability in thulium-doped fiber supply from Chinese rare-earth processors creates tariff exposure risk. Distribution runs through specialized medical device logistics providers with cold-chain capabilities for temperature-sensitive optical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDR compliance cost escalation is compressing viable participant counts, forcing sub-scale laser system manufacturers toward strategic exit or acquisition. Consolidation pressure intensifies as notified body backlogs extend certification timelines beyond cash runway thresholds.
For Market Incumbents: Deploy service contract unbundling to capture ambulatory surgery center demand without capital equipment discounting. Acquire thulium fiber laser specialists before wavelength migration accelerates replacement cycles. Lock in GPO purchasing agreements ahead of hospital network consolidation waves. For New Entrants and Emerging Players: The premium-economy price-point gap in refurbished holmium systems creates white-space opportunity in Midwestern United States community hospitals. Target independent urology practices in Japan's Tokyo-Osaka corridor where PMDA electromagnetic compatibility barriers protect certified entrants. Pursue software companion development for real-time endoscopic guidance as differentiated entry vector. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medtech conglomerates seeking urology portfolio fill-in. Five-to-ten year viability hinges on wavelength platform ownership rather than distribution relationships. Watch for thulium fiber laser adoption inflection in United States outpatient settings as signal for incumbent displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Extended certification timelines from German notified bodies force early filing sequences for European market retention. |
| Thulium Fiber Laser Platform Launch | 1940 nm wavelength systems reduce vaporization time versus holmium, capturing outpatient clinic replacement demand. |
| Hospital System Partnership | Bundled payment contracts with United States integrated delivery networks secure procedural volume commitments. |
| Reimbursement Strategy | CPT code optimization for site-of-service differentials drives ambulatory surgery center procurement decisions. |
| Software Companion Development | Real-time endoscopic guidance integration enhances photoselective vaporization precision and reduces training burden. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with urology clinic administrators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, PMDA approval registries, and European MDR notified body certificates provided device-specific certification timelines. Bottom-up procedural volume estimates triangulated against top-down capital equipment shipment data from German and Japanese trade associations.
Data-stream reconciliation across manufacturer shipment reports, hospital procurement databases, and ambulatory surgery center licensing records validated segmentation outputs. The analytical framework modeled device type, application site, end-user category, and technology modality across the projection horizon. CAGRs derived from fitted trend lines against demographic projections and reimbursement schedule adjustments. Laser fiber replacement cycle compression and outpatient migration velocity served as industry-specific forecast inputs.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time ambulatory surgery center transaction data introduce uncertainty bands around outpatient volume estimates. Forecasts reflect assumptions regarding MDR implementation pace and site-of-service payment differential stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Meniscal Rasps Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Silastic Implant Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market