
 Gastric Space-Occupying Devices Market | 2026-2036
Gastric Space-Occupying Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Gastric Space-Occupying Devices Market Foresight
Recurring maintenance and retrieval scheduling is hardening into a core revenue pillar alongside device placement itself. Apollo Endosurgery anchors its portfolio around comprehensive patient management programs that extend beyond implantation. Allurion Technologies differentiates through remote monitoring subscriptions that sustain engagement across treatment cycles. Obalon Therapeutics competes on physician training infrastructure and specialized deployment support rather than hardware alone.
Gastric space-occupying devices are implantable or insertable systems—typically silicone-based balloons or collapsible structures measuring 400–700 mL when deployed—that transiently reduce gastric volume to induce early satiety and restrict caloric intake. Intragastric balloons dominate current placement volumes while adjustable balloon systems command premium positioning due to their tunable fill volumes and extended dwell times. Fluid-filled configurations lead the product mix where physician familiarity and established retrieval protocols concentrate margin pools, whereas gas-filled alternatives are gaining fastest adoption in ambulatory settings seeking reduced patient discomfort profiles.
The FDA's Breakthrough Device designation pathway and the EU MDR's tightened clinical evidence requirements for temporary implantables are elevating barriers to market entry while favoring established manufacturers with robust quality management systems. Reimbursement volatility across Medicare Advantage plans and national health systems in Germany and France directly shapes provider willingness to adopt newer deployment modalities. Stakeholders must weigh regulatory capital intensity against the narrowing window for first-mover positioning in next-generation adjustable and bioabsorbable formats.
Market Dynamics
The shift from hardware-only sales to integrated patient management subscriptions is restructuring revenue architecture across manufacturers, forcing incumbents to build software capabilities and recurring billing infrastructure alongside balloon production.
Growth Catalysts
- Expanded Medicare Advantage coverage:United States payers are adding endoscopic weight-loss procedures to supplemental benefit packages, unlocking ambulatory surgical center demand.
- EU MDR harmonization:Centralized clinical evidence requirements for temporary implantables are streamlining multi-country market access for compliant manufacturers.
- Silicone elastomer advances:Improved burst resistance and thinner wall profiles enable longer dwell times without compromising retrieval safety.
Market Restraints
- Reimbursement volatility:German statutory health insurance deliberations on intragastric balloon coding create payment uncertainty for providers.
- Physician training bottlenecks:Specialized endoscopic deployment certification requirements limit addressable operator pools in concentrated metropolitan markets.
- Biocompatible polymer supply concentration:Medical-grade silicone sourcing depends on a narrow base of European and North American chemical suppliers.
Strategic Opportunities
- Japan's aging obesity demographic:METI incentives for minimally invasive metabolic interventions create favorable regulatory tailwinds for balloon system entrants.
- Remote patient monitoring integration:Convergence of ingestible sensors with mobile health platforms enables real-time compliance tracking and adverse event prediction.
- Direct-to-employer contracting:Self-insured corporations in the United States are piloting bundled bariatric device programs outside traditional payer channels.
Industry Challenges
- Post-market surveillance infrastructure:FDA's strengthened long-term safety tracking mandates for temporary implantables demand costly registry participation and data management systems.
- Cross-functional talent scarcity:Manufacturers struggle to recruit professionals combining endoscopic clinical expertise with connected device software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastric Space-Occupying Devices Market |
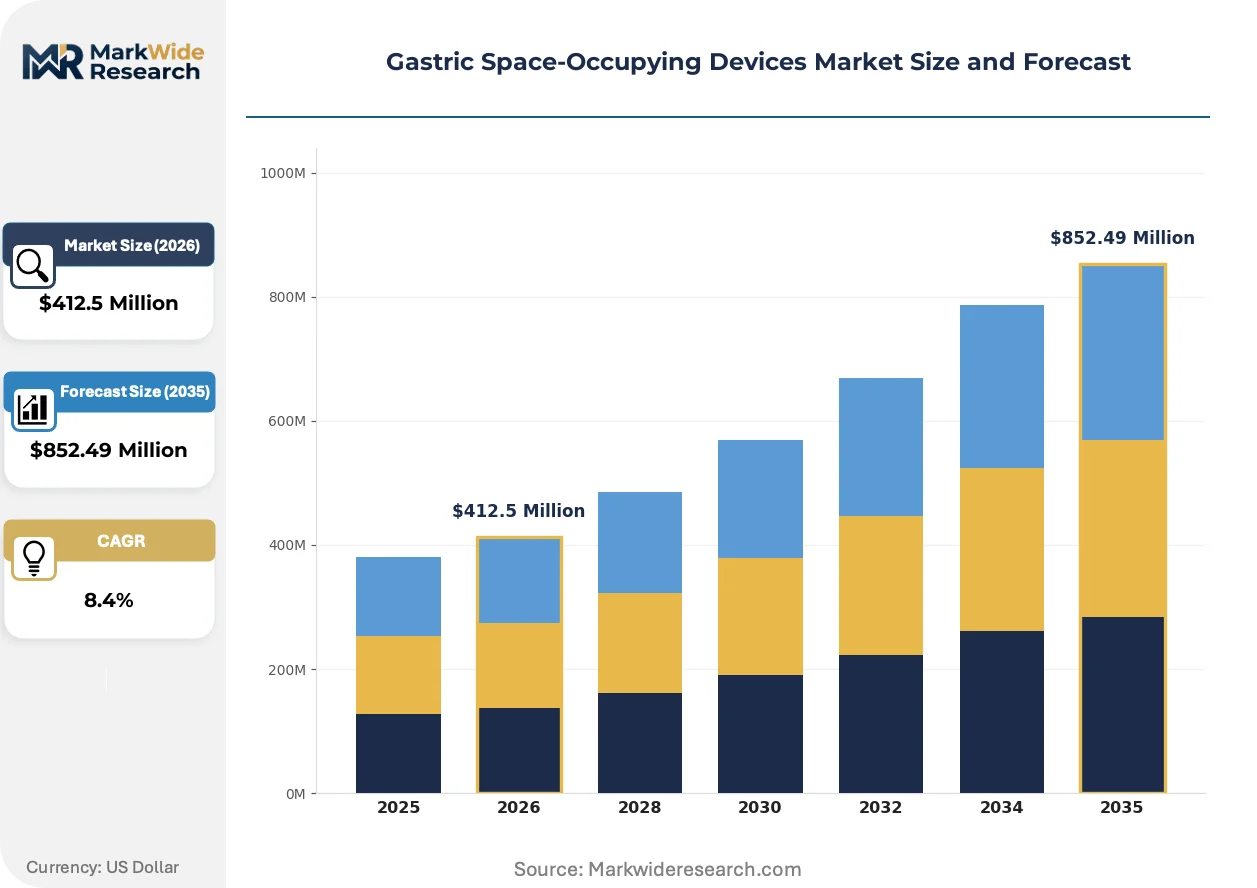
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intragastric Balloons, Endoscopic Devices, Adjustable Balloons, Fluid-Filled Balloons, Gas-Filled Balloons Therapy Area: Weight Management, Obesity Treatment, Metabolic Disorders, Diabetes Care, Bariatric Surgery Alternatives End User: Clinics, Ambulatory Surgical Centers, Obesity Treatment Centers, Medical Wellness Facilities, Gastroenterology Practices Deployment Type: Endoscopic, Minimally Invasive, Non-Surgical, Temporary, Removable |
| Companies Covered | Apollo Endosurgery, Allurion Technologies, Obalon Therapeutics, ReShape Medical, Spatz Medical, Helioscopie, Endalis, MEDSIL, Lexel Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastric Space-Occupying Devices Market Shifts & Advancements
Device architecture is pivoting from passive volume occupation toward active physiological monitoring, with embedded sensors and programmable fill mechanisms transforming balloons into data-generating therapeutic platforms.
Adjustable fluid-filled systems is overtaking fixed-volume balloons in premium placement segments. Academic medical centers in the United States and Germany are prioritizing tunable dwell-time protocols that match individual patient tolerance profiles. This capability compression is collapsing the historical distinction between temporary and semi-permanent bariatric interventions.
REACH substance restrictions on certain phthalate plasticizers are compelling silicone formulation changes across European supply chains. Manufacturers serving EU markets are accelerating alternative catalyst chemistry validation to maintain MDR compliance timelines. Fluid-filled balloon categories face the most intensive reformulation burden given direct patient contact duration.
Ambulatory surgical centers are consolidating purchasing decisions through group purchasing organizations that unbundle device procurement from mandatory training packages. This channel rationalization pressures manufacturers to compete on hardware margins alone while recovering service revenue through separate subscription structures. The United States exhibits the fastest procurement model transformation, with multi-state ASC networks standardizing on single-vendor platforms.
Gastric Space-Occupying Devices Market Segmentation
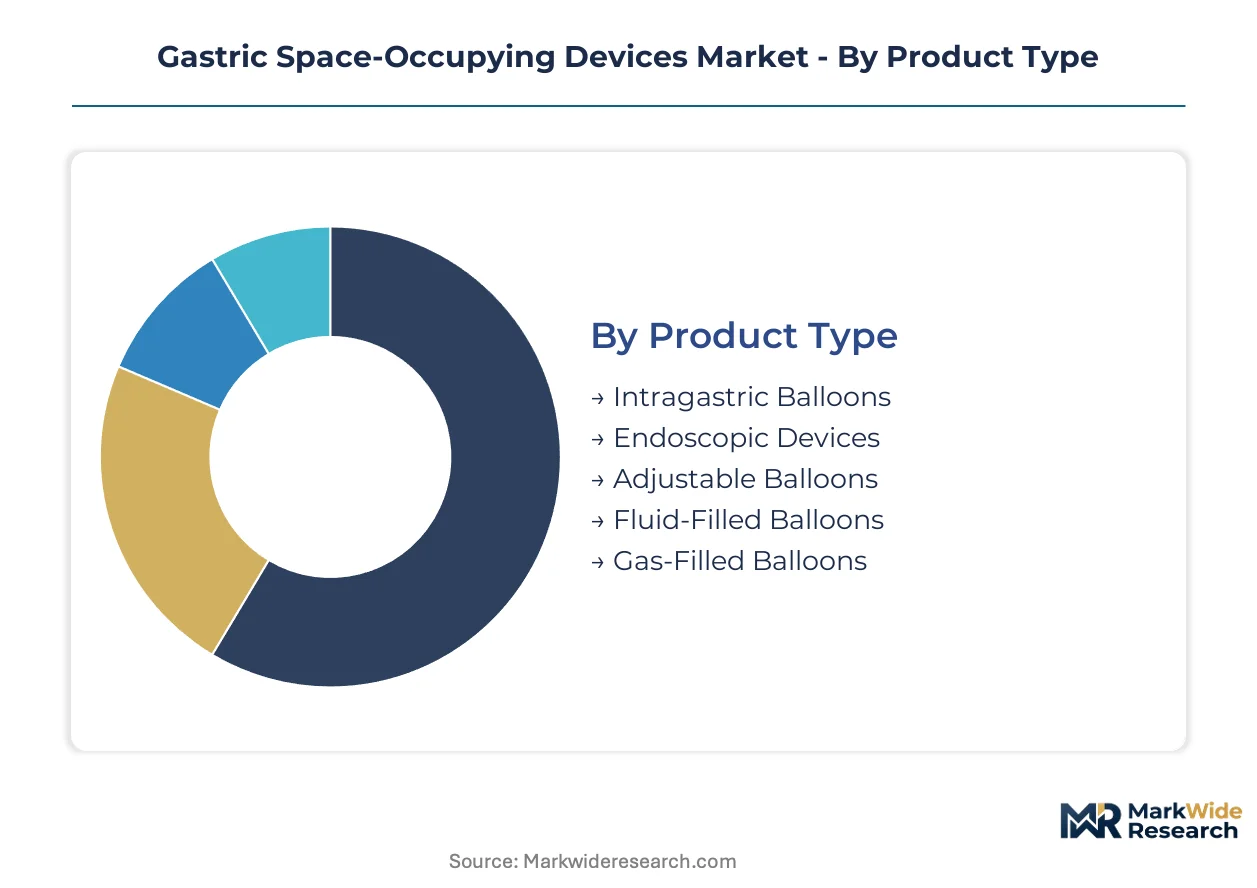
Device categorization in the gastric space-occupying market reveals divergent clinical workflows and reimbursement pathways. Product architecture, therapy positioning, and deployment setting each shape purchasing decisions and margin structures differently.
Product Type:
Customization intensity varies from off-the-shelf balloons to physician-tunable systems requiring specialized training infrastructure.
- Intragastric Balloons:Silicone elastomer spheres deployed endoscopically and filled with saline or gas to occupy 400-700 mL gastric volume. Demand clusters in United States ambulatory surgical centers where Medicare Advantage coverage expansion is accelerating procedure volume.
- Adjustable Balloons:Systems with tunable fill volumes and extended dwell protocols that collapse the distinction between temporary and semi-permanent interventions. German academic medical centers prioritize these for individualized tolerance matching, though REACH substance restrictions on phthalate plasticizers are forcing silicone reformulation.
- Endoscopic Devices:Delivery and retrieval systems enabling placement without laparoscopy.
- Fluid-Filled Balloons:Saline-based configurations with established retrieval protocols and concentrated margin pools.
- Gas-Filled Balloons:Air or nitrogen-filled alternatives reducing post-placement discomfort in outpatient settings.
Leading the category by volume: Intragastric Balloons. Expanding most quickly: Adjustable Balloons.
Therapy Area:
Clinical indication breadth stretches from lifestyle-managed weight reduction to presurgical metabolic preparation.
- Weight Management:Non-surgical caloric restriction for patients with BMI 30-40 seeking reversible intervention. United States employer-sponsored wellness programs are piloting bundled balloon programs outside traditional payer channels.
- Obesity Treatment:Structured protocols for BMI thresholds requiring documented comorbidity management. France and Germany face statutory insurance coding uncertainty that constrains provider adoption despite clinical efficacy.
- Metabolic Disorders:Insulin resistance and prediabetes intervention.
- Diabetes Care:Adjunct therapy for glycemic control in type 2 patients.
- Bariatric Surgery Alternatives:Bridge therapy or permanent substitute for surgical candidates.
Obesity Treatment commands the largest absolute placement volume. Bariatric Surgery Alternatives is gaining share fastest as ambulatory centers seek non-invasive options.
End User:
Facility type determines procurement complexity, from single-physician practices to multi-state purchasing networks.
- Ambulatory Surgical Centers:High-volume outpatient settings consolidating purchasing through group purchasing organizations that unbundle device procurement from training packages. United States multi-state ASC networks are standardizing on single-vendor platforms.
- Obesity Treatment Centers:Specialized metabolic facilities integrating remote patient monitoring with implantable devices. These centers sustain engagement through subscription-based patient management programs extending beyond implantation.
- Clinics:General practice settings with limited endoscopic capability.
- Medical Wellness Facilities:Lifestyle-focused centers emphasizing holistic intervention.
- Gastroenterology Practices:Physician groups with established endoscopic infrastructure.
Ambulatory Surgical Centers dominate procurement volume. Obesity Treatment Centers are climbing the fastest as integrated care models expand.
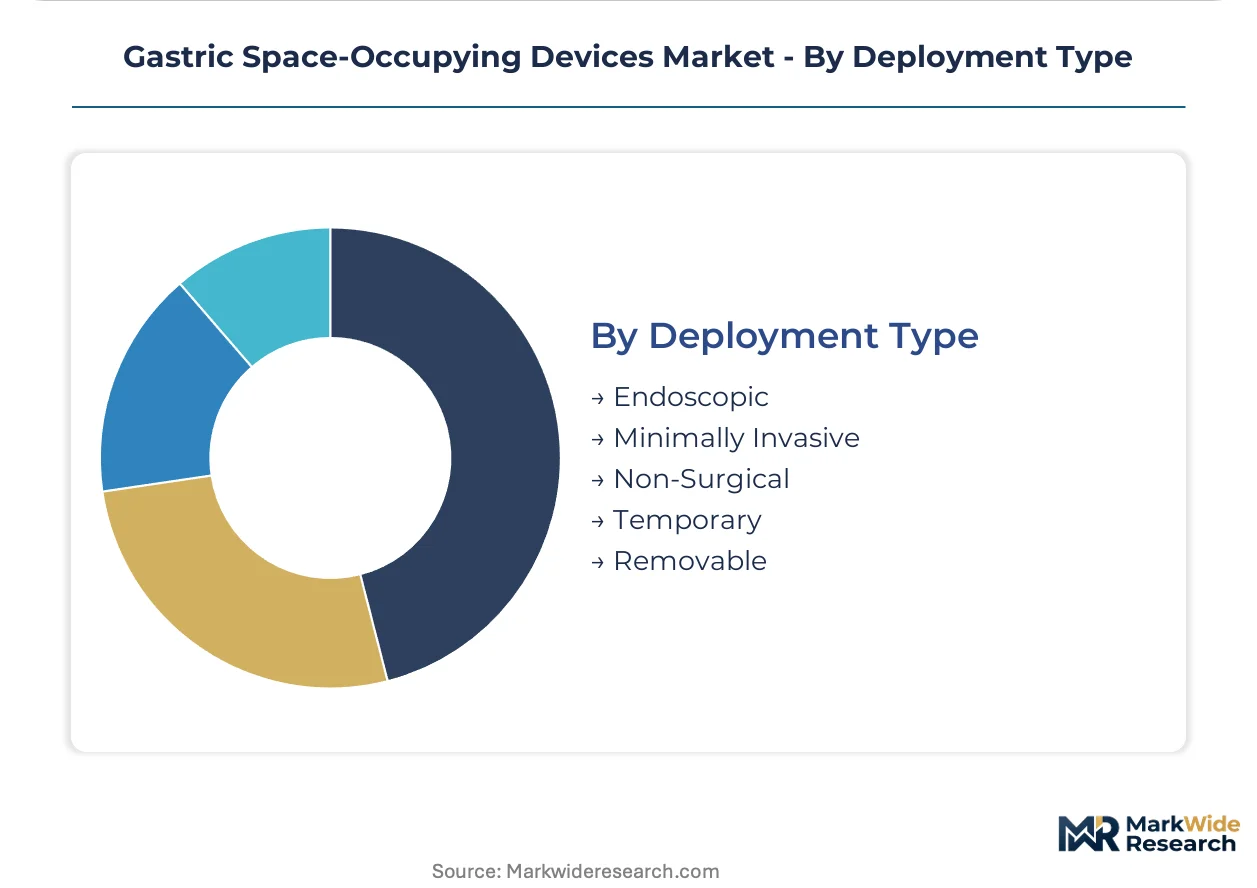
Deployment Type:
Technical invasiveness spectra range from fully endoscopic to ingestible self-deploying systems.
- Endoscopic:Placement and retrieval via gastroscopy requiring specialized operator certification. Physician training bottlenecks limit addressable operator pools in concentrated United States metropolitan markets.
- Minimally Invasive:Reduced-trauma approaches between endoscopic and surgical extremes. Japan's METI incentives for minimally invasive metabolic interventions are creating favorable regulatory tailwinds for these system formats.
- Non-Surgical:Procedures avoiding any incision or scope.
- Temporary:Defined dwell time with mandatory retrieval protocol.
- Removable:Systems designed for extraction without tissue integration.
Endoscopic deployment leads by procedure count. Minimally Invasive approaches are gaining share fastest as tunable systems extend dwell flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in European and North American chemical supply corridors, while procedure volume tilts toward United States ambulatory networks and German academic medical centers. Consumption patterns diverge sharply between mature reimbursement markets and emerging self-pay segments.
United States
Medicare Advantage plans are adding endoscopic weight-loss procedures to supplemental benefits, accelerating demand at multi-state ambulatory surgical center networks. FDA's Breakthrough Device designation pathway elevates clinical evidence requirements for temporary implantables. Texas and Florida ASC clusters are standardizing on single-vendor platforms that unbundle hardware procurement from mandatory training.
Germany
Statutory health insurance deliberations on intragastric balloon coding create payment uncertainty despite strong clinical adoption. REACH substance restrictions on phthalate plasticizers are forcing silicone formulation changes across medical-grade supply chains. Baden-Württemberg academic centers prioritize adjustable balloon systems with tunable dwell-time protocols.
France
ANSM oversight of temporary implantables aligns with EU MDR harmonization, streamlining multi-country market access for compliant manufacturers. Obesity treatment centers in Paris and Lyon integrate remote patient monitoring with implantable devices through subscription-based engagement programs. Reimbursement volatility constrains provider willingness to adopt newer deployment modalities.
Japan
METI incentives for minimally invasive metabolic interventions create favorable regulatory tailwinds for balloon system entrants. PMDA's evolving guidance on temporary implantable devices is reshaping post-market surveillance obligations for manufacturers. Tokyo and Osaka medical clusters are piloting ingestible self-deploying systems in employer-sponsored wellness programs.
United Kingdom
NHS England's specialized commissioning frameworks for bariatric services channel demand toward established endoscopic protocols. MHRA alignment with EU MDR clinical evidence requirements maintains regulatory continuity for European supply chains. London and Manchester obesity treatment centers are consolidating purchasing decisions through group purchasing organizations.
Gastric Space-Occupying Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the gastric space-occupying device landscape. The vendor base separates into integrated manufacturers controlling silicone formulation and retrieval system production versus specialists outsourcing balloon fabrication to medical-grade polymer foundries. Three archetypes dominate: comprehensive patient management platforms, hardware-focused device suppliers, and remote monitoring subscription providers. M&A activity concentrates on software capability acquisition and geographic expansion into Japanese and German reimbursement markets.
Within the comprehensive patient management tier, Apollo Endosurgery anchors integrated care models extending beyond implantation, while Allurion Technologies exemplifies remote monitoring subscription architectures. Obalon Therapeutics occupies a position emphasizing physician training infrastructure rather than hardware differentiation alone. These three represent divergent strategic bets on whether recurring service revenue or device margin capture will dominate next-generation competitive positioning.
| Leading Market Players |
|---|
| Apollo Endosurgery |
| Allurion Technologies |
| Obalon Therapeutics |
| ReShape Medical |
| Spatz Medical |
| Helioscopie |
| Endalis |
| MEDSIL |
| Lexel Medical |
| Others |
Supply & Pricing Matrix
Group purchasing organization consolidation across United States ambulatory surgical centers is stripping away bundled training revenue and forcing manufacturers to recover service value through separate subscription structures, compressing hardware margins while elevating the importance of recurring patient management contracts.
Pricing Analysis
Margin tightening in fluid-filled balloon tiers reflects unbundled procurement contracts that separate device acquisition from mandatory physician certification programs. Three-tier pricing structure across premium adjustable systems, standard fixed-volume balloons, and economy gas-filled alternatives stratifies by dwell-time flexibility and retrieval protocol complexity. Cost-down pressure on standard-tier SKUs accelerates because GPOs now mandate volume-based rebates exceeding historical levels. Ambulatory surgical centers exhibit highest price sensitivity while academic medical centers in Germany tolerate premium positioning for tunable systems.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements gate entry for medical-grade silicone compounders, concentrating qualified supply among German, Swiss, and select North American specialty chemical producers. Device fabrication draws from platinum-cured silicone elastomers, retrieval catheter assemblies, and endoscopic delivery sheaths. Single-source vulnerability persists for platinum catalyst supply amid REACH substance restrictions on legacy phthalate plasticizers. Distribution runs through manufacturer-direct sales to hospital systems and specialized obesity treatment centers, with emerging GPO intermediation in United States ASC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
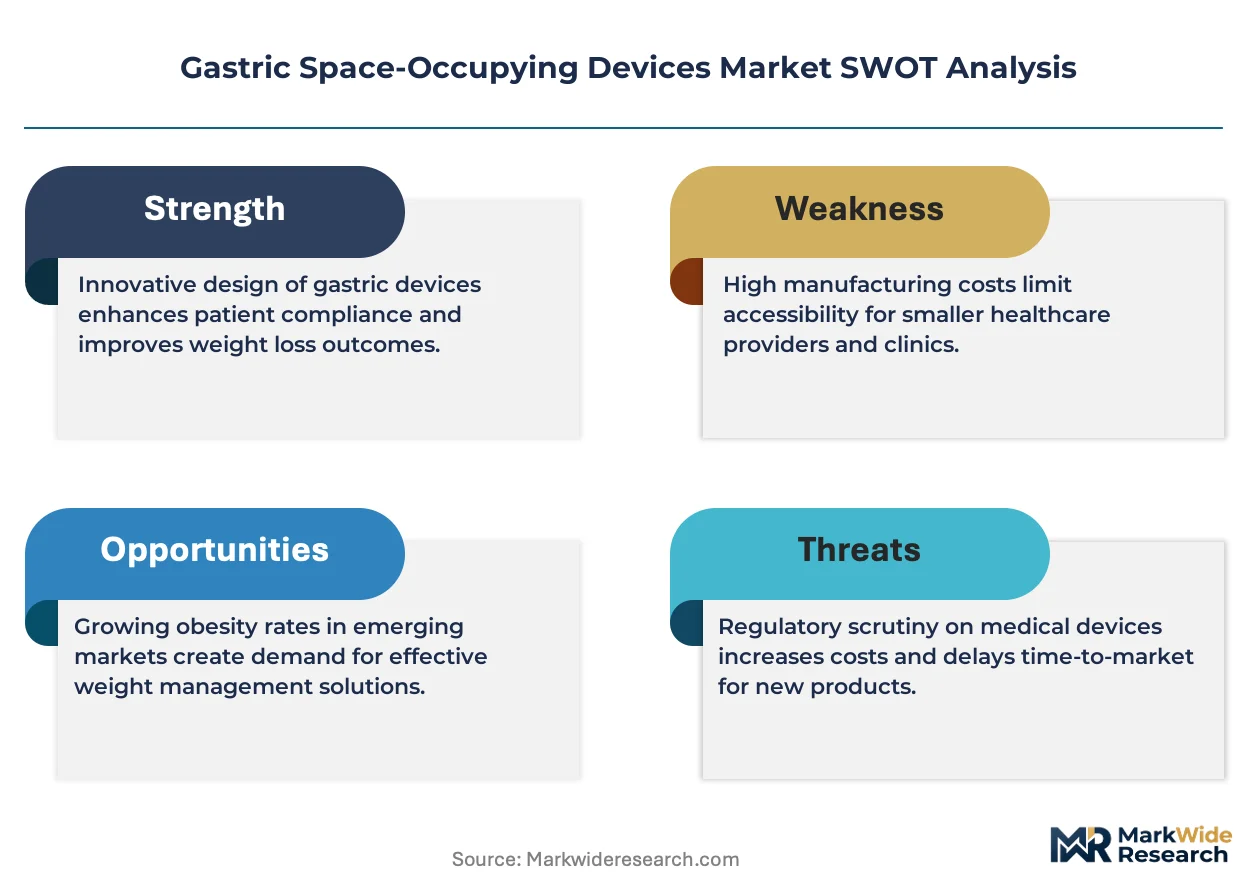
This market operates as a cost-of-compliance story where EU MDR clinical evidence requirements and FDA post-market surveillance mandates erect barrier-to-entry moats favoring manufacturers with established quality management systems and registry participation infrastructure.
For Market Incumbents: Deepen backward integration into platinum-cured silicone formulation to secure supply continuity amid REACH-driven catalyst transitions. Fortify patient management subscription platforms against emerging remote-monitoring specialists by embedding ingestible sensor partnerships directly into device architecture. Consolidate GPO relationship management through dedicated contracts teams addressing multi-state ASC network standardization trends. For New Entrants and Emerging Players: Capture Japan's employer-sponsored wellness pilot programs before METI incentive windows mature into established reimbursement codes. Exploit physician training infrastructure gaps in concentrated United States metropolitan markets where endoscopic certification bottlenecks limit incumbent capacity expansion. Lead with ingestible self-deploying systems that circumvent capital-intensive endoscopic delivery ecosystem requirements. For Investors and Strategic Acquirers: The window for entry favors software-enabled patient management platforms over pure hardware manufacturers given recurring revenue visibility and higher exit multiples. Long-term viability hinges on regulatory compliance infrastructure rather than device innovation alone. Monitor FDA Breakthrough Device designation awards as inflection signals for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Buildout | Centralized technical documentation accelerates multi-country market access for compliant manufacturers. |
| Remote Patient Monitoring Integration | Sensor-embedded balloons transform passive devices into data-generating therapeutic platforms. |
| GPO Contract Consolidation | Multi-state ASC networks standardizing on single-vendor platforms reshape procurement leverage. |
| Silicone Formulation Reformulation | Alternative catalyst chemistry validation maintains MDR compliance amid REACH phthalate restrictions. |
| Direct-to-Employer Contracting | Self-insured corporations pilot bundled bariatric programs outside traditional payer channels. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineers underwrites the qualitative findings in this analysis. Primary fieldwork engaged regulatory affairs leads at temporary implantable device manufacturers and endoscopic specialists at academic medical centers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare Advantage supplemental benefit announcements, and hospital procurement system records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Rate-of-change decomposition across the projection horizon segments volume and value by product architecture, therapy positioning, deployment setting, and geographic reimbursement cluster. Modeled dimensions include intragastric versus adjustable balloon systems, fluid-filled versus gas-filled configurations, ambulatory surgical center versus obesity treatment center procurement, and United States Medicare Advantage versus European statutory insurance coverage patterns. CAGRs derived from procedure volume trajectories adjusted for reimbursement policy elasticity and physician training capacity constraints.
The model holds under stable regulatory enforcement intensity and silicone supply continuity; deviation in FDA post-market surveillance mandate expansion or REACH substance restriction acceleration would shift volume assumptions materially. A model refresh is warranted upon material change in Medicare Advantage endoscopic weight-loss coverage determination or EU MDR notified body capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Guidewires Market
Medical Devices
Microdebrider Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Telehealth Device Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Breast Pump Flange Market