
 Germany Ophthalmic Devices Market | 2026-2036
Germany Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Ophthalmic Devices Market Foresight
Ophthalmic technician training capacity is rotating toward minimally invasive surgical platforms and advanced imaging modalities, tightening labor supply for conventional device servicing. Carl Zeiss Meditec AG leverages its Jena manufacturing base to sustain precision optics leadership across diagnostic and surgical portfolios. Alcon Inc anchors premium intraocular lens production through its German distribution infrastructure, while HAAG-Streit Group competes in slit lamp instrumentation with specialized Swiss-German engineering heritage.
Ophthalmic devices encompass precision instruments for ocular examination, surgical intervention, and vision correction, typically incorporating optical assemblies with micrometer-scale alignment tolerances, biocompatible materials, and software-driven diagnostic algorithms to detect refractive errors and pathological changes. These systems serve clinical decision-making in anterior and posterior segment disease management across outpatient and inpatient settings. Imaging systems dominate capital expenditure budgets among ophthalmology clinics, while surgical instruments capture concentrated margin pools tied to procedure volume growth. Diagnostic devices extend reach into community-based screening programs, and vision testing equipment occupies a mature replacement cycle position within eye hospitals.
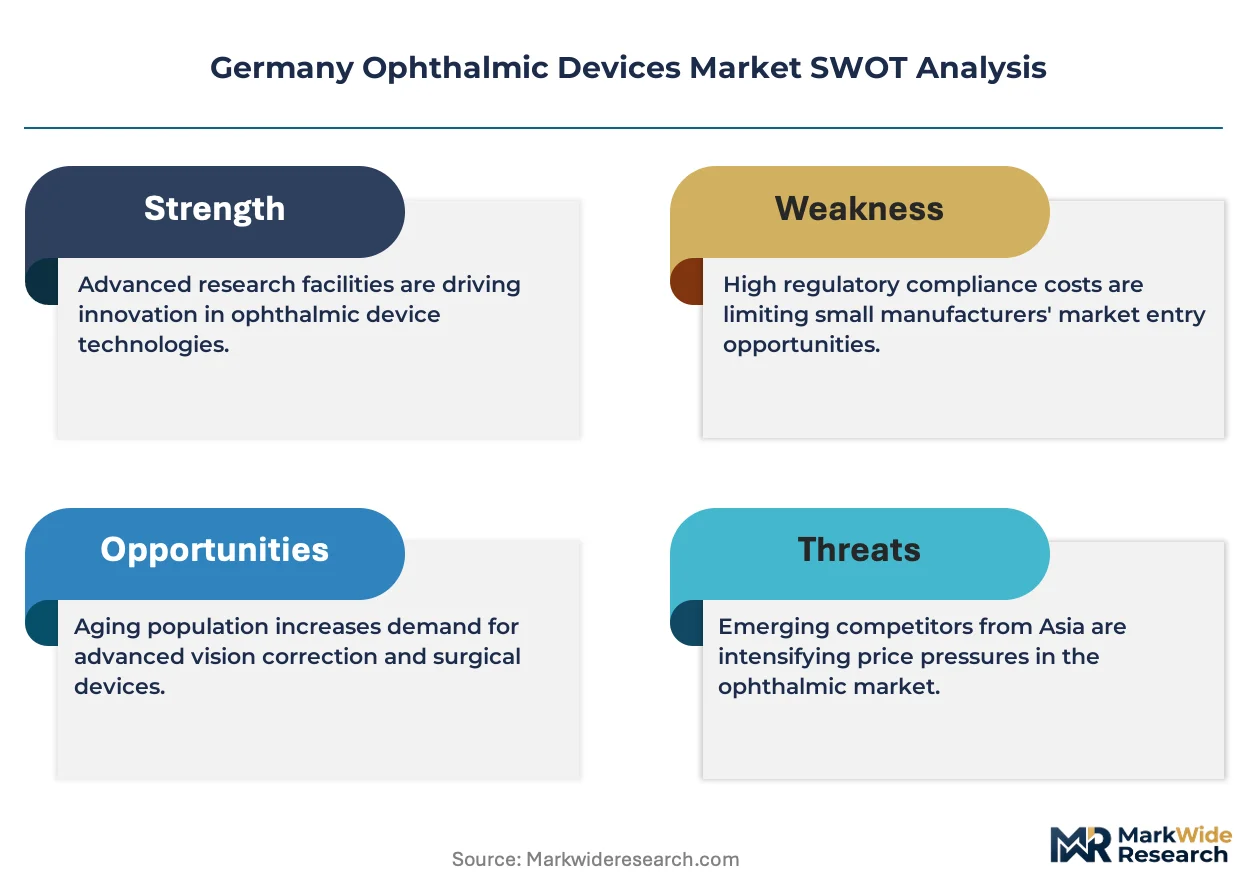
Germany's national implementation of the EU Medical Devices Regulation through BfArM oversight elevates clinical evidence requirements for market authorization, compressing timelines for legacy product transitions. CE marking conformity, ISO 13485 quality management, and KBA-notified body assessments structure competitive access thresholds for domestic and imported equipment. Stakeholders must monitor reimbursement pathway negotiations between statutory health insurers and device manufacturers, as these agreements determine adoption velocity for premium technology tiers.
Market Dynamics
BfArM's MDR enforcement timeline compresses conformity assessment windows for legacy ophthalmic devices, forcing manufacturers to accelerate clinical evidence generation while ambulatory surgery centers front-load capital expenditure on diagnostic suites ahead of reimbursement negotiations.
Growth Catalysts
- EU Medical Devices Regulation (MDR):BfArM's tightened oversight elevates clinical evidence standards, creating competitive moats for manufacturers with robust quality management systems and accelerating replacement cycles for non-compliant legacy equipment.
- Ambulatory surgery centers:Bavarian and Baden-Württemberg outpatient facilities are expanding procurement of integrated diagnostic-surgical suites to capture shifting reimbursement incentives favoring same-day procedures.
- Femtosecond laser platforms:Precision corneal incision technology is penetrating cataract workflows in German university hospitals, reducing phacoemulsification time and expanding addressable procedure volumes.
Market Restraints
- Optical-grade germanium supply:Concentration of raw material refining in East Asian supply chains exposes German manufacturers to input cost volatility and export control friction affecting thermal imaging components.
- Notified body capacity:KBA and other EU-recognized conformity assessment bodies face persistent backlogs for Class III ophthalmic device reviews, extending time-to-market for novel surgical platforms.
- Reimbursement compression:Statutory health insurer negotiations with device manufacturers impose pricing ceilings on premium intraocular lens tiers, constraining margin expansion for differentiated products.
Strategic Opportunities
- AI-integrated diagnostic imaging:Machine learning algorithms for diabetic retinopathy screening present white space in German community health networks, with regulatory pathways clarifying under EU AI Act risk classification frameworks.
- Tele-ophthalmology infrastructure:Rural Bavarian and Saxon regions remain underpenetrated by specialist ophthalmology services, creating demand for remote diagnostic platforms that interface with primary care workflows.
- Reusable instrument reprocessing:MDR sustainability requirements and hospital cost pressures are converging to favor centralized sterilization services for high-value surgical instruments, displacing single-use alternatives.
Industry Challenges
- Precision optics technician scarcity:German vocational training capacity for micrometer-scale optical assembly lags demand from diagnostic device manufacturers, extending production lead times for wavefront aberrometers.
- Legacy software validation:MDR cybersecurity annex requirements force substantial re-engineering of embedded systems in existing ophthalmic imaging platforms, consuming R&D resources that would otherwise target novel indications.
- Interoperability fragmentation:Proprietary data formats between competing diagnostic device ecosystems impede seamless integration of anterior segment imaging with electronic health record systems in multi-vendor German clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Ophthalmic Devices Market |
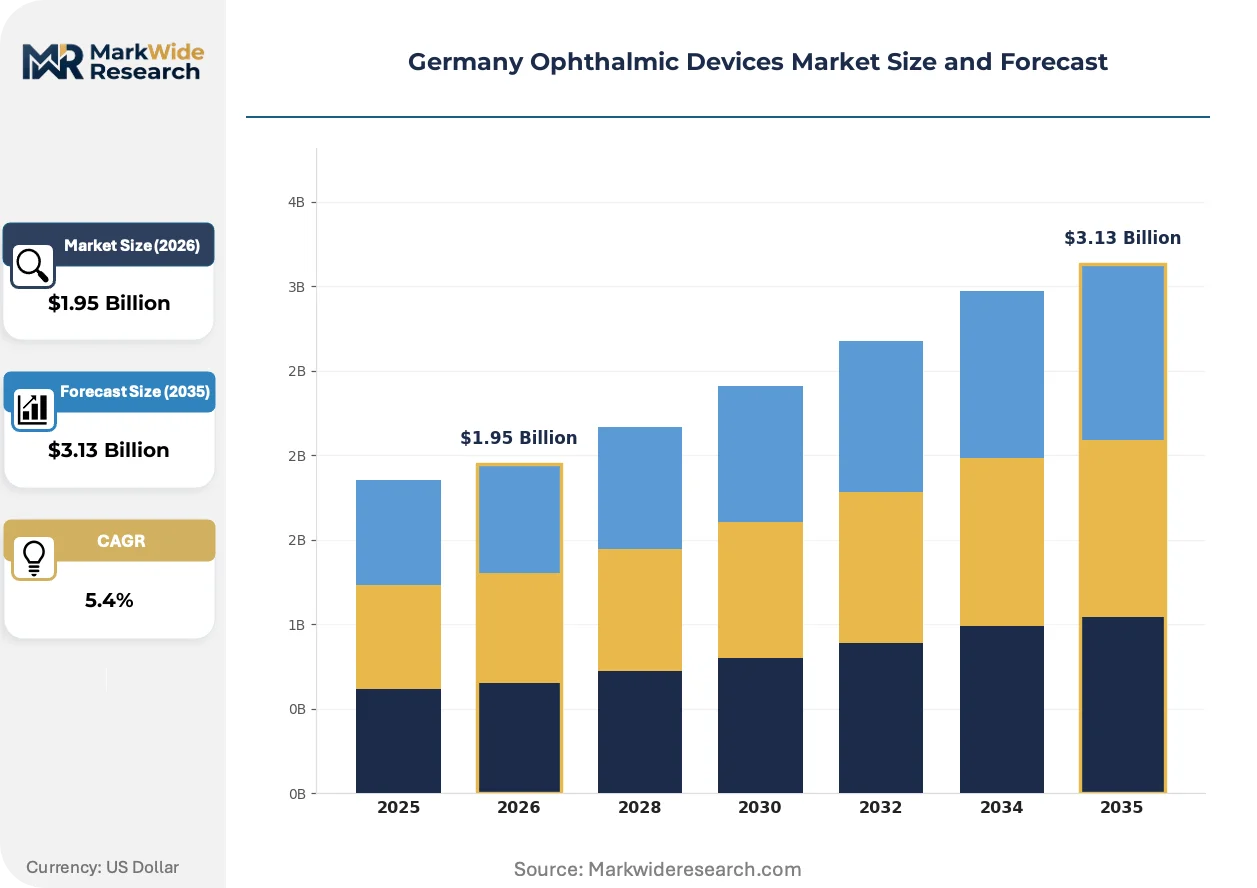
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slit Lamps, Fundus Cameras, Optical Coherence Tomography, Phoropters, Retinoscopes Technology: Imaging Systems, Diagnostic Devices, Surgical Instruments, Vision Testing Equipment, Laser Devices Application: Cataract Treatment, Glaucoma Management, Retinal Disorder Diagnosis, Refractive Error Correction, Corneal Disease Monitoring End User: Ophthalmology Clinics, Eye Hospitals, Diagnostic Centers, Research Institutes, Specialty Practices |
| Companies Covered | HAAG-Streit Group, Topcon Corporation, Carl Zeiss Meditec AG, Nidek Co Ltd, Bausch Health Companies Inc, Alcon Inc, Ziemer Ophthalmic Systems AG, EssilorLuxottica SA, Johnson & Johnson Vision Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Ophthalmic Devices Market Shifts & Advancements
Optical coherence tomography angiography is reshaping posterior segment diagnostics by displacing fluorescein-based imaging, while regulatory pressure on clinical evidence generation and shifting procurement authority within integrated care networks are restructuring competitive access.
swept-source OCT technology extends imaging depth beyond the choroid, enabling non-invasive visualization of deep vascular plexuses that conventional spectral-domain platforms cannot resolve. German retinal clinics in Heidelberg and Tübingen are adopting these systems at replacement-cycle velocity. swept-source platforms are supplanting dye-dependent angiography protocols in academic medical centers, compressing procedure time and eliminating contrast-related adverse events.
EU AI Act risk classification frameworks now subject ophthalmic diagnostic software with autonomous screening capabilities to conformity assessment pathways previously reserved for physical devices. BfArM guidance documents clarify that machine learning models for glaucoma progression prediction trigger higher scrutiny tiers. Algorithm-embedded perimetry systems face extended validation timelines, with manufacturers restructuring quality management systems to address post-market performance monitoring mandates.
Hospital procurement consortia in North Rhine-Westphalia and Berlin are consolidating ophthalmic device purchasing authority, displacing individual clinic autonomy with centralized tender processes. These aggregators negotiate multi-year framework agreements spanning diagnostic, surgical, and consumable categories, favoring vendors with comprehensive portfolio breadth. Integrated care organizations in urban German markets now dominate capital expenditure decisions, compressing sales cycle variability but intensifying price competition at contract renewal points.
Germany Ophthalmic Devices Market Segmentation
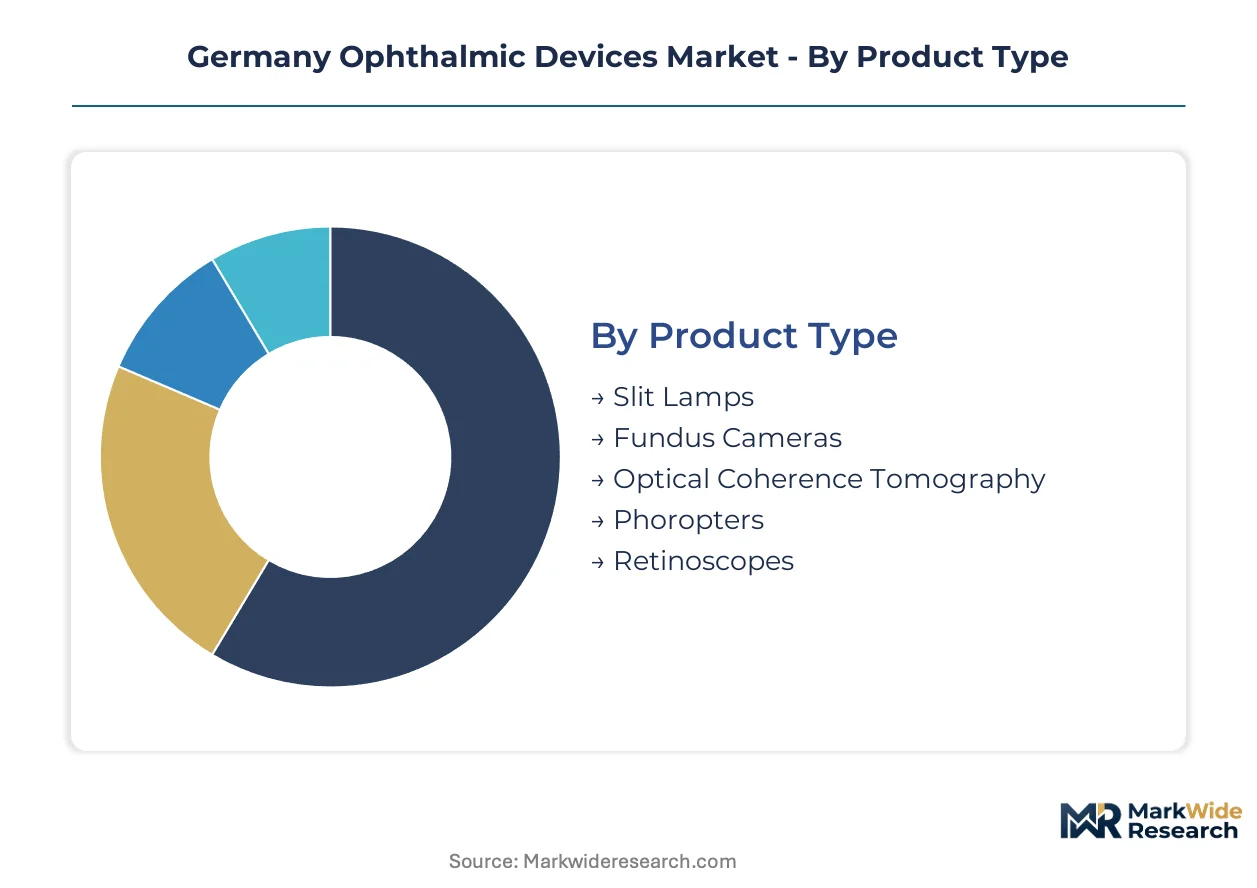
Precision optics manufacturing constraints and reimbursement pathway fragmentation create divergent margin profiles across ophthalmic device categories. Segment-level procurement authority varies sharply between consolidated hospital systems and fragmented specialty practices.
Product Type:
Optical coherence tomography systems command the steepest margin pools, while vision testing equipment operates on compressed replacement cycles.
- Slit Lamps:Biomicroscopic examination platforms with adjustable illumination geometry and stereoscopic viewing optics. Bavarian ambulatory surgery centers are standardizing on LED-illuminated models to reduce maintenance overhead and improve anterior segment visualization depth.
- Fundus Cameras:Non-mydriatic retinal imaging systems with automated focus and flash synchronization for posterior segment documentation. Baden-Württemberg diagnostic centers are prioritizing ultra-widefield variants to capture peripheral retinal pathology in single captures, though reimbursement coding lags technology capability.
- Optical Coherence Tomography:Interferometric cross-sectional imaging with micrometer-scale axial resolution for retinal layer segmentation.
- Phoropters:Mechanical refractive testing assemblies with synchronized lens wheel rotation for subjective refraction protocols.
- Retinoscopes:Handheld streak illumination devices for objective refractive error assessment in pediatric and non-verbal patient populations.
Slit lamps hold installed capacity. Optical coherence tomography is rotating up the share rankings.
Technology:
Capital expenditure concentration favors integrated diagnostic-surgical platforms over standalone vision testing modalities.
- Imaging Systems:Multimodal diagnostic platforms combining OCT, fundus photography, and angiography capabilities in unified hardware footprints. Heidelberg university hospitals are consolidating vendor relationships around swept-source architectures to reduce training burden and service contract complexity.
- Surgical Instruments:Femtosecond laser platforms and phacoemulsification systems with real-time anterior segment imaging integration. North Rhine-Westphalia procurement consortia are bundling capital equipment with multi-year consumable commitments to lock in per-procedure economics.
- Diagnostic Devices:Automated perimetry and specular microscopy systems for functional and structural assessment.
- Vision Testing Equipment:Standardized acuity charts and contrast sensitivity assessment tools for routine screening workflows.
- Laser Devices:Photocoagulation and selective laser trabeculoplasty systems for retinal and glaucoma interventions.
Surgical instruments concentrate margin capture. Diagnostic devices are expanding most quickly in community health networks.
Application:
Procedure volume distribution across anterior and posterior segment indications shapes capital allocation priorities.
- Cataract Treatment:Surgical workflows incorporating femtosecond laser capsulotomy and premium intraocular lens implantation. Statutory health insurer negotiations in Berlin are compressing reimbursement differentials between standard and toric multifocal lens tiers, constraining upgrade penetration.
- Glaucoma Management:Minimally invasive surgical devices and sustained-release drug delivery systems for intraocular pressure reduction. Tübingen academic centers are validating micro-invasive stent platforms against trabeculectomy benchmarks to support NUB innovation funding applications.
- Retinal Disorder Diagnosis:OCT angiography and widefield imaging for age-related macular degeneration and diabetic retinopathy screening.
- Refractive Error Correction:Excimer laser platforms and phakic intraocular lenses for elective vision correction procedures.
- Corneal Disease Monitoring:Scheimpflug tomography and anterior segment OCT for ectasia and transplant evaluation.
Cataract treatment anchors procedure economics. Glaucoma management is gaining share fastest as population aging accelerates.
End User:
Purchasing authority centralization is restructuring competitive access patterns across institutional categories.
- Ophthalmology Clinics:Outpatient facilities with mixed diagnostic and minor surgical capabilities serving urban and suburban catchments. Saxon specialty practices are delaying OCT replacement cycles to allocate capital toward MDR compliance documentation and quality management system upgrades.
- Eye Hospitals:Tertiary referral centers with comprehensive surgical suites and resident training programs. Berlin and Munich academic medical centers dominate femtosecond laser adoption through consolidated procurement tender processes spanning multiple department budgets.
- Diagnostic Centers:Standalone imaging facilities processing referrals from primary care networks.
- Research Institutes:University-affiliated laboratories conducting clinical trials and device validation studies.
- Specialty Practices:Single-specialty or small-group practices focusing on subspecialty niches.
Eye hospitals concentrate capital deployment. Ophthalmology clinics are rotating up the share rankings as same-day procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German states consume ophthalmic devices through divergent procurement pathways. Bavaria and Baden-Württemberg favor ambulatory surgery center expansion, while North Rhine-Westphalia concentrates hospital procurement authority.
Bavaria
Ambulatory eye surgery centers in Munich and Nuremberg are expanding femtosecond laser procurement for cataract workflows. BfArM's MDR enforcement compresses conformity assessment timelines for legacy diagnostic platforms. The Erlangen-Nuremberg medical technology cluster anchors precision optics assembly for wavefront aberrometers.
Baden-Württemberg
University hospitals in Heidelberg and Tübingen prioritize swept-source OCT adoption for retinal disease management. KBA-notified body assessments structure competitive access thresholds for Class III surgical devices. The Stuttgart-Tübingen corridor concentrates intraocular lens R&D through integrated manufacturer-research institute partnerships.
North Rhine-Westphalia
Hospital procurement consortia in Cologne and Düsseldorf consolidate diagnostic suite purchasing across multi-site networks. Statutory health insurer negotiations impose pricing ceilings on premium IOL tiers through regional framework agreements. The Rhine-Ruhr industrial basin hosts centralized sterilization services for reusable surgical instruments.
Berlin-Brandenburg
Academic medical centers dominate femtosecond laser adoption through consolidated tender processes spanning ophthalmology and refractive surgery departments. MDR cybersecurity annex requirements force re-engineering of embedded imaging software. The Berlin health technology startup ecosystem incubates AI-integrated diagnostic platforms for diabetic retinopathy screening.
Lower Saxony
Community health networks in Hanover and Brunswick deploy tele-ophthalmology infrastructure to address rural specialist access gaps. EU AI Act risk classification frameworks clarify regulatory pathways for autonomous screening algorithms. The Hanover medical device manufacturing base supplies automated perimetry systems to national distribution networks.
Germany Ophthalmic Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on single-modality platforms or regional service footprints. The upper tier commands procurement consortium relationships through comprehensive portfolio breadth spanning diagnostics, surgical capital, and consumables. Strategic archetypes include precision optics heritage manufacturers, diversified multinational health technology conglomerates, and specialized Swiss-German engineering houses. Competitive moves center on multi-year framework agreements bundling equipment with consumable commitments, and backward integration into optical-grade component sourcing.
Among diversified health technology conglomerates, Alcon Inc and Johnson & Johnson Vision Care occupy positions anchored by intraocular lens and vision care portfolios. Carl Zeiss Meditec AG exemplifies the precision optics heritage archetype through its Jena manufacturing base. HAAG-Streit Group represents specialized Swiss-German engineering concentration in slit lamp instrumentation. These three entities collectively illustrate how geographic manufacturing heritage and portfolio breadth determine competitive access within German procurement networks.
| Leading Market Players |
|---|
| HAAG-Streit Group |
| Topcon Corporation |
| Carl Zeiss Meditec AG |
| Nidek Co Ltd |
| Bausch Health Companies Inc |
| Alcon Inc |
| Ziemer Ophthalmic Systems AG |
| EssilorLuxottica SA |
| Johnson & Johnson Vision Care |
| Others |
Supply & Pricing Matrix
Long-term framework agreements between North Rhine-Westphalia hospital consortia and device manufacturers lock in multi-year supply access while compressing price visibility for premium intraocular lens tiers. KBA-notified body assessments and BfArM MDR enforcement timelines feed directly into contract renegotiation cycles, with procurement managers front-loading capital expenditure to hedge against conformity assessment delays.
Pricing Analysis
Project-based capital equipment tenders dominate ophthalmic device procurement, with diagnostic suite bundles commanding premium positioning against standalone vision testing modalities. Price differentiation hinges on CE marking tier under MDR Annex VIII classification and after-sales service contract comprehensiveness. Cost compression in standard intraocular lens categories is intensifying because statutory health insurer negotiations impose reimbursement ceilings. Ambulatory surgery centers exhibit highest price sensitivity, while Berlin academic medical centers prioritize technology capability over procurement cost.
Supply Chain Analysis
Inventory lead times for optical-grade germanium and precision-machined aluminum housings extend production schedules for thermal imaging components and wavefront aberrometers. German manufacturers draw from East Asian refining operations for germanium substrates, Swiss optical glass suppliers for lens elements, and domestic Jena-area precision machining for diagnostic platform assembly. Single-source vulnerability concentrates in East Asian rare earth processing. Distribution runs through manufacturer-direct sales teams serving hospital procurement consortia alongside specialized medical device distributors covering ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's ophthalmic devices market sits in a post-MDR transition cyclical recovery, with replacement demand accelerating as legacy equipment faces conformity assessment deadlines. Bavarian and Baden-Württemberg ambulatory surgery center expansion provides the demand floor for this cycle.
For Market Incumbents: Shield premium positioning by accelerating backward integration into optical-grade component sourcing and securing KBA-notified body pre-assessment commitments ahead of competitor submissions. MDR cybersecurity annex requirements threaten legacy software platforms; incumbents should prioritize embedded system re-engineering to defend service contract renewals against emerging AI-integrated diagnostic entrants. For New Entrants and Emerging Players: Differentiate on AI-integrated screening algorithms for diabetic retinopathy detection in rural Saxon and Lower Saxon community health networks. Tele-ophthalmology infrastructure presents the most penetrable white space, with autonomous diagnostic software clarifying regulatory pathways under EU AI Act risk classification frameworks. Partner with primary care workflow platforms for distribution leverage. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision optics heritage manufacturers with captive Jena-area assembly capacity and established BfArM relationship networks. Long-term viability centers on multi-year framework agreement penetration rather than spot equipment sales. Watch KBA-notified body capacity expansion announcements as the inflection signal for novel surgical platform time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Acceleration | KBA pre-submission programs compress time-to-market for Class III surgical platforms against backlog-constrained competitors. |
| AI Diagnostic Software Validation | BfArM guidance alignment under EU AI Act risk tiers unlocks autonomous screening reimbursement in community health networks. |
| Hospital System Partnership | North Rhine-Westphalia procurement consortia favor vendors with comprehensive diagnostic-surgical-consumable portfolio breadth. |
| Optical Component Backward Integration | Jena-area precision machining captive supply insulates wavefront aberrometer production from East Asian germanium volatility. |
| Tele-Ophthalmology Platform Launch | Rural Bavarian and Saxon specialist access gaps create first-mover advantage for remote diagnostic-primary care workflow integration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BfArM guidance documents, KBA conformity assessment procedural filings, and statutory health insurer framework agreement disclosures. Primary interviews engaged hospital procurement committee chairs, ambulatory surgery center managing directors, biomedical engineers at Heidelberg and Tübingen university hospitals, and GPO contracts managers serving North Rhine-Westphalia networks. Bottom-up equipment shipment analysis triangulates against top-down reimbursement pathway expenditure data from regional sickness funds.
Segmentation dimensions modeled span product type, technology platform, clinical application, and end-user institution category across the analysis window. CAGRs derive from procedure volume trajectories in cataract and glaucoma segments, capital equipment replacement cycles tied to MDR enforcement timelines, and premium intraocular lens penetration assumptions constrained by statutory insurer negotiation outcomes. Forecast inputs incorporate femtosecond laser adoption curves in academic medical centers and tele-ophthalmology infrastructure deployment rates in rural regions.
The analysis sits within stated boundaries; outcomes outside sustained BfArM enforcement intensity or KBA-notified body capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding MDR transition completion and EU AI Act implementation pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Microscope Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Toe Fixation System Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Asia-Pacific Ultrasound Devices Market