
 Flexible and Semi-Rigid Ureteroscopy Market | 2026-2036
Flexible and Semi-Rigid Ureteroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible and Semi-Rigid Ureteroscopy Market Analysis
Ambulatory surgery centers is repositioning procedure volumes away from traditional hospital settings toward lower-acuity environments. KARL STORZ leverages its integrated manufacturing base to supply rigid and flexible systems across European and North American urology suites. Boston Scientific Corporation competes through digital imaging platforms that reduce procedural time in high-throughput ASC networks. Olympus Corporation anchors its position via fiber-optic and video ureteroscopy portfolios serving academic medical centers in Japan and the United States.
Flexible and semi-rigid ureteroscopy encompasses endoscopic instruments inserted through the urethra and ureter to visualize, diagnose, and treat conditions of the upper urinary tract, typically employing working channels of 3.6 Fr or smaller and deflection capabilities exceeding 270 degrees for renal calyceal access. Digital ureteroscopy now displaces fiber-optic platforms in premium installations due to superior image resolution and durability. Therapeutic ureteroscopes command stronger margin pools than diagnostic configurations because laser lithotripsy and stone retrieval accessories attach to higher-ASP instrument systems. Hospitals remain the largest end-user category by installed base, though ambulatory surgery centers represent the fastest-growing site-of-service segment as payors shift reimbursement toward outpatient settings.
FDA 510(k) pathways govern market entry for ureteroscope devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable instruments in Europe. ISO 13485 quality management certification and biocompatibility testing per ISO 10993 shape supplier qualification standards across all major markets. Stakeholders must monitor reimbursement coding changes for single-use ureteroscopes and evolving sterilization validation protocols that determine total cost-of-ownership calculations for hospital procurement committees.
Market Dynamics
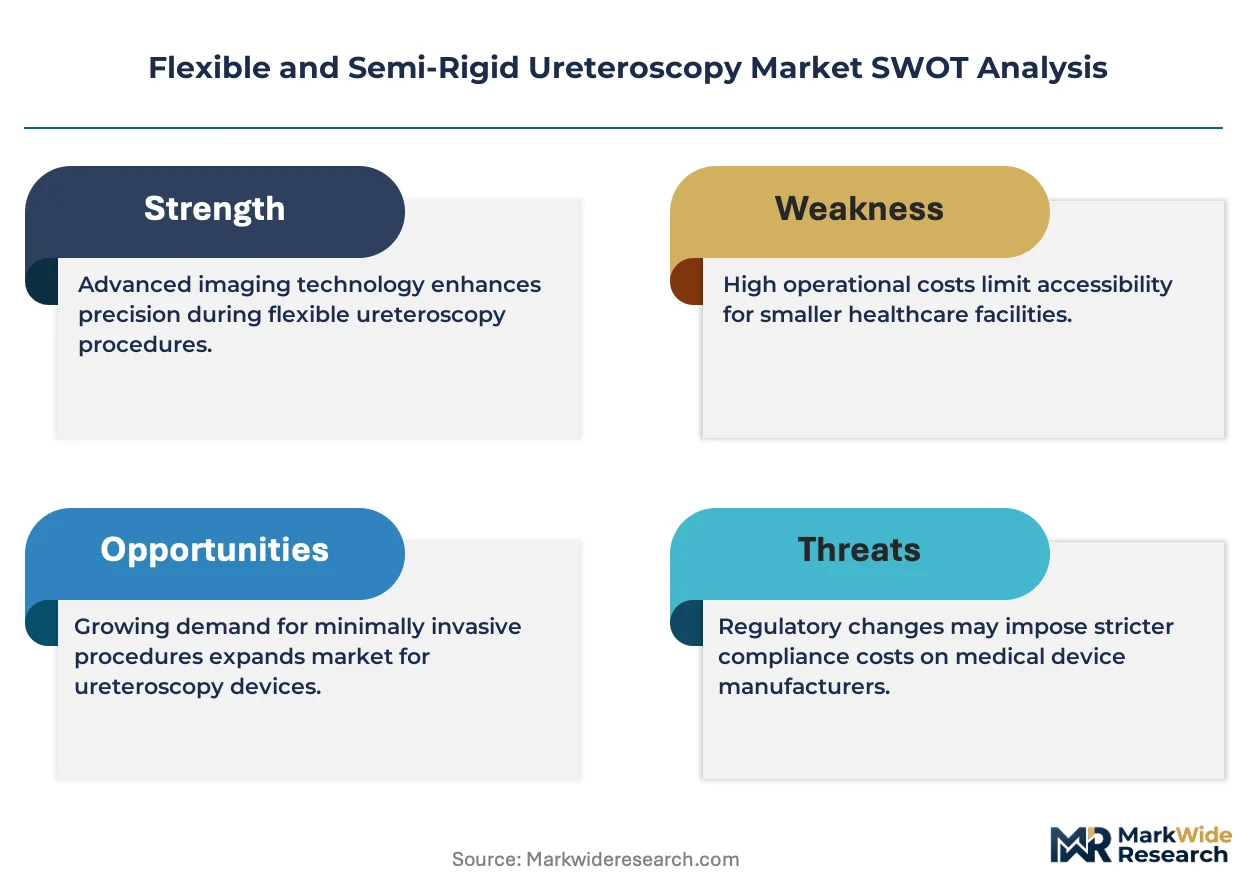
Single-use digital ureteroscopes are compressing sterilization infrastructure requirements while forcing capital equipment manufacturers toward disposable revenue models that alter hospital procurement calculus.
Growth Catalysts
- FDA 510(k) clearance pathways:Streamlined premarket notification processes for single-use devices accelerate commercialization timelines for manufacturers targeting ambulatory surgery centers.
- Laser lithotripsy integration:Holmium and thulium fiber laser compatibility with flexible ureteroscope working channels expands therapeutic indications beyond diagnostic visualization.
- ASC reimbursement migration:CMS outpatient procedure codes for ureteroscopic stone removal redirect patient volumes from inpatient hospital settings.
Market Restraints
- Reusable instrument sterilization validation:EU Medical Device Regulation mandates enhanced clinical evidence for reusable flexible ureteroscopes, extending compliance timelines.
- Optical fiber supply concentration:Japanese and German fiber-optic component suppliers control critical image transmission subassemblies.
- Capital equipment replacement cycles:Video processor and light source systems require seven-to-ten year depreciation schedules that delay technology refresh.
Strategic Opportunities
- Underpenetrated urology networks in India:CDSCO regulatory harmonization and private hospital chain expansion create first-mover positioning for digital platform suppliers.
- Artificial intelligence image enhancement:Real-time stone recognition algorithms converging with 4K digital sensors reduce fluoroscopy exposure.
- Direct-to-facility distribution models:Bypassing traditional distributor markups through manufacturer-owned field service organizations.
Industry Challenges
- Interventional urologist training pipelines:Fellowship programs produce insufficient procedural specialists to match ASC expansion rates.
- ISO 13485 quality management recertification:Annual surveillance audits and MDR technical documentation updates consume regulatory affairs bandwidth.
- Legacy video system interoperability:Fiber-optic ureteroscope fleets require adapter bridges for digital processor compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible and Semi-Rigid Ureteroscopy Market |
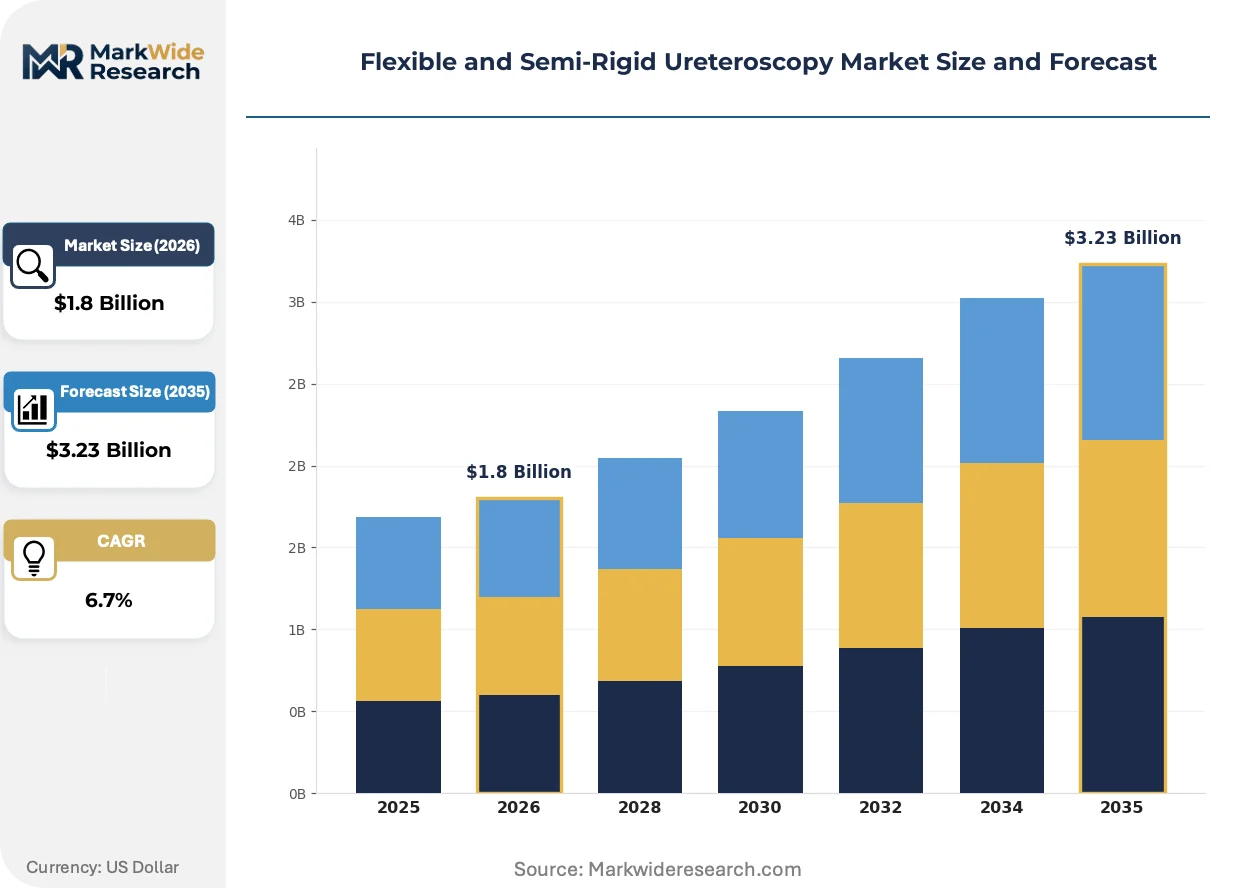
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ureteroscopes, Semi-Rigid Ureteroscopes, Diagnostic Ureteroscopes, Therapeutic Ureteroscopes End User: Hospitals, Clinics, Ambulatory Surgery Centers, Specialty Urology Centers Technology: Digital Ureteroscopy, Fiber-Optic Ureteroscopy, Video Ureteroscopy, Laser-Assisted Ureteroscopy Application: Stone Removal, Tumor Ablation, Urinary Tract Biopsy, Stent Placement |
| Companies Covered | KARL STORZ, Elmed Medical Systems, Boston Scientific Corporation, Rocamed, Maxer Endoscopy, Stryker Corporation, Richard Wolf, Vimex Endoscopy, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible and Semi-Rigid Ureteroscopy Market Emerging Trajectories
Digital imaging platforms, regulatory harmonization pressures, and site-of-service economics are compressing traditional technology adoption curves while fragmenting purchasing authority across health system stakeholders.
Robotic-assisted ureteroscope manipulation is automating stone targeting and laser firing sequences in select academic medical centers. High-volume stone centers in the United States are piloting autonomous tip deflection systems that reduce fluoroscopy time and operator fatigue. This automation is compressing the learning curve for complex renal calyceal access procedures.
EU Medical Device Regulation clinical evidence requirements are forcing manufacturers to compile post-market surveillance data for reusable flexible instruments. Stricter biocompatibility testing per ISO 10993-5 and -10 now governs all materials in patient-contact components. European urology suites are responding by accelerating evaluation of single-use alternatives that bypass sterilization validation burdens.
Stone disease management is consolidating into dedicated ambulatory networks that unbundle device procurement from capital equipment leases. United States specialty urology groups are negotiating direct purchasing agreements with manufacturers, displacing hospital materials management intermediaries. This channel compression is most visible in Texas and Florida metropolitan markets where physician-owned surgery centers dominate procedural volumes.
Flexible and Semi-Rigid Ureteroscopy Market Segmentation
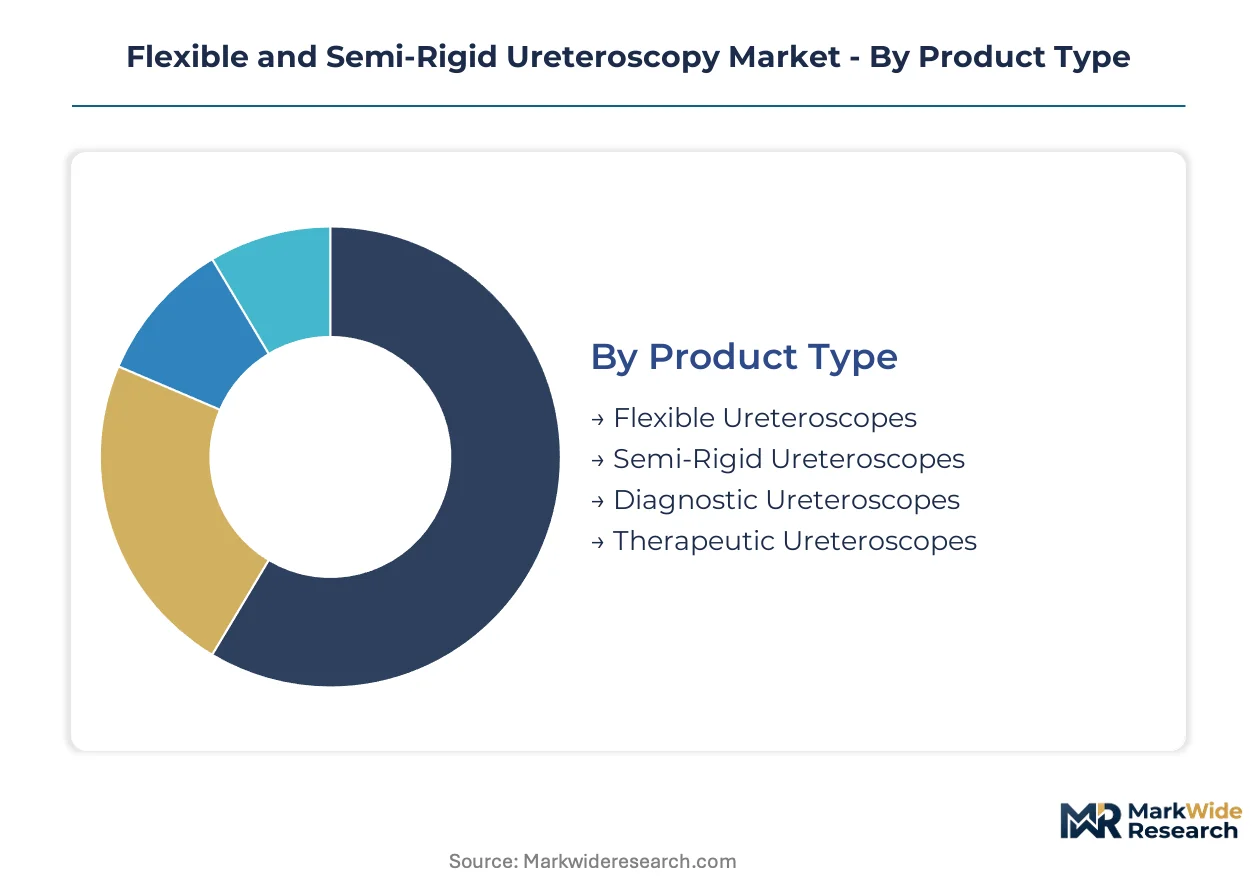
Ureteroscope segmentation reflects divergent capital intensity and sterilization economics across care settings. Procurement committees weigh image quality against total cost-of-ownership when allocating budgets across product tiers.
Product Type:
Standalone instruments dominate capital budgets, while embedded laser systems command premium configurations in high-throughput stone centers.
- Flexible Ureteroscopes:Deflection capabilities exceeding 270 degrees enable complete renal calyceal access through a single insertion point. Demand concentrates in United States ambulatory surgery centers where outpatient stone removal volumes are migrating from inpatient settings.
- Therapeutic Ureteroscopes:Working channels of 3.6 Fr or larger accommodate holmium laser fibers and stone retrieval baskets during active intervention. Specialty urology centers in Texas and Florida metropolitan markets favor these configurations for their higher procedure reimbursement rates.
- Semi-Rigid Ureteroscopes:Intermediate shaft rigidity suits distal ureteral pathology with reduced deflection complexity.
- Diagnostic Ureteroscopes:Narrower working channels prioritize visualization over intervention in academic medical center staging protocols.
Flexible ureteroscopes lead volumes today; therapeutic configurations are gaining share fastest.
End User:
Site-of-service economics fragment purchasing authority between capital-intensive hospital systems and lean ambulatory networks.
- Ambulatory Surgery Centers:CMS outpatient procedure codes for ureteroscopic stone removal redirect patient volumes from inpatient settings. These facilities prioritize single-use instruments that eliminate sterilization infrastructure and reduce turnover time between cases.
- Hospitals:Installed base of video processors and light source systems creates stickiness for compatible ureteroscope fleets. Seven-to-ten year depreciation schedules delay technology refresh cycles despite superior digital imaging alternatives.
- Specialty Urology Centers:Physician-owned networks in Sun Belt states negotiate direct purchasing agreements with manufacturers.
- Clinics:Limited procedure volumes restrict capital equipment acquisition to diagnostic configurations.
Hospitals retain the largest installed base; ambulatory surgery centers are expanding most quickly.
Technology:
Image transmission architecture determines compatibility with legacy video systems and sterilization validation burdens.
- Digital Ureteroscopy:CMOS and CCD sensors deliver 4K resolution that reduces fluoroscopy exposure and improves stone recognition. Academic medical centers in Japan and the United States anchor demand for these premium installations.
- Laser-Assisted Ureteroscopy:Holmium and thulium fiber laser integration expands therapeutic indications beyond diagnostic visualization. High-volume stone centers pilot autonomous tip deflection systems that automate stone targeting sequences.
- Fiber-Optic Ureteroscopy:Japanese and German fiber-optic component suppliers control critical image transmission subassemblies.
- Video Ureteroscopy:Intermediate tier bridges legacy processor compatibility with improved resolution.
Digital ureteroscopy leads premium installations; laser-assisted configurations are climbing the fastest.
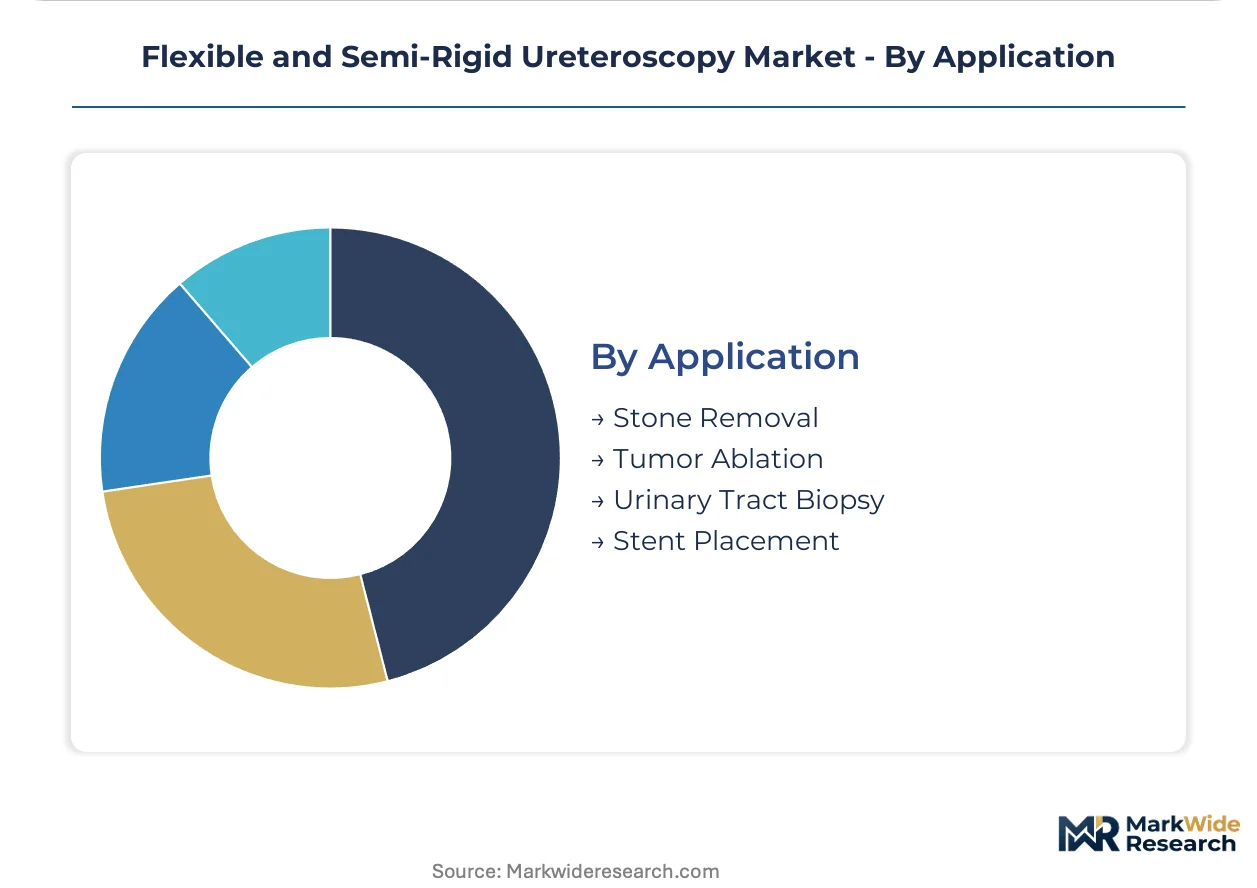
Application:
Procedure reimbursement codes and complication risk profiles shape instrument selection across clinical indications.
- Stone Removal:Ureteroscopic stone removal constitutes the dominant procedural indication, with laser lithotripsy and basket retrieval requiring therapeutic instrument configurations. United States specialty urology groups drive procedural volumes through dedicated ambulatory networks.
- Tumor Ablation:Upper tract urothelial carcinoma management demands superior image resolution for margin assessment. Academic medical centers deploy digital platforms with narrow-band imaging capabilities.
- Urinary Tract Biopsy:Diagnostic forceps compatibility influences working channel specification.
- Stent Placement:Guidewire manipulation requirements favor semi-rigid instrument stability.
Stone removal leads procedural volumes today; tumor ablation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting ureteroscope manufacturing toward jurisdictions with streamlined medical device approval pathways. The EU Medical Device Regulation's sterilization validation burdens are accelerating supplier migration toward markets with lighter compliance overhead.
United States
CMS outpatient procedure codes for ureteroscopic stone removal redirect patient volumes toward ambulatory surgery centers. FDA 510(k) clearance pathways streamline premarket notification processes for single-use digital platforms. Texas and Florida metropolitan markets host physician-owned specialty urology groups negotiating direct purchasing agreements with manufacturers.
Germany
Integrated manufacturing bases supply rigid and flexible systems across European urology suites. EU Medical Device Regulation mandates enhanced clinical evidence for reusable flexible instruments, extending compliance timelines for domestic producers. Tuttlingen industrial cluster anchors precision instrument fabrication serving academic medical centers.
Japan
Domestic fiber-optic component suppliers control critical image transmission subassemblies for global ureteroscope production. PMDA regulatory harmonization with ISO 13485 quality management standards shapes supplier qualification protocols. Tokyo and Osaka metropolitan academic medical centers anchor demand for 4K digital imaging platforms.
India
Private hospital chain expansion creates first-mover positioning for digital platform suppliers in underpenetrated urology networks. CDSCO regulatory harmonization with international standards accelerates import approval timelines for foreign manufacturers. Maharashtra and Karnataka host emerging specialty urology centers adopting laser-assisted therapeutic configurations.
China
NMPA medical device registration requirements are converging with international standards, reducing approval friction for imported digital platforms. Domestic manufacturers are scaling CMOS sensor production for cost-competitive ureteroscope assemblies. Yangtze River Delta industrial corridor concentrates endoscope component fabrication serving regional hospital procurement committees.
Flexible and Semi-Rigid Ureteroscopy Market Vendor Landscape
Portfolio diversification dominates the current landscape as capital equipment manufacturers pivot toward disposable revenue models. The vendor base segments across three tiers: integrated surgical systems conglomerates, specialized endoscopy instrument firms, and emerging single-use platform developers. Strategic archetypes include sterilization-bypass specialists targeting ambulatory surgery centers, laser-integration platform builders, and fiber-optic legacy system maintainers. M&A activity and direct-to-facility distribution expansion represent the dominant competitive vectors reshaping channel economics.
Among integrated surgical systems conglomerates, KARL STORZ and Stryker Corporation exemplify diversified endoscopy portfolio builders spanning rigid and flexible configurations. Boston Scientific Corporation occupies a position within the digital imaging platform tier, while Olympus Corporation anchors the fiber-optic and video ureteroscopy segment serving academic medical centers. These three entities represent distinct strategic postures: German integrated manufacturing, American disposable-platform pivoting, and Japanese optical heritage.
| Leading Market Players |
|---|
| KARL STORZ |
| Elmed Medical Systems |
| Boston Scientific Corporation |
| Rocamed |
| Maxer Endoscopy |
| Stryker Corporation |
| Richard Wolf |
| Vimex Endoscopy |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Precision optics engineers concentrated in Tuttlingen, Germany and Tokyo, Japan command wage premiums that widen pricing spreads between premium digital ureteroscopes and economy fiber-optic alternatives. Labor-cost differentials in these specialized manufacturing clusters feed directly into tiered product positioning across ambulatory surgery centers and academic medical centers.
Pricing Analysis
Distributor markups of 25-40% separate manufacturer list prices from hospital procurement committee negotiations, though direct-to-facility agreements in Texas and Florida metropolitan markets compress these layers. Pricing stratifies across premium, standard, and economy tiers based on image sensor resolution and sterilization validation status. Cost compression in single-use configurations is intensifying as Boston Scientific and emerging competitors bypass capital equipment leasing structures. Ambulatory surgery centers exhibit highest price sensitivity due to per-procedure margin constraints, while academic medical centers prioritize image quality over unit economics.
Supply Chain Analysis
Freight costs for temperature-controlled CMOS sensor shipments from Japan and precision shaft components from Germany add 8-12% to landed instrument costs for North American assembly facilities. Manufacturing concentrates in Germany, Japan, and the United States, with each jurisdiction anchoring distinct technology tiers. Raw material dependencies include optical glass fibers, biocompatible polymers, and miniature sensor arrays. Single-source vulnerability in Japanese fiber-optic component suppliers creates supply chain concentration risk. Distribution runs through manufacturer-owned field service organizations and GPO contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Flexible and Semi-Rigid Ureteroscopy Market functions as a stable compounder anchored by irreversible site-of-service migration toward outpatient stone removal procedures.
For Market Incumbents: Extend digital platform roadmaps to capture ASC procurement cycles before single-use alternatives commoditize premium tiers. Defend against emerging disposable entrants by securing exclusive GPO contracts with specialty urology networks. Backward integration into CMOS sensor sourcing reduces exposure to Japanese supply concentration.
For New Entrants and Emerging Players: Begin with underpenetrated private hospital chains in Maharashtra and Karnataka, India, where CDSCO regulatory harmonization accelerates import approvals. Target laser-assisted therapeutic configurations in physician-owned surgery centers seeking to unbundle from hospital materials management. Pursue direct-to-facility distribution bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Integrated surgical systems conglomerates are the most active acquirer in this space, seeking disposable-platform capabilities to offset capital equipment revenue decline. Long-term viability rests on recurring revenue models replacing depreciation-heavy instrument sales. Monitor FDA 510(k) clearance velocity for single-use digital platforms as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlines premarket entry for single-use digital platforms targeting ambulatory surgery centers. |
| Hospital System Partnership | Secures installed base stickiness through video processor compatibility and service contracts. |
| Backward Integration | Captures CMOS sensor supply chain value currently concentrated in Japanese component suppliers. |
| Reimbursement Strategy | Aligns product positioning with CMS outpatient procedure codes redirecting volumes to ASCs. |
| Software Companion Development | Enables AI-powered stone recognition algorithms reducing fluoroscopy exposure in high-volume centers. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market cluster. The analysis combines structured interviews with interventional urologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, PMDA submissions, CDSCO import records, and hospital procurement databases. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user site-of-service, technology architecture, and clinical application. CAGRs derive from logistic diffusion curves fitted to technology substitution patterns and reimbursement code migration timelines. Forecast inputs incorporate laser lithotripsy penetration rates and single-use instrument adoption curves.
Caveats apply where EU Medical Device Regulation sterilization validation delays or supply chain disruptions in Japanese optical fiber production could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Microscope Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Surgical Display Market
Medical Devices
Artificial Retina Market
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Dermal Allograft Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market