
 Infertility Treatment Devices Market | 2026-2036
Infertility Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Infertility Treatment Devices Market Intelligence
The gap between premium laboratory-grade systems and entry-level clinical tools is rebalancing as fertility clinics demand modular upgrade paths without full capital replacement. Thermo Fisher Scientific leverages its analytical instrument heritage to dominate high-complexity embryology workflows. CooperSurgical anchors the North American clinic channel through deep consumables integration. Vitrolife AB specializes in culture media and time-lapse incubators that command sustained pricing power in European ART centers.
Infertility treatment devices encompass precision instruments, incubation systems, micromanipulation platforms, and cryogenic storage equipment engineered to maintain gamete and embryo viability within strict temperature, pH, and osmolality parameters. These systems enable clinical extraction, fertilization, embryo culture, and implantation procedures that underpin assisted reproductive technology outcomes. IVF equipment leads installed base value due to capital intensity and replacement cycles, while cryopreservation technology captures expanding margin pools as elective fertility preservation rises among younger patients. Hormonal pumps occupy a mature but stable position in ovarian stimulation protocols across clinic networks.
FDA 510(k) clearance pathways and EMA Medical Device Regulation classifications shape product development timelines and commercial access for embryo culture platforms and laser-assisted hatching systems. ISO 13485 quality management and WHO laboratory standards further constrain supplier qualification, favoring manufacturers with established regulatory infrastructure. Stakeholders must monitor reimbursement policy shifts in Germany and Japan as public funding for ART cycles directly influences clinic capital budgets and device upgrade cadence.
Market Dynamics
Modular upgrade architectures are displacing monolithic capital equipment purchases as fertility clinics seek to preserve embryology workflow continuity without full system replacement cycles.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for embryo culture platforms reduce time-to-clinic deployment, compressing commercialization timelines for validated systems.
- Elective Fertility Preservation:Younger patient cohorts in the United States and Japan are expanding cryogenic storage infrastructure requirements beyond traditional infertility treatment populations.
- Time-Lapse Imaging:Continuous embryo monitoring without incubator disruption is integrating into standard embryology protocols, replacing static observation methods.
Market Restraints
- Capital Intensity:Laser-assisted hatching systems and micromanipulation platforms require seven-figure clinic investments that strain independent practice budgets.
- Supply Concentration:Specialized culture media formulations depend on a limited supplier base concentrated in Northern Europe, creating vulnerability to batch variability.
- EMA MDR Classification:Reclassification of embryo culture devices under stricter conformity assessment procedures extends certification timelines by 12-18 months.
Strategic Opportunities
- Germany Reimbursement Expansion:Proposed public funding increases for ART cycles would unlock capital equipment budgets across university-affiliated reproductive centers.
- AI-Enhanced Morphokinetics:Machine vision algorithms analyzing time-lapse embryo development are converging with automated grading systems to reduce subjective embryologist assessment.
- Direct-to-Clinic Consumables:Subscription-based media and disposables delivery models bypass traditional distributor markups in saturated metropolitan markets.
Industry Challenges
- Embryologist Certification Bottlenecks:Extended training periods for complex micromanipulation techniques constrain clinic expansion velocity in high-demand regions.
- Legacy Incubator Integration:Time-lapse systems require physical retrofitting of existing laboratory infrastructure, complicating phased technology adoption.
- ISO 13485 Audit Burden:Annual surveillance assessments for quality management systems consume substantial regulatory affairs resources at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infertility Treatment Devices Market |
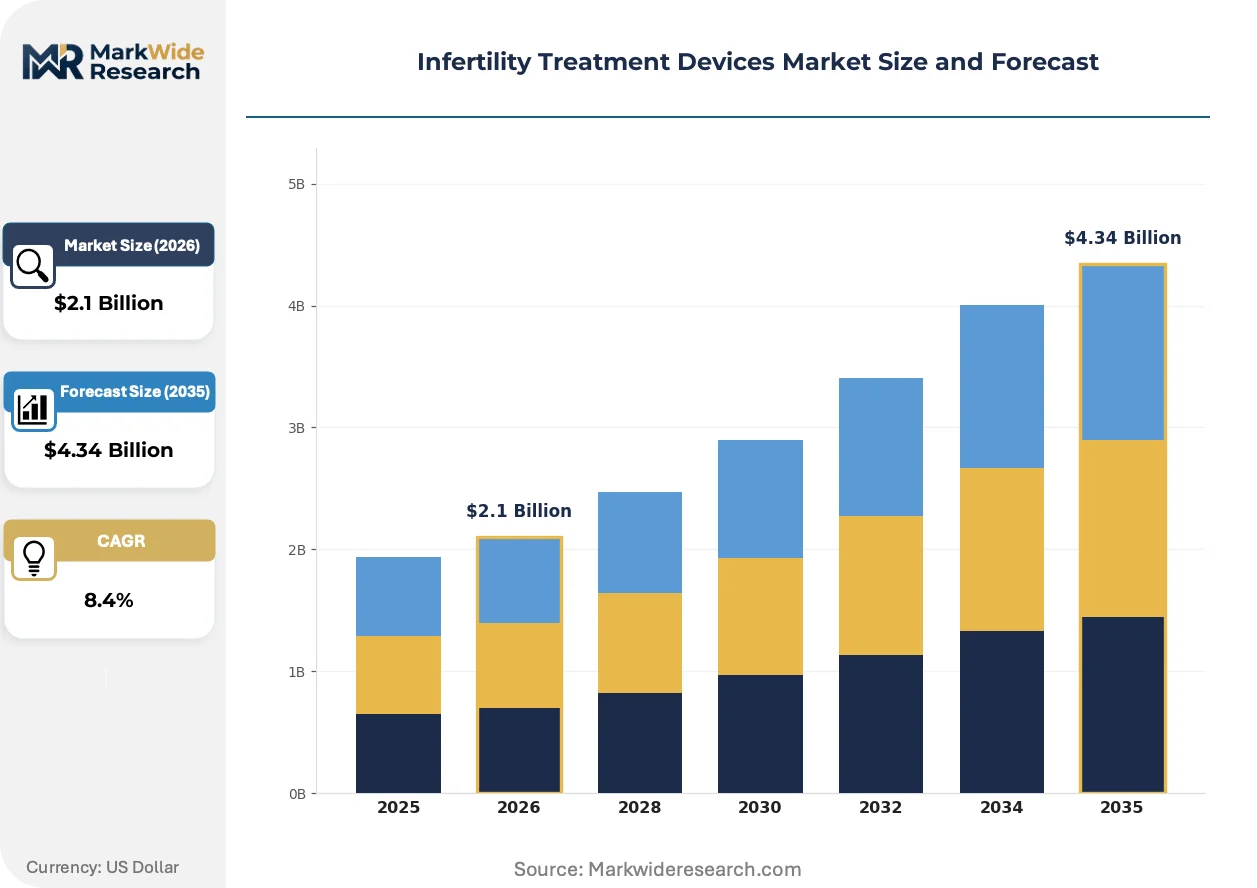
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insemination Devices, IVF Equipment, Surgical Instruments, Hormonal Pumps End User: Clinics, Hospitals, Research Laboratories, Home Users Technology: Laser Technologies, Cryopreservation, Intrauterine Devices, Sperm Retrieval Techniques Application: Assisted Reproductive Technologies, Hormonal Therapy, Sperm Analysis, Egg Preservation |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, CooperSurgical, Kitazato Corporation, FUJIFILM Irvine Scientific, Vitrolife AB, Hamilton Thorne, Rocket Medical, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infertility Treatment Devices Market Strategic Shifts & Innovations
Assisted reproductive technology is experiencing simultaneous pressure from precision medicine expectations and operational efficiency mandates, forcing equipment architectures toward adaptive, data-integrated designs.
Preimplantation genetic testing workflows are integrating with automated embryo biopsy platforms to reduce manual handling errors and standardize cell retrieval procedures. High-throughput fertility clinics in the United States are adopting these systems at replacement-cycle pace. The technology is integrating genetic screening directly into embryology laboratory workflows, compressing the timeline between fertilization and transfer decisions.
EMA Medical Device Regulation enforcement is tightening post-market surveillance requirements for embryo culture media and cryopreservation solutions. Manufacturers must now maintain clinical follow-up data across extended implantation windows. European ART centers are responding by consolidating supplier relationships toward vendors with established pharmacovigilance infrastructure.
Service unbundling is fragmenting traditional equipment-procurement contracts into discrete lease, maintenance, and consumables agreements. Independent fertility clinics are driving this disintermediation to improve cash-flow predictability. Japan exhibits the most pronounced shift, where metropolitan clinic networks now negotiate separate agreements for incubator hardware, time-lapse software licenses, and per-cycle media supplies.
Infertility Treatment Devices Market Segmentation
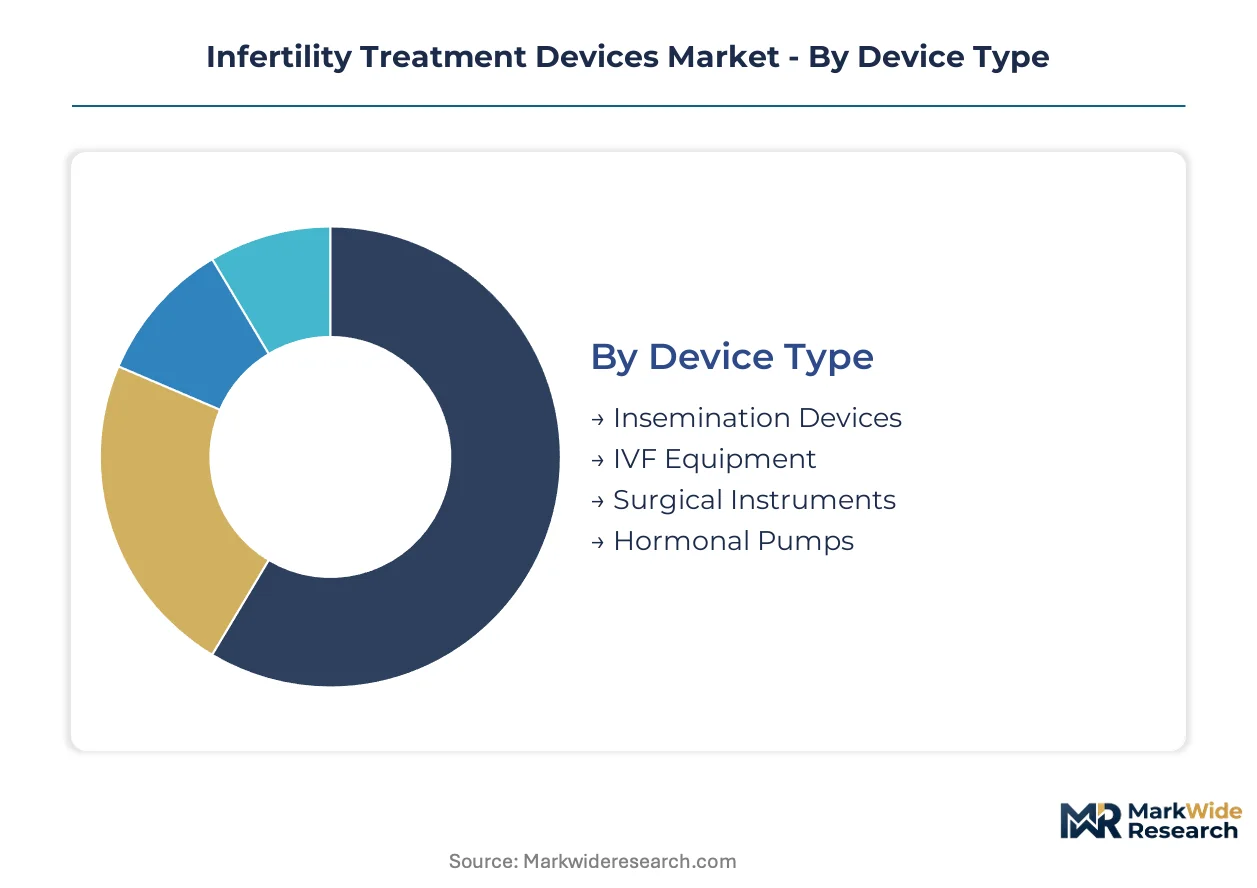
Infertility treatment devices fragment across four distinct classification axes that shape procurement patterns and margin structures differently. Device type and end-user categories dominate capital allocation decisions, while technology and application segments determine workflow integration complexity and reimbursement eligibility.
Device Type:
Standardization prevails in capital-intensive platforms, whereas consumables and accessories permit greater clinic-level customization.
- IVF Equipment:Integrated incubation, micromanipulation, and embryo culture systems command the highest installed-base value due to multi-year replacement cycles and ISO 13485 certification requirements. Demand concentrates in university-affiliated fertility centers across Germany and Japan, where public reimbursement frameworks support capital refresh programs.
- Cryopreservation:Vitrification systems and cryogenic storage infrastructure enable elective fertility preservation workflows that extend patient relationships beyond acute treatment cycles. United States metropolitan clinics are expanding liquid nitrogen storage capacity fastest as younger patient cohorts pursue deferred reproduction timelines.
- Insemination Devices:Catheters and specimen collection systems occupy a mature procurement category with stable unit economics.
- Surgical Instruments:Laparoscopic and hysteroscopic tools for tubal procedures maintain consistent replacement demand.
- Hormonal Pumps:Programmable infusion devices for controlled ovarian stimulation protocols serve established clinic networks with predictable utilization rates.
Leading the category by volume: Hormonal Pumps. Growing fastest: Cryopreservation.
End User:
Procurement sophistication varies sharply across facility types, with research laboratories demanding configurable platforms and home users driving simplicity-at-scale.
- Clinics:Specialized fertility centers generate the majority of device revenue through high-throughput embryology laboratories requiring modular upgrade paths. German clinic networks are consolidating vendor relationships to streamline EMA MDR compliance costs.
- Hospitals:Academic medical centers integrate reproductive medicine within broader obstetrics-gynecology departments, favoring multi-purpose equipment with cross-departmental utilization.
- Research Laboratories:Preclinical and translational research facilities require flexible configurations for experimental protocols.
- Home Users:Ovulation monitoring and hormone tracking devices serve self-managed fertility awareness applications.
Highest capital intensity: Clinics. Expanding most quickly: Home Users.
Technology:
Patent-proprietary platforms compete against open-architecture alternatives, with regulatory clearance timelines determining commercialization velocity.
- Cryopreservation:Vitrification and slow-freeze methods for gamete and embryo storage represent the technology category with broadest application across patient demographics. Japanese ART centers are adopting automated vitrification systems to reduce technician-dependent variability.
- Laser Technologies:Assisted hatching and embryo biopsy systems enable precision interventions without mechanical contact. United States high-volume clinics deploy these platforms for preimplantation genetic testing integration.
- Intrauterine Devices:Catheter-based delivery systems for artificial insemination procedures maintain cost-efficient positioning.
- Sperm Retrieval Techniques:Microsurgical epididymal sperm aspiration and testicular sperm extraction tools serve male-factor infertility cases.
Widest installed base: Cryopreservation. Steepest technology refresh: Laser Technologies.
Application:
Reimbursement eligibility and outcome measurability drive application-level prioritization in clinic budgeting processes.
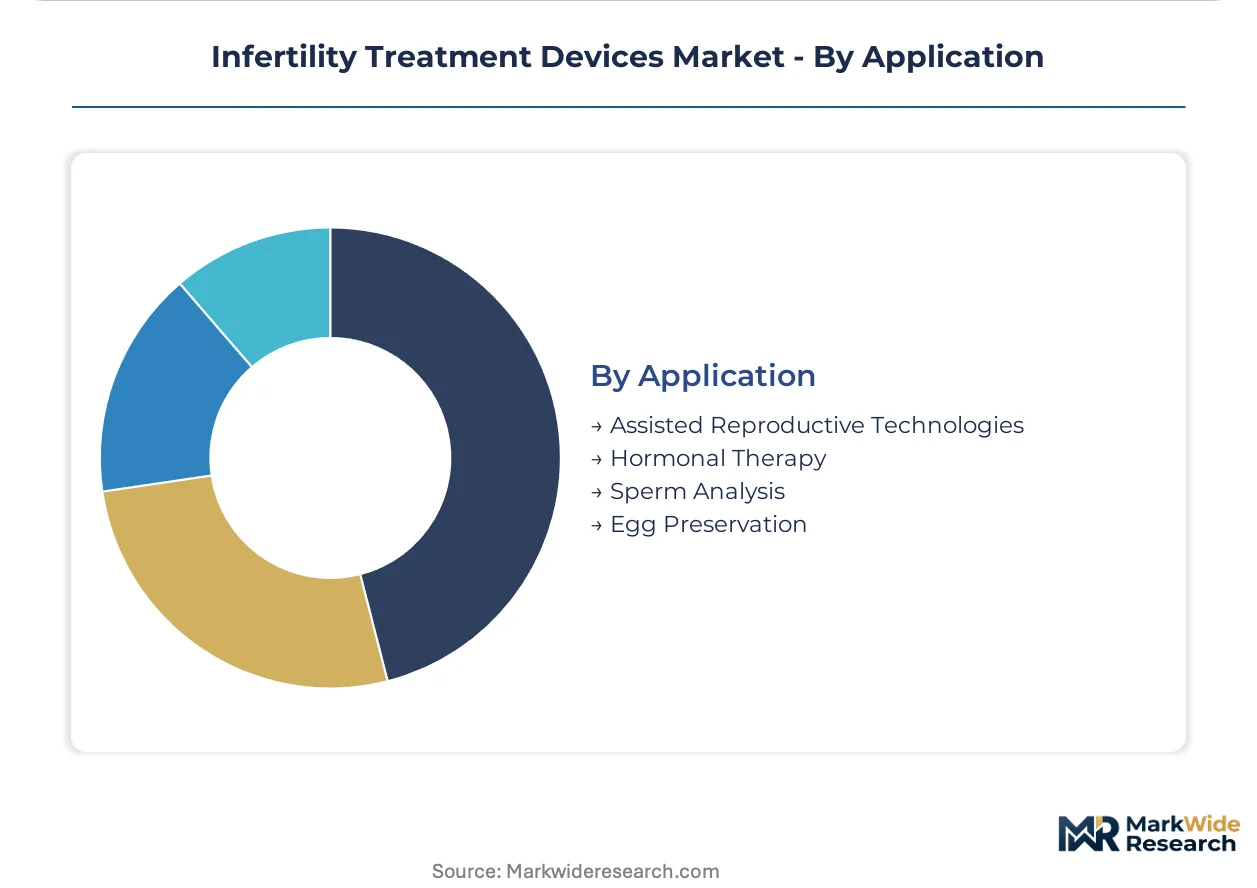
- Assisted Reproductive Technologies:IVF, ICSI, and related clinical procedures constitute the core revenue-generating application with established CPT coding and insurance coverage pathways. German public health funding directly influences ART cycle volume and associated device procurement.
- Egg Preservation:Elective oocyte cryopreservation for fertility deferral is gaining procedural volume among younger patients without immediate infertility diagnoses. United States employer-sponsored benefits expansion is accelerating clinic infrastructure investment.
- Hormonal Therapy:Ovarian stimulation and luteal support protocols utilize programmable delivery systems.
- Sperm Analysis:Diagnostic semen assessment and sperm preparation techniques support treatment planning.
Dominant revenue share: Assisted Reproductive Technologies. Gaining share fastest: Egg Preservation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American reproductive medicine infrastructure, hosting flagship fertility centers that set procurement standards for embryology equipment nationwide.
United States
Employer-sponsored fertility benefits and elective egg freezing are driving cryopreservation infrastructure expansion across metropolitan clinic networks. FDA 510(k) pathways for embryo culture platforms compress clearance timelines, accelerating commercial deployment. New York and California fertility corridors concentrate high-throughput laboratories adopting time-lapse monitoring systems.
Germany
Public reimbursement frameworks for ART cycles directly influence capital equipment budgets at university-affiliated reproductive centers. EMA Medical Device Regulation reclassification of embryo culture devices extends conformity assessment timelines by 12-18 months. Bavarian reproductive medicine clusters are consolidating supplier relationships to streamline compliance cost burdens.
Japan
Metropolitan clinic networks are unbundling traditional equipment contracts into separate hardware, software, and consumables agreements to improve cash-flow predictability. PMDA quality standards for assisted reproductive technologies shape product development requirements. Tokyo and Osaka fertility centers lead adoption of automated vitrification systems to reduce technician-dependent variability.
United Kingdom
Private fertility clinic chains are expanding laboratory capacity amid National Health Service waiting list pressures for ART services. MHRA post-Brexit regulatory frameworks maintain alignment with EMA MDR standards for embryo culture media. London and Greater Manchester reproductive medicine hubs drive procurement of modular incubator upgrade paths.
Australia
Regional fertility clinic networks are investing in satellite laboratory infrastructure to extend service reach beyond major metropolitan centers. TGA medical device classifications for laser-assisted hatching systems align with ISO 13485 quality management requirements. Sydney and Melbourne embryology laboratories anchor demand for integrated micromanipulation platforms.
Infertility Treatment Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory certification depth and embryology workflow integration complexity. The vendor base organizes into three tiers: analytical instrument heritage companies commanding high-complexity platforms, clinic-channel specialists with deep consumables integration, and regional equipment fabricators serving price-sensitive markets. Two dominant competitive moves are reshaping positioning: strategic partnerships between device manufacturers and culture media suppliers, plus geographic expansion through distributor acquisition in underserved metropolitan corridors.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions reflecting analytical instrument heritage applied to embryology workflows. CooperSurgical represents the clinic-channel integration archetype, anchoring North American procurement relationships through consumables bundling. Vitrolife AB exemplifies the specialized media and time-lapse equipment model that commands sustained pricing power in European ART centers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| CooperSurgical |
| Kitazato Corporation |
| FUJIFILM Irvine Scientific |
| Vitrolife AB |
| Hamilton Thorne |
| Rocket Medical |
| Cook Medical |
| Others |
Cost & Logistics Intelligence
EMA MDR sustainability and quality compliance mandates gate qualified supply access for embryo culture media manufacturers, restricting premium-tier pricing power to vendors with established pharmacovigilance infrastructure while excluding mid-scale competitors from high-margin European ART center contracts.
Pricing Analysis
Value-based pricing anchored to live birth rate outcomes and embryology workflow throughput dominates IVF equipment procurement, with clinics paying premium tiers for time-lapse systems demonstrating superior implantation yields. Price differentiation separates FDA 510(k)-cleared platforms from CE-marked alternatives, while volume scale discounts apply to metropolitan clinic networks. Pricing pressure stems from unbundled service contracts as Japanese fertility centers negotiate separate hardware, software, and consumables agreements. Independent fertility clinics exhibit highest price sensitivity; university-affiliated reproductive centers show lowest sensitivity due to public reimbursement buffers.
Supply Chain Analysis
Warehouse-distribution layers for cryogenic storage equipment concentrate in regional hubs serving United States metropolitan corridors, Germany's Bavarian reproductive medicine clusters, and Japan's Tokyo-Osaka fertility center networks. Specialized culture media formulations draw from Northern European chemical synthesis capabilities, while precision micromanipulation components source from Japanese optical manufacturing and German medical device fabrication. Single-source vulnerability pervades vitrification solution supply, with batch variability creating downstream clinic workflow disruption. Distribution runs through direct-to-clinic consumables subscription models bypassing traditional distributor markups in saturated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Time-lapse imaging systems are displacing static embryo observation methods, forcing equipment architectures toward adaptive data-integrated designs that compress the timeline between fertilization and transfer decisions.
For Market Incumbents: Deploy consumables bundling as the defensive lever to anchor clinic relationships against modular upgrade architectures threatening full system replacement cycles. Deepen integration with automated embryo biopsy platforms to capture preimplantation genetic testing workflow volume. Invest in ISO 13485 quality management infrastructure to absorb EMA MDR surveillance audit burdens that strain mid-scale competitors. For New Entrants and Emerging Players: Launch via direct-to-clinic consumables subscription models targeting United States metropolitan fertility corridors where traditional distributor markups create pricing whitespace. Target elective fertility preservation segments among younger patient cohorts pursuing deferred reproduction timelines. Pursue automated vitrification system development to reduce technician-dependent variability in high-throughput Japanese ART centers. For Investors and Strategic Acquirers: Germany's proposed public funding expansion for ART cycles is the leading indicator that capital equipment budgets at university-affiliated reproductive centers will unlock substantial procurement velocity. Long-term viability centers on vendors combining hardware platforms with recurring media revenue streams. Monitor FDA 510(k) clearance timelines for embryo culture platforms as the signal for commercial deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Morphokinetics Development | Machine vision algorithms from Hamilton Thorne reduce subjective embryologist assessment variability in time-lapse workflows. |
| Reimbursement Strategy Alignment | German public health funding frameworks directly influence ART cycle volume and associated device procurement budgets. |
| CE Marking Pathway Investment | EMA MDR conformity assessment procedures extend certification timelines, favoring established regulatory infrastructure. |
| Hospital System Partnership | Academic medical centers integrate reproductive medicine within obstetrics-gynecology departments favoring multi-purpose equipment. |
| Software Companion Development | Time-lapse software licenses unbundled from incubator hardware improve cash-flow predictability for Japanese clinic networks. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, EMA MDR certification trajectories, and ART cycle reimbursement policy shifts anchored the trend analysis, supplemented by interviews with embryology laboratory directors, fertility clinic procurement managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from FDA device filings, EMA medical device regulation updates, hospital procurement databases, and CMS Medicare fertility treatment coverage data. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Segment-weighting across device type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle analysis and elective fertility preservation demand elasticity modeling. Forecast inputs incorporated time-lapse imaging adoption curves, automated vitrification system penetration rates, and unbundled contract proliferation patterns.
Regulatory reclassification delays, reimbursement policy reversals, and culture media batch contamination events are the dominant revision risks that could compress or extend commercial deployment timelines. Forecasts reflect documented assumptions regarding ISO 13485 audit burden absorption and PMDA quality standard harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Thermometer Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
C-Arms Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Nanomedical Devices Market