
 Italy Artificial Organs and Bionic Implants Market | 2026-2036
Italy Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Artificial Organs and Bionic Implants Market Foresight
Remote patient monitoring subscriptions for implantable cardiac devices is restructuring how Italian hospitals contract for long-term care. Medtronic leverages its integrated device-monitoring platform to anchor recurring revenue streams across Lombardy's cardiology networks. LivaNova, PLC specializes in neuromodulation service contracts that sustain multi-year relationships with epilepsy centers in northern Italy. Boston Scientific Corporation competes through software-upgradeable implant architectures that extend product lifecycles without replacement surgery.
Artificial organs and bionic implants encompass electromechanical and biological substitute systems engineered to restore physiological functions lost to disease or trauma, typically incorporating biocompatible alloys, polymers, or living tissue constructs manufactured under ISO 13485 cleanroom protocols. These devices serve critical therapeutic purposes in organ failure, sensory impairment, and musculoskeletal disability across acute and chronic care settings. Cardiac implants occupy the dominant revenue position given Italy's aging demographic burden and established interventional cardiology infrastructure, while neuroprosthetics represent the fastest-expanding margin pool as spinal cord stimulation and deep brain therapy gain AIFA coverage. Orthopedic bionic devices concentrate demand in trauma surgery applications where 3D printing technology enables patient-specific implant geometries that reduce revision rates.
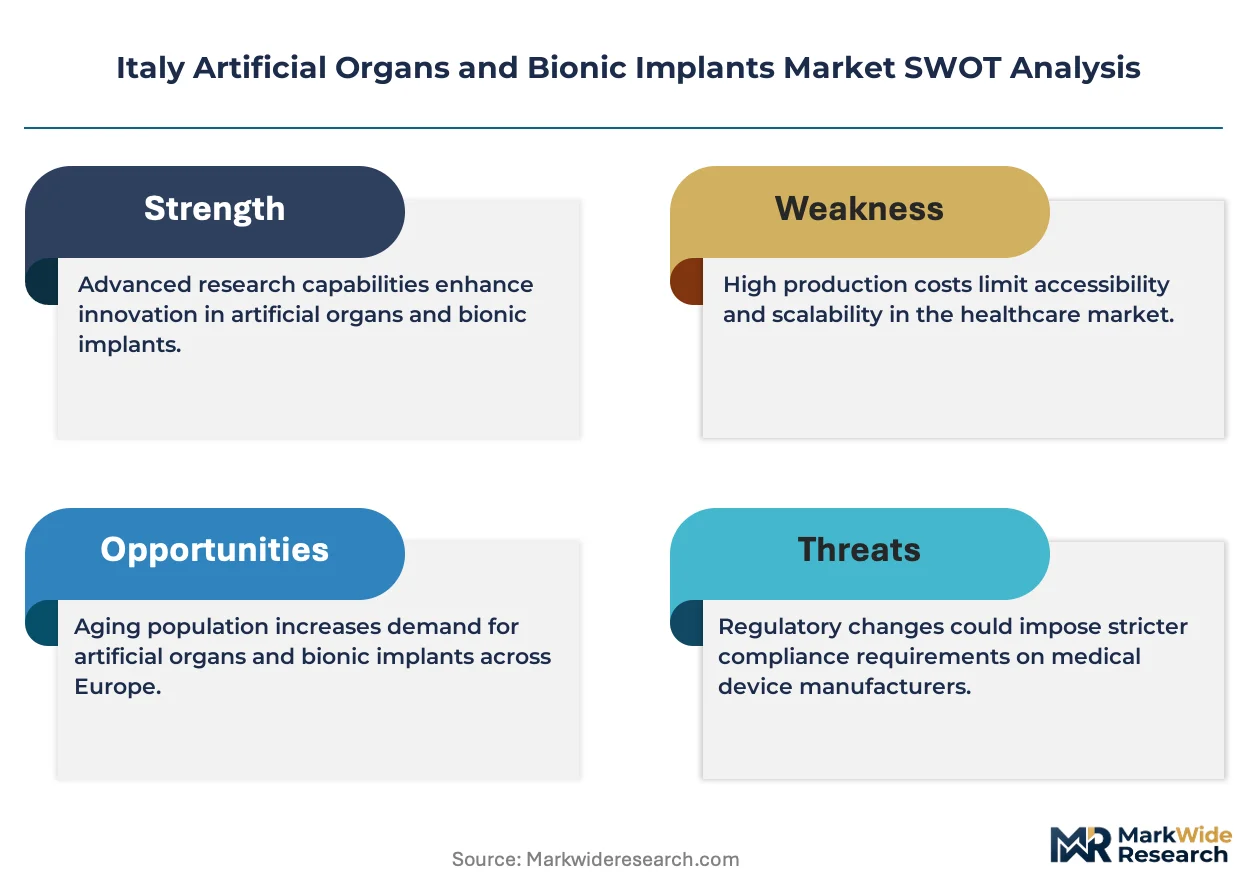
AIFA, the Italian Medicines Agency, governs pre-market authorization and reimbursement classification for high-risk implantable devices, while MDR compliance through notified bodies in Milan and Rome shapes technical documentation requirements for CE-marked products. Italy's Ministry of Health periodically updates the national essential devices list, directly determining which bionic categories receive public hospital funding and regional procurement eligibility. Stakeholders must monitor AIFA's parallel pathway for breakthrough device designation, as faster reimbursement decisions will reshape competitive dynamics for novel neuroprosthetic and artificial organ entrants before rival systems establish clinical evidence portfolios.
Market Dynamics
Remote patient monitoring subscriptions for implantable cardiac devices are restructuring how Italian hospitals contract for long-term care, shifting capital expenditure models toward recurring service relationships anchored by software platforms.
Growth Catalysts
- AIFA Reimbursement Pathways:The Italian Medicines Agency's accelerated coverage decisions for breakthrough devices compress patient access timelines for novel neuroprosthetic systems.
- Lombardy Cardiovascular Clusters:Milan's interventional cardiology infrastructure generates concentrated demand for next-generation cardiac implants and associated monitoring services.
- 3D Printing in Trauma Surgery:Patient-specific orthopedic implant geometries manufactured via additive processes reduce revision rates and drive replacement cycle compression.
Market Restraints
- Titanium Alloy Supply Concentration:Biocompatible metal feedstock for implant manufacturing concentrates among a limited supplier base, exposing producers to input cost volatility.
- MDR Technical Documentation Burden:The EU Medical Device Regulation's expanded clinical evidence requirements extend CE-marking timelines for high-risk implantable devices.
- Biological Substitute Competition:Tissue-engineered organ alternatives and regenerative medicine approaches threaten long-term demand for electromechanical artificial organs.
Strategic Opportunities
- Emilia-Romagna Neuroprosthetic Expansion:Bologna's established epilepsy and movement disorder centers present underpenetrated demand for deep brain stimulation systems.
- Software-Upgradeable Architectures:Firmware-enhanceable implant designs enable lifecycle extension without surgical replacement, creating recurring revenue streams.
- Regional Procurement Consolidation:Northern Italy's hospital network integration creates channel concentration favorable to integrated device-monitoring platform vendors.
Industry Challenges
- ISO 13485 Cleanroom Specialist Scarcity:Qualified manufacturing engineers for implantable device production remain concentrated among limited training programs.
- Legacy System Integration Complexity:New monitoring platforms face interoperability friction with existing hospital information systems across fragmented regional networks.
- Extended Clinical Trial Timelines:Long-term safety data requirements for permanent implants delay market entry for novel artificial organ designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Artificial Organs and Bionic Implants Market |
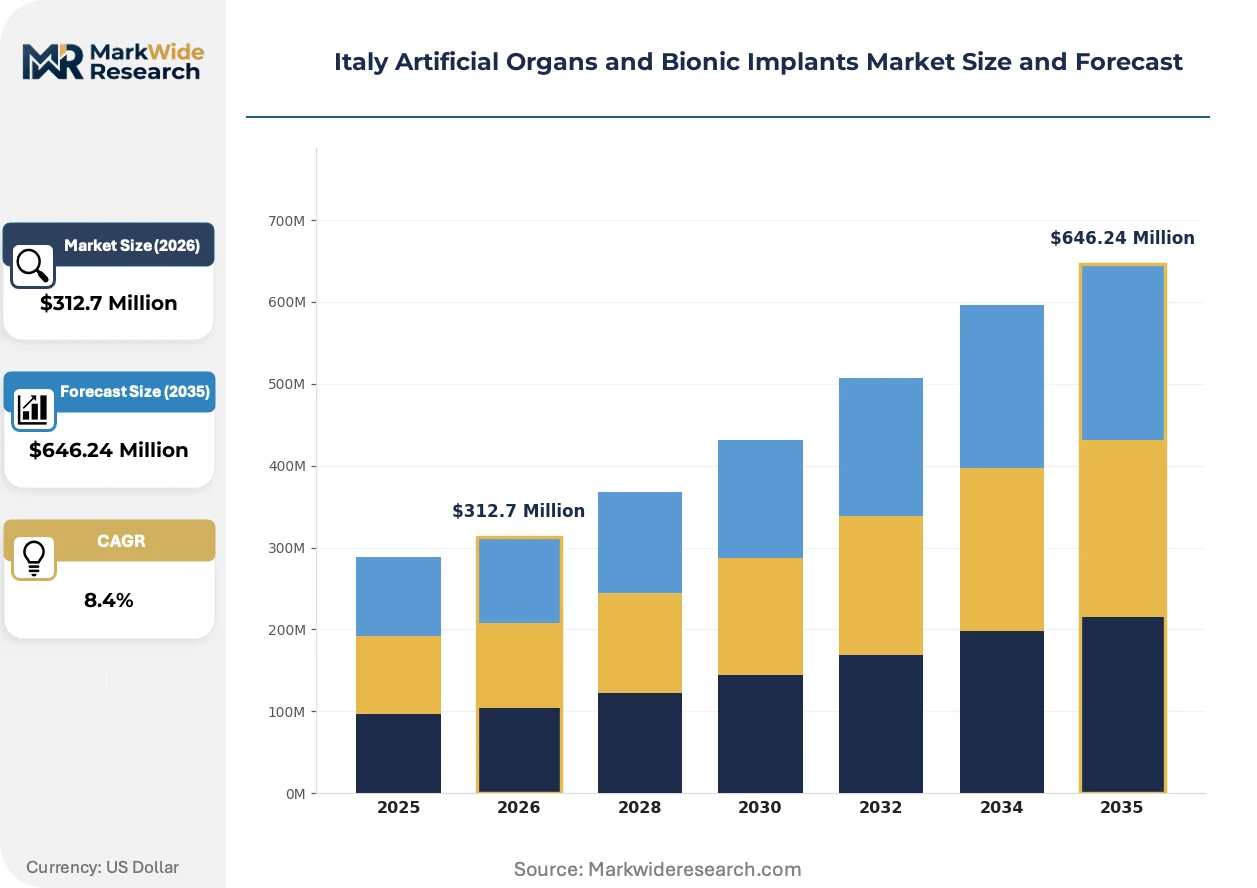
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $646.24 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Neuroprosthetics, Orthopedic Devices, Artificial Organs End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Home Care Technology: 3D Printing, Bioprinting, Stem Cell Therapy, Nano-coating Application: Trauma Surgery, Cosmetic Surgery, Organ Replacement, Pain Management |
| Companies Covered | Cochlear Ltd, Abiomed Inc., Berlin Heart, Össur, LivaNova, PLC, Medtronic, Getinge AB, Ekso Bionics, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Artificial Organs and Bionic Implants Market Shifts & Advancements
Biocompatible polymer formulations and wireless energy transfer systems are actively displacing traditional implant architectures, while regulatory frameworks accelerate differentiation between premium-connected and standard-device tiers.
Closed-loop neurostimulation systems with embedded biosensors are expanding into movement disorder and epilepsy treatment protocols. Leading neurology centers in northern Italy are piloting these platforms for real-time symptom adjustment. The technology is expanding into service contract structures that capture multi-year patient relationships and displace conventional device-only procurement.
AIFA's parallel pathway for breakthrough device designation compresses reimbursement classification timelines for novel implantable systems. The policy creates first-mover advantages for neuroprosthetic entrants that establish clinical evidence portfolios before rival systems complete traditional review. Deep brain stimulation and spinal cord therapy categories are responding with accelerated pre-market engagement strategies.
Hospital procurement departments in Lombardy and Emilia-Romagna are unbundling device acquisition from long-term monitoring services. Cardiology networks now contract separately for implant placement and remote patient management, favoring vendors with integrated software platforms. This behavioral shift concentrates contract value in northern Italy's cardiovascular surgery clusters around Milan and Bologna.
Italy Artificial Organs and Bionic Implants Market Segmentation
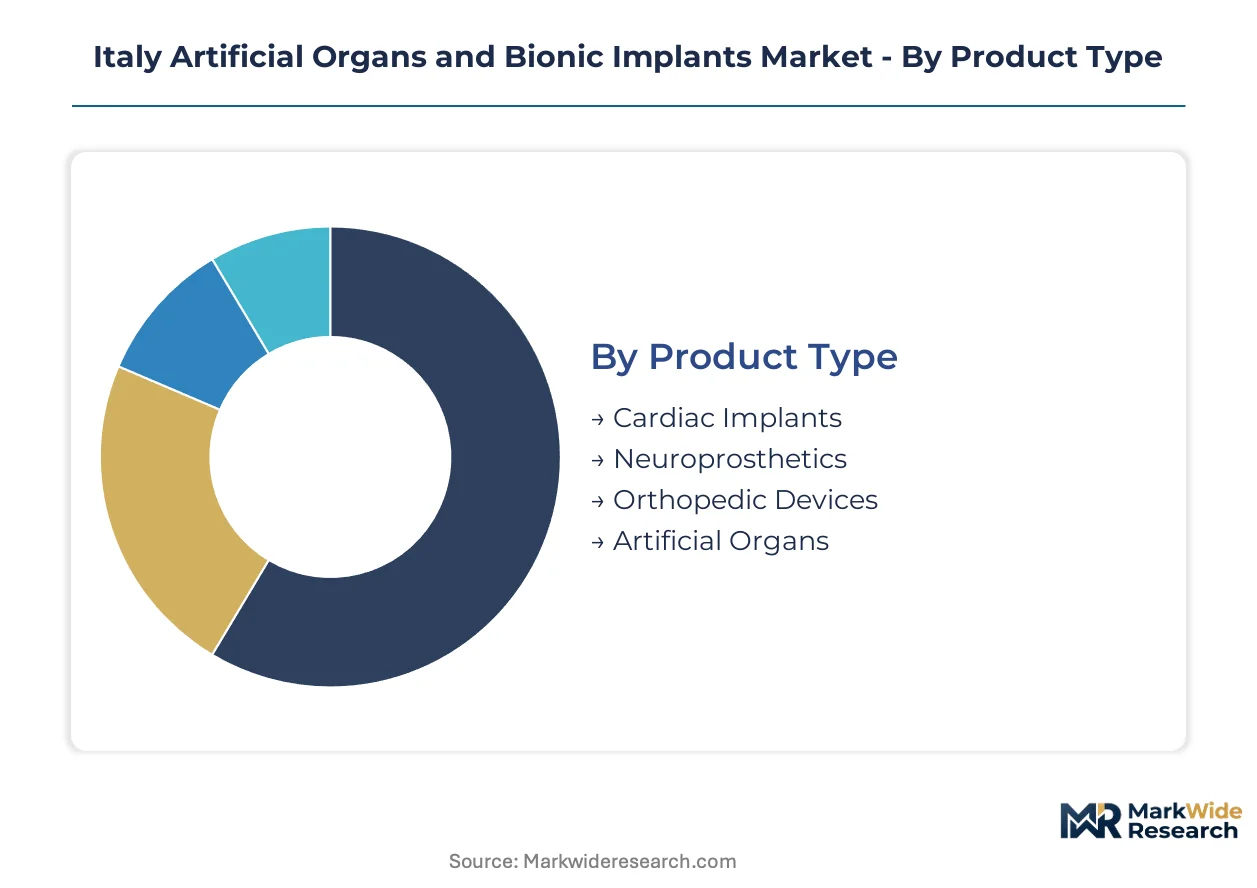
Segmentation in Italy's artificial organs and bionic implants market reveals distinct capital requirements, reimbursement pathways, and procurement behaviors across product categories. Understanding these divisions enables targeted positioning within AIFA-regulated procurement channels and regional hospital networks.
Product Type:
Capital intensity varies sharply across implant categories, with cardiac and neuroprosthetic systems demanding substantially higher upfront manufacturing investment than orthopedic alternatives.
- Cardiac Implants:These electromechanical systems—encompassing pacemakers, ICDs, and ventricular assist devices—incorporate biocompatible titanium housings, lithium-iodine batteries, and wireless telemetry modules manufactured under ISO 13485 protocols. Lombardy's cardiovascular surgery clusters around Milan absorb the dominant share of procurement volume, driven by an aging demographic and established interventional cardiology infrastructure.
- Neuroprosthetics:Deep brain stimulation and spinal cord modulation systems feature programmable pulse generators with embedded biosensors for closed-loop therapy adjustment. Bologna's epilepsy and movement disorder centers in Emilia-Romagna generate concentrated demand as AIFA accelerates reimbursement pathways for breakthrough neuromodulation devices.
- Orthopedic Devices:Patient-specific trauma implants leverage 3D-printed titanium geometries to reduce revision rates in fracture repair.
- Artificial Organs:Mechanical circulatory support and wearable renal replacement systems address organ failure through electromechanical rather than biological substitution.
Cardiac implants absorb the bulk of installed capacity; neuroprosthetics are expanding most quickly.
End User:
Procurement authority concentrates differently across settings, with public hospital networks controlling high-value implant decisions while surgical centers focus on volume throughput.
- Hospitals:Lombardy and Emilia-Romagna's regional health systems dominate cardiac and neuroprosthetic procurement through centralized tendering processes that bundle device acquisition with long-term monitoring service contracts.
- Surgical Centers:These facilities concentrate on high-volume orthopedic trauma procedures where 3D-printed implant geometries enable same-day surgical planning.
- Rehabilitation Facilities:Post-implant recovery centers coordinate with acute care hospitals for neuroprosthetic programming and parameter optimization.
- Home Care:Remote patient monitoring platforms for implantable cardiac devices extend care delivery beyond institutional settings.
Hospitals command the majority of procurement value; home care is gaining share fastest as remote monitoring subscriptions restructure contracting models.
Technology:
Manufacturing process selection directly determines regulatory classification timelines and cleanroom capital requirements under MDR compliance frameworks.
- 3D Printing:Additive manufacturing of patient-specific titanium orthopedic implants enables geometric complexity impossible with conventional machining, reducing revision rates in trauma surgery applications.
- Bioprinting:Layered deposition of living cells and biocompatible scaffolds produces tissue-engineered constructs that threaten long-term demand for electromechanical artificial organs.
- Stem Cell Therapy:Regenerative approaches for cardiac and neural tissue repair compete with permanent implantable devices.
- Nano-coating:Surface modification technologies improve biocompatibility and reduce thrombogenicity in blood-contacting implant surfaces.
3D printing anchors current manufacturing investment; bioprinting shows the steepest expansion trajectory as tissue-engineered alternatives advance.
Application:
Clinical indication shapes reimbursement velocity and evidence requirements, with life-sustaining applications receiving priority coverage decisions from AIFA.
- Trauma Surgery:Emergency orthopedic interventions in northern Italy's hospital networks drive demand for rapid-turnaround 3D-printed patient-specific implants.
- Cosmetic Surgery:Aesthetic applications face stricter reimbursement scrutiny and longer AIFA classification timelines.
- Organ Replacement:Mechanical circulatory support and artificial kidney systems address end-stage organ failure with life-sustaining therapeutic intent.
- Pain Management:Spinal cord stimulation for chronic refractory pain expands through service contract structures that capture multi-year patient relationships.
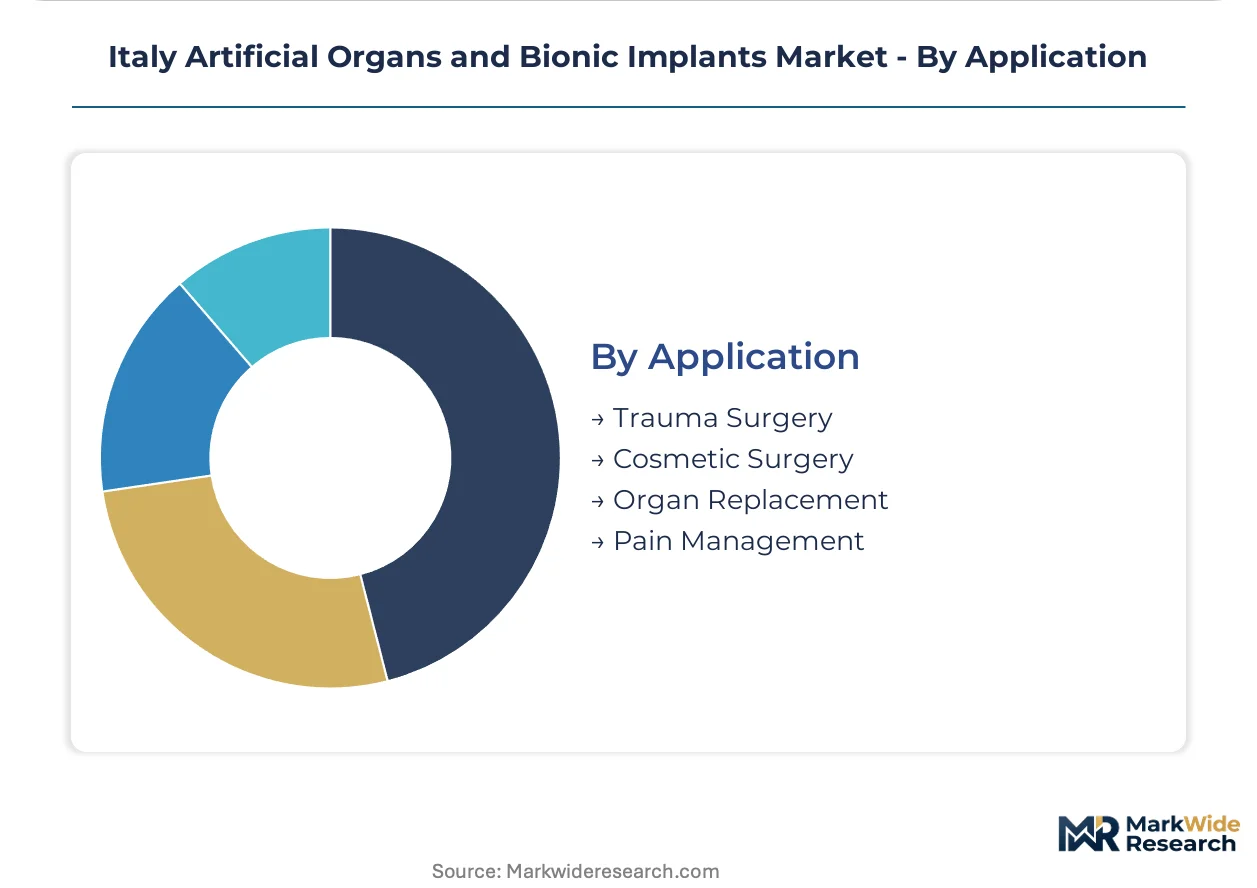
Trauma surgery and organ replacement together dominate procedure volume; pain management applications are climbing the fastest as spinal cord stimulation gains AIFA coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's artificial organs and bionic implants production concentrates in Lombardy and Emilia-Romagna, while consumption spreads across northern cardiovascular surgery clusters that absorb the bulk of cardiac and neuroprosthetic procurement.
Lombardy
Milan's interventional cardiology infrastructure generates concentrated demand for pacemakers, ICDs, and ventricular assist devices. AIFA's national reimbursement pathways determine which cardiac implants receive public hospital funding across the region's health system. The city's cardiovascular surgery networks are unbundling device acquisition from remote monitoring services, favoring vendors with integrated software platforms.
Emilia-Romagna
Bologna's epilepsy and movement disorder centers drive neuroprosthetic expansion, particularly for deep brain stimulation systems. The Italian Medicines Agency's accelerated coverage decisions for breakthrough devices compress patient access timelines for novel neuromodulation entrants. Regional procurement consolidation is creating channel concentration favorable to integrated device-monitoring platform vendors.
Piedmont
Turin's medical device manufacturing base supplies biocompatible titanium components and lithium-iodine battery systems to implant producers. MDR compliance through notified bodies in Milan and Rome shapes technical documentation requirements for CE-marked products originating from the region. Local cleanroom facilities operate under ISO 13485 protocols for high-risk implantable device production.
Veneto
Verona and Padua host trauma surgery centers adopting 3D-printed patient-specific orthopedic implants for fracture repair. The Ministry of Health's periodic updates to the national essential devices list determine which bionic categories receive public hospital funding in the region. Additive manufacturing specialists are reducing revision rates through geometric complexity impossible with conventional machining.
Lazio
Rome's notified bodies and regulatory consulting services support CE-marking timelines for implantable devices entering the Italian market. AIFA's parallel pathway for breakthrough device designation creates first-mover advantages for neuroprosthetic entrants establishing clinical evidence portfolios. The capital's regulatory infrastructure shapes national compliance frameworks that cascade to regional hospital procurement.
Italy Artificial Organs and Bionic Implants Market Competitive Landscape
Top-tier vendors anchor integrated device-monitoring platforms, while mid-tier specialists compete through software-upgradeable implant architectures and neuromodulation service contracts. The market structure reflects concentrated procurement authority within Lombardy and Emilia-Romagna's regional health systems. Three archetypes dominate: platform-integrated cardiac device vendors, neuromodulation service contract specialists, and 3D-printed orthopedic implant manufacturers. Competitive moves center on M&A for monitoring software capabilities and strategic partnerships with northern Italy's hospital networks.
Within the platform-integrated tier, Medtronic and Boston Scientific Corporation exemplify vendors leveraging recurring revenue streams through remote patient monitoring subscriptions. LivaNova, PLC occupies a position among neuromodulation specialists sustaining multi-year relationships with epilepsy centers. These three companies represent distinct competitive vectors—device-platform integration, service contract anchoring, and software-upgradeable architectures—that are reshaping how Italian hospitals contract for long-term implant care.
| Leading Market Players |
|---|
| Cochlear Ltd |
| Abiomed Inc. |
| Berlin Heart |
| Össur |
| LivaNova, PLC |
| Medtronic |
| Getinge AB |
| Ekso Bionics |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Titanium sponge price indices cascading through Italian implant manufacturing determine how procurement tiers separate premium-connected cardiac systems from standard-device categories. Input cost volatility in biocompatible metal feedstock compresses margins for mid-tier producers while platform-integrated vendors absorb fluctuations through long-term service contract structures.
Pricing Analysis
Margin tightening in standard-device tiers reflects MDR compliance cost absorption and ISO 13485 cleanroom specialist scarcity. Three-tier pricing structure across premium-connected, standard CE-marked, and economy-device levels stratifies by telemetry capability and AIFA reimbursement velocity. Pricing pressure stems from regional procurement consolidation in Lombardy and Emilia-Romagna. Academic medical centers demonstrate lowest price sensitivity; community hospitals face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Milan and Bologna operate hub-and-spoke patterns radiating to cardiovascular surgery clusters across northern Italy. Manufacturing draws from titanium alloy suppliers in Germany and the United States, lithium-iodine battery cell producers in Japan, and biocompatible polymer compounders in Switzerland. Single-source vulnerability in titanium sponge refining exposes producers to commodity price swings. Distribution runs through GPO-affiliated logistics networks serving consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-integrated vendors as AIFA reimbursement pathways favor early clinical evidence portfolios and MDR compliance costs eliminate marginal producers.
For Market Incumbents: Cement dominance through backward integration into biocompatible titanium component manufacturing and captive supply of lithium-iodine battery systems. Deepen software platform stickiness by unbundling device acquisition from mandatory multi-year remote monitoring subscriptions. Defend against tissue-engineered organ substitutes by accelerating firmware-upgradeable implant architectures that extend surgical replacement cycles. For New Entrants and Emerging Players: Begin with underpenetrated neuroprosthetic service contracts in Emilia-Romagna's epilepsy centers, where AIFA breakthrough designation creates first-mover windows before rival evidence portfolios mature. Target 3D-printed patient-specific orthopedic trauma implants in Veneto's same-day surgical planning workflows. Pursue white-label manufacturing partnerships with Piedmont's ISO 13485 cleanroom facilities to bypass capital intensity barriers. For Investors and Strategic Acquirers: The window for entry favors neuromodulation service contract specialists with established Bologna epilepsy center relationships and software-upgradeable implant IP. Long-term viability hinges on AIFA reimbursement velocity rather than device innovation cycles alone. Monitor AIFA's parallel pathway approval velocity as the inflection signal for portfolio rebalancing between electromechanical and biological substitute exposures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation through Milan and Rome notified bodies determines market access timelines for high-risk implants. |
| Hospital System Partnership | Lombardy cardiology network integration creates procurement concentration favoring integrated device-monitoring platform vendors. |
| Software Companion Development | Remote patient monitoring applications restructure contracting from capital expenditure to recurring service relationships. |
| Reimbursement Strategy | AIFA parallel pathway engagement compresses coverage decisions for breakthrough neuroprosthetic and artificial organ entrants. |
| Backward Integration | In-house production of biocompatible titanium housings and lithium-iodine battery systems defends margin position against feedstock volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and AIFA regulatory affairs specialists combined with secondary validation from EU MDR submission databases, AIFA reimbursement classification records, and Italian Ministry of Health procurement disclosures. Bottom-up installed base modeling and top-down healthcare expenditure triangulation reconciled volume and value estimates.
Data-stream reconciliation across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating AIFA reimbursement velocity, MDR compliance timeline assumptions, and regional procurement consolidation patterns. Forecast inputs included ISO 13485 cleanroom capacity expansion plans and 3D printing adoption curves in trauma surgery centers.
Underlying measurement precision varies by segment; cardiac implants and neuroprosthetics carry tighter precision than orthopedic devices due to consolidated procurement data availability. Forecasts reflect assumptions regarding AIFA breakthrough designation approval rates and MDR notified body capacity constraints. Periodic stress-testing of base assumptions against biological substitute technology advancement timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Submucosal Injections Market
Medical Devices
Reusable Medical Battery Market