
 North America Medical Device Reprocessing Market | 2026-2036
North America Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Device Reprocessing Market Analytics
The gap between premium validated reprocessing and commodity cleaning services is expanding. Stryker leverages its vertically integrated reprocessing infrastructure to dominate high-margin cardiovascular device categories. Medline Industries anchors its position through hospital-centric distribution networks that bundle reprocessing with broadline supply contracts. Cardinal Health competes by extending logistics capabilities into reverse supply chain collection and tracking systems for regulated devices.
Medical device reprocessing encompasses the collection, cleaning, functional testing, sterilization, and repackaging of previously used medical devices to render them suitable for additional clinical use, with steam sterilization cycles typically requiring exposure to saturated steam at 121°C for 15–30 minutes depending on load configuration. The primary purpose is to reduce healthcare acquisition costs while maintaining device performance equivalent to original manufacture. Cardiovascular devices command the largest revenue share due to high unit costs and established FDA reclassification pathways for specific catheter families. Automated reprocessing systems are gaining fastest within the technology dimension as facilities seek to reduce human factor variability in high-volume sterilization workflows. Endoscopy devices represent a concentrated margin pool given the complexity of flexible scope channel cleaning and the liability exposure from inadequate high-level disinfection.
FDA's Quality System Regulation and the Medical Device Reporting framework govern reprocessor validation requirements, while Health Canada's Medical Devices Bureau enforces parallel establishment licensing standards for cross-border service providers. These frameworks shape demand by mandating extensive performance testing that elevates barriers for uncertified entrants. State-level variations in Medicaid reimbursement policy for reprocessed devices create additional complexity for national contract structuring. Stakeholders must monitor evolving FDA guidance on reprocessing of single-use devices labeled for one-time use, as any restriction expansion would immediately reshape addressable volume across the service landscape.
Market Dynamics
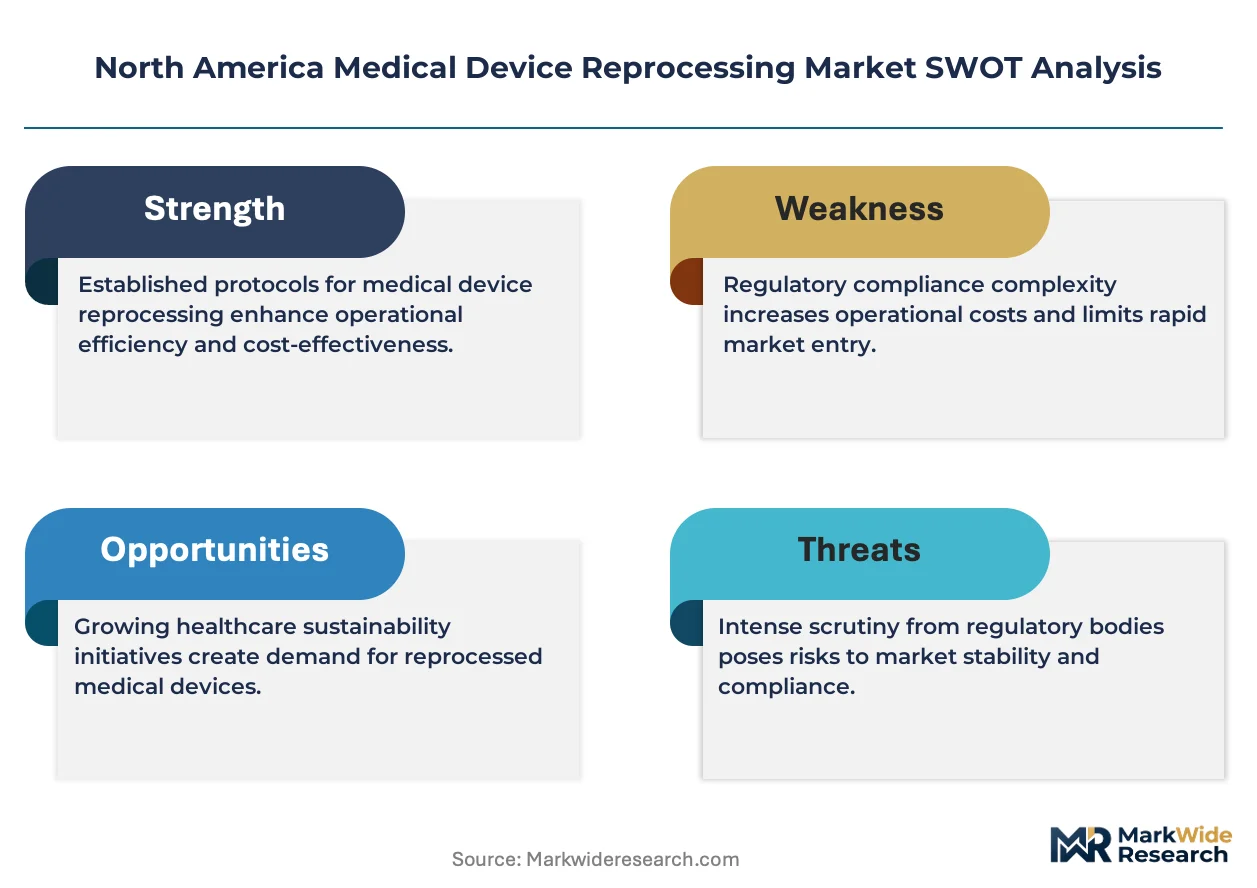
FDA's intensified scrutiny of single-use device revalidation protocols is compressing third-party reprocessor margins while favoring vertically integrated hospital service models that control end-to-end quality documentation.
Growth Catalysts
- Medicaid reimbursement policy:State-level coverage expansion for reprocessed cardiovascular catheters in Texas, Florida, and California is pulling volume from virgin device purchasing.
- Automated high-level disinfection systems:Endoscopy suites in Ontario and Quebec are deploying closed-loop washer-disinfectors to reduce human factor variability in flexible scope channel cleaning.
- Ambulatory surgical center proliferation:United States outpatient facilities are accelerating adoption of reprocessed laparoscopic instruments to manage per-procedure supply cost targets.
Market Restraints
- Ethylene oxide sterilization capacity concentration:Centralized EtO processing facilities in Illinois and Georgia create geographic supply vulnerability for reprocessors dependent on outsourced terminal sterilization.
- FDA Quality System Regulation compliance costs:Extensive performance testing requirements for single-use device reclassification elevate barriers for uncertified market entrants.
- Original equipment manufacturer lock-out technologies:Proprietary connector designs and embedded authentication chips in next-generation cardiovascular catheters threaten physical reprocessing feasibility.
Strategic Opportunities
- Underpenetrated Canadian provinces:Alberta and British Columbia health authorities are evaluating sterilization service outsourcing models established in Ontario and Quebec.
- Electrophysiology device reprocessing:Diagnostic and ablation catheters represent an emerging application category with established FDA predicate pathways but limited commercial penetration.
- Hospital-owned reprocessing subsidiary formation:IDN consolidation is creating captive supply structures that internalize margin capture previously flowing to third-party vendors.
Industry Challenges
- Biocompatibility testing technician shortage:Cytotoxicity and sensitization assay expertise is concentrated among a limited pool of ISO 10993-qualified laboratory personnel.
- Legacy sterilization validation documentation:Paper-based batch records and non-integrated quality management systems impede real-time traceability for FDA inspection readiness.
- Cross-border Health Canada establishment licensing:United States reprocessors face extended timeline friction for Canadian provincial contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Device Reprocessing Market |
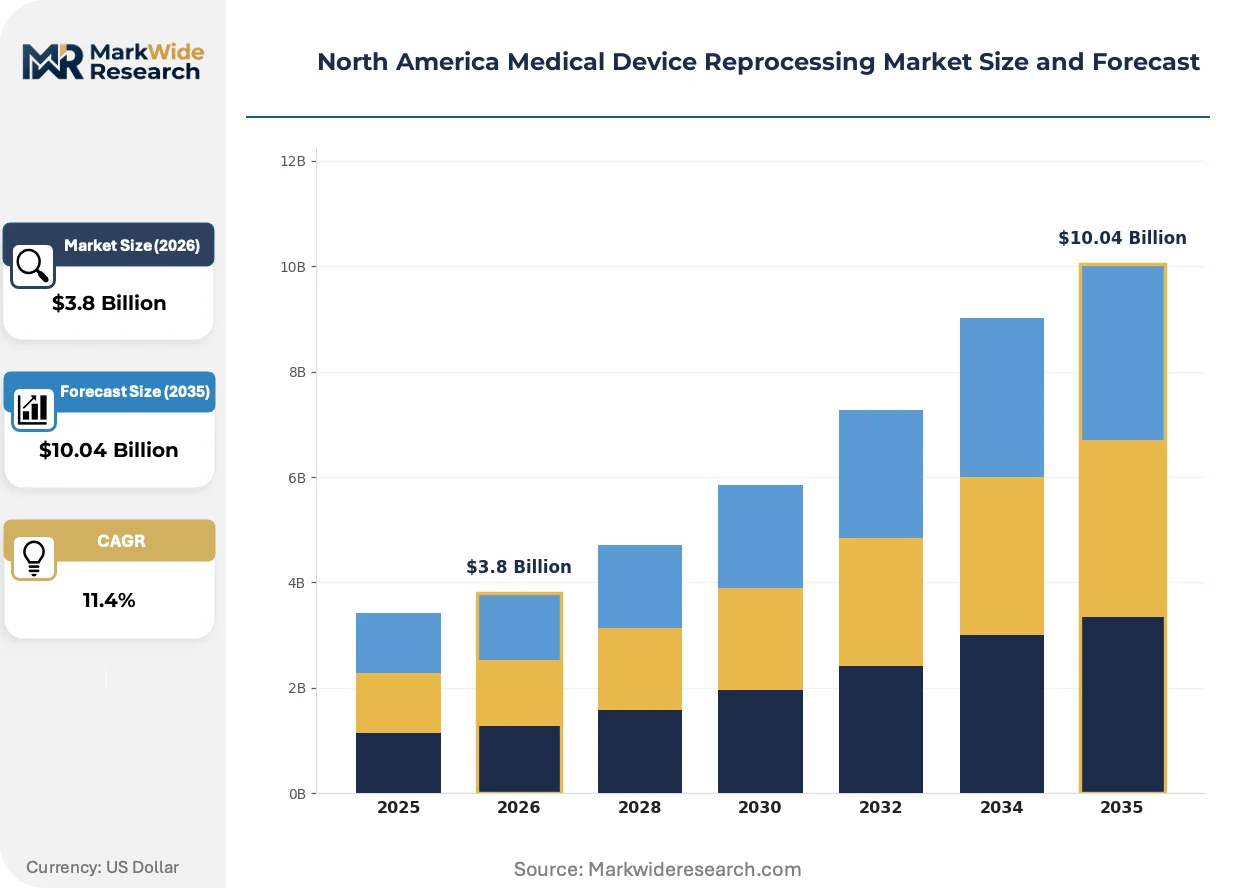
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiovascular Devices, Surgical Instruments, Endoscopy Devices, Neurology Devices Service Type: Transportation, Cleaning, Packaging, Sterilization End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Technology: Manual Reprocessing, Automated Reprocessing, Chemical Disinfection, Steam Sterilization |
| Companies Covered | Stryker, Medline Industries, SureTek Medical, ReNu Medical, Arjo, NEScientific, Cardinal Health, SterilMed, Soma Tech Intl, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Device Reprocessing Market Evolving Landscape
Reprocessing workflows are converging with digital quality infrastructure and closed-loop sterilization technologies that compress cycle variability while expanding device category eligibility.
Closed-loop automated washer-disinfector systems are integrating RFID-enabled load tracking with real-time conductivity and temperature monitoring to eliminate manual documentation gaps. United States hospital sterile processing departments are deploying these platforms in high-volume cardiovascular catheter workflows. The technology is integrating quality data streams directly into electronic health record interfaces, compressing audit preparation timelines and reducing FDA inspection observation rates.
Health Canada's Medical Devices Bureau is tightening establishment licensing standards for cross-border reprocessors serving Ontario and Quebec health systems. The policy shift requires on-site quality system audits that were previously waived under mutual recognition arrangements. United States-based third-party reprocessors are responding by establishing dedicated Canadian subsidiary entities with captive sterilization capacity to maintain provincial contract eligibility.
Hospital procurement committees are consolidating reprocessing vendor relationships under multi-year enterprise agreements that bundle device collection, testing, and sterilization into per-procedure unit pricing. Group purchasing organizations are displacing spot-market purchasing for cardiovascular and endoscopy categories. This concentration is most visible in United States integrated delivery networks with centralized supply chain governance structures spanning multiple states.
North America Medical Device Reprocessing Market Segmentation
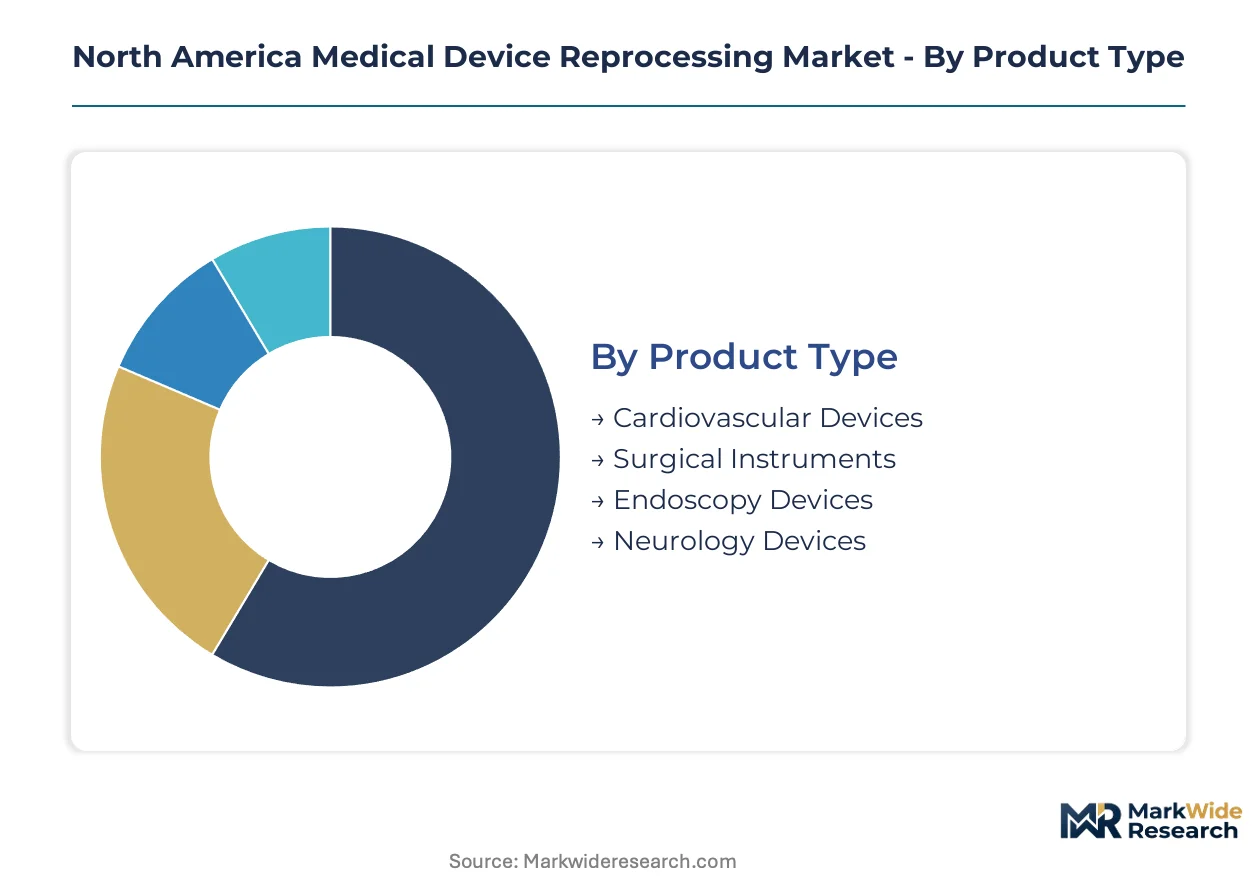
Device reprocessing workflows demand precise matching between product complexity and service infrastructure. Segmentation reveals where capital investment concentrates and which technology transitions reshape operational economics across the value chain.
Product Type:
Upgrade cycles in cardiovascular and endoscopy categories are compressing as FDA reclassification pathways mature and hospitals gain confidence in validated reprocessing protocols.
- Cardiovascular Devices:Diagnostic catheters, guidewires, and electrophysiology equipment undergo functional testing and sterilization at temperatures reaching 121°C. United States integrated delivery networks in Texas and Florida are expanding cardiovascular reprocessing contracts to capture per-procedure savings on high-unit-cost devices.
- Endoscopy Devices:Flexible gastrointestinal and pulmonary scopes require channel brushing, leak testing, and high-level disinfection with automated washer-disinfector systems. Ontario health authorities are mandating closed-loop tracking for all flexible endoscope reprocessing to eliminate documentation gaps.
- Surgical Instruments:Laparoscopic graspers, scissors, and trocars comprise metallic instruments suited to steam sterilization cycles. Ambulatory surgical centers in California are accelerating adoption to meet per-procedure supply cost targets.
- Neurology Devices:Microcatheters and embolization coils used in interventional neuroradiology present biocompatibility validation challenges. Limited FDA predicate device pathways constrain commercial penetration.
Cardiovascular devices sit at the top of the volume ranking, with endoscopy devices climbing the fastest.
Service Type:
Cost tier differentiation separates premium validated services from commodity logistics and packaging functions.
- Transportation:Reverse supply chain collection uses RFID-tracked containers with temperature monitoring for regulated devices. Cardinal Health extends logistics networks to capture hospital system contracts spanning multiple states.
- Cleaning:Automated washing with enzymatic detergents and ultrasonic cavitation removes biological debris from device lumens. FDA Quality System Regulation mandates cleaning validation protocols that elevate third-party reprocessor compliance costs.
- Packaging:Sterile barrier systems employ Tyvek pouches and rigid containers with humidity indicators. United States hospitals are consolidating packaging specifications under enterprise agreements to reduce SKU complexity.
- Sterilization:Terminal sterilization via ethylene oxide, gamma irradiation, or steam delivers sterility assurance levels. EtO capacity concentration in Illinois and Georgia creates geographic supply vulnerability for reprocessors lacking captive sterilization assets.
Sterilization commands the highest margin tier, with cleaning services expanding most quickly as automation reduces labor intensity.
End User:
Customer type determines contract structure complexity and regulatory documentation requirements.
- Hospitals:Large acute-care facilities operate sterile processing departments with in-house reprocessing for high-volume categories. IDN consolidation in the United States is creating captive supply structures that internalize margin capture.
- Ambulatory Surgical Centers:Outpatient facilities lack capital for automated reprocessing infrastructure and rely on third-party service contracts. Texas and Florida Medicaid reimbursement expansion for reprocessed devices is pulling volume toward ASC settings.
- Clinics:Physician office laboratories and specialty clinics represent fragmented demand with limited sterilization validation expertise. Cross-selling from hospital-centric vendors faces account management cost barriers.
- Diagnostic Laboratories:Pathology and clinical chemistry operations require reprocessed specimen collection devices and automated analyzer components. Health Canada establishment licensing requirements create friction for United States reprocessors seeking Canadian provincial contracts.
Hospitals anchor service revenue, with ambulatory surgical centers gaining share fastest as outpatient migration accelerates.
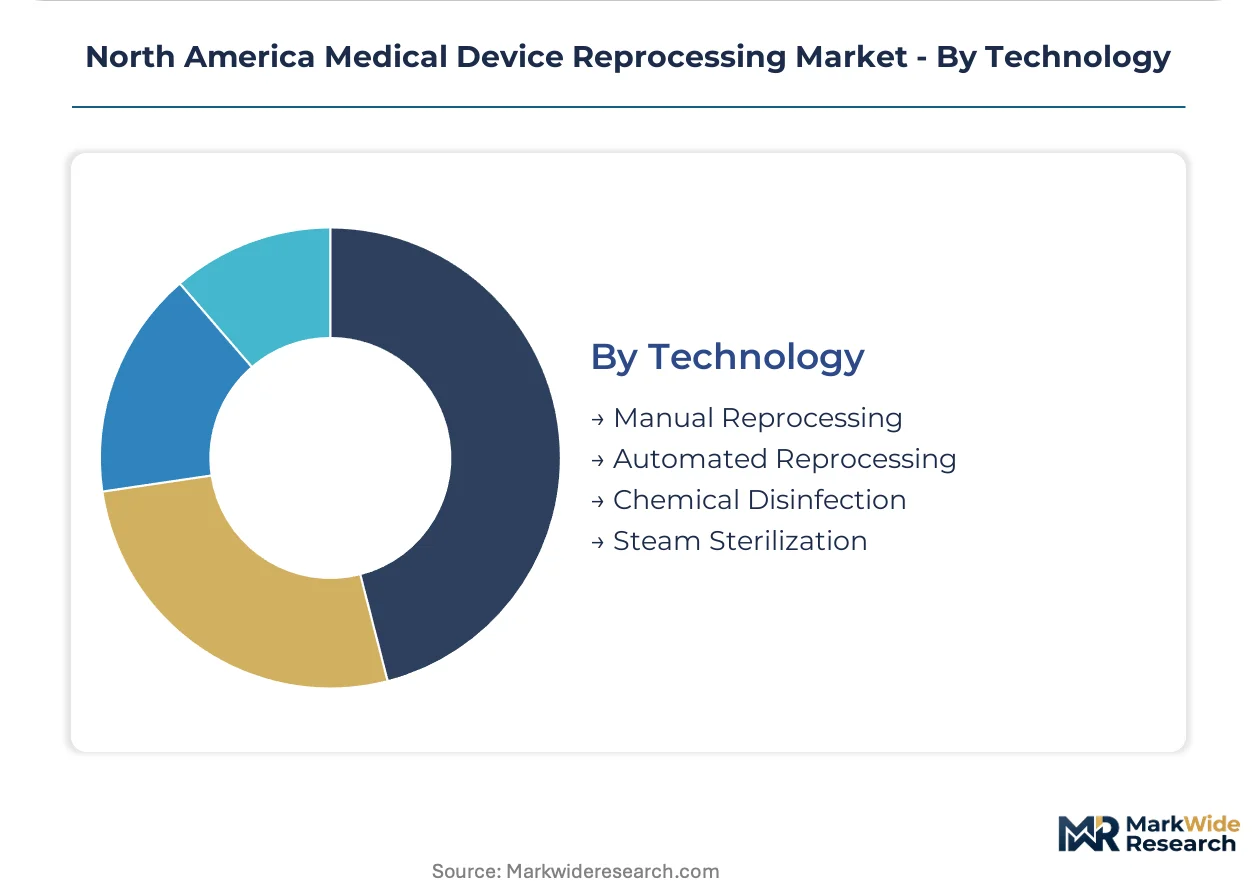
Technology:
Technology maturity curves separate established steam sterilization from emerging automated platforms.
- Manual Reprocessing:Human-dependent cleaning and inspection workflows persist for complex device geometries unsuited to automation. Biocompatibility testing technician shortages constrain scale-up for ISO 10993-qualified operations.
- Automated Reprocessing:Closed-loop washer-disinfector systems integrate RFID tracking with real-time conductivity monitoring. United States cardiovascular catheter workflows are deploying these platforms to compress FDA inspection observation rates.
- Chemical Disinfection:High-level disinfection with glutaraldehyde, ortho-phthalaldehyde, or peracetic acid targets heat-sensitive endoscopy devices. Health Canada is tightening establishment licensing standards for cross-border providers serving Ontario and Quebec.
- Steam Sterilization:Saturated steam exposure at 121°C for 15–30 minutes remains the gold standard for metallic instruments. Legacy batch record documentation systems impede real-time traceability for regulatory inspection readiness.
Steam sterilization maintains volume leadership, with automated reprocessing posting the steepest expansion trajectory as facilities reduce human factor variability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biocompatibility testing technicians and ISO 10993-qualified laboratory personnel concentrate in the United States and Ontario, anchoring the regional reprocessing infrastructure and creating geographic skill dependencies for cross-border service expansion.
United States
Texas, Florida, and California health systems are expanding Medicaid reimbursement coverage for reprocessed cardiovascular catheters, pulling volume from virgin device purchasing. FDA intensified scrutiny of single-use device revalidation protocols under Quality System Regulation updates, compressing third-party reprocessor margins. The Illinois and Georgia corridor hosts concentrated ethylene oxide sterilization capacity, creating geographic supply vulnerability for reprocessors lacking captive terminal sterilization assets.
Canada
Ontario and Quebec health authorities are mandating closed-loop tracking for all flexible endoscope reprocessing to eliminate documentation gaps. Health Canada's Medical Devices Bureau tightened establishment licensing standards for cross-border reprocessors, requiring on-site quality system audits previously waived under mutual recognition arrangements. Alberta and British Columbia health authorities are evaluating sterilization service outsourcing models established in Ontario and Quebec.
Mexico
Medical device manufacturing clusters in Baja California and Chihuahua are generating reprocessing demand for surgical instruments used in maquiladora operations. COFEPRIS regulatory alignment with FDA quality standards is facilitating cross-border service contracts for United States-based reprocessors. Mexico City metropolitan hospitals are piloting third-party reprocessing agreements for laparoscopic instrument categories.
North America Medical Device Reprocessing Market Competitive Landscape
Top-tier vendors anchor high-margin cardiovascular and endoscopy categories, while mid-tier logistics specialists compete on reverse supply chain efficiency and geographic coverage. The vendor base stratifies across vertically integrated hospital service models, third-party reprocessors with captive sterilization assets, and distribution-centric bundlers. Three archetypes dominate: infrastructure owners controlling end-to-end quality documentation, logistics platforms extending into regulated device tracking, and hospital-owned captives internalizing margin capture. Consolidation concentrates through IDN subsidiary formation and multi-year enterprise agreement bundling.
Within the infrastructure-owner tier, Stryker and Cardinal Health exemplify divergent strategic positions. Stryker anchors high-margin cardiovascular device categories through vertically integrated reprocessing infrastructure controlling end-to-end quality documentation. Cardinal Health occupies a logistics-centric position, extending distribution networks into reverse supply chain collection and tracking systems for regulated devices. Medline Industries sits within the hospital-centric bundling archetype, leveraging broadline supply contracts to anchor reprocessing services within integrated delivery network procurement structures.
| Leading Market Players |
|---|
| Stryker |
| Medline Industries |
| SureTek Medical |
| ReNu Medical |
| Arjo |
| NEScientific |
| Cardinal Health |
| SterilMed |
| Soma Tech Intl |
| Others |
Value Network & Pricing Analysis
ISO 10993-qualified biocompatibility testing technicians concentrated in the United States and Ontario create labor-cost differentials that widen pricing-tier spreads between premium validated reprocessing services and commodity sterilization offerings. Third-party reprocessors absorb elevated technician wages and FDA compliance overhead, while hospital-owned captives internalize these costs through captive labor pools.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the value chain. Hospital procurement committees favor per-procedure unit pricing that wraps collection, testing, and sterilization into enterprise agreements, compressing margins for standalone service vendors. Price differentiation rests on FDA Quality System Regulation certification tier and captive sterilization asset ownership. Pricing pressure intensifies as IDN consolidation concentrates buyer power across multi-state contracts. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure cost targets, while integrated delivery networks prioritize quality documentation over unit cost.
Supply Chain Analysis
Warehouse-distribution layer configurations favor regional distribution centers in Illinois and Georgia that cluster ethylene oxide terminal sterilization capacity. The supply chain draws from United States, Canada, and Mexico manufacturing corridors, with cardiovascular catheter and endoscope device collection feeding reverse logistics networks. Critical dependencies include ethylene oxide gas supply, enzymatic detergent formulations, and Tyvek sterile barrier materials. Single-source vulnerability concentrates in EtO sterilization assets, where geographic concentration creates supply disruption exposure. Distribution runs through hospital sterile processing departments and third-party reprocessing facilities with RFID-tracked container networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical device reprocessing hinges on automation-driven cost compression in high-volume cardiovascular catheter workflows and the premium-tier shift toward closed-loop quality documentation systems.
For Market Incumbents: Deploy backward integration into captive ethylene oxide sterilization assets to offset geographic supply vulnerability in Illinois and Georgia corridors. Consolidate vendor relationships under multi-year enterprise agreements that bundle device categories and lock out spot-market competitors. Stryker and Cardinal Health face emerging pressure from hospital-owned captives internalizing margin capture through IDN subsidiary formation. For New Entrants and Emerging Players: Enter via electrophysiology device reprocessing, where FDA predicate pathways exist but commercial penetration remains limited. Alberta and British Columbia health authorities evaluating sterilization outsourcing models present underpenetrated provincial demand. Target ambulatory surgical center contracts in Texas and Florida leveraging Medicaid reimbursement expansion for reprocessed cardiovascular catheters. For Investors and Strategic Acquirers: Hospital-owned captive supply structures are the most active acquirer in this space, internalizing third-party reprocessor margin through subsidiary formation. Long-term viability favors vertically integrated infrastructure owners with end-to-end quality documentation control over logistics-centric bundlers. Monitor FDA guidance evolution on single-use device reprocessing restrictions as the critical inflection signal for addressable volume reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | IDN consolidation creates captive supply structures that internalize reprocessing margin capture. |
| FDA Quality System Regulation Compliance Investment | Certification tier separation elevates barriers for uncertified entrants in cardiovascular categories. |
| Automated Washer-Disinfector Deployment | Closed-loop systems with RFID tracking compress FDA inspection observation rates in high-volume workflows. |
| Canadian Subsidiary Establishment | Health Canada on-site audit requirements force United States reprocessors to build provincial captive capacity. |
| Electrophysiology Device Reprocessing Expansion | Diagnostic and ablation catheters offer FDA predicate pathways with limited incumbent penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterile processing department managers, biomedical engineers, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, Health Canada establishment licensing records, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up device volume modeling and top-down service revenue estimates were triangulated across segmentation dimensions.
Comparable historical periods anchored the projection horizon to observed adoption curves for cardiovascular catheter reprocessing and endoscope high-level disinfection automation. The analytical framework modeled product type, service tier, end-user facility category, and technology deployment pattern segments across the forecast period. CAGRs were derived from regression analysis of Medicaid reimbursement expansion trajectories and ambulatory surgical center proliferation rates, with sterilization capacity utilization and technician wage inflation as key forecast inputs.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time hospital contract pricing transparency introduce uncertainty bands around service revenue estimates. Forecasts reflect documented assumptions regarding FDA enforcement intensity and provincial outsourcing adoption timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Carts Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Bench-Top Dental Autoclaves Market