
 Transradial Closure Devices Market | 2026-2036
Transradial Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Transradial Closure Devices Market Analytics
Ambulatory surgical centers are unwinding the historical hospital-centric procurement model for transradial closure devices as same-day discharge protocols expand. Terumo Corporation leverages its integrated catheter-to-closure portfolio to dominate Japanese and North American supply channels. Merit Medical Systems anchors its position through dedicated radial access training programs that lock in physician preference. Beijing Demax Medical Technology Co., Ltd. competes on cost-engineered mechanical devices across Asia-Pacific price-sensitive tenders.
Transradial closure devices are implantable or topical systems designed to achieve hemostasis at the radial artery puncture site following catheterization, typically incorporating collagen plugs, suture-mediated mechanisms, or biodegradable polymers that degrade within 30 to 90 days. These devices eliminate manual compression burden and enable faster ambulation, which directly supports hospital throughput metrics and patient satisfaction scores. Collagen-based products occupy the mature revenue core due to decades of clinical validation and established reimbursement codes, while biodegradable segments capture the fastest expansion as health systems prioritize absorbable materials that eliminate foreign body retention. Mechanical variants sustain margin pools in cost-conscious European and Asian procurement environments where reusable components offset per-procedure expenses.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose divergent evidence requirements that fragment product launch sequencing between the United States and European markets. ISO 10993 biocompatibility testing and ASTM F2902 vascular implant standards further condition material selection and validation timelines for manufacturers seeking multi-regional approval. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA breakthrough device designations that could reshape competitive entry dynamics for novel closure mechanisms.
Market Dynamics
Same-day discharge mandates from United States payers are compressing hemostasis timelines from hours to minutes, forcing device selection criteria toward rapid ambulation metrics rather than cost per unit alone.
Growth Catalysts
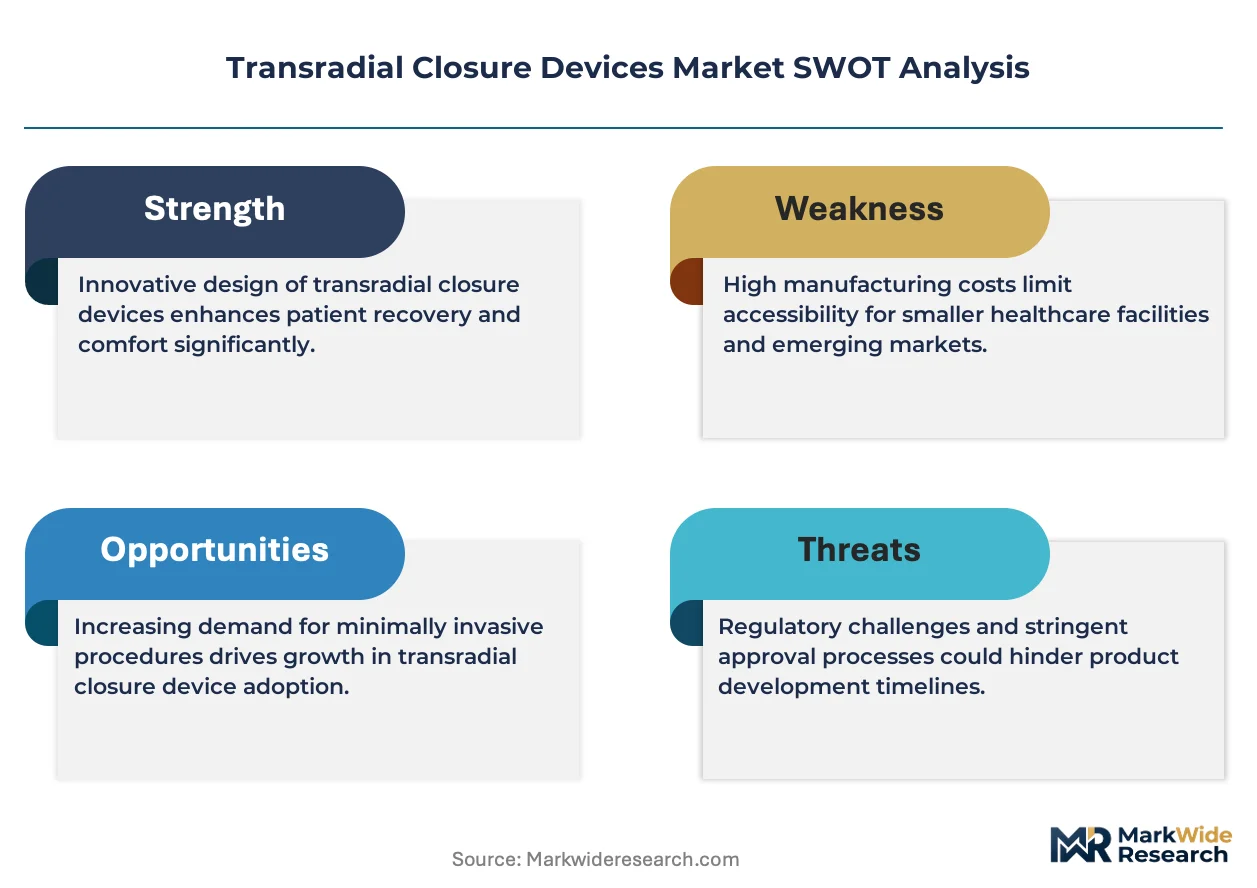
- Ambulatory surgical center expansion:United States Medicare reimbursement changes now cover transradial percutaneous coronary intervention in outpatient settings, pulling device procurement away from inpatient purchasing committees.
- FDA 510(k) pathway streamlining:Predicate device referencing for mechanical closure systems has reduced premarket notification review timelines, accelerating competitive entry for absorbable polymer platforms.
- Radial-first catheterization protocols:Cardiac catheterization laboratories in Japan and South Korea now default to radial access for diagnostic procedures, expanding the addressable procedure base beyond intervention-only volumes.
Market Restraints
- Bovine collagen supply concentration:Three suppliers control pharmaceutical-grade collagen sourcing from South American herds, exposing manufacturers to input cost volatility and herd health disruptions.
- MDR notified body capacity constraints:European Union Medical Device Regulation implementation has thinned certification capacity, stretching biocompatibility validation timelines for novel biodegradable polymers.
- Manual compression substitution:Low-compression band systems retain dominance in Indian and Southeast Asian price-sensitive tenders, capping premium device penetration in fastest-volume geographies.
Strategic Opportunities
- Brazilian regulatory opening:ANVISA's accelerated pathway for cardiovascular devices with prior FDA clearance creates first-mover positioning for manufacturers holding 510(k) clearances.
- Pediatric radial access protocols:Congenital heart centers in Germany and the United States are piloting transradial closure for pediatric populations, opening a procedure category without established hemostasis standards.
- Direct-to-hospital distribution:Bypassing distributor markups through manufacturer-employed clinical specialists is capturing preference in mid-tier United States health systems seeking bundled pricing transparency.
Industry Challenges
- Radial access training bottlenecks:Simulator-based credentialing programs cannot match the throughput needed for conversion of femoral-trained interventional cardiologists, slowing protocol adoption in community hospitals.
- ISO 10993-18 chemical characterization delays:Extractables and leachables testing for novel polymer formulations now extends eighteen to twenty-four months, compressing effective patent life for biodegradable platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transradial Closure Devices Market |
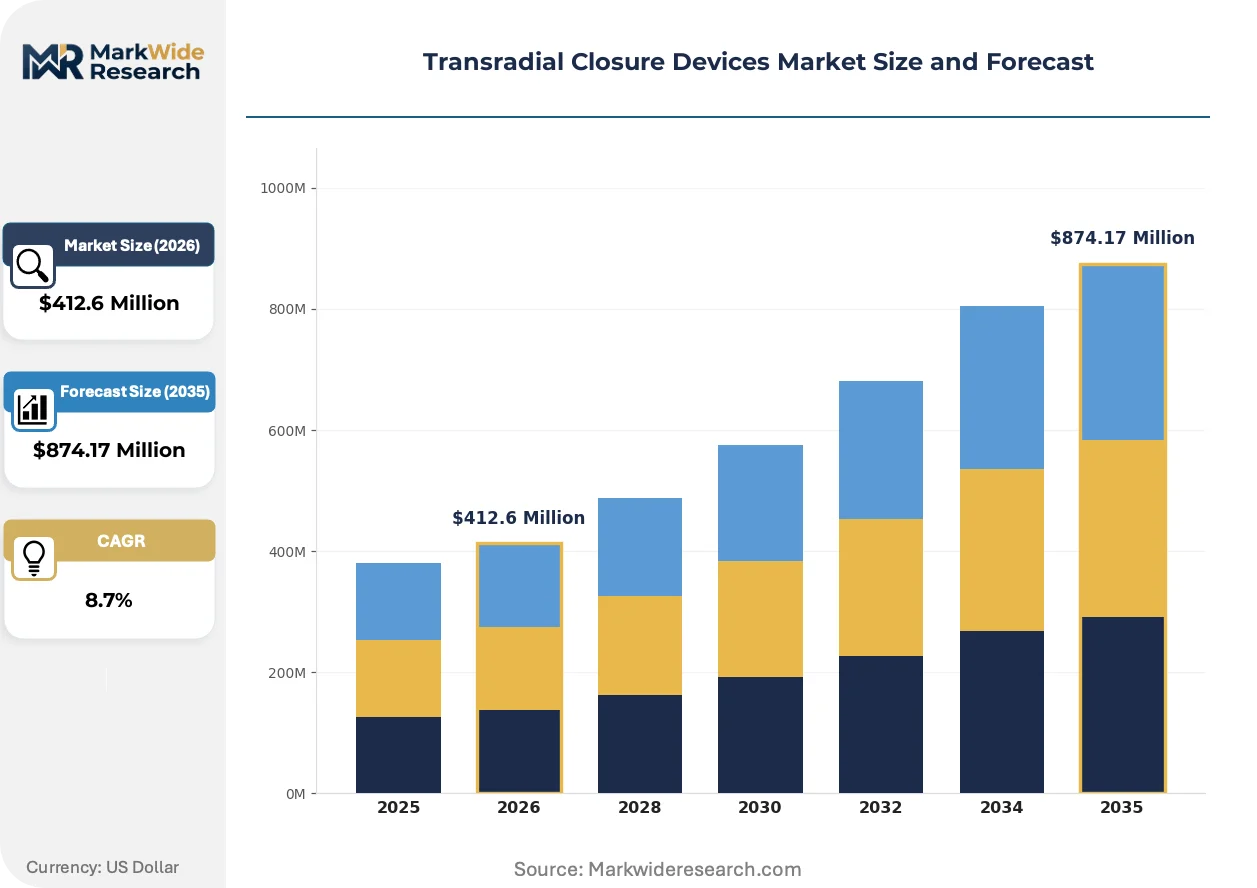
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen-Based, Biodegradable, Mechanical, Adhesive End User: Hospitals, Cardiac Centers, Ambulatory Surgical Centers, Specialty Clinics Application: Coronary Procedures, Peripheral Procedures, Electrophysiology, Research Studies Material: Polymer, Natural Biopolymer, Composite, Metal |
| Companies Covered | Terumo Corporation, Merit Medical Systems, Abbott Laboratories, Teleflex Incorporated, Haemonetics Corporation, Beijing Demax Medical Technology Co., Ltd., Vasorum Ltd., Cordis, Advanced Vascular Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transradial Closure Devices Market Evolving Landscape
Biodegradable polymer chemistry and real-world evidence requirements are converging to redefine competitive positioning, with material absorbability now carrying equivalent weight to mechanical performance in procurement scoring.
Polyglycolic acid-lactide copolymer platforms are displacing collagen plug systems in premium-tier hospital contracts by eliminating foreign body retention concerns and enabling magnetic resonance imaging compatibility without artifact. Academic medical centers in the United States and Germany are piloting these absorbable systems for complex anticoagulated patients, compressing the addressable market for permanent implant categories.
EU Medical Device Regulation post-market surveillance requirements are forcing manufacturers to fund prospective registries tracking radial artery patency and device-related complications. This surveillance burden falls disproportionately on mid-tier European competitors lacking the capital reserves to underwrite multi-year follow-up studies, consolidating advantage with diversified cardiovascular conglomerates.
Hospital value analysis committees now weight total procedure cost against device price alone, bundling closure selection with catheter and sheath purchasing decisions. United States integrated delivery networks are consolidating vendor lists to three preferred suppliers per category, forcing manufacturers to defend position through training infrastructure commitments rather than unit economics.
Transradial Closure Devices Market Segmentation
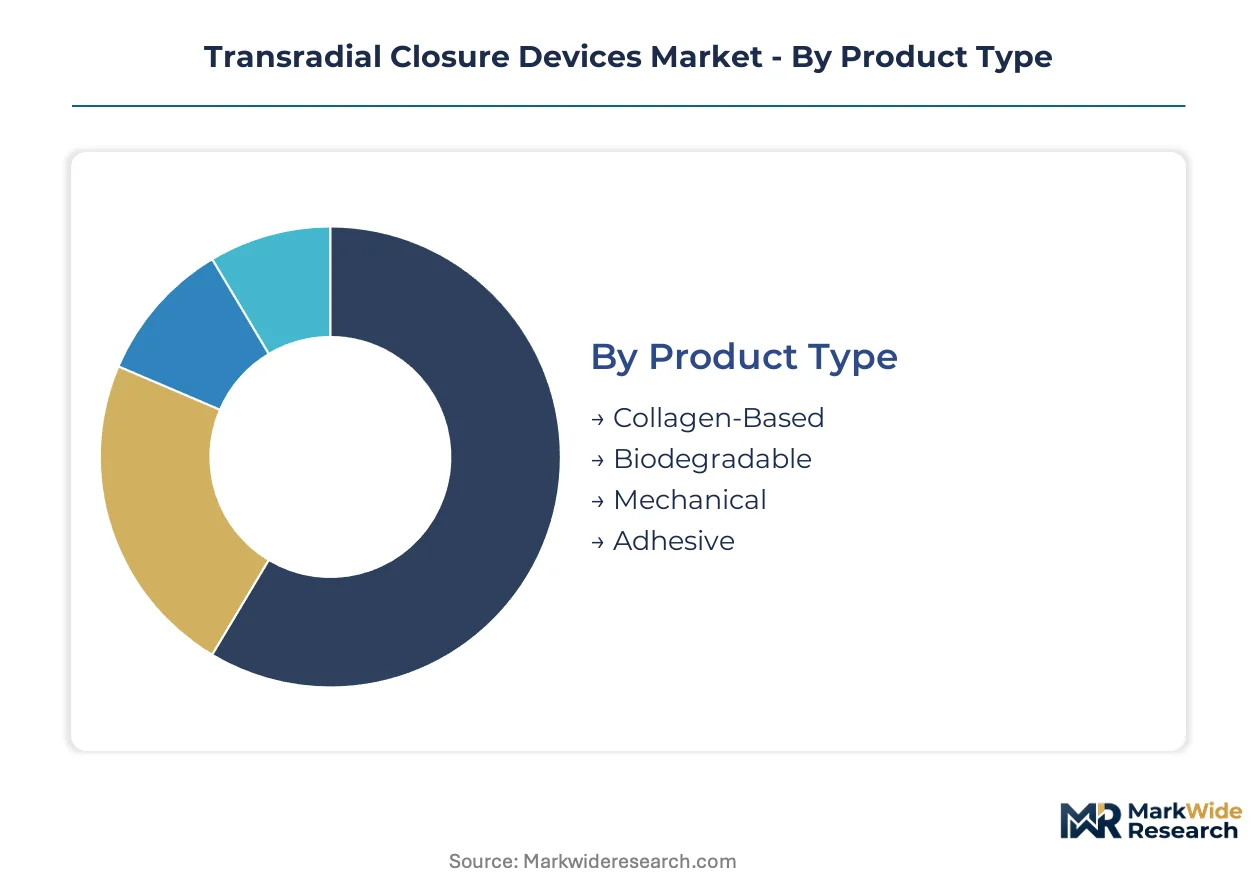
Device selection in transradial closure hinges on hemostasis speed, material absorbability, and reimbursement alignment. Procurement committees now weight total procedure economics over unit cost alone, reshaping how segments compete for contract slots.
Product Type:
Channel mix varies sharply by product category: collagen-based systems flow through established hospital distribution networks with GPO contracts, while biodegradable platforms increasingly bypass distributors through manufacturer direct sales.
- Collagen-Based:Bovine-derived collagen plugs deliver immediate mechanical compression with decades of procedural familiarity. United States cardiac catheterization laboratories anchor demand due to entrenched reimbursement codes and physician training pathways.
- Biodegradable:Polyglycolic acid-lactide copolymers degrade within 60 to 90 days, eliminating foreign body retention and MRI artifact concerns. Academic medical centers in Germany and the United States are piloting these systems for anticoagulated patients, compressing addressable share for permanent implants.
- Mechanical:Suture-mediated and clip-based systems dominate cost-sensitive tenders across Asia-Pacific markets where reusable components offset per-procedure spend.
- Adhesive:Cyanoacrylate and fibrin-based topical sealants occupy niche applications in pediatric and high-bleeding-risk protocols.
Collagen-based systems dominate installed base. Biodegradable platforms are where expansion concentrates.
End User:
Customer type determines procurement velocity and contract structure, with volume commitments and training obligations replacing transactional purchasing.
- Hospitals:Integrated delivery networks consolidate vendor lists to three preferred suppliers, bundling closure devices with catheter and sheath purchasing decisions. Value analysis committees weight total procedure cost against device price alone.
- Cardiac Centers:Dedicated interventional facilities prioritize rapid ambulation metrics to maximize laboratory throughput. Simulator-based credentialing programs lock in physician preference for specific device platforms.
- Ambulatory Surgical Centers:Medicare reimbursement changes now cover transradial percutaneous coronary intervention in outpatient settings, pulling procurement away from inpatient purchasing committees.
- Specialty Clinics:Electrophysiology and peripheral vascular clinics represent fragmented, lower-volume demand with price sensitivity.
Hospitals retain volume concentration. Ambulatory surgical centers are climbing the fastest.
Application:
Procedure type dictates hemostasis complexity and device performance requirements, with coronary volumes funding R&D amortization across narrower peripheral and electrophysiology segments.
- Coronary Procedures:Diagnostic and interventional cardiac catheterization generates the core revenue base, with radial-first protocols in Japan and South Korea expanding addressable volumes beyond intervention-only cases.
- Peripheral Procedures:Lower-extremity and renal artery interventions require larger sheath compatibility, favoring mechanical closure systems with adjustable compression force.
- Electrophysiology:Ablation procedures with prolonged sheath dwell times demand secure hemostasis without radial artery occlusion, driving interest in biodegradable sealants.
- Research Studies:Investigational device trials and registry participation create non-recurring revenue with high regulatory documentation burdens.
Coronary procedures anchor revenue. Peripheral applications are gaining share fastest.
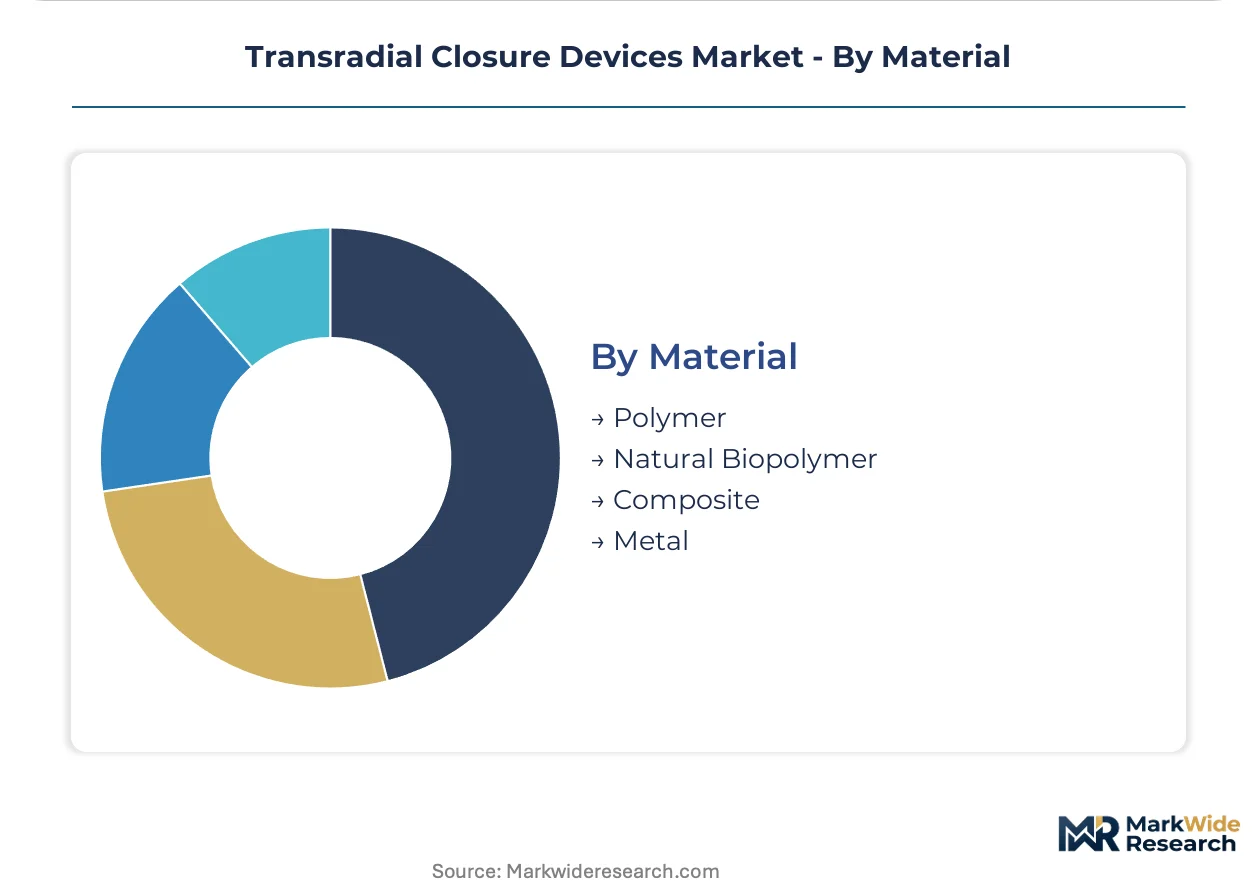
Material:
Material chemistry governs biocompatibility validation timelines and supply chain concentration, with natural sourcing exposing manufacturers to input volatility.
- Polymer:Synthetic absorbable platforms face eighteen to twenty-four month ISO 10993-18 extractables and leachables testing, compressing effective patent life for novel formulations.
- Natural Biopolymer:Pharmaceutical-grade collagen sourcing concentrates among three South American suppliers, exposing manufacturers to herd health disruptions and input cost volatility.
- Composite:Hybrid material structures combining synthetic and natural elements balance performance with cost in mid-tier European contracts.
- Metal:Titanium and stainless steel components persist in mechanical clip systems for reusable sterilization cycles.
Natural biopolymers dominate current production. Polymer platforms are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export transradial closure devices to United States cardiac catheterization laboratories, while South Korean suppliers feed demand from Australian ambulatory surgical centers expanding radial-first protocols.
United States
Medicare reimbursement changes now cover transradial percutaneous coronary intervention in outpatient settings, pulling procurement toward ambulatory surgical centers. The FDA's streamlined 510(k) pathway for vascular closure devices accelerates product clearance timelines. Minneapolis and Boston anchor device development clusters where integrated delivery networks consolidate vendor lists to three preferred suppliers.
Japan
Cardiac catheterization laboratories default to radial access for diagnostic procedures, expanding addressable volumes beyond intervention-only cases. The PMDA maintains alignment with FDA clearance standards for cardiovascular devices. Tokyo and Osaka medical device corridors concentrate manufacturing for collagen-based and biodegradable platforms serving domestic and export markets.
Germany
Academic medical centers pilot biodegradable polymer systems for anticoagulated patients, compressing demand for permanent implants. The EU Medical Device Regulation imposes post-market surveillance requirements that favor capitalized conglomerates over mid-tier competitors. Frankfurt and Munich cardiac centers drive procurement for absorbable closure mechanisms.
China
Domestic manufacturers compete on cost-engineered mechanical devices across price-sensitive hospital tenders. The NMPA regulates vascular implant standards under GB medical device classification. Beijing and Shanghai medical device zones concentrate production for mechanical closure systems serving Asia-Pacific volume markets.
Brazil
ANVISA's accelerated pathway for cardiovascular devices with prior FDA clearance creates first-mover positioning for manufacturers holding 510(k) clearances. São Paulo and Rio de Janeiro cardiac centers drive demand as private health networks adopt radial-first catheterization protocols.
Transradial Closure Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capability. The market structure concentrates around diversified cardiovascular conglomerates with integrated catheter-to-closure portfolios and dedicated training infrastructures. Three archetypes dominate: integrated device conglomerates with full radial access suites, mid-tier specialists with cost-optimized mechanical platforms, and regional fabricators serving price-sensitive tenders. Competitive moves center on direct-to-hospital distribution bypassing distributor markups, and bundled pricing transparency capturing mid-tier health system contracts.
Among Japan-based listed conglomerates, Terumo Corporation exemplifies the integrated portfolio archetype spanning catheters through closure. Merit Medical Systems, a US-based public company, occupies a position emphasizing physician training infrastructure as a lock-in mechanism. Beijing Demax Medical Technology Co., Ltd. represents the cost-engineered mechanical tier competing across Asia-Pacific price-sensitive procurement environments.
| Leading Market Players |
|---|
| Terumo Corporation |
| Merit Medical Systems |
| Abbott Laboratories |
| Teleflex Incorporated |
| Haemonetics Corporation |
| Beijing Demax Medical Technology Co., Ltd. |
| Vasorum Ltd. |
| Cordis |
| Advanced Vascular Dynamics |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month ISO 10993-18 extractables and leachables testing timelines for novel polymer formulations compress effective patent windows and concentrate pricing power with manufacturers holding validated material libraries. This lead-time burden shapes procurement toward incumbent suppliers while forcing new entrants to absorb extended cash conversion cycles before revenue recognition.
Pricing Analysis
Current-generation biodegradable polymer platforms command 40-60% premiums over prior-generation collagen plug systems, while next-generation absorbable composites under development target anticoagulated patient segments with further price stratification. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts from community hospital tenders and Asia-Pacific procurement bids. Cost compression in mechanical device tiers is intensifying because Chinese manufacturers are flooding price-sensitive tenders with reusable-component alternatives. Ambulatory surgical centers exhibit the highest price sensitivity due to Medicare reimbursement caps, while integrated delivery networks prioritize total procedure economics over unit cost.
Supply Chain Analysis
Argentina, Brazil, and Uruguay anchor pharmaceutical-grade bovine collagen sourcing for collagen-based closure devices, while Japan and Germany concentrate biodegradable polymer formulation and precision manufacturing. Supply chains draw from South American herd outputs, synthetic polymer feedstocks from petrochemical complexes, and sterilization packaging from specialized medical-grade film suppliers. Single-source vulnerability concentrates in collagen harvesting where three suppliers control herd access, exposing manufacturers to foot-and-mouth disease outbreaks and export restriction risks. Distribution runs through group purchasing organizations for hospital networks, direct manufacturer sales for ambulatory surgical centers, and regional distributors for Asia-Pacific price-sensitive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized radial access training infrastructure represents the scarce capability that separates sustainable market position from commodity competition, with simulator-based credentialing programs requiring capital commitments that mid-tier competitors cannot replicate.
For Market Incumbents: Compound training infrastructure lock-in by expanding simulator-based credentialing programs to community hospitals converting from femoral protocols, while securing backward integration into pharmaceutical-grade collagen sourcing to hedge South American supply concentration. Manual compression substitution in Indian and Southeast Asian markets threatens margin pools; defend through localized mechanical device production with reusable component economics. For New Entrants and Emerging Players: Differentiate on pediatric radial access protocols where congenital heart centers in Germany and the United States lack established hemostasis standards, creating white-space without incumbent entrenchment. Target direct-to-hospital distribution in mid-tier United States health systems seeking bundled pricing transparency, bypassing GPO markups that inflate apparent cost barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates seeking to divest non-core closure device divisions amid EU MDR surveillance cost burdens. Long-term viability hinges on absorbable polymer platforms displacing permanent implants across the analysis window, with patent cliff exposure for collagen-based revenue cores serving as the critical inflection signal for portfolio rebalancing timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in three-preferred-supplier status with integrated delivery networks bundling catheter and closure procurement. |
| CE Marking Pathway | Navigates MDR notified body capacity constraints for biodegradable polymer platforms seeking European market entry. |
| Backward Integration into Collagen Sourcing | Captures herd supply security against Argentine and Brazilian export disruption risks. |
| Software Companion Development | Enables real-world evidence capture for post-market surveillance compliance under EU MDR registry requirements. |
| Reimbursement Strategy | Aligns rapid ambulation metrics with Medicare outpatient coverage expansion for ambulatory surgical center placement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registration filings, hospital procurement contract disclosures, and CMS Medicare reimbursement bulletins. Bottom-up procedure volume estimates were triangulated against top-down manufacturer revenue allocations across product categories.
Across the analysis window, the forecasting framework modeled segmentation dimensions including device type, material chemistry, end-user facility category, application procedure type, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories weighted by device penetration rates and pricing tier mixes. Forecast inputs incorporated radial-first protocol adoption curves, MDR certification timeline assumptions, and ambulatory surgical center reimbursement expansion schedules.
Material uncertainties — regulatory pathway delays, herd health disruptions, and training program throughput constraints — sit outside the modeled envelope. Forecasts reflect assumptions about physician conversion rates from femoral to radial access and notified body capacity normalization. Recalibration cycles align with material shifts in Medicare reimbursement policy, FDA breakthrough device designation announcements, and South American collagen export regulation changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UAE Respiratory Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Global Motion Preservation Devices Market