
 Organ-On-A-Chip Systems Market | 2026-2036
Organ-On-A-Chip Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Organ-On-A-Chip Systems Market Insights
Polydimethylsiloxane is broadening design flexibility as manufacturers migrate from conventional thermoplastics toward this optically transparent, gas-permeable elastomer that supports real-time imaging and oxygen exchange. Emulate, Inc. leverages its human-emulation platform to anchor partnerships with major pharmaceutical clients. MIMETAS B.V. competes through its organ-on-a-chip technology specialized in perfused 3D tissue models. CN Bio Innovations Ltd sustains differentiation via liver-on-a-chip systems that replicate organ-level metabolic responses.
Organ-on-a-chip systems integrate living cells within microfluidic channels to simulate organ-level physiology, typically operating at microliter-scale fluid volumes with shear stresses ranging from 0.1 to 10 dynes per square centimeter to replicate in vivo mechanical environments. These platforms serve primarily to reduce late-stage drug failure rates by enabling human-relevant efficacy and toxicity readouts earlier in development pipelines. Microfluidic chips capture the dominant share of product-type revenue due to their foundational role in enabling perfusion control and cell co-culture architectures. Drug development applications generate the steepest growth trajectory within the application dimension, driven by pharmaceutical sponsors seeking alternatives to animal models under evolving regulatory acceptance frameworks. Contract Research Organizations represent an expanding end-user category as outsourcing partners build dedicated organ-on-a-chip service capabilities to capture sponsor demand.
The FDA's Modernization Act 2.0 reshapes validation pathways by explicitly permitting non-animal test methods for drug approval submissions, directly stimulating platform procurement across U.S.-based development pipelines. EMA's ongoing qualification opinions for microphysiological systems under the ICH M3(R2) guidelines similarly steer European toxicology program redesign toward chip-based alternatives. ISO technical committees are advancing standardization protocols for reproducibility and inter-laboratory validation that will determine which platform architectures achieve broad regulatory acceptance. Stakeholders must monitor which validation frameworks achieve cross-jurisdictional harmonization first, as this will concentrate procurement authority among platforms that secure multi-regulatory qualification.
Market Dynamics
FDA Modernization Act 2.0 removed mandatory animal testing requirements, redirecting pharmaceutical validation budgets toward human-relevant microphysiological platforms and compressing traditional toxicology service timelines.
Growth Catalysts
- Regulatory pathway reform:The FDA Modernization Act 2.0 explicitly permits non-animal test methods for drug approval submissions, eliminating a decades-old barrier to platform adoption.
- Material innovation:Polydimethylsiloxane migration from thermoplastics enables optically transparent, gas-permeable chip architectures supporting real-time imaging and oxygen exchange.
- Cluster concentration:Federal research funding and biotech clustering in Boston and San Diego generate concentrated procurement pull from pharmaceutical sponsors.
Market Restraints
- Input cost volatility:Specialized cell sourcing and primary human tissue procurement create margin pressure for platform manufacturers.
- Technical standardization gaps:Absence of harmonized ISO protocols for inter-laboratory reproducibility limits cross-site validation confidence.
- Regulatory friction:EMA qualification opinions for microphysiological systems under ICH M3(R2) remain incomplete, delaying European program redesign.
Strategic Opportunities
- Underpenetrated geography:Contract Research Organizations in Asia-Pacific represent nascent demand as regional pharmaceutical sponsors build dedicated organ-on-a-chip service capabilities.
- Technology convergence:Integration of artificial intelligence with perfused 3D tissue models enables predictive toxicity scoring beyond static endpoint analysis.
- Regulatory tailwind:ISO technical committee advancement of standardization protocols will concentrate procurement authority among first-mover platforms achieving multi-regulatory qualification.
Industry Challenges
- Specialized talent scarcity:Microfluidic engineering and organ-specific cell biology expertise remains concentrated in academic laboratories, constraining manufacturing scale-up.
- Certification timeline compression:Platform qualification for regulatory submission requires extended validation studies that delay revenue recognition.
- Integration complexity:Legacy high-content screening infrastructure demands custom interface development for chip-based readout compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ-On-A-Chip Systems Market |
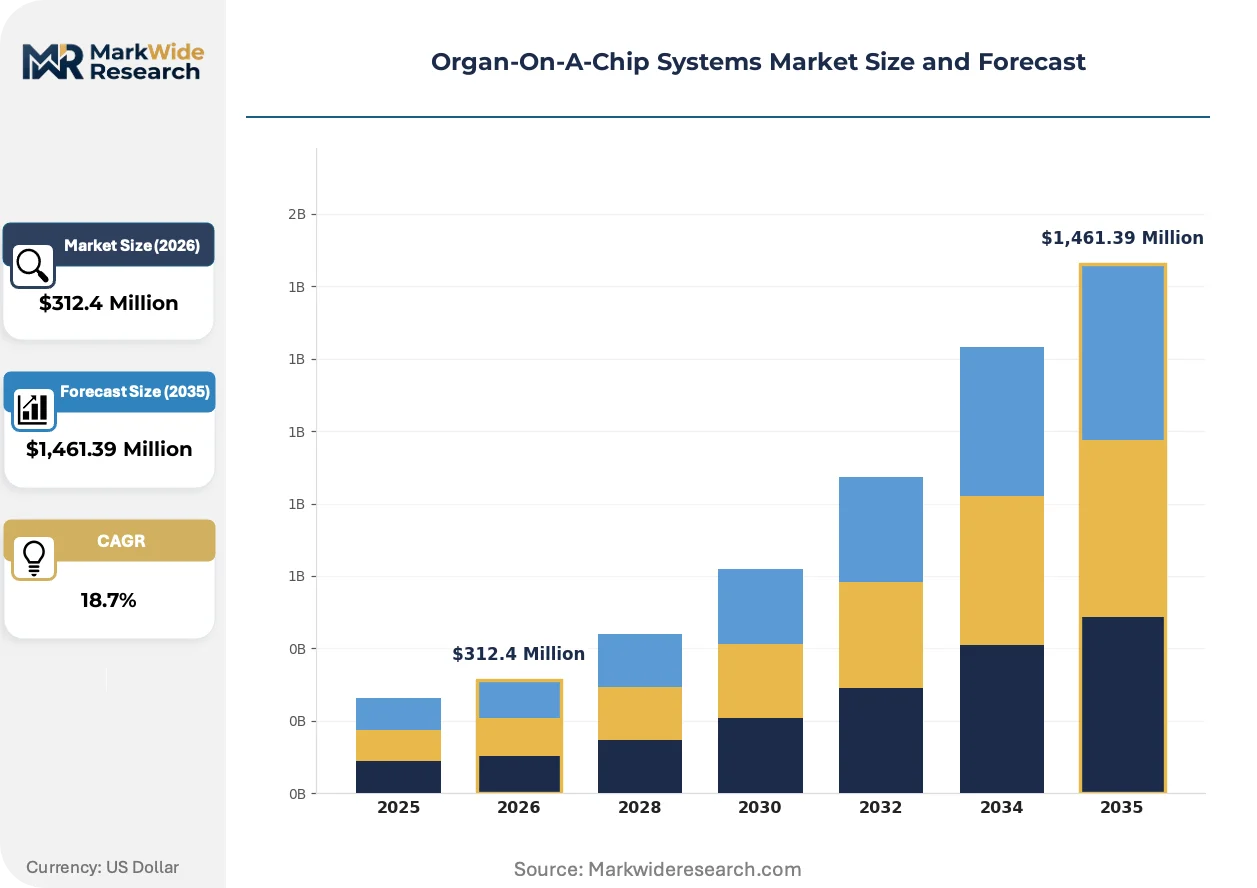
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Chips, Cell Culture Models, Organ Models, Assay Kits Application: Drug Development, Toxicity Testing, Disease Modeling, Personalized Medicine End User: Pharmaceutical Companies, Research Institutions, Academic Entities, Contract Research Organizations Technology: 3D Bioprinting, Microfabrication, Biomimetic Engineering, Imaging Techniques |
| Companies Covered | Emulate, Inc., MIMETAS B.V., CN Bio Innovations Ltd, InSphero, TissUse GmbH, Hesperos, Inc., Nortis, Inc., AxoSim, AlveoliX AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ-On-A-Chip Systems Market Trends and Innovations
Microphysiological systems are transitioning from exploratory research tools to validated preclinical assets, with platform architectures converging on standardized perfusion control and multi-organ coupling capabilities.
Multi-organ chip platforms are unifying liver, kidney, and cardiac tissue models within interconnected microfluidic circuits. Pharmaceutical sponsors in Boston and San Diego are deploying these systems for absorption-distribution-metabolism-excretion profiling. This convergence is unifying previously siloed toxicology workflows into continuous human-relevant validation pipelines.
EMA's ongoing qualification opinions for microphysiological systems under ICH M3(R2) guidelines are steering European toxicology program redesign. Pharmaceutical sponsors are restructuring preclinical departments to accommodate chip-based alternatives. Liver-on-a-chip applications face the steepest compliance recalibration as metabolic pathway validation standards crystallize.
Pharmaceutical procurement departments are consolidating vendor relationships around platforms with dual FDA-EMA qualification pathways. Contract Research Organizations are displacing fragmented point-solution providers with integrated service offerings. This concentration is most visible in the United States, where sponsor outsourcing budgets are capturing dedicated organ-on-a-chip capabilities.
Organ-On-A-Chip Systems Market Segmentation
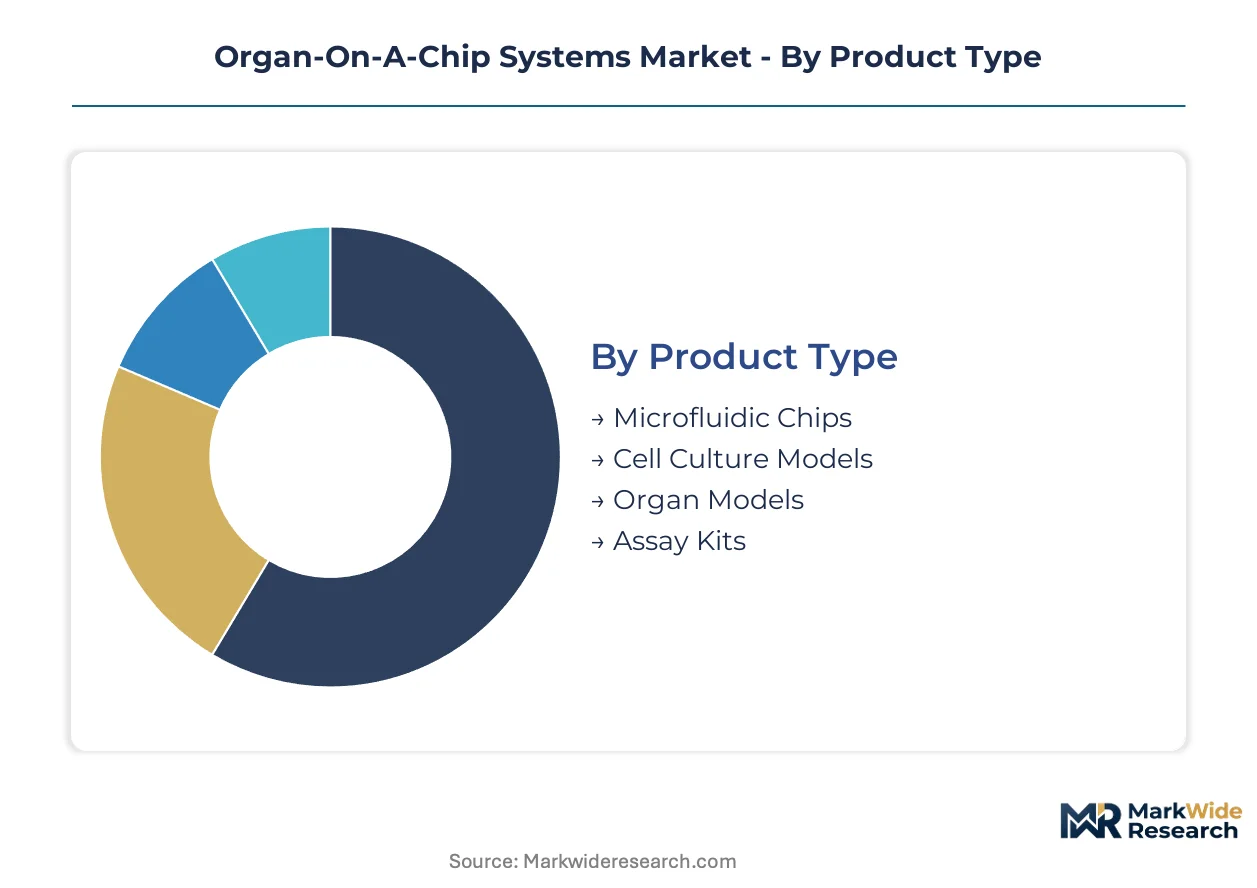
Platform architecture choices determine validation throughput and regulatory acceptance trajectories. Segmentation reveals where procurement budgets concentrate and which technology combinations command premium positioning.
Product Type:
Upgrade cycles favor platforms with modular perfusion architectures over fixed-format legacy systems.
- Microfluidic Chips:These substrates integrate living cells within precision-engineered channels operating at microliter-scale fluid volumes. Demand concentrates in pharmaceutical development pipelines across the United States, where FDA Modernization Act 2.0 compliance accelerates replacement of static well-plate formats.
- Cell Culture Models:Three-dimensional tissue constructs replicate organ-level metabolic responses within controlled microenvironments. Boston and San Diego biotech clusters drive procurement pull for human-relevant hepatocyte and cardiomyocyte models.
- Organ Models:Multi-tissue platforms simulate physiological coupling between liver, kidney, and cardiac systems.
- Assay Kits:Standardized reagent packages enable endpoint detection and biomarker quantification.
Volume placements concentrate in Microfluidic Chips; the faster expansion belongs to Organ Models.
Application:
Cost tier stratification separates high-budget pharmaceutical sponsors from constrained academic laboratories.
- Drug Development:Preclinical screening pipelines deploy human-relevant efficacy and toxicity readouts to compress traditional toxicology timelines. EMA qualification opinions under ICH M3(R2) guidelines steer European program redesign toward these platforms.
- Toxicity Testing:Hepatotoxicity and cardiotoxicity profiling replaces animal-based safety assessment with mechanistic human tissue responses.
- Disease Modeling:Patient-derived cells recreate pathophysiological mechanisms for rare and complex disorders.
- Personalized Medicine:Individual patient biopsies enable therapeutic response prediction prior to treatment initiation.
Procurement authority clusters in Drug Development; Personalized Medicine is gaining share fastest.
End User:
Customer type determines contract structure, with multi-year enterprise agreements dominating sponsor relationships.
- Pharmaceutical Companies:Internal preclinical departments build dedicated organ-on-a-chip capabilities to secure regulatory submission pathways. Federal research funding and biotech clustering in Boston and San Diego generate concentrated demand from sponsor headquarters.
- Contract Research Organizations:Outsourcing partners capture sponsor budgets through integrated service offerings spanning platform operation and data interpretation.
- Research Institutions:Academic laboratories concentrate microfluidic engineering and organ-specific cell biology expertise.
- Academic Entities:University consortia advance standardization protocols for reproducibility and inter-laboratory validation.
Revenue concentration favors Pharmaceutical Companies; Contract Research Organizations are expanding most quickly.
Technology:
Supply concentration among specialized equipment vendors shapes procurement lead times and qualification requirements.
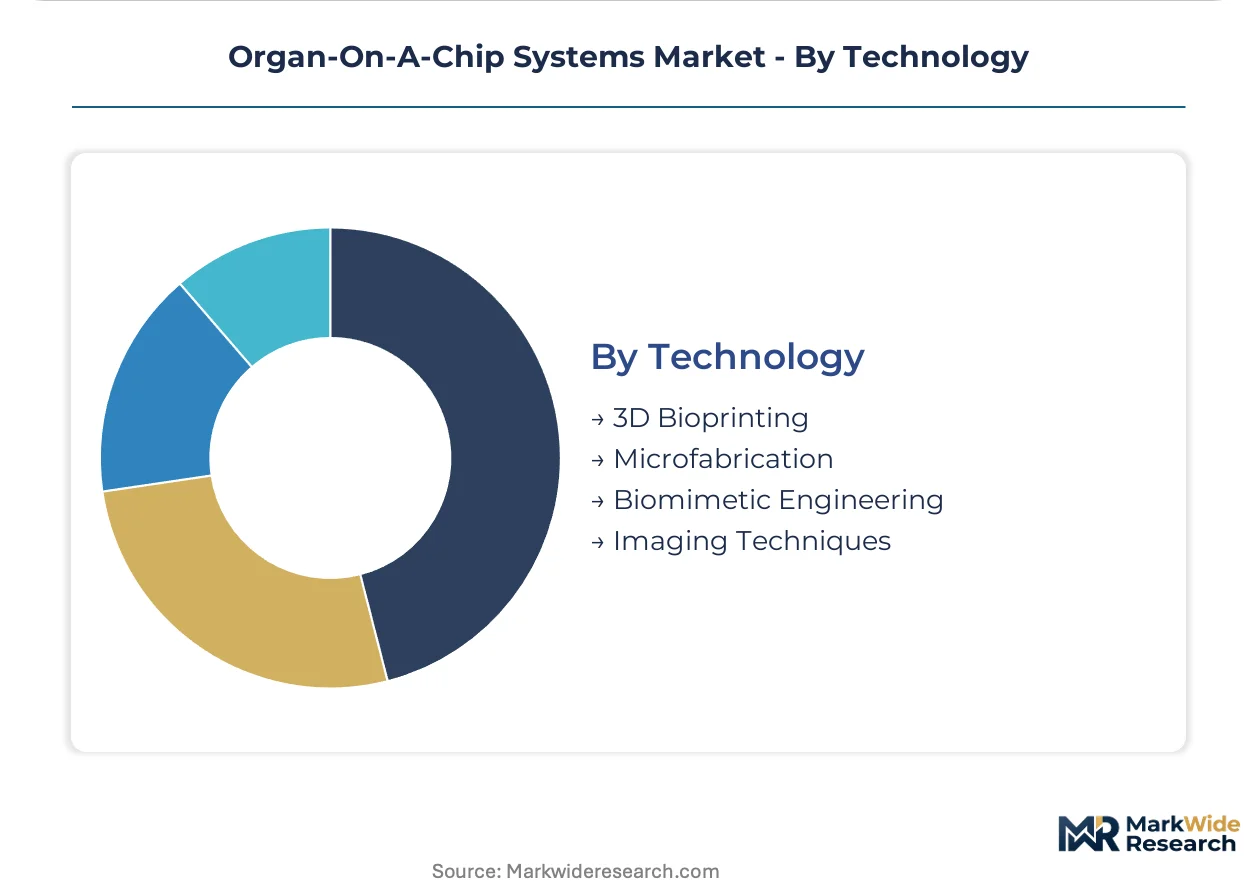
- Microfabrication:Photolithography and soft-lithography processes pattern polydimethylsiloxane into optically transparent, gas-permeable architectures. ISO technical committee advancement of standardization protocols will determine which fabrication approaches achieve broad regulatory acceptance.
- 3D Bioprinting:Layer-by-layer deposition constructs perfusable tissue geometries with spatially controlled cell placement.
- Biomimetic Engineering:Synthetic scaffolds replicate extracellular matrix mechanical properties and biochemical signaling.
- Imaging Techniques:Real-time microscopy and high-content screening integrate with chip-based readout compatibility.
Platform deployments concentrate in Microfabrication; 3D Bioprinting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement budgets concentrate most acutely in the United States, where federal research funding and biotech clustering generate concentrated platform demand. The FDA Modernization Act 2.0 eliminated mandatory animal testing requirements, redirecting validation spend toward human-relevant microphysiological systems.
United States
Federal research funding from the National Institutes of Health and Defense Advanced Research Projects Agency sustains platform development pipelines. The FDA Modernization Act 2.0 explicitly permits non-animal test methods for drug approval submissions, eliminating decades-old regulatory barriers. Boston and San Diego biotech clusters generate concentrated procurement pull from pharmaceutical sponsors restructuring preclinical departments.
Germany
Industrial research consortia and Fraunhofer Institute networks drive microfluidic engineering expertise into commercial applications. The German national pharmaceutical regulator evaluates microphysiological systems under evolving EU-wide qualification frameworks. Heidelberg and Munich research corridors concentrate organ-on-a-chip startups alongside established laboratory automation vendors.
United Kingdom
Medical Research Council funding and Innovate UK grants accelerate translation from academic laboratories to contract research services. The Medicines and Healthcare products Regulatory Agency participates in EMA qualification opinion processes for microphysiological systems. Cambridge and London biotech clusters host platform developers targeting pharmaceutical outsourcing contracts.
Netherlands
Public-private partnerships between university medical centers and instrumentation manufacturers reduce commercialization timelines for perfusion control technologies. The Dutch national pharmaceutical regulator aligns with EMA microphysiological system qualification pathways under ICH guidelines. Leiden and Eindhoven host specialized vendors supplying modular chip architectures to European pharmaceutical sponsors.
Japan
Pharmaceutical sponsors facing aging demographics and compressed development timelines seek mechanistic human tissue responses for safety assessment. The Pharmaceuticals and Medical Devices Agency evaluates microphysiological system data for regulatory submission acceptance. Tokyo and Osaka industrial clusters concentrate microfabrication expertise serving domestic and Asia-Pacific contract research demand.
Organ-On-A-Chip Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform developers capturing direct pharmaceutical relationships while instrumentation suppliers serve research infrastructure upgrades. The vendor base organizes into three tiers: integrated platform providers with regulatory qualification pathways, specialized chip fabricators supplying modular components, and contract research organizations building dedicated service capabilities. Two dominant competitive moves structure rivalry: strategic partnerships between platform developers and pharmaceutical sponsors for co-validation studies, and technology licensing agreements that extend microfluidic architectures into adjacent application areas.
Within the integrated platform tier, Emulate, Inc., MIMETAS B.V., and CN Bio Innovations Ltd occupy positions representing distinct specialization vectors. Emulate anchors human-emulation platform development with pharmaceutical partnership structures. MIMETAS exemplifies perfused 3D tissue model specialization. CN Bio Innovations sits within liver-on-a-chip metabolic response replication. These three entities represent archetype differentiation around organ specificity, partnership depth, and regulatory engagement intensity.
| Leading Market Players |
|---|
| Emulate, Inc. |
| MIMETAS B.V. |
| CN Bio Innovations Ltd |
| InSphero |
| TissUse GmbH |
| Hesperos, Inc. |
| Nortis, Inc. |
| AxoSim |
| AlveoliX AG |
| Others |
Pricing and Supply Chain Analysis
ISO 10993 biocompatibility certification gates both qualified polydimethylsiloxane supply and premium-tier pricing access for microfluidic chip manufacturers, compressing margins for uncertified entrants while concentrating procurement authority among validated fabricators serving FDA submission pathways.
Pricing Analysis
Volume placements concentrate in standardized microfluidic chips while margins accrue to customized multi-organ platforms. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-qualified platforms from research-grade alternatives from consumable assay kits. Price differentiation hinges on ISO certification status and after-sales validation support. Pricing pressure stems from specialized primary human tissue procurement costs. Academic laboratories exhibit highest price sensitivity; pharmaceutical sponsors prioritize qualification certainty over unit economics.
Supply Chain Analysis
Regional distribution centers in Massachusetts and California operate hub-and-spoke patterns serving Boston and San Diego biotech clusters. Fabrication concentrates in the United States, Germany, and Japan. Polydimethylsiloxane substrates, precision photolithography equipment, and primary human hepatocytes constitute critical input dependencies. Single-source vulnerability in specialized cell sourcing creates supply risk. Distribution runs through direct pharmaceutical procurement channels and CRO service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microphysiological systems are displacing static well-plate toxicology workflows, with polydimethylsiloxane-based perfusion architectures replacing legacy animal models across preclinical validation pipelines.
For Market Incumbents: Anchor regulatory submission pathways through accelerated FDA co-qualification studies with pharmaceutical sponsors. Deepen backward integration into primary human tissue sourcing to defend margin position against cell procurement volatility. Prioritize ISO standardization committee participation to shape interoperability protocols that freeze out unvalidated competitors. For New Entrants and Emerging Players: Contract Research Organizations in Asia-Pacific represent the most penetrable channel partner type for platform-as-a-service offerings. Target Japan's PMDA qualification pathway as a differentiated regulatory entry point. Pursue technology licensing agreements with established microfabrication houses to compress capital requirements. For Investors and Strategic Acquirers: EMA qualification opinion completion under ICH M3(R2) is the leading indicator that European procurement budgets will accelerate toward chip-based alternatives. Five-to-ten-year viability favors platforms with dual FDA-EMA validation trajectories and proprietary organ-specific cell sourcing relationships. Monitor ISO technical committee publication timelines as inflection signals for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Co-Qualification Partnership | Pharmaceutical sponsors secure FDA submission pathways through joint validation studies with platform developers. |
| Backward Integration into Cell Sourcing | Primary human tissue procurement control reduces input cost volatility for liver-on-a-chip manufacturers. |
| Multi-Organ Platform Convergence | Interconnected liver-kidney-cardiac circuits unify ADMET profiling into continuous validation pipelines. |
| Artificial Intelligence Integration | Predictive toxicity scoring extends endpoint analysis beyond static biomarker quantification methods. |
| Asia-Pacific CRO Service Buildout | Regional pharmaceutical sponsors in Japan capture dedicated organ-on-a-chip capabilities through outsourcing contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, preclinical department heads, and CRO service directors combined with FDA submission databases, EMA qualification opinions, NIH funding disclosures, and ISO technical committee drafts. Bottom-up platform shipment estimates and top-down pharmaceutical R&D spend allocations underwent triangulation validation.
Data-stream reconciliation across product architecture, application segment, end-user category, and technology type dimensions shaped the analytical framework across the analysis window. CAGRs derived from regression analysis of historical procurement patterns and regulatory acceptance trajectory modeling. Segment-specific inputs incorporated FDA Modernization Act 2.0 implementation pace and EMA ICH M3(R2) qualification timelines.
Caveats apply where ISO standardization delays or primary tissue sourcing disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Cardiac Implants Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Alpha Emitter Market
Medical Devices
Speech Generating Devices Market