
 India Urology Market | 2026-2036
India Urology Market Size, Share, and Industry Trends Forecast 2026-2036
India Urology Market Insights
The India urology device landscape is consolidating around a sharp split between premium imported systems and cost-engineered domestic alternatives. Stryker India leverages its integrated surgical platform to dominate high-end endoscopic suites in metropolitan hospitals. Fresenius Medical Care India anchors dialysis and renal care infrastructure across tier-two cities, sustaining volume leadership through established service networks. Cook Medical India differentiates in interventional urology with specialized catheter and stent portfolios tailored to Indian anatomical prevalence patterns.
Urology encompasses the medical and surgical discipline addressing diseases of the urinary tract and male reproductive system, employing endoscopes with optical resolutions of 4K-8K, laser lithotripters operating at 532-2100 nm wavelengths, and robotic platforms with sub-millimeter instrument articulation for prostate and renal procedures. Endoscopes command the largest installed base among product categories, though robotic-assisted surgical systems represent the fastest-growing technology segment as hospitals compete for medical tourism revenue. Among applications, prostate disorders generate the highest procedure volume, while uro-oncology commands premium pricing due to multidisciplinary care requirements and advanced imaging dependencies.
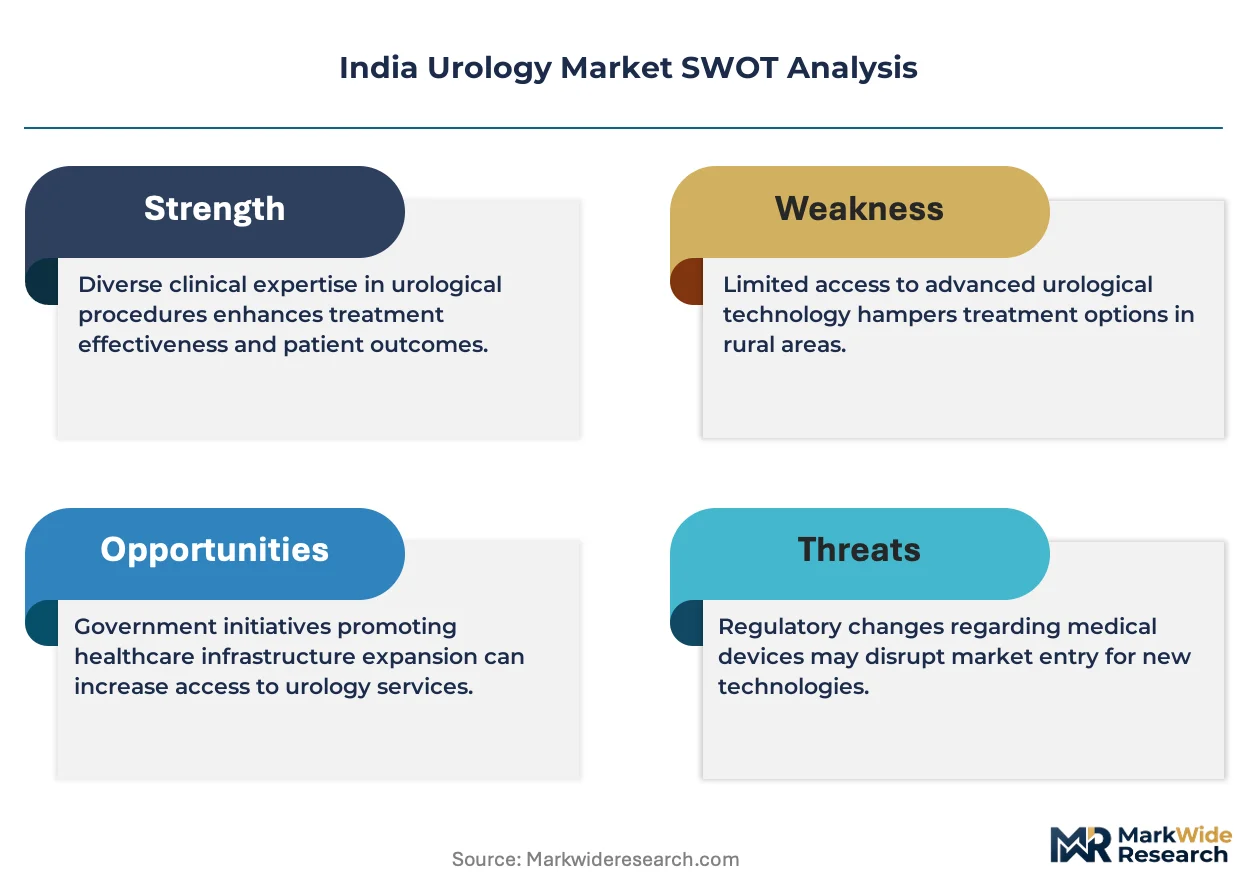
CDSCO governs medical device registration and quality standards, while the PLI scheme incentivizes domestic production of high-value urology equipment, collectively narrowing import dependence for standard surgical instruments. BIS certification mandates ensure electrical safety and biocompatibility compliance for devices deployed in hospital settings. Stakeholders must monitor state-level health infrastructure budgets and Ayushman Bharat reimbursement expansions to anticipate demand shifts between public procurement and private premium channels.
Market Dynamics
CDSCO's streamlined device approval pathways and the PLI scheme for domestic manufacturing are compressing import dependence for standard urological instruments while tier-one hospitals in Mumbai and Delhi accelerate minimally invasive suite expansion.
Growth Catalysts
- Ayushman Bharat reimbursement expansion:Public insurance coverage for endoscopic stone removal and prostate procedures is pulling demand into tier-two and tier-three hospital networks across Tamil Nadu and Karnataka.
- 4K-8K optical resolution migration:Metropolitan teaching hospitals are replacing legacy endoscope fleets with ultra-high-definition visualization systems to capture medical tourism revenue from Gulf and African patients.
- PLI scheme capital subsidies:Domestic manufacturers of rigid cystoscopes and lithotripter handpieces are scaling production to serve price-sensitive government procurement channels.
Market Restraints
- Robotic surgical platform import concentration:Da Vinci and Versius systems face 100% foreign exchange exposure, constraining deployment beyond Mumbai, Delhi, and Bangalore corporate hospital chains.
- Holmium laser fiber supply fragility:Single-source dependence on German and Japanese fiber manufacturers creates procedure-day availability risk for lithotripsy centers.
- BIS electrical safety certification timelines:Six-to-nine month testing queues at NABL-accredited labs delay commercialization of domestically assembled electrosurgical generators.
Strategic Opportunities
- Kerala and Andhra Pradesh urology center density gaps:Specialty clinic chains can establish greenfield ambulatory surgical centers in coastal cities with aging demographics and limited competitor presence.
- Tele-urology diagnostic convergence:Integration of portable ultrasound with cloud-based stone volume analysis enables remote pre-operative planning for district hospital networks.
- CDSCO conditional approval pilot:Accelerated market entry for AI-assisted polyp detection modules in cystoscopy creates first-mover positioning for software-enabled device bundles.
Industry Challenges
- Endourology fellowship pipeline constraints:Only twelve MCh urology programs produce sufficient robotic console-certified surgeons to match installed system capacity.
- Legacy sterilization infrastructure incompatibility:Imported flexible ureteroscopes require low-temperature hydrogen peroxide sterilization cycles unavailable in 60% of tier-two hospital central sterile supply departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Urology Market |
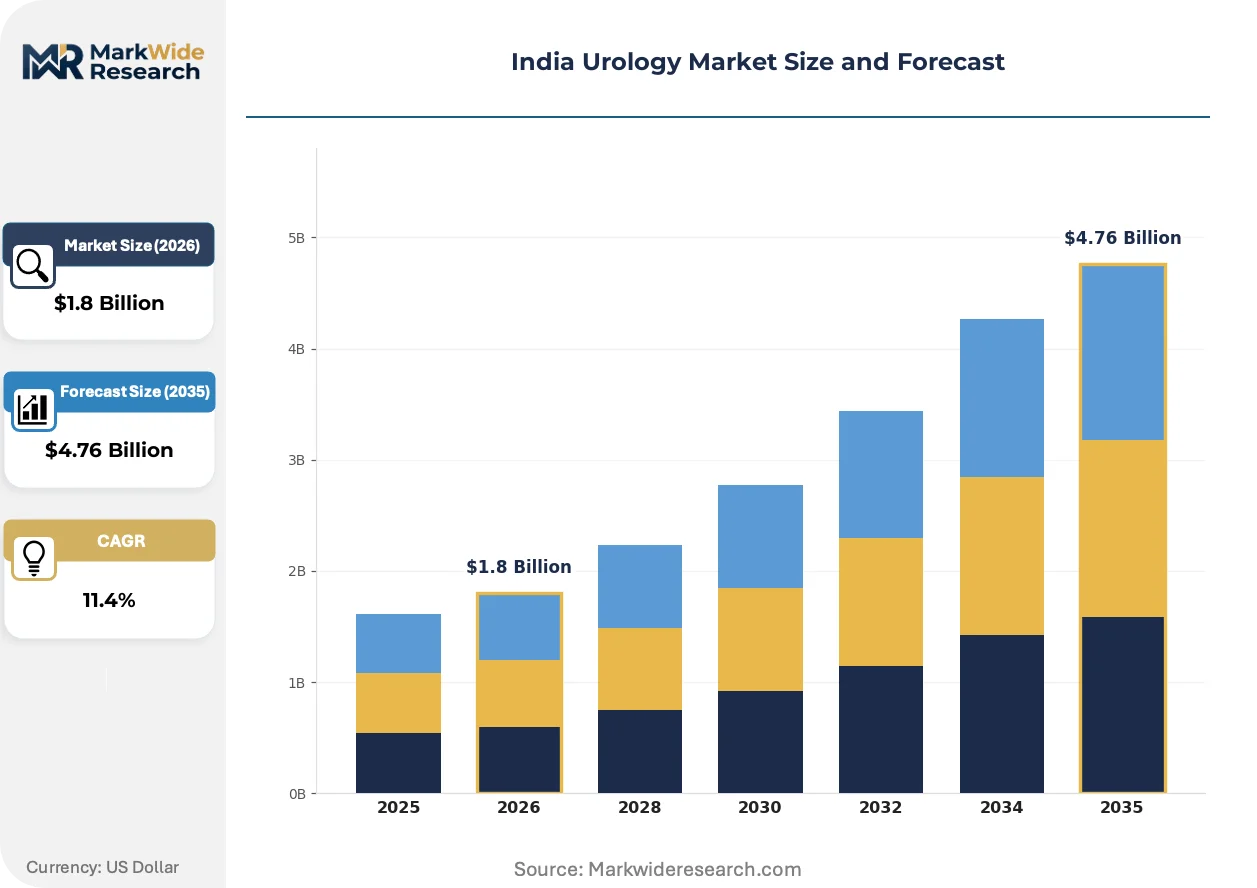
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Imaging Systems, Surgical Instruments, Diagnostic Equipment Application: Kidney Stones, Prostate Disorders, Bladder Control, Uro-Oncology End User: Hospitals, Specialty Clinics, Research Institutes, Diagnostic Labs Technology: Laparoscopy, Robotics, Ultrasound, Laser |
| Companies Covered | Stryker India Pvt. Ltd., Fresenius Medical Care India Pvt. Ltd., Boston Scientific India Pvt Ltd, Becton Dickinson Private Limited, B. Braun Medical (India) Pvt. Ltd., Olympus Medical Systems India Pvt Ltd, India Medtronic Pvt. Ltd., KARL STORZ Endoscopy, India Pvt. Ltd., Cook Medical India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Urology Market Trends and Innovations
Digital pathology integration and disposable endoscope economics are restructuring capital deployment patterns across Indian urology departments, with technology choices increasingly tied to procedure volume thresholds and reimbursement category stability.
Single-use flexible ureteroscopes are automating reprocessing workflow elimination for high-volume stone centers. Corporate hospital chains in Delhi and Bangalore are adopting these devices for cases exceeding fifteen procedures weekly. The shift is automating capital-light scaling for ambulatory surgery centers that lack in-house sterilization infrastructure.
CDSCO's 2023 risk-based classification amendment for software-as-a-medical-device is tightening clinical validation requirements for AI-assisted stone detection algorithms. Domestic manufacturers must now submit prospective multi-center accuracy studies before marketing clearance. The regulation most affects Bangalore-based startups developing real-time calculus segmentation tools for portable ultrasound platforms.
Equipment leasing with bundled maintenance contracts is displacing outright purchase for lithotripter and laser systems in tier-two private hospitals. Medical device financiers are capturing margin through per-procedure revenue-sharing arrangements rather than fixed lease payments. This model is most visible in Gujarat and Rajasthan, where single-specialty urology chains prioritize cash flow predictability over balance sheet asset ownership.
India Urology Market Segmentation
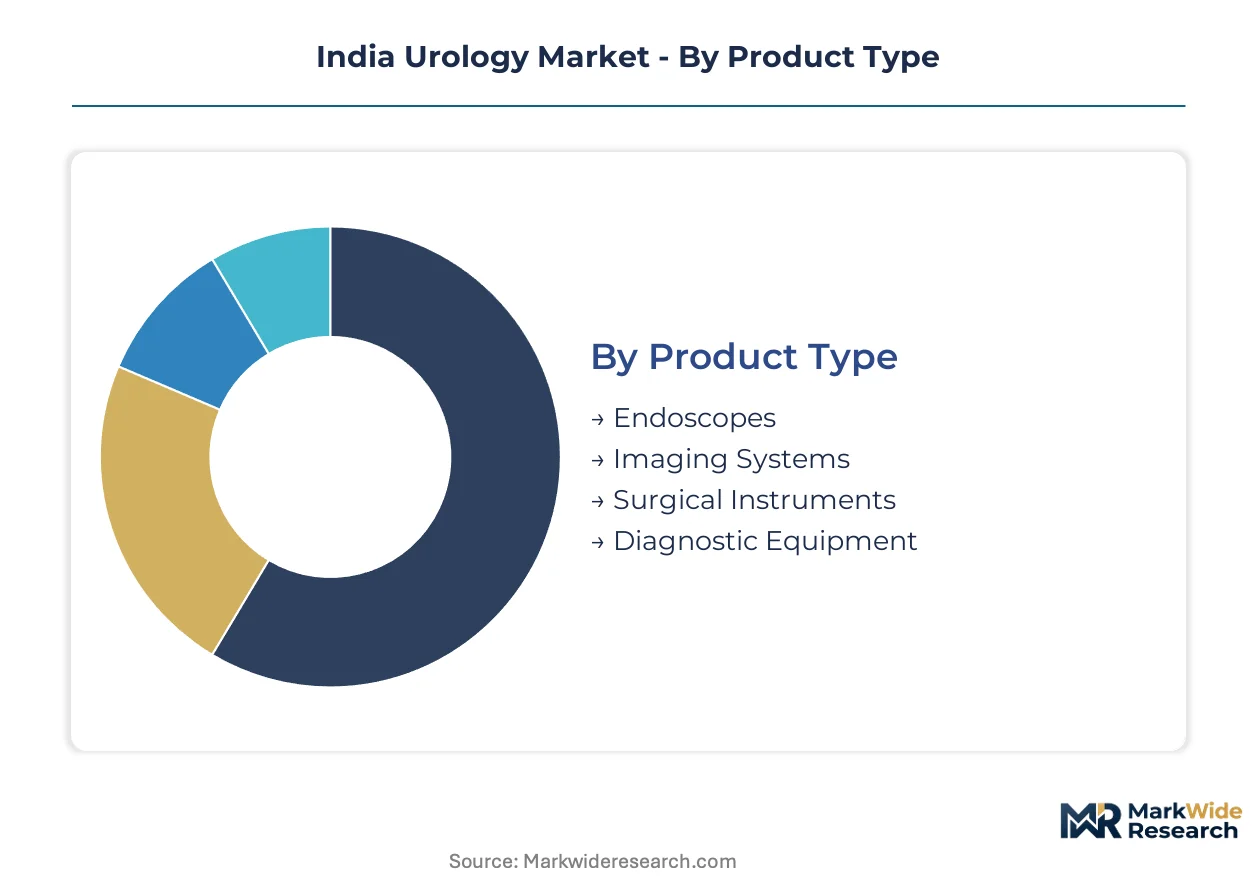
Equipment capital intensity and reimbursement category stability dictate procurement patterns across Indian urology departments. Segmentation reveals where domestic manufacturing incentives under PLI scheme compress import dependence versus where foreign exchange exposure constrains technology diffusion.
Product Type:
Endoscopes and imaging systems demand the heaviest upfront capital deployment, with metropolitan teaching hospitals budgeting for 4K-8K visualization suites to capture medical tourism revenue.
- Endoscopes:Rigid cystoscopes and flexible ureteroscopes with 4K-8K optical resolution form the procedural backbone of stone and prostate interventions. Demand clusters in Mumbai and Delhi tier-one hospitals replacing legacy fleets; CDSCO's streamlined approval pathways accelerate domestic assembly of standard rigid instruments.
- Imaging Systems:Ultrasound platforms with real-time elastography and CT-fluoroscopy fusion enable precision targeting for percutaneous nephrolithotomy. Southern India's specialty urology centers in Tamil Nadu and Karnataka drive procurement; Ayushman Bharat reimbursement for pre-operative stone mapping pulls volume into tier-two networks.
- Surgical Instruments:Lithotripter handpieces and electrosurgical generators serve high-throughput stone centers.
- Diagnostic Equipment:Uroflowmetry systems and portable ultrasound dominate ambulatory screening workflows.
Endoscopes absorb the bulk of installed capacity; imaging systems are expanding most quickly as hospitals compete for referral networks.
Application:
Procedure volume and pricing power diverge sharply across clinical indications, with benign conditions driving throughput while oncology commands multidisciplinary care premiums.
- Kidney Stones:Percutaneous nephrolithotomy and ureteroscopic laser lithotripsy constitute the highest annual procedure volume nationwide. Tamil Nadu's stone belt districts generate concentrated demand; seasonal dehydration patterns in central India create predictable capacity planning cycles for lithotripter operators.
- Prostate Disorders:Transurethral resection and emerging laser enucleation procedures target India's aging male demographic. Bangalore and Hyderabad corporate hospital chains invest in holmium laser platforms to differentiate from standard monopolar resection; fellowship-trained surgeon scarcity constrains system utilization rates.
- Bladder Control:Sacral neuromodulation and sling procedures address stress and urge incontinence.
- Uro-Oncology:Robotic radical prostatectomy and nephron-sparing surgery require integrated oncology-radiology-urology multidisciplinary teams.
Kidney stone interventions absorb the bulk of installed capacity; uro-oncology is climbing the fastest as robotic platform deployment accelerates in metropolitan chains.
End User:
Capital access and sterilization infrastructure availability segment the customer base, with public procurement channels prioritizing cost-engineered alternatives.
- Hospitals:Tier-one corporate chains in Mumbai, Delhi, and Bangalore deploy integrated surgical platforms with bundled service contracts. CDSCO's PLI scheme eligibility criteria steer government hospital procurement toward domestically assembled standard instruments; 60% of tier-two facilities lack hydrogen peroxide sterilization for flexible endoscopes.
- Specialty Clinics:Single-specialty urology chains in Gujarat and Rajasthan favor equipment leasing with per-procedure revenue sharing. Kerala and Andhra Pradesh coastal cities present greenfield expansion opportunities with limited competitor density and aging demographics.
- Research Institutes:Academic medical centers in Karnataka and Tamil Nadu host training programs driving technology evaluation and adoption curves.
- Diagnostic Labs:Standalone imaging centers perform pre-operative stone volume analysis and post-operative surveillance.
Hospitals absorb the bulk of installed capacity; specialty clinics are gaining share fastest through capital-light leasing structures.
Technology:
Regulatory classification maturity and import dependence determine commercialization velocity, with newer modalities facing extended validation timelines.
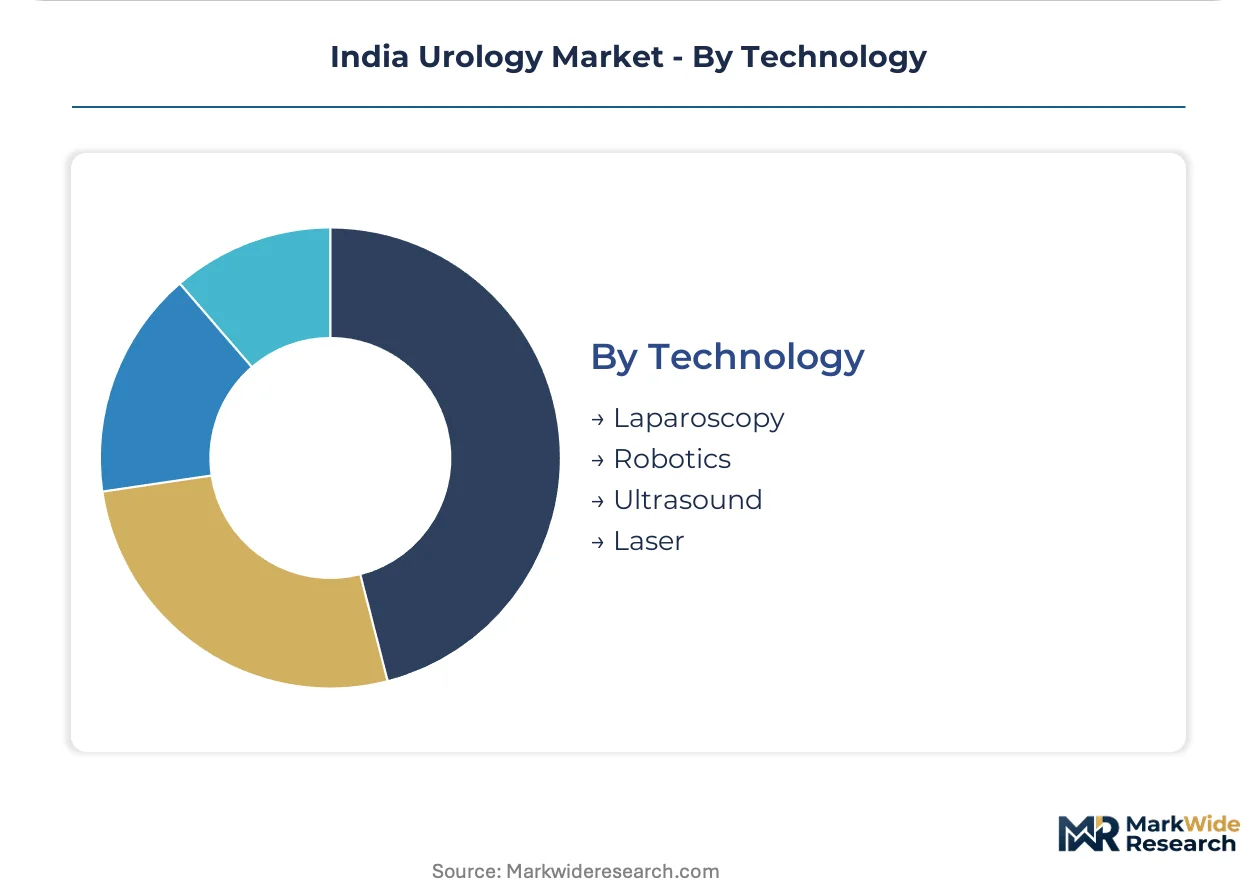
- Laparoscopy:Mature instrumentation with established sterilization protocols and surgeon training pipelines dominates tier-two hospital adoption. Domestic manufacturers under PLI scheme capture standard trocar and grasper demand; metropolitan teaching hospitals migrate toward 4K visualization integration.
- Robotics:Da Vinci and Versius platforms face 100% foreign exchange exposure and twelve-to-eighteen month procurement cycles. Only Mumbai, Delhi, and Bangalore corporate chains justify capital deployment; MCh fellowship programs produce insufficient console-certified surgeons to match installed capacity.
- Ultrasound:Portable platforms with cloud-based stone volume analysis enable tele-urology pre-operative planning for district hospital networks.
- Laser:Holmium and thulium fiber systems for lithotripsy and prostate enucleation face single-source supply fragility from German and Japanese manufacturers.
Laparoscopy absorbs the bulk of installed capacity; robotics shows the steepest expansion trajectory where capital and surgeon availability align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Delhi anchor the India urology device landscape, with tier-one hospitals in these metros expanding minimally invasive surgical suites to capture medical tourism revenue from Gulf and African patients.
Maharashtra
Mumbai's corporate hospital chains drive demand for 4K-8K endoscopic visualization systems and robotic surgical platforms. CDSCO's streamlined medical device approval pathways accelerate import clearance for premium equipment. The Mumbai-Pune corridor hosts the highest concentration of fellowship-trained urologists and MCh training programs.
Delhi-NCR
Delhi's public and private hospital networks generate concentrated procurement volume for dialysis and renal care infrastructure under Ayushman Bharat expansion. The PLI scheme for domestic manufacturing incentivizes local assembly of standard surgical instruments in neighboring Haryana industrial zones. Gurugram and Faridabad host emerging medical device manufacturing clusters serving government procurement channels.
Karnataka
Bangalore's corporate hospital chains invest in holmium laser platforms and robotic-assisted surgical systems to differentiate urology service offerings. BIS electrical safety certification requirements govern deployment of domestically assembled electrosurgical generators. The state hosts major academic medical centers driving technology evaluation and surgeon training pipelines.
Tamil Nadu
Chennai and Coimbatore specialty urology centers generate sustained demand for stone management equipment and flexible ureteroscopes. Seasonal dehydration patterns in central Tamil Nadu's stone belt districts create predictable capacity planning cycles for lithotripter operators. The state maintains India's highest density of specialty urology centers and endourology training institutes.
Telangana
Hyderabad's corporate hospital chains are expanding robotic surgery programs amid competition for medical tourism revenue. CDSCO conditional approval pathways for AI-assisted diagnostic modules attract Bangalore-based startups developing stone detection algorithms. The city's diagnostic lab networks perform pre-operative stone volume analysis for tier-two hospital referrals.
India Urology Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling capabilities. The India urology market structures around a sharp bifurcation between integrated surgical platform vendors and specialized component suppliers. Three archetypes dominate: multinational integrated system providers, regional service-network anchored distributors, and domestic PLI-scheme beneficiaries targeting government procurement. Competitive moves concentrate on equipment leasing with bundled maintenance contracts and backward integration into sterilization-compatible disposable manufacturing.
Among multinational integrated system providers, Stryker India Pvt. Ltd. and Fresenius Medical Care India Pvt. Ltd. occupy positions exemplifying divergent strategic emphases—surgical platform integration versus dialysis infrastructure scale. Cook Medical India represents the specialized interventional portfolio archetype, with domestic manufacturers under the PLI scheme increasingly challenging standard instrument categories.
| Leading Market Players |
|---|
| Stryker India Pvt. Ltd. |
| Fresenius Medical Care India Pvt. Ltd. |
| Boston Scientific India Pvt Ltd |
| Becton Dickinson Private Limited |
| B. Braun Medical (India) Pvt. Ltd. |
| Olympus Medical Systems India Pvt Ltd |
| India Medtronic Pvt. Ltd. |
| KARL STORZ Endoscopy, India Pvt. Ltd. |
| Cook Medical India |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialty clinic chains in Gujarat and Rajasthan anchor pricing discipline through per-procedure revenue-sharing contracts, compressing capital deployment timelines while forcing equipment financiers to absorb residual sterilization infrastructure risk. This ownership pattern tightens supply chain responsiveness as lessors demand shorter procurement cycles from domestic PLI-scheme manufacturers serving government hospital channels.
Pricing Analysis
Outcome-based pricing anchored to procedure throughput dominates metropolitan hospital procurement, with 4K-8K visualization suites commanding premiums tied to medical tourism patient volumes. Three-tier pricing structure across premium, standard, and economy levels separates Da Vinci robotic platforms from holmium laser systems and domestically assembled rigid cystoscopes. Cost compression in standard instrument tiers intensifies as PLI scheme subsidies expand local assembly capacity. Government procurement channels exhibit highest price sensitivity; corporate hospital chains in Mumbai and Delhi prioritize uptime guarantees over per-unit acquisition cost.
Supply Chain Analysis
Workforce availability in Haryana's industrial zones and Tamil Nadu's medical device corridors shapes domestic manufacturing scale for standard surgical instruments under PLI scheme incentives. Supply concentrates in Germany and Japan for holmium laser fibers, in the United States for robotic surgical platforms, and in India for electrosurgical generators and rigid endoscopes. Single-source vulnerability for fiber components creates procedure-day availability risk. Distribution runs through regional service-network distributors with sterilization-compatible disposable backward integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India urology market functions as a vertical-integration race where control over sterilization-compatible disposable manufacturing determines margin capture. Players are pursuing downstream integration into hydrogen peroxide sterilization infrastructure to unlock flexible ureteroscope deployment in tier-two networks.
For Market Incumbents: Lock in surgeon training pipelines through MCh fellowship program partnerships, insulating robotic console utilization rates from emerging domestic laser platform competitors. Prioritize backward integration into single-use flexible ureteroscope manufacturing to automate reprocessing workflow elimination for high-volume stone centers. For New Entrants and Emerging Players: Enter via Kerala and Andhra Pradesh coastal cities where aging demographics and limited competitor density create greenfield ambulatory surgical center opportunities. Target tele-urology diagnostic convergence through portable ultrasound with cloud-based stone volume analysis for district hospital networks. Pursue CDSCO conditional approval pilot positioning for AI-assisted polyp detection modules in cystoscopy. For Investors and Strategic Acquirers: CDSCO's 2023 risk-based classification amendment for software-as-a-medical-device is the leading indicator that clinical validation requirements will consolidate Bangalore-based startup competition. Long-term viability rests on acquiring domestic manufacturers with established BIS certification pathways and PLI scheme eligibility. Monitor Ayushman Bharat reimbursement expansion announcements as volume inflection signals for tier-two hospital network penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker India secures bundled maintenance contracts across Mumbai-Delhi tier-one chains. |
| CE Marking Pathway | Domestic manufacturers accelerate European market entry for PLI-scheme produced instruments. |
| Software Companion Development | Bangalore startups integrate AI stone detection with portable ultrasound platforms. |
| Reimbursement Strategy | Fresenius Medical Care aligns dialysis infrastructure with Ayushman Bharat expansion timelines. |
| Backward Integration | Cook Medical India captures margin through captive supply of anatomically tailored stent portfolios. |
Research Methodology
CDSCO registration databases, hospital procurement records, and PLI scheme beneficiary disclosures formed the secondary backbone, cross-referenced with primary interviews with urology department heads, biomedical engineers, GPO contracts managers, and equipment leasing financiers. Bottom-up triangulation across installed base estimates and top-down validation through reimbursement expansion modeling anchored segmentation outputs.
Historical trendline analysis of procedure volume growth across kidney stone, prostate disorder, and uro-oncology applications informed projection frameworks. Segmentation dimensions spanned product type, application, end user, and technology maturity tier. CAGRs derived from weighted average of procedure volume trajectories and capital deployment cycle compression observed across tier-two hospital networks.
Revisions become necessary when CDSCO regulatory amendments tighten software-as-a-medical-device validation requirements, PLI scheme eligibility criteria shift, or Ayushman Bharat reimbursement categories exclude previously covered procedures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Voiding Cystourethrogram Market
Urology
North America Transrectal Ultrasound Market
Urology
Europe Bladder Disorders Market
Urology
Urology Devices Market
Urology
Ureter Cancer Treatment Market
Urology
US Urology Devices Market
Urology
Global Hydronephrosis Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Global Bladder Scanner Market
Urology
Self-Intermittent Catheters Market
Urology
Ureteral Obstruction Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Urinary Incontinence Market