
 Urinary Retention Drugs Market | 2026-2036
Urinary Retention Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Retention Drugs Market Intelligence
Urology clinics are reorganizing procurement priorities around outpatient alpha-blocker protocols. Astellas Pharma sustains leadership in benign prostatic hyperplasia-linked retention through its urology-focused commercial infrastructure. Pfizer leverages broad hospital formulary access to compete across acute and chronic settings. AbbVie anchors its position through specialty care networks that coordinate urologist-pharmacist prescribing pathways.
Urinary retention drugs comprise pharmacological agents that modulate detrusor muscle contractility or relax bladder outlet resistance through selective receptor targeting, with alpha blockers achieving onset within hours via adrenergic antagonism and 5-alpha reductase inhibitors requiring months for prostate volume reduction. These therapeutics restore voiding function across obstructive, neurogenic, and iatrogenic etiologies. Alpha blockers occupy the dominant revenue position due to rapid symptom relief and extensive generic availability. Cholinergic agents represent the fastest-expanding category as neurogenic bladder management migrates toward outpatient settings. Hospital pharmacies capture the deepest margin pools through bundled procurement of perioperative retention protocols.
The FDA governs new drug approvals and bioequivalence standards for generic alpha-blocker substitutions, while the EMA's MDR framework shapes device-drug combination products used in catheterization-sparing protocols. Japan's PMDA enforces localized pharmacovigilance requirements that extend post-approval commitment timelines for cholinergic agents. Stakeholders must monitor evolving reimbursement thresholds for catheter-free recovery pathways as payers scrutinize comparative effectiveness data.
Market Dynamics
Hospital procurement departments are consolidating perioperative urinary retention protocols around catheter-sparing pharmacological pathways, compressing traditional device-centric supply chains and elevating formulary positioning for alpha-blocker and cholinergic agents.
Growth Catalysts
- FDA 505(b)(2) Pathway:The streamlined approval mechanism for reformulated urological agents accelerates generic market entry and expands therapeutic options for acute retention management.
- Postoperative Protocol Standardization:Surgical departments across Germany and Japan are embedding alpha-blocker prophylaxis into enhanced recovery after surgery pathways, institutionalizing pharmacological first-line intervention.
- Neurogenic Bladder Migration:Outpatient management of spinal cord injury and multiple sclerosis patients is displacing inpatient catheterization, driving cholinergic agent volume through home healthcare channels.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Tamsulosin and solifenacin precursor supply clusters in Indian and Chinese manufacturing corridors, exposing formularies to geopolitical logistics disruption.
- Reimbursement Compression:Medicare's hospital outpatient prospective payment system bundles catheterization and pharmacological retention management into single episode rates, constraining standalone drug pricing flexibility.
- Generic Erosion Velocity:Patent cliff dynamics for dutasteride and silodosin formulations compress branded revenue windows before prostate volume reduction benefits achieve clinical documentation.
Strategic Opportunities
- Underpenetrated Home Infusion:Japan's aging rural prefectures lack urology specialist density, creating white space for telemedicine-coordinated cholinergic prescribing and remote voiding monitoring.
- Device-Drug Convergence:Smart bladder scanners integrated with automated alpha-blocker dosing algorithms represent unclaimed territory in catheterization-sparing protocols for postoperative units.
- EMA MDR Tailwind:The Medical Device Regulation framework incentivizes CE-marked combination products that pair transdermal oxybutynin with wearable biofeedback sensors, opening premium reimbursement tiers.
Industry Challenges
- Specialty Pharmacy Integration:Hospital systems struggle to synchronize electronic health record workflows with specialty distributors handling restricted cholinergic agents, creating prescription abandonment friction.
- Pharmacovigilance Talent Scarcity:Post-market surveillance requirements for anticholinergic cognitive safety signals demand neuropharmacology expertise that exceeds current regulatory affairs staffing levels in mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Retention Drugs Market |
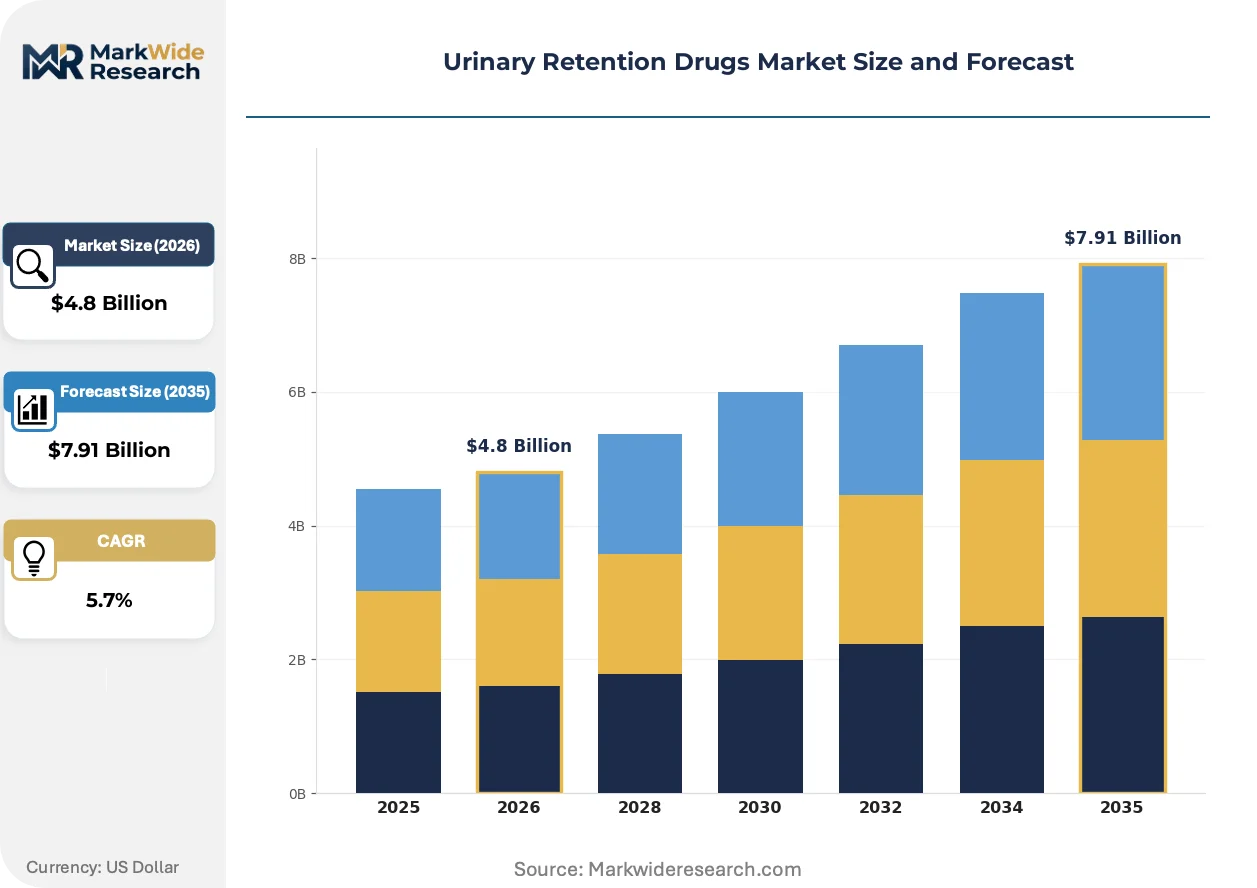
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha Blockers, Cholinergic Agents, 5-Alpha Reductase Inhibitors, Anticholinergics Application: Chronic Urinary Retention, Neurogenic Bladder, Acute Urinary Retention, Postoperative Urinary Retention End User: Hospitals, Ambulatory Surgical Centers, Urology Clinics, Long-Term Care Facilities Distribution Channel: Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesale Distributors |
| Companies Covered | AbbVie Inc., Astellas Pharma Inc., Pfizer Inc., Teva Pharmaceutical Industries Limited, Sun Pharmaceutical Industries Limited, Johnson & Johnson, Sanofi S.A., Lupin Limited, Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Retention Drugs Market Strategic Shifts & Innovations
Transdermal and implantable delivery systems are displacing oral tablet dominance in urological pharmacology, while regulatory frameworks on both sides of the Atlantic accelerate convergence between pharmaceutical and medical device approval pathways.
Intravesical botulinum toxin administration is miniaturizing through micro-needle array technologies that enable office-based detrusor injection without cystoscopic guidance. Urology clinics in the United States and Germany are adopting these systems to reduce anesthesia requirements and procedure room utilization. This miniaturization is compressing the traditional hospital-based surgical intervention model for neurogenic bladder toward ambulatory reimbursement structures.
EMA's Medical Device Regulation is mandating clinical evidence standards for catheterization-sparing drug-device combinations that previously operated under pharmaceutical-only pathways. Manufacturers must now generate prospective data on device-integrated alpha-blocker delivery systems before CE marking. The catheter-free recovery segment faces the steepest compliance burden, with several European hospital consortia delaying procurement until 2026 guidance clarifications.
Buyers are unbundling after-sales clinical support from product procurement, with integrated delivery networks negotiating standalone contracts for pharmacist-led patient education on alpha-blocker orthostatic hypotension management. This disintermediation of manufacturer field forces is most pronounced in United States Medicare Advantage plans, where risk-bearing entities internalize medication therapy management to reduce emergency department visits for syncope-related falls.
Urinary Retention Drugs Market Segmentation
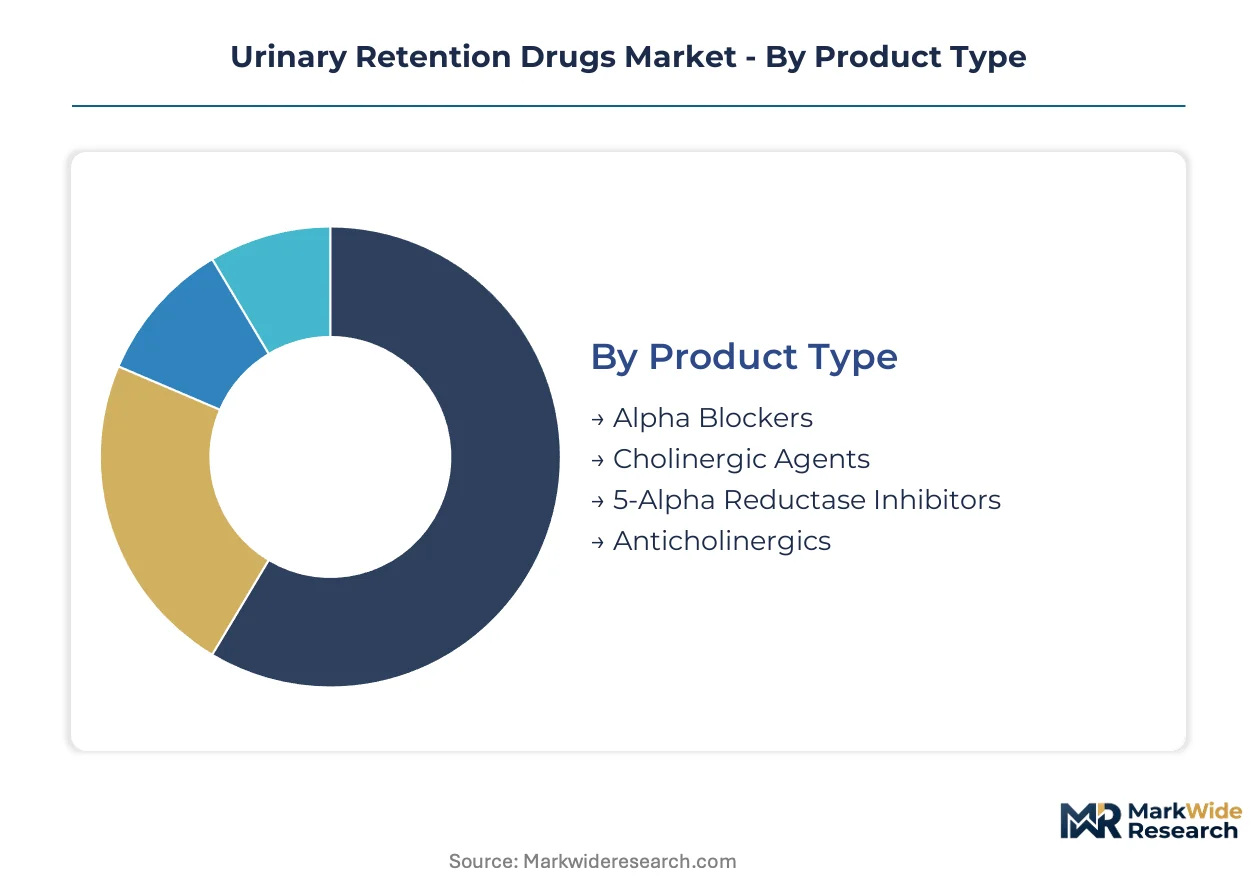
Urinary retention therapeutics traverse fragmented procurement channels where hospital formularies, retail pharmacies, and emerging telemedicine platforms each demand distinct product configurations. Segment boundaries increasingly blur as catheter-sparing protocols force cross-channel coordination between acute and chronic care settings.
Product Type:
Hospital procurement departments route alpha-blockers through centralized formularies while cholinergic agents flow through specialty distributors with cold-chain requirements.
- Alpha Blockers:These adrenergic antagonists achieve symptomatic relief within hours through selective relaxation of prostatic smooth muscle. Demand concentrates in United States Medicare Advantage plans where bundled surgical episode payments incentivize rapid postoperative voiding restoration. Orthostatic hypotension management requirements complicate outpatient dispensing protocols.
- Cholinergic Agents:Direct parasympathomimetics stimulate detrusor contraction through muscarinic receptor activation. Neurogenic bladder management in German spinal cord injury centers drives volume, though cognitive safety monitoring burdens constrain primary care prescribing.
- 5-Alpha Reductase Inhibitors:Prostate volume reduction agents requiring months for clinical effect.
- Anticholinergics:Detrusor overactivity modulators deployed in mixed retention-incontinence presentations.
By volume, Alpha Blockers leads. By growth pace, Cholinergic Agents is ahead.
Application:
Cost tier stratification separates acute intervention protocols reimbursed under surgical bundles from chronic management funded through pharmacy benefit structures.
- Postoperative Urinary Retention:Catheter-sparing pharmacological protocols embedded in enhanced recovery after surgery pathways. United States hospital systems and Japanese surgical departments institutionalize alpha-blocker prophylaxis to reduce catheter-associated urinary tract infection rates and shorten length-of-stay metrics.
- Neurogenic Bladder:Spinal cord injury and multiple sclerosis etiologies requiring coordinated urologist-pharmacist prescribing pathways. Outpatient migration in Germany displaces inpatient catheterization, elevating home healthcare channel volume for intermittent self-catheterization alternatives.
- Chronic Urinary Retention:Long-term obstructive etiology management with benign prostatic hyperplasia predominating.
- Acute Urinary Retention:Emergency department presentation requiring rapid pharmacological or mechanical intervention.
By patient encounters, Postoperative Urinary Retention dominates. By expansion trajectory, Neurogenic Bladder climbs the fastest.
End User:
Customer type determines formulary leverage, with integrated delivery networks extracting steeper rebates than independent urology practices.
- Hospitals:Centralized procurement of perioperative retention protocols with bundled device-drug contracting. Deep margin pools attract manufacturer field force investment, though electronic health record integration friction complicates specialty pharmacy synchronization.
- Urology Clinics:Outpatient alpha-blocker prescribing with micro-needle botulinum toxin adoption compressing surgical referral patterns. German and United States ambulatory settings lead intravesical administration miniaturization.
- Ambulatory Surgical Centers:Fast-turnover environments favoring rapid-onset pharmacological agents.
- Long-Term Care Facilities:Aging resident populations with polypharmacy complexity and fall risk considerations.
By procurement scale, Hospitals leads. By volume growth, Urology Clinics is expanding most quickly.
Distribution Channel:
Supply concentration in Indian and Chinese active pharmaceutical ingredient corridors exposes each channel to geopolitical logistics disruption.
- Hospital Pharmacies:Captive dispensing integrated with electronic health record workflows and medication therapy management programs. United States Medicare Advantage risk-bearing entities internalize pharmacist-led patient education to reduce emergency department visits for syncope-related falls.
- Wholesale Distributors:Consolidated procurement of generic alpha-blockers with inventory pooling across regional hospital consortia. Cold-chain requirements for cholinergic agents limit distributor consolidation compared to ambient small-molecule categories.
- Pharmacies:Retail dispensing with prior authorization friction for branded agents.
- Online Pharmacies:Direct-to-patient fulfillment with telemedicine coordination in Japan's rural prefectures.
By revenue concentration, Hospital Pharmacies leads. By channel growth, Online Pharmacies gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese active pharmaceutical ingredient corridors supply tamsulosin and solifenacin precursors to formularies in the United States, Germany, and Japan, creating concentrated trade-flow dependencies that shape procurement risk assessments.
United States
Medicare Advantage bundled surgical episode payments incentivize rapid postoperative voiding restoration through alpha-blocker protocols. The FDA's 505(b)(2) pathway accelerates generic entry for reformulated urological agents. Hospital procurement departments in the Southeast and Midwest consolidate perioperative retention formularies around catheter-sparing pharmacological pathways.
Germany
Spinal cord injury centers drive cholinergic agent volume as neurogenic bladder management migrates toward outpatient settings. The EMA's MDR framework mandates clinical evidence standards for device-drug combinations before CE marking. Bavarian and North Rhine-Westphalian hospital consortia embed alpha-blocker prophylaxis into enhanced recovery after surgery pathways.
Japan
Aging rural prefectures lack urology specialist density, creating demand for telemedicine-coordinated cholinergic prescribing. PMDA pharmacovigilance requirements extend post-approval commitment timelines for cognitive safety monitoring. Kanto and Kansai regions institutionalize catheter-free recovery protocols in surgical departments to reduce length-of-stay metrics.
India
Domestic manufacturing clusters produce tamsulosin precursors for export to regulated markets while serving a growing domestic patient base. CDSCO oversight governs bioequivalence standards for generic alpha-blocker substitutions. Gujarat and Maharashtra-based API facilities face geopolitical logistics exposure that Western formularies factor into supply security planning.
China
Dual carbon goals and environmental compliance costs are reshaping solifenacin precursor production economics in coastal manufacturing zones. NMPA regulates new drug approvals with increasing alignment to international bioequivalence standards. Yangtze River Delta chemical corridors supply intermediate compounds to global pharmaceutical finishers under intensifying sustainability scrutiny.
Urinary Retention Drugs Market Key Industry Players
Player mix skews toward diversified pharmaceutical conglomerates with urology-focused commercial infrastructure alongside mid-tier generic specialists. Market structure exhibits tiered consolidation where hospital formulary access determines competitive positioning. Three archetypes dominate: Big Pharma with broad therapeutic portfolios, urology-focused specialists with dedicated field forces, and API-integrated generic manufacturers with cost-positioning advantages. Competitive moves center on strategic partnerships for device-drug convergence and geographic expansion into underpenetrated home infusion channels.
Among Japan-based pharmaceutical conglomerates, Astellas Pharma Inc. anchors the urology-focused specialist archetype through its dedicated commercial infrastructure. Pfizer Inc. and AbbVie Inc. represent the diversified Big Pharma tier, leveraging broad hospital formulary access and specialty care network coordination respectively. These three companies exemplify how competitive positioning in urinary retention therapeutics depends on channel-specific capabilities rather than molecule differentiation alone.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Limited |
| Sun Pharmaceutical Industries Limited |
| Johnson & Johnson |
| Sanofi S.A. |
| Lupin Limited |
| Merck & Co. Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for tamsulosin and solifenacin precursors lock in supply access for United States and German hospital formularies while anchoring price visibility against API volatility. These contracts insulate procurement departments from spot-market swings in Indian and Chinese manufacturing corridors.
Pricing Analysis
Generic-generation pricing gaps separate rapid-onset alpha-blockers from slower-acting 5-alpha reductase inhibitors and emerging cholinergic formulations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence tiering and cold-chain handling requirements. Cost compression in the generic alpha-blocker tier intensifies because Medicare bundled episode payments constrain standalone drug pricing flexibility. United States Medicare Advantage plans exhibit highest price sensitivity due to risk-bearing structures, while Japanese hospital systems show lowest sensitivity where PMDA pharmacovigilance commitments justify premium positioning.
Supply Chain Analysis
Inbound logistics costs through Nhava Sheva and Shanghai-Ningbo corridors fluctuate with container availability and Red Sea routing disruptions, elevating landed costs for European formularies. Active pharmaceutical ingredient production clusters in Gujarat, Maharashtra, and Yangtze River Delta chemical zones, drawing from specialized precursor chemistries and fermentation-based intermediate processes. Single-source vulnerability concentrates in solifenacin precursor supply where environmental compliance costs are reshaping Chinese coastal manufacturing economics. Distribution runs through wholesale distributors with inventory pooling across regional hospital consortia, though cold-chain requirements for cholinergic agents limit consolidation compared to ambient small-molecule categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary retention drugs market tracks a cyclical recovery pattern as surgical volumes normalize and catheter-sparing protocols institutionalize across postoperative pathways. Hospital procurement department budget cycles and generic patent cliff dynamics create predictable compression-expansion rhythms.
For Market Incumbents: Consolidate formulary positioning through backward integration into API supply and captive production of tamsulosin precursors in Indian manufacturing zones. Deepen hospital system partnerships by embedding clinical pharmacists into medication therapy management workflows, countering Medicare bundled payment pressure that compresses standalone drug margins.
For New Entrants and Emerging Players: Differentiate on device-drug convergence by developing wearable biofeedback sensors paired with transdermal oxybutynin delivery, exploiting EMA MDR premium reimbursement tiers. Japan's aging rural prefectures offer the most penetrable geography where telemedicine-coordinated cholinergic prescribing addresses urology specialist scarcity.
For Investors and Strategic Acquirers: Urology-focused commercial infrastructure specialists with dedicated field forces and established hospital formulary access represent the priority acquisition archetype. Monitor FDA 505(b)(2) approval velocity as an inflection signal indicating generic competition intensity and reformulated agent market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Device-Drug Combination Development | EMA MDR compliance opens premium reimbursement tiers for catheter-sparing protocols in German hospital consortia. |
| API Manufacturing Scale-Up | Captive production in Indian chemical corridors insulates formularies against geopolitical logistics disruption. |
| Specialty Pharmacy Integration | Electronic health record synchronization reduces prescription abandonment friction for restricted cholinergic agents. |
| Telemedicine Platform Partnership | Remote voiding monitoring expands addressable market in Japan's urology specialist-deficient rural prefectures. |
| Pharmacovigilance Capability Buildout | Anticholinergic cognitive safety monitoring expertise addresses regulatory staffing scarcity at mid-tier manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, urology clinic directors, regulatory affairs leads, and specialty pharmacy operators and refined through secondary validation. FDA 505(b)(2) filings, EMA MDR guidance documents, PMDA pharmacovigilance protocols, and hospital formulary databases anchored quantitative triangulation. Bottom-up prescription volume modeling and top-down therapeutic category expenditure analysis converged on segment-level estimates.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension modeled: pharmacological class, application etiology, end-user facility type, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with neurogenic bladder outpatient migration rates and catheter-sparing protocol adoption curves serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicare bundled payment structures or stable API trade flows would require recalibration. Forecasts reflect documented assumptions regarding surgical volume normalization and generic entry timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Antiviral Drugs Market