
 Antiviral Drugs Market | 2026-2036
Antiviral Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antiviral Drugs Market Analysis
Virology-trained medicinal chemists are redrawing the pace of antiviral pipeline advancement as Big Pharma and biotech sponsors compete for scarce talent. Gilead Sciences leverages its nucleotide prodrug platform to sustain dominance in hepatitis C and HIV combination therapies. Merck anchors its position through oral antiviral development for respiratory pathogens, while Pfizer competes by extending small-molecule manufacturing scale across multiple therapeutic modalities.
Antiviral drugs comprise synthetic or biologically derived agents engineered to interrupt viral replication through enzyme inhibition, genome integration blockade, or host-cell entry prevention, with molecular weight thresholds and lipophilicity profiles dictating oral bioavailability and tissue penetration. Their primary commercial purpose centers on reducing viral load, transmission rates, and disease severity in infected populations. Nucleoside analogues occupy the largest revenue share due to decades of clinical validation and generic availability, while protease inhibitors command premium pricing in HIV combination regimens where resistance profiles differentiate therapeutic value. Oral delivery mode leads prescription volumes globally, though intravenous formulations retain higher per-dose margins in hospital settings where compliance monitoring justifies administration costs.
FDA breakthrough therapy designation and EMA priority medicines pathways are compressing development timelines for novel antiviral mechanisms, while WHO prequalification standards shape access dynamics in low-income procurement markets. EPA environmental assessment requirements for manufacturing discharge are adding compliance layers to active pharmaceutical ingredient production, particularly for nucleoside analogues with ecotoxicity profiles. Stakeholders must monitor how regulatory convergence on real-world evidence requirements reshapes post-approval commitment burdens and lifecycle management strategies.
Market Dynamics
Hospital procurement of antiviral therapies is intensifying as viral respiratory infections strain inpatient capacity worldwide, while FDA breakthrough therapy designation compresses development timelines and reshapes competitive entry patterns.
Growth Catalysts
- FDA Accelerated Approval Pathways:Breakthrough therapy designation compresses clinical trial phases and enables earlier commercial entry for novel mechanisms targeting unmet viral diseases.
- Medicare Reimbursement Structures:US federal procurement programs sustain above-average prescription volumes through pandemic preparedness stockpiling and hospital formulary inclusion mandates.
- Nucleotide Prodrug Platforms:Advanced medicinal chemistry capabilities enable once-daily dosing regimens that improve adherence in chronic hepatitis C and HIV management.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Nucleoside analogue manufacturing concentrates in China and India, creating single-source vulnerabilities for Western formulation facilities.
- Ecotoxicity Compliance Burden:EPA environmental assessment requirements for manufacturing discharge add cost layers to nucleoside production with documented aquatic toxicity profiles.
- Generic Substitution Pressure:Off-patent protease inhibitors and nucleoside analogues face rapid commoditization in HIV combination therapy markets.
Strategic Opportunities
- WHO Prequalification Standards:Low-income country procurement programs create volume opportunities for manufacturers meeting international quality benchmarks at reduced margins.
- Oral Antiviral Expansion:Respiratory pathogen indications beyond influenza represent white space where small-molecule bioavailability advantages over biologics concentrate investment.
- Host-Cell Entry Inhibition:Convergence of structural biology and cryo-EM capabilities enables novel mechanism discovery against emerging viral families.
Industry Challenges
- Virology Medicinal Chemist Scarcity:Specialized talent pools for antiviral drug design remain shallow relative to oncology and immunology, extending recruitment cycles for pipeline programs.
- Resistance Surveillance Infrastructure:Real-world evidence collection for post-approval commitment burdens requires investment in sequencing networks and clinical data integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiviral Drugs Market |
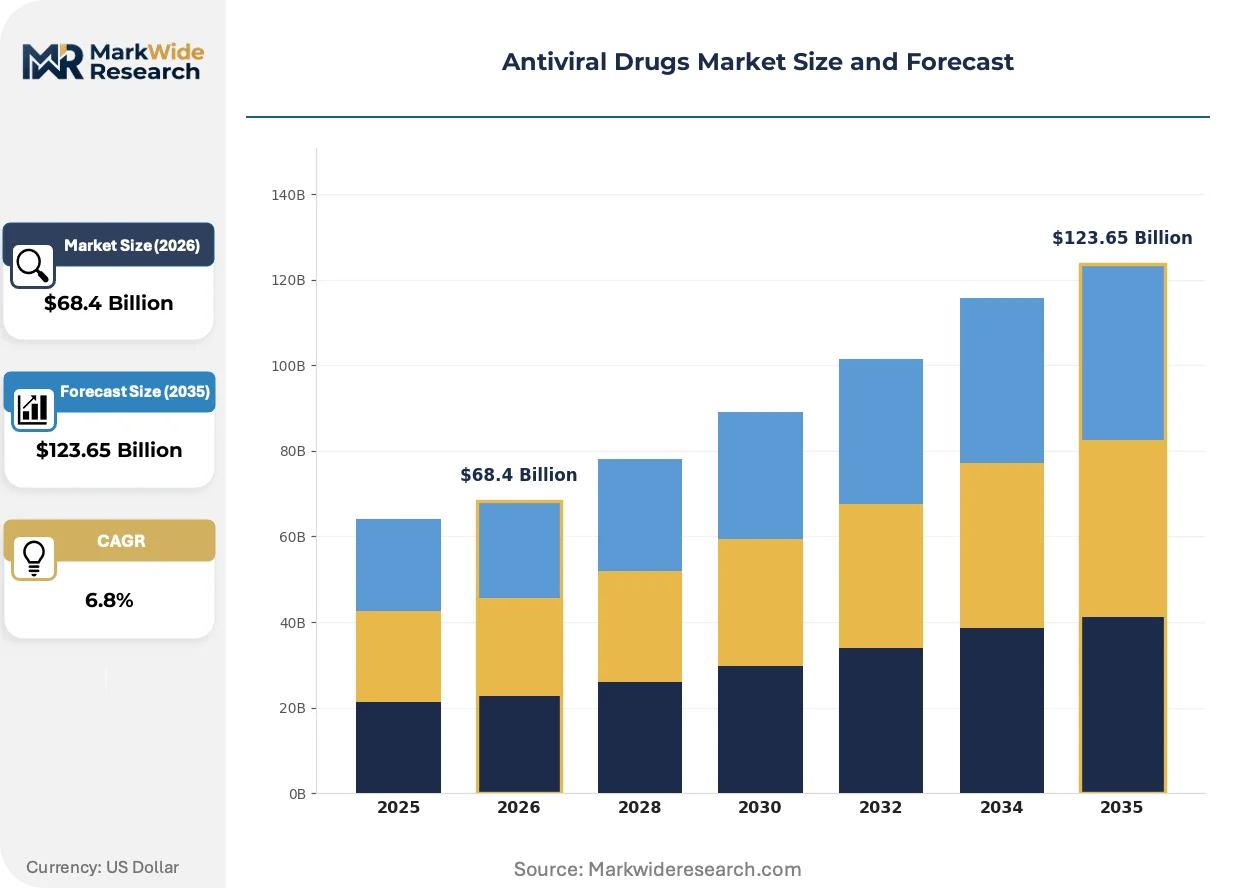
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleoside Analogues, Non-Nucleoside Inhibitors, Protease Inhibitors, Entry Inhibitors Therapy Area: HIV, Hepatitis, Influenza, Herpes Simplex Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Research Laboratories |
| Companies Covered | Gilead Sciences, GlaxoSmithKline, Merck, F. Hoffmann-La Roche, AbbVie, Bristol-Myers Squibb, Johnson & Johnson, Pfizer, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiviral Drugs Market Emerging Trajectories
Antiviral development is pivoting toward platform-based approaches that compress discovery timelines while regulatory convergence on real-world evidence requirements reshapes lifecycle management strategies.
RNA-dependent RNA polymerase inhibition is decomposing traditional antiviral development paradigms by enabling broad-spectrum activity across viral families. Large pharmaceutical sponsors and government procurement agencies are accelerating adoption of these mechanisms for pandemic preparedness stockpiles. This technology is decomposing the historical trade-off between spectrum breadth and potency, enabling single-agent coverage of multiple respiratory pathogens.
EMA priority medicines pathways and FDA breakthrough designations are compressing review timelines for novel mechanisms targeting emerging viral threats. Manufacturers are reconfiguring clinical development programs to generate real-world evidence earlier in the commercial lifecycle. Hospital formulary committees in Germany and France are prioritizing these expedited therapies for stockpiling contracts.
Hospital-based procurement consolidation is compressing vendor qualification cycles and favoring suppliers with integrated manufacturing and distribution capabilities. Group purchasing organizations are displacing direct manufacturer relationships in acute care antiviral purchasing. This concentration is most visible in the United States, where Medicare reimbursement structures align hospital incentives toward standardized formularies.
Antiviral Drugs Market Segmentation
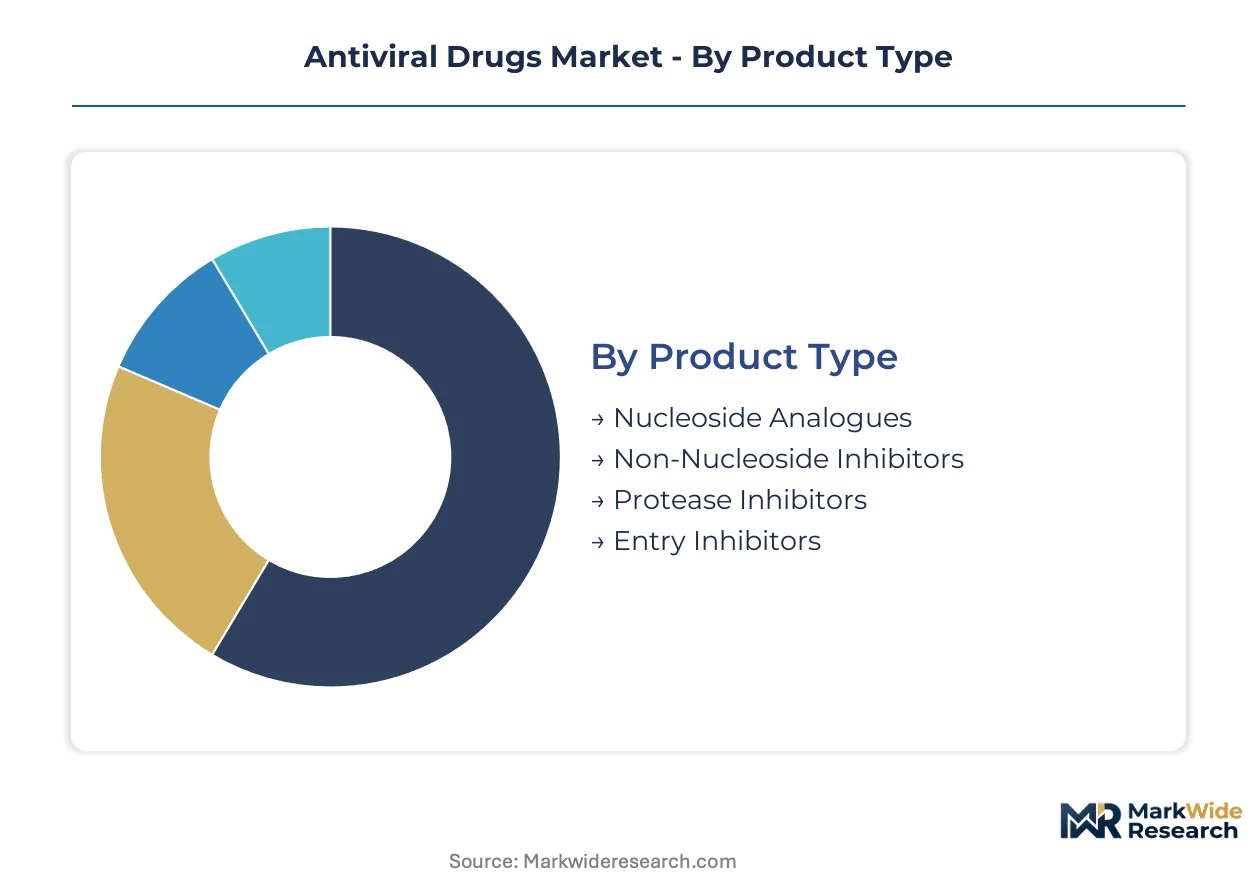
Antiviral drug segmentation reveals divergent margin structures across molecular mechanisms and care settings. Product type and delivery mode categories concentrate profitability where formulation complexity creates manufacturing moats, while therapy area and end user dimensions expose volume-leverage opportunities in chronic disease management.
Product Type:
Margin pools concentrate in protease inhibitors and entry inhibitors where resistance profiles sustain premium positioning, while nucleoside analogues compete on manufacturing scale and generic substitution resilience.
- Nucleoside Analogues:Synthetic compounds that mimic natural nucleosides to terminate viral DNA chain elongation. Hospital procurement in the United States favors these agents for hepatitis C and HIV regimens where decades of clinical validation reduce formulary resistance. Generic availability compresses per-unit margins but sustains volume leadership through combination therapy anchoring.
- Protease Inhibitors:Small molecules that cleave viral polyproteins into functional units, requiring sophisticated stereoselective synthesis. Medicare reimbursement structures in the United States sustain above-average pricing for HIV triple-therapy combinations where resistance mutation profiles differentiate therapeutic value and justify patent-protected premiums.
- Non-Nucleoside Inhibitors:Allosteric binders that distort viral enzyme active sites without nucleoside incorporation, enabling once-daily dosing in HIV management.
- Entry Inhibitors:Peptide or small-molecule blockers of host-cell fusion mechanisms, commanding development premiums for emerging viral families where no established alternatives exist.
The dominant share belongs to nucleoside analogues, while entry inhibitors are closing the gap fastest as structural biology advances enable novel mechanism discovery against respiratory pathogens.
Therapy Area:
Application concentration varies sharply between chronic disease maintenance and acute outbreak response, with reimbursement durability and patient compliance economics determining investment prioritization.
- HIV:Lifelong combination therapy generating predictable prescription volumes through integrated care programs. The United States dominates revenue concentration where Ryan White Program funding and Medicaid expansion sustain treatment access for over one million diagnosed patients, while resistance surveillance requirements create recurring diagnostic and therapeutic upgrade cycles.
- Hepatitis:Curative intent therapies with finite treatment duration shifting value capture toward cure rates and relapse prevention. Direct-acting antiviral procurement by the Department of Veterans Affairs and correctional health systems in the United States demonstrates concentrated government purchasing power in elimination-campaign settings.
- Influenza:Seasonal and pandemic stockpiling demand with volatile volume patterns tied to surveillance data and strain matching.
- Herpes Simplex:Recurrent infection management with high patient-initiated prescription volumes and over-the-counter substitution pressure in topical segments.
HIV retains the largest revenue base, though hepatitis is expanding most quickly as national elimination programs accelerate curative therapy access.
Delivery Mode:
Cost tier differentiation separates hospital-administered intravenous formulations from outpatient oral therapies, with bioavailability engineering and compliance economics driving modality selection.
- Oral:Small-molecule tablets and capsules dominating prescription volumes through patient self-administration and pharmacy dispensing efficiency. Nucleotide prodrug platforms enable once-daily regimens that improve adherence in chronic hepatitis C and HIV management, with the United States retail pharmacy channel capturing the majority of dispensed units through Medicare Part D and commercial insurance formularies.
- Intravenous:Hospital-based infusion therapies retaining higher per-dose margins where compliance monitoring and acute care supervision justify administration infrastructure costs. Inpatient capacity strain from respiratory viral infections is intensifying procurement of IV antivirals for severe disease presentations.
- Topical:Cream and ointment formulations for localized herpes simplex and HPV lesions with limited systemic exposure.
- Inhalation:Nebulized or dry-powder delivery for respiratory tract infections, representing developmental white space where lung deposition efficiency determines therapeutic index.
Oral delivery commands the greatest prescription volume, while inhalation is gaining share fastest as RNA polymerase inhibitors target respiratory pathogen indications.
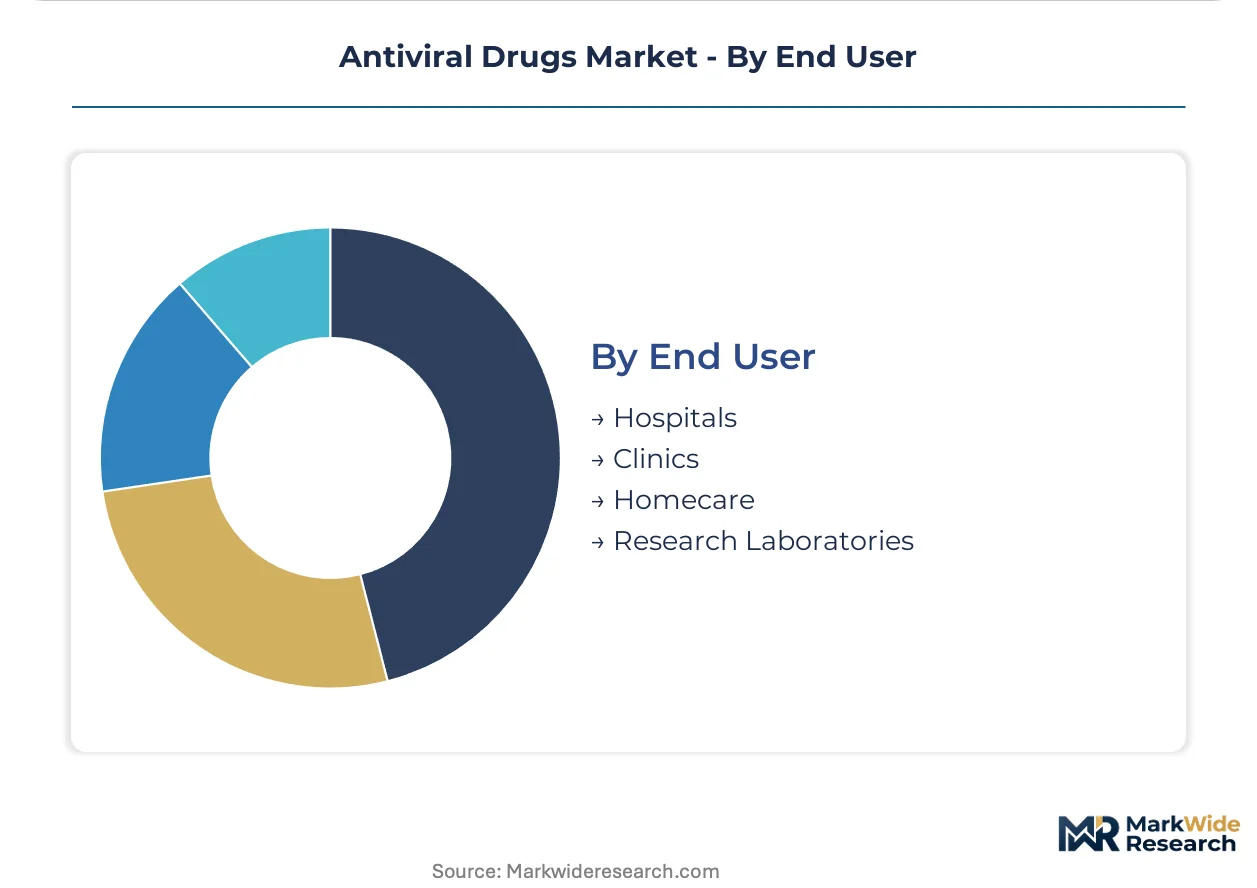
End User:
Customer type segmentation exposes procurement concentration in institutional buyers versus fragmented retail access, with formulary control and reimbursement mechanics determining competitive entry patterns.
- Hospitals:Acute care institutions with consolidated purchasing through group purchasing organizations, prioritizing IV formulations and stockpiling contracts for pandemic preparedness. Medicare reimbursement structures in the United States align hospital incentives toward standardized antiviral formularies that reduce pharmacy inventory complexity.
- Clinics:Outpatient settings including infectious disease specialists and community health centers managing chronic HIV and hepatitis caseloads.
- Homecare:Patient-directed administration supported by specialty pharmacy distribution and remote monitoring infrastructure.
- Research Laboratories:Preclinical and clinical trial supply procurement with stringent chain-of-custody and documentation requirements.
Hospitals hold the dominant procurement volume, while homecare is closing the gap fastest as oral antiviral expansion enables patient-managed therapy outside institutional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor demand concentration in the United States, while EMA priority medicines frameworks and WHO prequalification standards shape procurement dynamics across European and low-income markets respectively.
United States
Medicare reimbursement structures and pandemic preparedness stockpiling sustain above-average prescription volumes through hospital formulary inclusion mandates. The Ryan White Program and Medicaid expansion fund treatment access for over one million diagnosed HIV patients, creating predictable demand cycles. Boston and San Francisco anchor biocluster concentration where virology-trained medicinal chemists command recruitment premiums.
Germany
Hospital formulary committees prioritize expedited therapies for stockpiling contracts, compressing vendor qualification cycles for suppliers with integrated manufacturing capabilities. The country's national pharmaceutical regulator enforces stringent post-approval commitment burdens for novel antiviral mechanisms. The Rhine-Main biopharma corridor concentrates formulation facilities serving European Union distribution networks.
India
Active pharmaceutical ingredient manufacturing for nucleoside analogues concentrates in Gujarat and Maharashtra, creating supply leverage for Western formulation facilities. CDSCO regulatory harmonization with WHO prequalification standards enables low-income country procurement program participation. Hyderabad's vaccine and bulk drug cluster is expanding into nucleotide prodrug chemistry capabilities.
Japan
PMDA review timelines for breakthrough antiviral therapies align with EMA and FDA convergence patterns, enabling earlier commercial entry for respiratory pathogen indications. METI industrial policy supports domestic manufacturing resilience for pandemic preparedness stockpiles. The Kanto region's pharmaceutical R&D infrastructure anchors regional clinical trial network density.
Switzerland
Specialty chemical manufacturing for protease inhibitor synthesis leverages Basel's historical pharmaceutical chemistry expertise. Swissmedic regulatory frameworks emphasize real-world evidence collection requirements that reshape lifecycle management strategies for novel mechanisms. The country's biopharma manufacturing base serves as a European distribution hub for hospital-administered intravenous formulations.
Antiviral Drugs Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with nucleotide prodrug platforms and oral antiviral development capabilities separating scale players from niche entrants. The upper tier commands hospital procurement relationships and pandemic stockpiling contracts through manufacturing breadth, while mid-cap specialists compete on resistance profile differentiation in HIV combination regimens. Strategic archetypes include platform-technology anchorers, respiratory-pathogen focused developers, and generic-scale nucleoside manufacturers. Competitive moves concentrate on medicinal chemistry talent acquisition and backward integration into active pharmaceutical ingredient production.
Within the platform-technology tier, Gilead Sciences and Merck exemplify divergent strategic positioning around chronic disease maintenance versus acute respiratory indications. Gilead Sciences occupies a position anchored in nucleotide prodrug chemistry, while Merck represents oral antiviral development prioritization. Pfizer sits within the scale-driven archetype, extending small-molecule manufacturing capabilities across multiple therapeutic modalities.
| Leading Market Players |
|---|
| Gilead Sciences |
| GlaxoSmithKline |
| Merck |
| F. Hoffmann-La Roche |
| AbbVie |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Pfizer |
| Novartis |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough therapy designation gates both supply qualification and price differentiation simultaneously, compressing vendor approval timelines for manufacturers while enabling premium positioning for novel mechanisms that clear accelerated pathways. Manufacturers with integrated nucleotide prodrug platforms command formulary inclusion at higher price points, while generic nucleoside suppliers compete on volume scale with thinner margins.
Pricing Analysis
Geographic price spreads separate United States Medicare-reimbursed antivirals from WHO prequalified procurement tiers by margins exceeding standard pharmaceutical differentials. Contract-based long-term offtake dominates hospital stockpiling arrangements, with price differentiation driven by resistance profile certification and manufacturing origin tier. Cost compression in off-patent HIV combination therapies is intensifying as Indian generic manufacturers expand FDA-approved facility capacity. Government procurement programs show lowest price sensitivity, while retail pharmacy channels face highest substitution pressure.
Supply Chain Analysis
Strategic stockpile preferences among hospital purchasing organizations override just-in-time efficiency for respiratory antivirals, creating inventory buffers that absorb supply shocks. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Switzerland, with nucleoside analogue chemistry drawing from specialized fermentation and synthetic capabilities. Single-source vulnerability runs through Gujarat-based bulk drug facilities serving Western formulation sites. Distribution feeds from regional hubs into group purchasing organization networks that consolidate acute care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antiviral drug markets operate as defensive-moat structures where regulatory entrenchment creates switching costs that lock hospital formularies into validated supplier relationships. FDA approval history and resistance surveillance infrastructure investments compound this structural advantage.
For Market Incumbents: Secure backward integration into nucleoside API production to defend against Indian generic substitution pressure and tariff exposure. Anchor hospital procurement relationships through pandemic stockpiling contracts that embed compliance monitoring services, raising switching costs for formulary committees considering vendor changes. For New Entrants and Emerging Players: FDA accelerated approval pathways offer certification fast-tracks into respiratory pathogen indications where no established alternatives exist. Target inhalation delivery formulations for RNA polymerase inhibitors as the most penetrable white space, entering through specialty pharmacy distribution partnerships that bypass consolidated hospital purchasing. For Investors and Strategic Acquirers: EMA-FDA regulatory convergence reshapes the acquisition landscape toward platform-technology assets with multi-jurisdiction approval potential. Five-to-ten year viability favors nucleotide prodrug chemistry specialists with integrated manufacturing footprints. Watch WHO prequalification award velocity as the signal indicating low-income market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses clinical phases and enables earlier commercial entry for novel mechanisms. |
| Backward Integration | Captive nucleoside API production insulates Western formulation facilities from single-source supply disruptions. |
| Manufacturing Scale-Up | Expanded nucleotide prodrug capacity supports once-daily regimen demand in hepatitis C and HIV management. |
| Pipeline Diversification | RNA polymerase inhibitor expansion into respiratory indications reduces reliance on chronic disease maintenance markets. |
| Hospital System Partnership | Integrated distribution capabilities align with group purchasing organization consolidation in acute care procurement. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchored market size estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by product type, therapy area, delivery mode, and end user, with regional regulatory clusters as an additional dimension. CAGRs derived from fitted growth curves incorporating epidemiological surveillance data, patent expiration schedules, and procurement contract renewal patterns.
Underlying assumptions cover stable Medicare reimbursement structures and WHO prequalification harmonization, with deviation risk concentrated in API supply disruptions and resistance mutation emergence. Revision becomes warranted when FDA approval velocity or pandemic stockpiling thresholds cross materially from baseline trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Calcium Channel Blocker Market