
 GCC Implantable Medical Devices Market | 2026-2036
GCC Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Implantable Medical Devices Market Intelligence
Saudi Arabia's SFDA medical device quality mark requirements is realigning procurement standards across GCC health systems. Medtronic leverages its cardiac rhythm management portfolio to sustain institutional contracts across Saudi and Emirati hospital networks. Boston Scientific Corporation anchors its regional position through dedicated catheterization lab partnerships in Dubai and Riyadh. Abbott Laboratories differentiates via integrated vascular and structural heart platforms that align with Gulf state cardiac center expansion plans.
Implantable medical devices encompass electromechanical and biocompatible apparatus inserted into human tissue to restore physiological function, monitor biological parameters, or deliver therapeutic agents; cardiac pacemakers typically incorporate lithium-iodine batteries with 5-15 year lifespans and titanium or biocompatible polymer housings designed for hermetic sealing against bodily fluids. Orthopedic prosthetic joints command substantial margin pools due to revision surgery volumes and premium bearing surface technologies, while bioresorbable stent platforms represent the fastest-growing technology segment as interventional cardiologists in Gulf teaching hospitals shift toward absorbable scaffold options. Active implantable devices dominate value generation through their embedded power systems and programmable diagnostic capabilities.
SFDA, the UAE Ministry of Health and Prevention, and GCC Standardization Organization harmonization frameworks collectively shape product registration timelines, clinical evidence requirements, and post-market surveillance obligations for device manufacturers seeking multi-country commercialization. The EU MDR's extraterritorial influence on Gulf regulators is elevating quality management system expectations, particularly for bioresorbable and hybrid technology categories. Stakeholders must monitor how Saudi and Emirati health procurement authorities integrate lifecycle cost analytics into implantable device tender evaluations.
Market Dynamics
Bioresorbable scaffold technology is compressing replacement cycles for coronary interventions across Gulf teaching hospitals, while SFDA and MOHAP harmonization pressures force manufacturers to consolidate multi-country registration strategies into single compliance frameworks.
Growth Catalysts
- Cardiac center expansion:Saudi Arabia's tertiary hospital construction pipeline in Riyadh and Jeddah is absorbing implantable defibrillator and pacemaker volumes as patient referrals concentrate in government-funded facilities.
- EU MDR extraterritorial influence:Gulf regulators are elevating quality management system expectations for bioresorbable and hybrid technology categories, accelerating manufacturer readiness investments.
- Lithium-iodine battery longevity:Extended 10-15 year power cell lifespans in cardiac rhythm devices are reducing revision surgery burdens and expanding eligible patient pools across aging Gulf populations.
Market Restraints
- Titanium supply concentration:Hermetic housing fabrication depends on specialty metal suppliers concentrated in East Asian refining corridors, exposing manufacturers to input cost volatility and logistics friction.
- Clinical evidence requirements:SFDA's updated registration pathways demand extended local safety datasets, lengthening time-to-revenue for novel bioresorbable platforms.
- Bearing surface technology cost:Premium orthopedic prosthetic joints require ceramic-on-ceramic or cross-linked polyethylene components that inflate procedure costs beyond standard reimbursement bands in Emirati and Saudi health systems.
Strategic Opportunities
- Catheterization lab partnerships:Dedicated device-physician collaboration models in Dubai and Riyadh cardiac centers are creating captive procedure volumes for integrated vascular platform suppliers.
- Absorbable scaffold adoption:Interventional cardiologists in Kuwait and Qatar teaching hospitals represent underpenetrated demand for bioresorbable stent platforms as training programs expand.
- GCC Standardization Organization harmonization:Unified technical regulations across member states are enabling single-registration-to-multiple-market access strategies that compress commercialization overhead.
Industry Challenges
- Electrophysiology specialist scarcity:Complex cardiac rhythm device implantation and programming require fellowship-trained physicians, creating bottlenecks as procedure volumes outpace Gulf medical education pipeline output.
- Post-market surveillance infrastructure:Longitudinal device registries and adverse event reporting systems remain fragmented across Saudi, Emirati, and other national health authorities, complicating real-world evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Implantable Medical Devices Market |
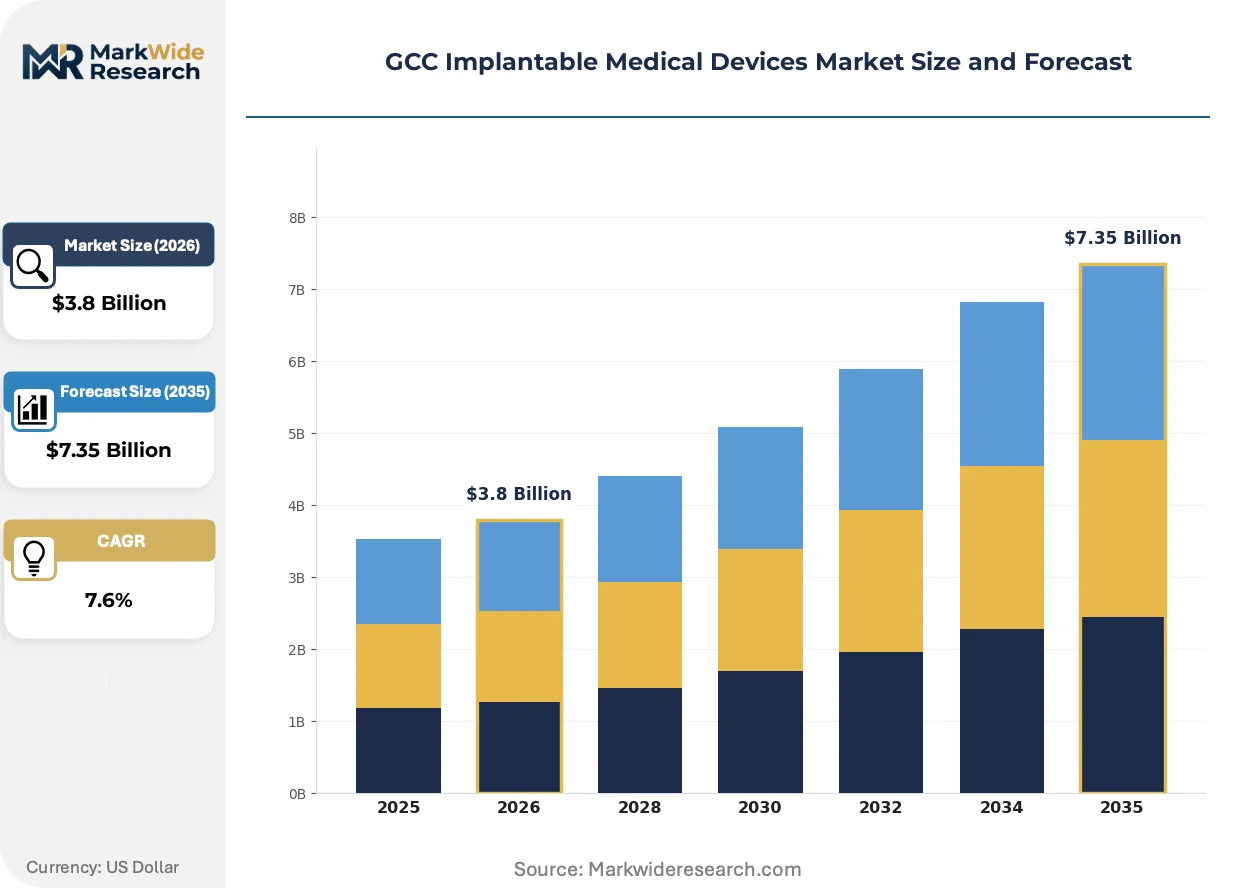
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Stents, Prosthetic Joints, Implantable Defibrillators Technology: Active, Passive, Bioresorbable, Hybrid End User: Hospitals, Clinics, Long-term Care Facilities, Home Care Application: Cardiology, Orthopedics, Neurology, Dentistry |
| Companies Covered | Boston Scientific Corporation, Smith & Nephew plc, Medtronic, Integra LifeSciences Holdings Corporation, Cochlear Limited, Johnson & Johnson, Stryker Corporation, Biotronik SE & Co. KG, Abbott Laboratories, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Implantable Medical Devices Market Strategic Shifts & Innovations
Programmable diagnostic capabilities embedded in active implantable devices are enabling remote patient monitoring ecosystems that reshape how Gulf health systems manage chronic cardiac conditions and post-surgical recovery.
Bioresorbable stent platforms incorporate poly-lactic acid polymers that dissolve within 24-36 months after vessel remodeling, eliminating permanent metal foreign body retention. Interventional cardiologists at Saudi Arabia's King Faisal Specialist Hospital and Dubai's Rashid Hospital are expanding into absorbable scaffold procedures for younger patients with single-vessel disease. This technology is expanding into premium procedure segments previously dominated by durable metal drug-eluting stents, compressing long-term antiplatelet therapy burdens and revision risk profiles.
SFDA's medical device quality mark requirements now mandate ISO 13485-certified quality management systems for all imported active implantables, aligning Gulf standards with EU MDR technical documentation expectations. Manufacturers face compressed registration timelines as the authority implements risk-based classification pathways that expedite review for established cardiac rhythm and vascular technologies. Cardiac pacemaker and implantable cardioverter-defibrillator categories bear the heaviest compliance load as post-market surveillance obligations expand to include mandatory annual safety reports and implant registry participation.
Government health procurement authorities in Riyadh and Abu Dhabi are consolidating implantable device purchasing through centralized tender frameworks that emphasize lifecycle cost analytics over upfront device pricing. Hospital networks are displacing fragmented specialty distributor relationships with direct manufacturer contracting for high-volume cardiac and orthopedic implant categories. Saudi Arabia's National Unified Procurement Company and the UAE's Ministry of Health and Prevention supply chains exhibit the most advanced tender sophistication, requiring suppliers to submit total cost-of-ownership models spanning implantation through revision surgery probability.
GCC Implantable Medical Devices Market Segmentation
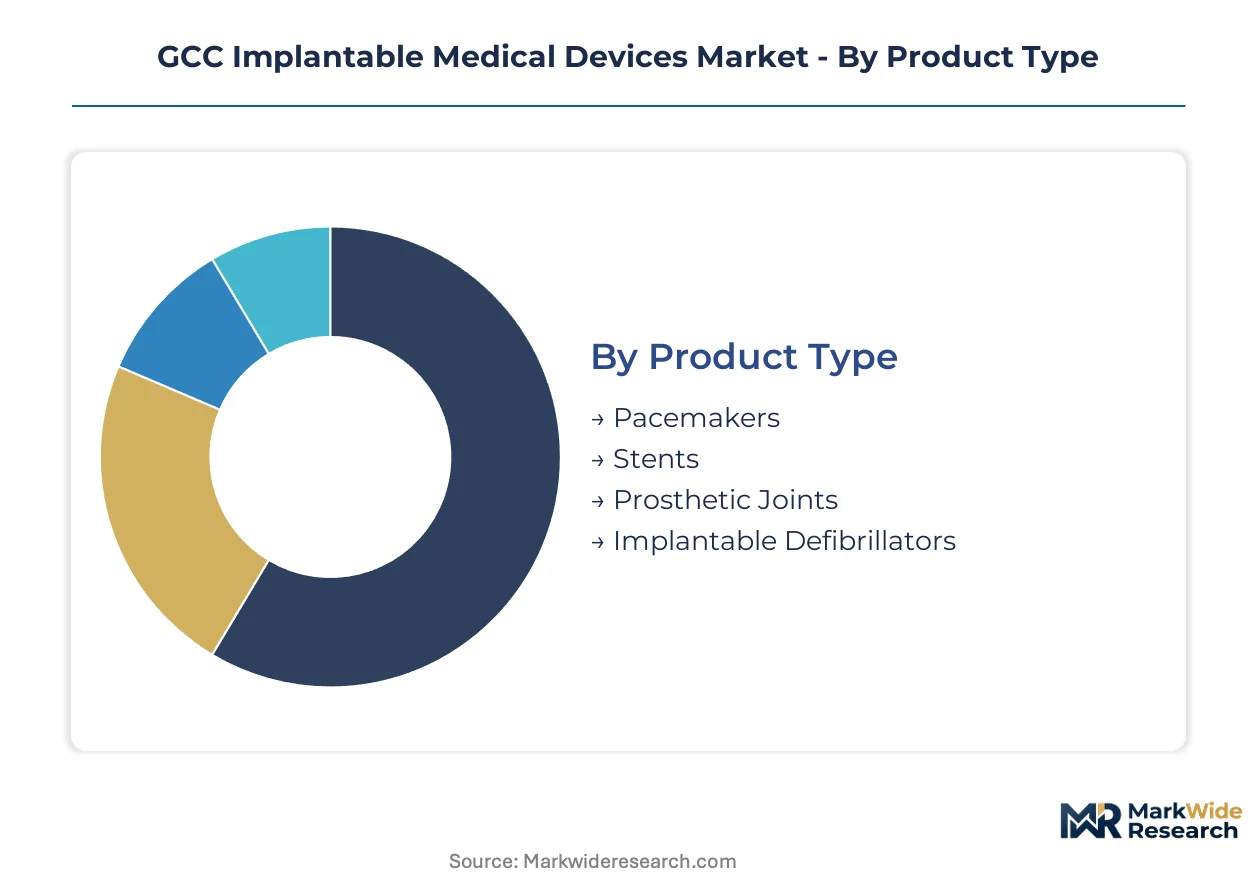
Implantable device procurement across Saudi Arabia and the UAE fragments across four distinct classification axes, each imposing divergent regulatory burdens and tender evaluation criteria. Manufacturers must map SFDA quality mark requirements against specific product-technology combinations to compress multi-country registration timelines.
Product Type:
SFDA's risk-based classification pathways impose ISO 13485 certification mandates most heavily on active implantable categories, while passive devices navigate streamlined technical documentation requirements.
- Implantable Defibrillators:These active devices incorporate lithium-iodine power cells delivering 10-15 year lifespans within hermetic titanium housings. Demand concentrates in Riyadh's King Faisal Specialist Hospital and Jeddah's tertiary cardiac centers as government-funded infrastructure expansion absorbs high-complexity electrophysiology procedures.
- Pacemakers:Cardiac rhythm management devices feature programmable diagnostic capabilities enabling remote patient monitoring ecosystems. Procurement volumes align with Saudi Arabia's National Unified Procurement Company tender frameworks that emphasize lifecycle cost analytics over upfront device acquisition costs.
- Stents:Coronary scaffold platforms span durable metal drug-eluting and bioresorbable polymer variants. SFDA registration pathways demand extended local safety datasets for novel absorbable platforms.
- Prosthetic Joints:Orthopedic implants command premium margins through ceramic-on-ceramic and cross-linked polyethylene bearing surfaces. Revision surgery probability models factor into Abu Dhabi health procurement authority tender evaluations.
Leading the category by volume: Pacemakers. Growing fastest: Implantable Defibrillators.
Technology:
Power source integration and material dissolution profiles determine margin structures and regulatory scrutiny intensity across Gulf health systems.
- Bioresorbable:Poly-lactic acid scaffolds dissolve within 24-36 months post-implantation, eliminating permanent foreign body retention. Interventional cardiologists at Dubai's Rashid Hospital and Kuwait's teaching hospitals are expanding absorbable procedure volumes for younger single-vessel patients.
- Active:Embedded battery systems and programmable diagnostic capabilities dominate value generation through remote monitoring compatibility. EU MDR extraterritorial influence elevates quality management system expectations for this technology class.
- Hybrid:Combinations of active power systems with bioresorbable structural elements face compressed registration timelines as novel platform categories.
- Passive:Non-powered implants including standard orthopedic hardware encounter reduced post-market surveillance obligations under GCC Standardization Organization harmonization frameworks.
Bioresorbable platforms command premium pricing tiers. Active technology generates the largest revenue pool.
End User:
Procurement centralization intensity varies sharply across facility types, with government hospital networks displacing fragmented distributor relationships.
- Hospitals:Tertiary cardiac centers and orthopedic departments in Riyadh-Jeddah corridor facilities absorb the highest implantable device volumes through direct manufacturer contracting.
- Clinics:Outpatient settings concentrate on diagnostic and follow-up services rather than complex implantation procedures.
- Long-term Care Facilities:Post-acute settings manage chronic cardiac condition monitoring through remote patient data transmission.
- Home Care:Emerging delivery channel for remote monitoring-enabled devices as programmable diagnostic capabilities reshape chronic disease management.
Hospitals capture the dominant procurement share. Home Care is expanding most quickly.
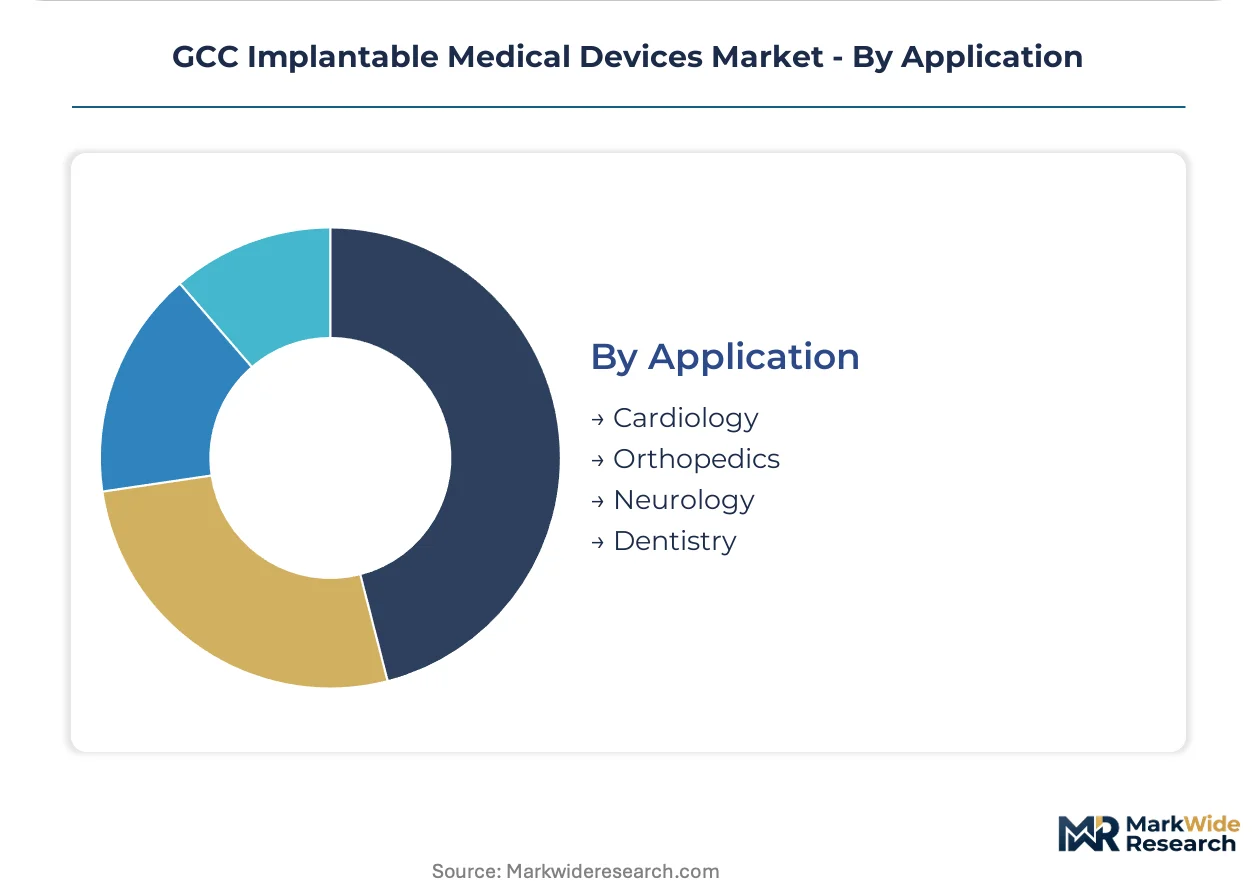
Application:
Specialist physician availability and training program output constrain procedure volume expansion across clinical domains.
- Cardiology:Catheterization lab partnerships in Dubai and Riyadh create captive procedure volumes for integrated vascular platform suppliers. Electrophysiology specialist scarcity creates implantation bottlenecks as volumes outpace Gulf medical education pipeline output.
- Orthopedics:Revision surgery volumes and premium bearing surface technologies sustain margin pools for prosthetic joint manufacturers.
- Neurology:Deep brain stimulation and neurostimulator categories face extended SFDA clinical evidence requirements.
- Dentistry:Dental implants encounter distinct reimbursement band structures separate from cardiac and orthopedic procurement frameworks.
Cardiology leads by procedure value. Orthopedics follows by implant unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GCC implantable medical device consumption concentrates in Saudi Arabia and the UAE while manufacturing inputs flow from East Asian refining corridors. Domestic production remains negligible across all six member states. Regulatory harmonization through the GCC Standardization Organization is compressing multi-country commercialization timelines.
Saudi Arabia
King Faisal Specialist Hospital and Jeddah's tertiary cardiac centers absorb the highest pacemaker and defibrillator volumes as government-funded infrastructure expansion accelerates. SFDA's updated medical device quality mark requirements now mandate ISO 13485 certification for all imported active implantables. The Riyadh-Jeddah corridor dominates procurement concentration through the National Unified Procurement Company's centralized tender frameworks.
United Arab Emirates
Dubai's Rashid Hospital and Abu Dhabi cardiac centers drive bioresorbable stent adoption for younger single-vessel patients as interventional cardiology training expands. MOHAP supply chains exhibit advanced tender sophistication requiring total cost-of-ownership models spanning implantation through revision probability. The Dubai-Abu Dhabi axis anchors catheterization lab partnerships that create captive procedure volumes for integrated vascular platform suppliers.
Kuwait
Teaching hospitals in Kuwait City represent underpenetrated demand for bioresorbable scaffold platforms as fellowship programs expand interventional cardiology capacity. The national pharmaceutical regulator maintains alignment with GCC Standardization Organization technical regulations for streamlined device registration. Government health procurement authorities are consolidating purchasing through centralized frameworks that emphasize lifecycle cost analytics over upfront device pricing.
Qatar
Hamad Medical Corporation's cardiac center expansion is absorbing implantable defibrillator volumes as patient referrals concentrate in government-funded facilities. The national health authority integrates EU MDR-influenced quality management system expectations into post-market surveillance obligations. Doha's medical city cluster is emerging as a regional hub for complex electrophysiology procedures requiring fellowship-trained physician availability.
Oman and Bahrain
Smaller Gulf markets rely on distributor networks for orthopedic prosthetic joint and cardiac rhythm device procurement as direct manufacturer contracting remains limited. National health authorities participate in GCC Standardization Organization harmonization frameworks to reduce regulatory friction. Muscat and Manama medical centers concentrate specialist procedure volumes while sourcing through Saudi and Emirati procurement channels.
GCC Implantable Medical Devices Market Key Industry Players
The competitive structure tilts toward integrated multinational medical technology conglomerates with dedicated cardiac rhythm management portfolios. Three to five global manufacturers capture dominant procurement shares across Saudi and Emirati hospital networks through institutional contracting relationships. Strategic archetypes include full-stack cardiac platform suppliers, orthopedic revision surgery specialists, and hearing implant focused manufacturers. Competitive moves concentrate on catheterization lab partnerships and direct government tender participation displacing fragmented distributor relationships.
Among US-based medical technology conglomerates, Boston Scientific Corporation, Medtronic, and Abbott Laboratories exemplify the integrated cardiac platform archetype through their institutional presence across Riyadh and Dubai cardiac centers. Smith & Nephew plc and Stryker Corporation represent orthopedic-focused competitors capturing premium prosthetic joint margins through revision surgery probability models. Johnson & Johnson occupies a diversified position spanning both cardiovascular and orthopedic segments. Biotronik SE & Co. KG anchors the European specialist tier in cardiac rhythm management. Cochlear Limited exemplifies the single-disease focused manufacturer archetype in hearing implants.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Smith & Nephew plc |
| Medtronic |
| Integra LifeSciences Holdings Corporation |
| Cochlear Limited |
| Johnson & Johnson |
| Stryker Corporation |
| Biotronik SE & Co. KG |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
EU MDR-aligned quality management system mandates gate qualified supply access and premium-tier pricing eligibility across GCC implantable device procurement channels. SFDA's ISO 13485 certification requirements for active implantables compress the supplier base while elevating compliance costs that transmit into tiered pricing structures.
Pricing Analysis
Value-based pricing anchored to total cost-of-ownership models dominates government tender evaluations across Saudi and Emirati hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates bioresorbable scaffold platforms from conventional drug-eluting stents and basic bare-metal alternatives. Price differentiation stems from certification tier and after-sales remote monitoring service bundling. Cost compression in standard-tier cardiac rhythm devices is intensifying because centralized procurement authorities weight lifecycle analytics over upfront acquisition. Government hospital networks exhibit lowest price sensitivity; private clinic distributors face highest margin pressure.
Supply Chain Analysis
Titanium hermetic housing fabrication rests on East Asian specialty metal refining corridors concentrated in Japan, South Korea, and China. Lithium-iodine battery cell production draws from Japanese and South Korean electrochemical suppliers, while poly-lactic acid bioresorbable polymers source from European and North American specialty chemical manufacturers. Single-source vulnerability pervades titanium sponge processing capacity concentrated in limited East Asian facilities. Distribution runs through Saudi Arabia's National Unified Procurement Company and UAE Ministry of Health and Prevention supply chains, displacing fragmented specialty distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC implantable medical devices represent a consolidation play as SFDA-MOHAP harmonization pressures force sub-scale manufacturers to exit multi-country registration races.
For Market Incumbents: Hedge titanium supply exposure through dual-source qualification of Japanese and South Korean refining capacity. Secure catheterization lab partnerships in Riyadh and Dubai cardiac centers to lock procedure volumes against emerging integrated vascular platform competitors. Backward integration into lithium-iodine battery cell assembly mitigates power source cost volatility. For New Entrants and Emerging Players: Begin with bioresorbable scaffold distribution partnerships in Kuwait and Qatar teaching hospitals, the most penetrable geography for absorbable platform adoption. Target interventional cardiology fellowship programs expanding absorbable procedure training as the entry wedge. Pursue direct contracting with Hamad Medical Corporation and Kuwait's centralized procurement authority rather than distributor intermediation. For Investors and Strategic Acquirers: SFDA quality mark pathway acceleration for established cardiac rhythm technologies is the leading indicator that regulatory consolidation will favor scaled compliance infrastructure. Long-term viability across the projection horizon requires captive GCC registration capabilities and ISO 13485-certified quality management systems. Acquisition target archetype: mid-cap cardiac rhythm management specialists with existing SFDA registrations and Dubai-Riyadh hospital network relationships. Watch for GCC Standardization Organization technical regulation finalization as the inflection signal enabling single-registration-to-multiple-market access.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Quality Mark Acceleration | Expedited review pathways compress time-to-revenue for established cardiac rhythm manufacturers with compliant documentation. |
| Catheterization Lab Partnership | Dedicated device-physician collaboration models in Dubai and Riyadh cardiac centers create captive procedure volumes. |
| Bioresorbable Scaffold Training Program | Fellowship expansion in Kuwait and Qatar teaching hospitals builds absorbable platform procedure capacity for younger patients. |
| Dual-Source Titanium Qualification | East Asian refining corridor diversification mitigates hermetic housing input cost volatility and logistics friction. |
| Remote Monitoring Platform Integration | Programmable diagnostic capabilities in active implantables enable chronic cardiac condition management ecosystems across Gulf health systems. |
Research Approach
Multi-period observation of SFDA registration pathway timelines, MOHAP tender award patterns, and cardiac center construction pipelines anchored the trend analysis, supplemented by interviews with hospital procurement committee directors, biomedical engineers, interventional cardiologists, and GCC Standardization Organization technical committee members. Secondary validation drew from SFDA medical device quality mark databases, UAE Ministry of Health and Prevention supply chain disclosures, hospital procurement registries, and EU MDR technical documentation guidance. Bottom-up implant volume modeling and top-down health expenditure allocation triangulation produced convergent market sizing.
Input-output matrices mapped lithium-iodine battery longevity assumptions, bioresorbable scaffold dissolution profiles, and revision surgery probability curves against patient demographic projections across the analysis window. Segmentation dimensions spanned product type, technology class, end-user facility tier, and application specialty. CAGRs derived from procedure volume elasticities to cardiac center capacity expansion and pricing trajectories tied to centralized tender sophistication evolution. Forecast inputs incorporated electrophysiology specialist training pipeline output and GCC harmonization framework implementation schedules.
Underlying measurement precision varies by segment; active implantable device categories carry tighter precision than passive orthopedic hardware due to concentrated manufacturer reporting. Forecasts reflect documented assumptions regarding SFDA review timeline compression and EU MDR extraterritorial influence persistence. Regulatory pathway disruption, titanium supply shock, or electrophysiology specialist training bottlenecks could revise projections. A small set of triggers—GCC Standardization Organization technical regulation finalization, Saudi National Unified Procurement Company tender framework revision, and bioresorbable scaffold long-term safety data publication—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Lenses Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Capsule Endoscope Systems Market