
 Injectable Cytotoxic Drugs Market | 2026-2036
Injectable Cytotoxic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Cytotoxic Drugs Market Analysis
Patient-monitoring subscription services bundled with injectable cytotoxic regimens is broadening what manufacturers capture beyond the vial. Bristol-Myers Squibb leverages its immuno-oncology portfolio to anchor bundled care contracts with major hospital systems. Fresenius Kabi AG competes through vertical integration into parenteral manufacturing capacity and cold-chain logistics. Eli Lilly and Company differentiates via precision dosing algorithms tied to biomarker testing platforms.
Injectable cytotoxic drugs comprise sterile, biologically active formulations—alkylating agents, antimetabolites, plant alkaloids, and cytotoxic antibiotics—engineered for parenteral administration to achieve rapid systemic bioavailability in cancer treatment. These formulations require aseptic compounding, often under negative-pressure isolators, with strict endotoxin limits and stability profiles measured in hours to days. Monoclonal antibodies command premium positioning due to complex bioprocessing and patent-protected targets, while small molecule inhibitors represent the fastest-expanding pipeline as oral bioavailability challenges push intravenous formulations for recalcitrant indications. Intravenous delivery still dominates hospital throughput, though subcutaneous formulations are gaining share in outpatient cancer treatment centers where chair time directly constrains capacity.
FDA oversight through current Good Manufacturing Practice (cGMP) and the Drug Supply Chain Security Act (DSCSA) shapes batch-release protocols and track-and-trace mandates that raise compliance costs for sterile injectables. EMA's Annex 1 revision on sterile medicinal products and the EU's Falsified Medicines Directive impose parallel serialization and environmental monitoring requirements that filter market access for non-compliant suppliers. Stakeholders must monitor how biosimilar entry into cytotoxic monoclonal antibodies reshapes contracting dynamics and whether subcutaneous formulation investments alter site-of-care economics before committing capacity expansion decisions.
Market Dynamics
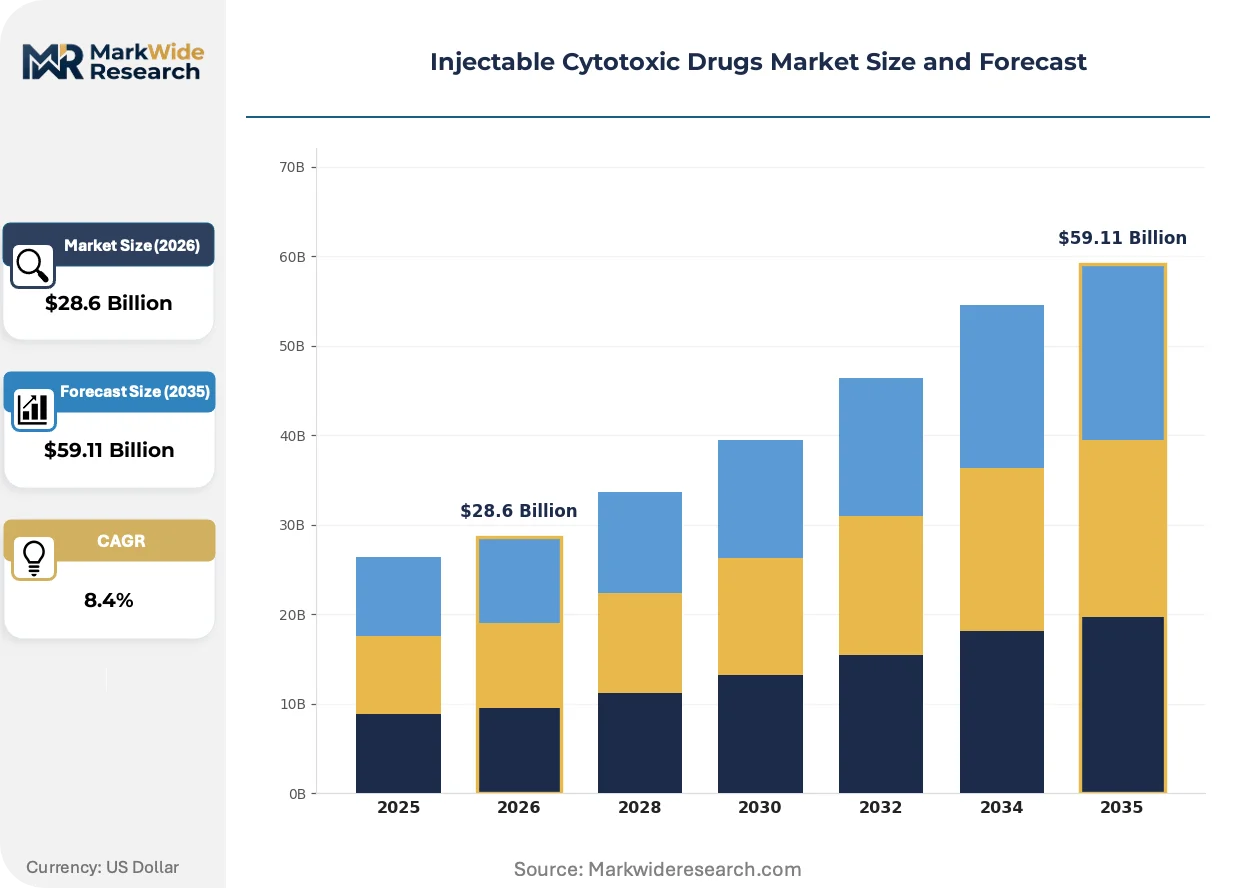
FDA's accelerated approval pathways compress development timelines for breakthrough oncology therapies, while biosimilar entry into monoclonal antibody categories reshapes hospital contracting dynamics and site-of-care economics.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review framework compresses Phase II-to-approval timelines for cytotoxic agents addressing unmet oncology needs, pulling forward revenue recognition for developers.
- Subcutaneous formulation migration:Outpatient cancer centers in the United States adopt subcutaneous delivery to reduce chair-time constraints and expand patient throughput capacity.
- Biomarker-driven patient stratification:Companion diagnostic integration with cytotoxic regimens expands addressable populations for precision-dosed therapies in solid tumor protocols.
Market Restraints
- Platinum-group metal input volatility:Cisplatin and carboplatin synthesis depends on platinum supply concentrated in South African and Russian mining operations, creating cost unpredictability.
- Cold-chain infrastructure scarcity:Temperature-controlled distribution capacity constraints in secondary US markets limit biologic cytotoxic reach beyond major metropolitan oncology hubs.
- EMA Annex 1 compliance costs:Revised sterile manufacturing requirements for isolator technology and continuous environmental monitoring raise capital thresholds for European market entry.
Strategic Opportunities
- Home infusion channel expansion:Specialty pharmacy networks in the United States build ambulatory capacity for cytotoxic administration outside hospital walls, capturing site-of-care shift economics.
- AI-assisted dosing algorithms:Machine learning platforms integrated with pharmacokinetic monitoring converge with electronic health record systems to enable real-time dose personalization.
- IRA Medicare price negotiation:Selected small molecule cytotoxics face CMS pricing authority, creating strategic positioning windows for agents exempt from initial selection rounds.
Industry Challenges
- Aseptic compounding workforce shortage:USP Chapter 797 compliance demands for sterile handling certification outpace training program output, constraining hospital pharmacy capacity.
- Biosimilar switching friction:Oncology formulary committees navigate therapeutic equivalence debates for cytotoxic monoclonal antibodies, delaying adoption decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Cytotoxic Drugs Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Monoclonal Antibodies, Small Molecule Inhibitors, Hormonal Therapies Therapy Area: Oncology, Hematology, Autoimmune Disorders, Infectious Diseases Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intratumoral End User: Hospitals, Cancer Treatment Centers, Clinics, Research Institutions |
| Companies Covered | Bristol-Myers Squibb, Eli Lilly and Company, Pfizer Inc., Fresenius Kabi AG, Merck KGaA, F. Hoffmann-La Roche Ltd., Novartis AG, Sun Pharmaceutical Industries Ltd., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Cytotoxic Drugs Market Emerging Trajectories
Injectable cytotoxic development is pivoting toward formulation technologies that compress administration duration and enable care migration from infusion centers to lower-acuity settings.
Closed-system transfer devices (CSTDs) for hazardous drug compounding is converging with robotic aseptic filling platforms to eliminate human exposure risk while accelerating batch throughput. Hospital systems with high cytotoxic volume deploy these integrated systems to satisfy USP 800 requirements without expanding physical cleanroom footprint. The structural consequence is compression of per-dose labor cost and reduction of occupational health liability exposure.
EMA's Annex 1 revision on sterile medicinal products mandates continuous viable particle monitoring and barrier isolator technology for all cytotoxic manufacturing. European contract manufacturers retrofit legacy filling lines or exit the cytotoxic category entirely, consolidating production among compliant facilities. High-complexity biologics and antibody-drug conjugates face the steepest compliance cost escalation, favoring sponsors with captive manufacturing assets.
Hospital procurement committees unbundle drug acquisition from infusion service fees, pressuring manufacturers to justify premium positioning through outcome guarantees rather than clinical data alone. Integrated cancer centers in the United States negotiate risk-sharing arrangements where cytotoxic reimbursement ties to pathway adherence metrics. This behavioral shift is most visible in Medicare Advantage–dominated markets where total cost of care accountability concentrates with provider systems.
Injectable Cytotoxic Drugs Market Segmentation
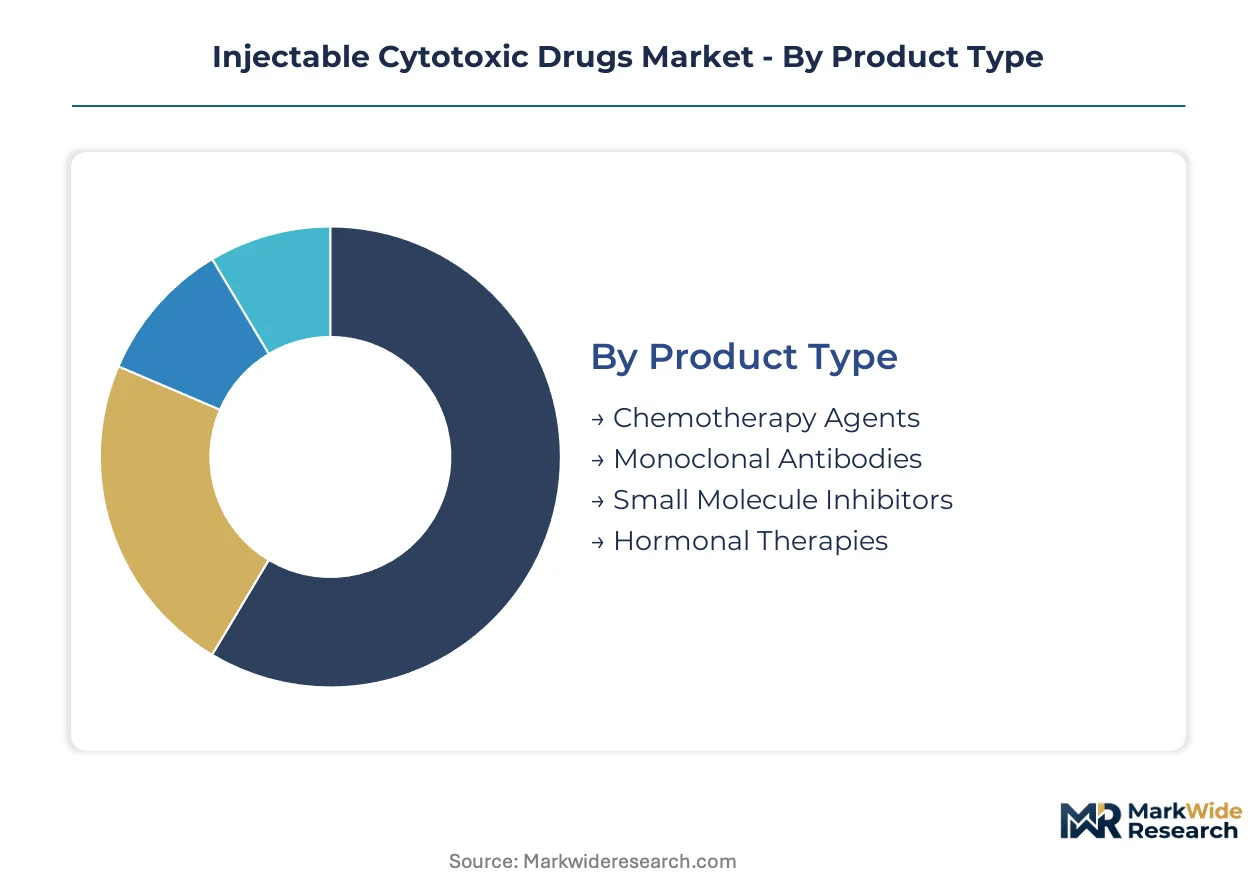
Injectable cytotoxic drugs fragment across multiple decision axes that determine procurement priority, site-of-care economics, and reimbursement pathway. Buyers weight formulation complexity against administration logistics, while therapy area specialization dictates regulatory and clinical support requirements.
Product Type:
Hospital formulary committees segment procurement by manufacturing complexity and patent protection status, with biologics commanding distinct contracting terms from small molecules.
- Chemotherapy Agents:Alkylating agents, antimetabolites, plant alkaloids, and cytotoxic antibiotics constitute the historical backbone of parenteral oncology protocols. Demand concentrates in academic medical centers with high solid-tumor throughput, constrained by platinum-group metal supply volatility affecting platinum-based regimens.
- Monoclonal Antibodies:Complex bioprocessing requirements and patent-protected targets position these at premium price tiers with extended infusion durations. United States specialty pharmacy networks drive volume for these agents as biosimilar entry reshapes hospital contracting dynamics.
- Small Molecule Inhibitors:Intravenous formulations address recalcitrant indications where oral bioavailability fails, with precision dosing algorithms tied to biomarker testing platforms.
- Hormonal Therapies:Parenteral depot formulations for prostate and breast cancer protocols, administered in outpatient settings with extended dosing intervals.
Monoclonal antibodies lead on scale; small molecule inhibitors lead on momentum.
Therapy Area:
Reimbursement pathway design and companion diagnostic requirements vary sharply across therapeutic domains, shaping manufacturer investment priority.
- Oncology:Solid tumor and hematologic malignancy protocols dominate injectable cytotoxic utilization, with FDA accelerated approval pathways compressing development timelines for breakthrough therapies.
- Hematology:Leukemia, lymphoma, and myeloma regimens require specialized compounding protocols and extended monitoring infrastructure.
- Autoimmune Disorders:Off-label cytotoxic use in severe rheumatoid arthritis and lupus nephritis concentrates in tertiary referral centers with infusion capacity.
- Infectious Diseases:Limited parenteral cytotoxic applications in severe parasitic infections, primarily in research settings.
Oncology commands absolute volume; hematology maintains the steepest expansion trajectory.
Delivery Mode:
Site-of-care migration economics and chair-time constraints determine formulation preference, with subcutaneous options gaining share in capacity-constrained outpatient settings.
- Intravenous:Remains dominant for hospital throughput, enabling rapid systemic bioavailability and dose titration flexibility in acute oncology protocols.
- Subcutaneous:Outpatient cancer centers in the United States adopt these formulations to reduce chair-time constraints and expand patient throughput capacity.
- Intramuscular:Limited applications for hormonal depot formulations and select cytotoxic antibiotics with sustained-release profiles.
- Intratumoral:Experimental localized delivery for accessible lesions, requiring interventional radiology or surgical oncology coordination.
Intravenous delivery retains installed base dominance; subcutaneous formulations gain share fastest.
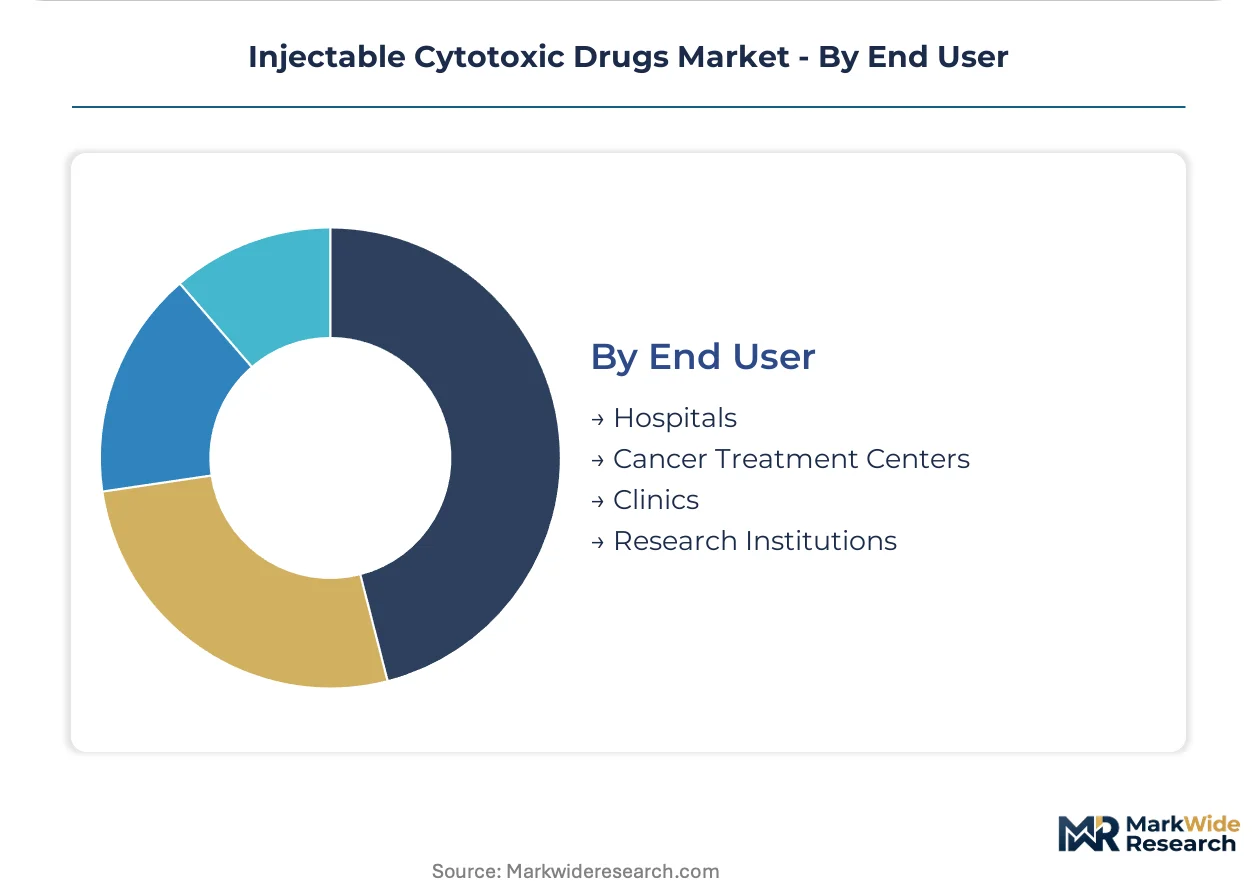
End User:
Procurement scale and risk-sharing capability separate institutional buyers, with integrated delivery networks extracting distinct terms from standalone facilities.
- Hospitals:Academic medical centers and community hospital systems with captive oncology service lines, negotiating bundled care contracts with outcome guarantees.
- Cancer Treatment Centers:Dedicated outpatient infusion facilities where chair-time economics and USP 800 compliance costs determine formulary preference.
- Clinics:Smaller physician practices with limited compounding capacity, dependent on external specialty pharmacy networks for cytotoxic supply.
- Research Institutions:Early-phase clinical trial sites with investigational new drug handling requirements and protocol-specific formulation needs.
Hospitals anchor procurement volume; cancer treatment centers drive site-of-care shift economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty pharmacy networks command higher cytotoxic volumes than German hospital procurement systems, while Japanese regulators impose stricter manufacturing standards than their North American counterparts.
United States
Integrated cancer centers in Texas and Florida expand subcutaneous formulation capacity to reduce infusion chair-time constraints. FDA accelerated approval pathways compress Phase II-to-approval timelines for breakthrough oncology therapies. The Memorial Sloan Kettering network in New York anchors precision dosing algorithm development for solid tumor protocols.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive demand for complex biologic cytotoxics requiring specialized compounding infrastructure. EMA Annex 1 revisions mandate continuous viable particle monitoring and barrier isolator technology for sterile manufacturing. The Rhine-Main cluster around Frankfurt consolidates contract manufacturing capacity as smaller facilities exit the cytotoxic category.
Japan
PMDA oversight of antibody-drug conjugates creates extended review timelines that favor sponsors with established local pharmacovigilance infrastructure. The country's national pharmaceutical regulator requires Japanese clinical trial data for novel cytotoxic indications regardless of prior FDA or EMA approval. Osaka-based hospital systems pioneer home infusion channel expansion for select hematology regimens.
India
CDSCO fast-track pathways for oncology biosimilars attract contract manufacturing investment from multinational sponsors seeking cost-competitive parenteral production. The country's national pharmaceutical regulator harmonizes with ICH guidelines for sterile injectable export certification. Hyderabad and Ahmedabad clusters specialize in cytotoxic API synthesis and aseptic filling for European and North American markets.
Switzerland
Swissmedic's proximity to EMA headquarters enables parallel submission strategies that accelerate European market entry for novel cytotoxic agents. The regulator maintains distinct pharmacovigilance requirements that influence global safety database architecture for multinational sponsors. Basel anchors captive manufacturing assets for high-complexity biologics and antibody-drug conjugates.
Injectable Cytotoxic Drugs Market Vendor Landscape
Top-tier vendors anchor premium biologic positioning, while mid-scale manufacturers compete on parenteral capacity and cold-chain reliability. The vendor base stratifies across three archetypes: immuno-oncology portfolio integrators, vertical manufacturing specialists, and precision-dosing platform developers. Consolidation pressures intensify as biosimilar entry reshapes hospital contracting dynamics and site-of-care economics force portfolio diversification moves.
Within the integrated pharmaceutical tier, Bristol-Myers Squibb and Eli Lilly and Company occupy positions that exemplify divergent strategic anchors—portfolio bundling versus algorithmic dosing differentiation. Fresenius Kabi AG represents the manufacturing-centric archetype with captive parenteral capacity. These three entities collectively illustrate how competitive positioning in cytotoxic markets depends on controlling distinct value chain nodes rather than uniform scale advantages.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Merck KGaA |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Others |
Supply Flow & Price Mechanics
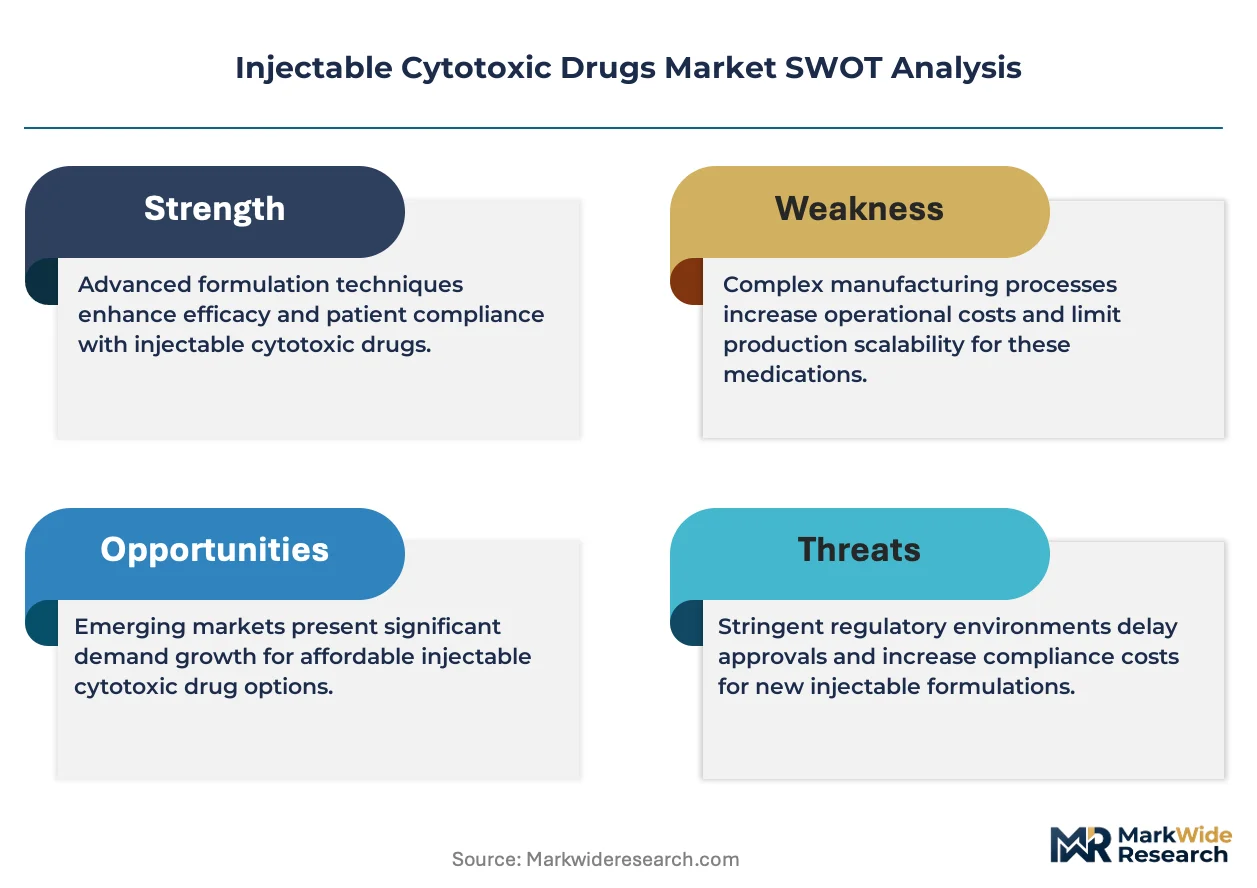
EMA Annex 1 sterile manufacturing mandates gate qualified supply for European market access and anchor premium-tier pricing for antibody-drug conjugates and high-complexity biologics. Compliance capital thresholds filter marginal producers from contract manufacturing, concentrating volume among facilities with isolator technology and continuous environmental monitoring systems.
Pricing Analysis
Capacity additions in India are reshaping price floors for generic chemotherapy agents while biologic monoclonals maintain premium positioning through patent-protected targets and complex bioprocessing requirements. Three-tier pricing structure across premium, standard, and economy levels separates originator biologics from biosimilar entrants and commodity alkylating agents. Cost compression in platinum-based regimens is intensifying because of South African and Russian mining supply volatility. Community hospital systems exhibit highest price sensitivity; integrated cancer centers with risk-sharing contracts demonstrate lowest.
Supply Chain Analysis
Cold-chain freight costs for temperature-controlled biologics constrain distribution reach beyond major metropolitan oncology hubs into secondary US markets. API synthesis concentrates in India and China; aseptic filling capacity clusters in Germany, Switzerland, and the United States. Platinum-group metals for cisplatin and carboplatin draw from concentrated mining operations, creating single-source vulnerability. Distribution runs through specialty pharmacy networks with last-mile infusion center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable cytotoxic drugs function as a stable compounder anchored by oncology protocol expansion and FDA accelerated approval pathways that compress development timelines for breakthrough therapies.
For Market Incumbents: Acquire captive aseptic manufacturing capacity to secure supply continuity against EMA Annex 1 compliance exits and biosimilar entry pressure. Consolidate contract manufacturing relationships with facilities holding barrier isolator certifications. Deepen backward integration into parenteral formulation technology to defend margin position against Indian and Chinese API cost advantages. For New Entrants and Emerging Players: Begin with subcutaneous formulation development for outpatient cancer centers facing chair-time capacity constraints in Texas and Florida markets. Target home infusion channel partnerships with Medicare Advantage–dominated provider systems. Lead with precision dosing algorithm integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale contract manufacturers with EMA Annex 1 compliance and cold-chain certification because European production consolidation is eliminating non-compliant legacy facilities. Five-to-ten year viability hinges on antibody-drug conjugate capacity expansion. Monitor biosimilar switching velocity in US hospital formularies as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for developers. |
| Manufacturing Scale-Up | Isolator technology deployment satisfies USP 800 and EMA Annex 1 compliance requirements. |
| Backward Integration | Captive parenteral capacity reduces dependency on contract manufacturers facing compliance exits. |
| Platform Integration | AI-assisted dosing algorithms converge with EHR systems for real-time personalization. |
| Geographic Expansion | Home infusion channel buildout captures site-of-care shift economics in Medicare Advantage markets. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with oncology pharmacy directors, formulary committee chairs, regulatory affairs leads, and specialty pharmacy network executives combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of treatment protocol adoption rates and biosimilar penetration patterns informs the projection framework across the analysis window. Segmentation dimensions include product type, therapy area, delivery mode, and end-user facility scale. CAGRs derive from fitted growth curves applied to patient population projections and dosing frequency assumptions. Forecast inputs incorporate platinum-group metal supply volatility and cold-chain infrastructure expansion timelines.
Several conditions sit outside the modeled scope, including pandemic-related manufacturing disruptions, abrupt regulatory framework revisions, and therapeutic class substitution from oral small molecule breakthroughs. Forecasts reflect documented assumptions about approval pathway velocity and site-of-care migration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Acetylspiramycin Market