
 Pharma Management Software Market | 2026-2036
Pharma Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Management Software Market Analysis
Subscription-based financing and asset-light SaaS procurement is tilting competitive dynamics toward vendors with scalable cloud architectures. Oracle leverages its enterprise database dominance to anchor integrated pharma suites across large manufacturers. Veeva Systems specializes in cloud-native life sciences applications, sustaining premium positioning through vertical depth. IQVIA competes by combining software with real-world data services, extending its footprint beyond pure technology licensing.
Pharma management software encompasses integrated digital platforms that orchestrate drug development, regulatory submission, supply chain tracking, and quality assurance workflows through validated electronic systems. These platforms incorporate audit trails, electronic signatures, and role-based access controls to satisfy stringent data integrity requirements across GxP environments. Clinical Trial Management systems lead current revenue pools as decentralized trial complexity demands real-time patient monitoring and site coordination. Cloud-Based deployment represents the fastest-expanding segment, with hybrid architectures gaining traction among mid-tier firms balancing legacy infrastructure with elastic compute needs.
FDA 21 CFR Part 11, EMA GMP Annex 11, and EU GDPR collectively shape product roadmaps by mandating electronic record integrity, data privacy safeguards, and cross-border transfer protocols. EMA's Clinical Trial Information System and FDA's evolving guidance on computer software assurance are tightening validation burdens while creating replacement demand for non-compliant legacy installations. Stakeholders must weigh the trade-off between single-vendor consolidation and best-of-breed specialization as regulatory scope broadens from manufacturing quality into pharmacovigilance and real-world evidence collection.
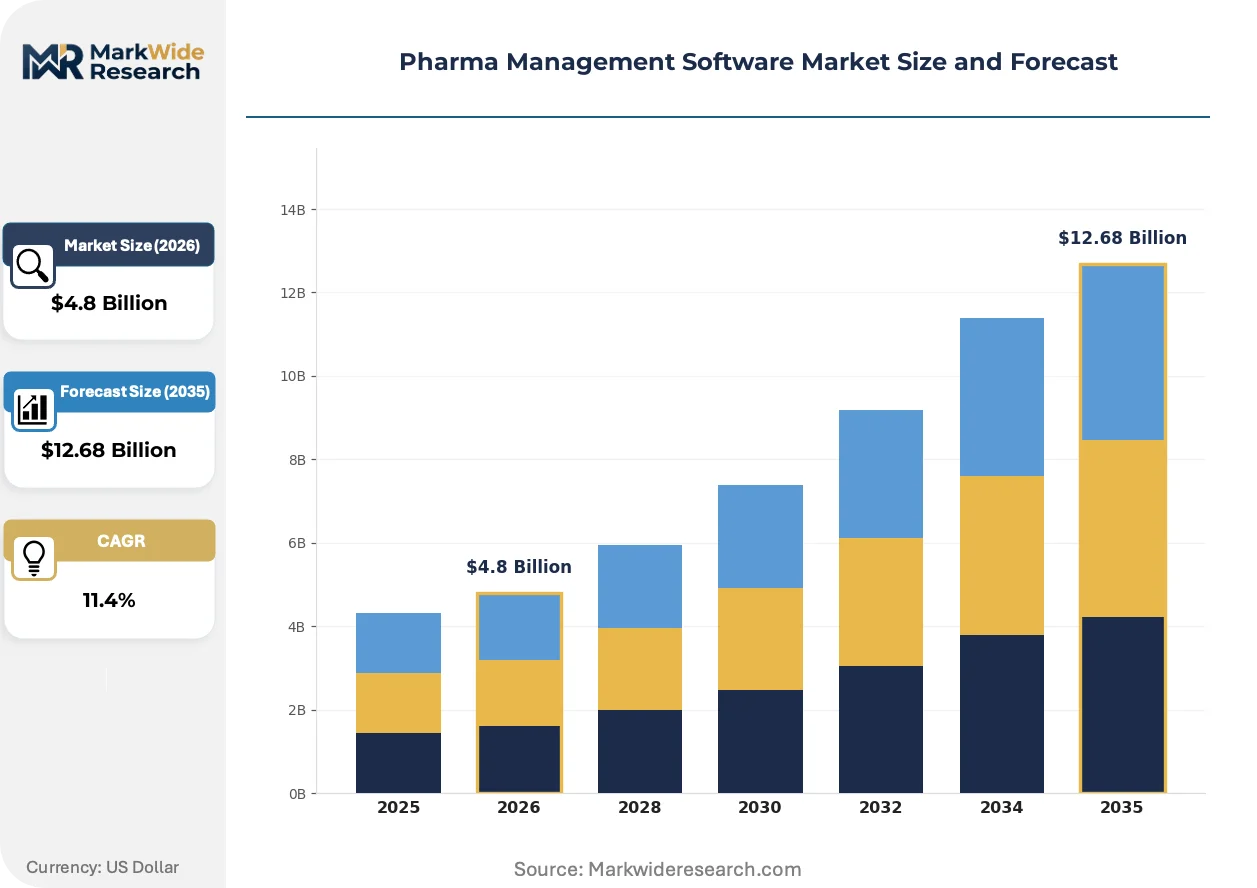
Market Dynamics
Cloud migration is compressing replacement cycles for validated pharmaceutical systems as FDA 21 CFR Part 11 compliance deadlines force asset retirements. Contract Research Organizations now drive disproportionate demand growth through outsourced clinical operations.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record integrity mandates accelerate legacy system replacements across GxP environments. Validation requirements create sustained upgrade pressure.
- Decentralized trial complexity:Real-time patient monitoring demands Clinical Trial Management systems with elastic cloud architectures. Mid-tier sponsors expand technology procurement.
- Contract Research Organizations:Outsourcing concentration in the United States generates concentrated software demand. CROs prioritize scalable platforms for multi-site coordination.
Market Restraints
- Validation cost structure:Computer software assurance documentation requirements inflate implementation timelines. Small manufacturers defer upgrades.
- Technical debt accumulation:Hybrid cloud architectures introduce interoperability friction with on-premise legacy databases. Data migration risks stall procurement decisions.
- Substitution threat from integrated suites:Enterprise database vendors bundle pharma modules at discounted rates. Standalone application vendors face pricing compression.
Strategic Opportunities
- Pharmacovigilance automation:EMA's evolving signal detection requirements create whitespace for AI-augmented adverse event processing. Regulatory scope expansion favors specialized modules.
- Real-world evidence convergence:Linkage between electronic health records and trial management systems enables post-market surveillance integration. Data service bundling differentiates vendors.
- India CDSCO pathway digitization:Clinical trial approval acceleration initiatives drive demand for regulatory submission software. Domestic CROs modernize infrastructure.
Industry Challenges
- Qualified validation engineer scarcity:GxP computer system validation expertise concentrates among specialized consultants. Talent competition inflates implementation costs.
- Multi-vendor integration complexity:Best-of-breed procurement strategies create API maintenance burdens. Data integrity audit trails fragment across platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Management Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Trial Management, Laboratory Information Management, Regulatory Compliance Management, Inventory Management End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Data Management, Workflow Automation, Reporting and Analytics, Cost Management |
| Companies Covered | Veeva Systems, Oracle, McKesson Corporation, Cerner Corporation, Epic Systems Corporation, IQVIA, LS Retail, Liberty Software, Datascan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Management Software Market Emerging Trajectories
Artificial intelligence and distributed computing architectures are restructuring how pharmaceutical data flows through development pipelines. Regulatory digitization and buyer consolidation are compressing vendor selection cycles.
Edge computing for clinical site data capture is hybridizing with centralized cloud repositories to enable real-time protocol deviations monitoring. Mid-sized biotechnology sponsors in the United States adopt these architectures fastest. The technology is hybridizing patient enrollment timelines by collapsing data reconciliation delays between investigative sites and central monitors.
EMA's Clinical Trial Information System mandates are forcing submission format standardization across European sponsors. Regulatory dossier preparation now requires structured data exchange protocols. Small-to-mid pharmaceutical companies in Germany and France accelerate software procurement to meet compliance deadlines.
Outcome-based licensing arrangements are displacing perpetual license models among large manufacturers. Subscription financing transfers capital expenditure risk to vendors. This shift concentrates most visibly among United States-based Contract Research Organizations managing variable trial portfolios.
Pharma Management Software Market Segmentation
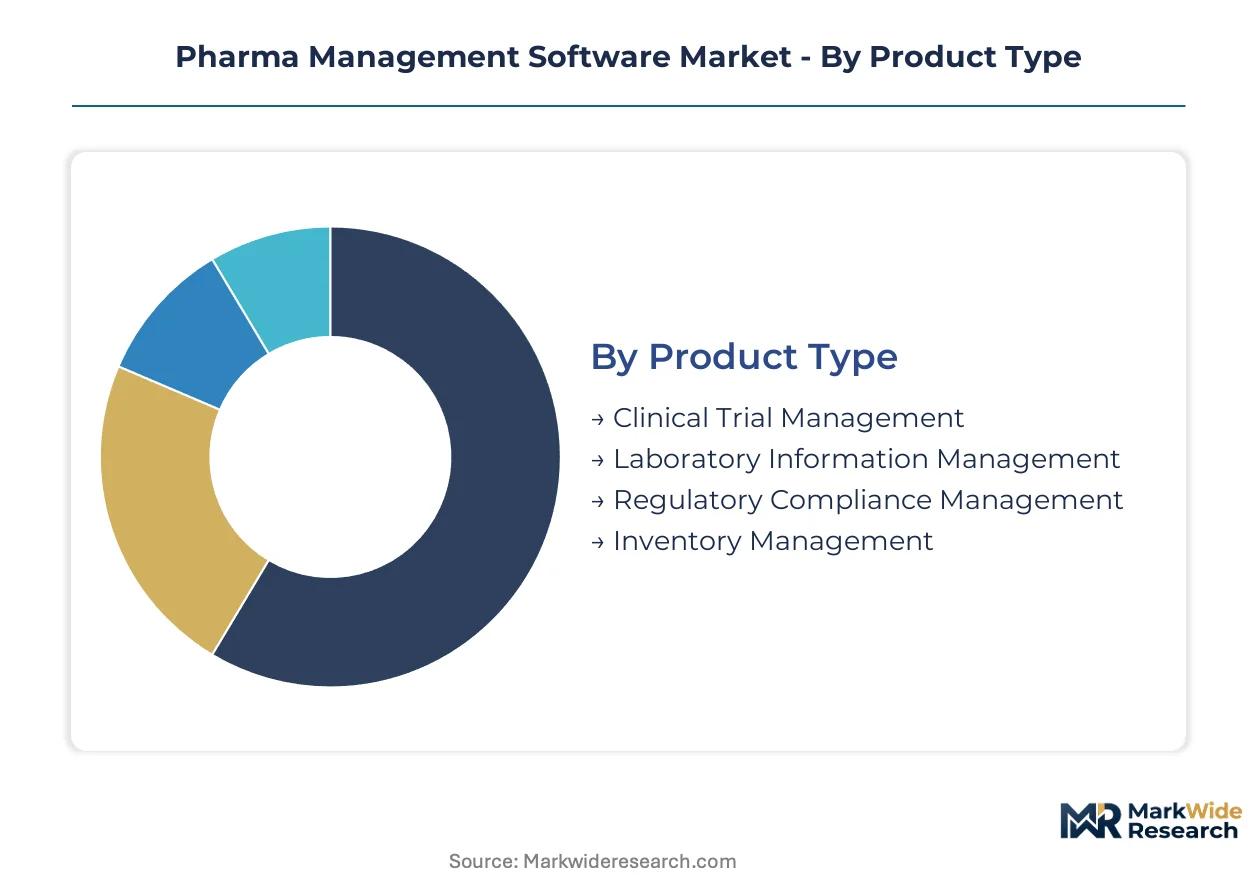
Segmentation reveals how regulatory complexity and outsourcing economics reshape procurement patterns across pharmaceutical software. Buyers prioritize validated architectures that compress trial timelines while satisfying multi-jurisdiction compliance mandates.
Product Type:
Application focus determines validation burden and replacement frequency across GxP environments.
- Clinical Trial Management:Orchestrates site coordination, patient enrollment, and protocol deviation monitoring through centralized dashboards. Contract Research Organizations in the United States drive disproportionate demand as outsourced trial execution concentrates. FDA 21 CFR Part 11 validation requirements sustain premium pricing for audit-ready configurations.
- Laboratory Information Management:Manages sample tracking, instrument integration, and analytical workflow documentation across quality control operations. Biotechnology firms prioritize cloud-native deployments to accelerate method transfer between CRO partners. Data integrity audit trails consume implementation engineering resources.
- Regulatory Compliance Management:Structures submission dossiers for EMA and FDA electronic gateways.
- Inventory Management:Tracks serialized drug products through distribution channels with chain-of-custody documentation.
Clinical Trial Management holds installed capacity. Laboratory Information Management is rotating up the share rankings.
End User:
Buyer scale and outsourcing intensity create divergent platform requirements across the value chain.
- Pharmaceutical Companies:Demand enterprise-grade suites integrating manufacturing quality, clinical operations, and pharmacovigilance through unified data architectures. Large manufacturers consolidate vendor relationships to reduce validation overhead across global affiliates. Oracle and SAP database dominance anchors procurement decisions.
- Contract Research Organizations:Prioritize elastic cloud architectures supporting variable trial portfolios and multi-site coordination. United States-based CROs expand technology procurement fastest as sponsor outsourcing intensifies. Subscription financing transfers capital expenditure risk from balance sheets.
- Biotechnology Firms:Favor modular, best-of-breed applications with rapid deployment timelines.
- Academic Institutions:Utilize grant-funded installations for investigator-initiated trials with limited commercial scope.
Pharmaceutical Companies anchor revenue concentration. Contract Research Organizations are climbing the fastest.
Deployment:
Infrastructure choice reflects data sovereignty requirements and legacy system entanglement across buyer segments.
- Cloud-Based:Delivers elastic compute for decentralized trial data capture and real-time analytics without capital infrastructure. Mid-tier biotechnology sponsors adopt these architectures fastest in the United States. EMA GDPR cross-border transfer protocols complicate European deployments.
- SaaS:Transfers operational responsibility to vendors through outcome-based licensing with embedded maintenance. Contract Research Organizations managing variable trial volumes favor consumption-aligned pricing. Validation documentation standardization reduces customer engineering burden.
- On-Premises:Retains physical control over validated servers for high-security manufacturing environments.
- Hybrid:Balances legacy database retention with cloud analytics for transitional architectures.
On-Premises retains validation depth. Cloud-Based is gaining share fastest.
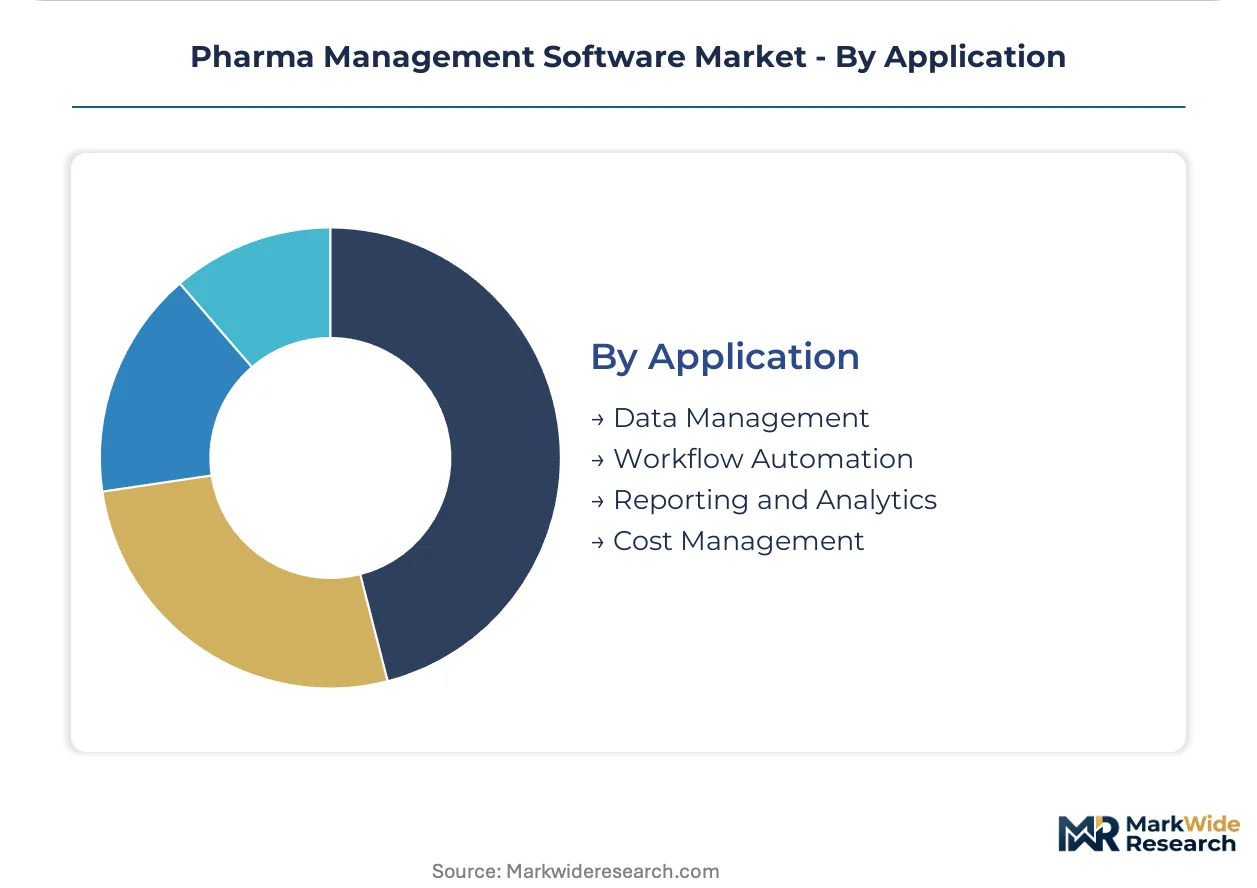
Application:
Functional priority shapes integration architecture and user workflow design across platform configurations.
- Workflow Automation:Eliminates manual handoffs between clinical, regulatory, and quality functions through predefined business rules. Pharmaceutical companies reduce protocol amendment cycle times by collapsing sequential approval chains. FDA computer software assurance guidance elevates documentation requirements.
- Reporting and Analytics:Aggregates trial performance metrics and safety signals for real-time portfolio oversight. Biotechnology sponsors leverage these capabilities to optimize site selection and patient recruitment strategies. EMA signal detection mandates expand adverse event processing scope.
- Data Management:Centralizes electronic health record linkages and real-world evidence repositories.
- Cost Management:Tracks clinical trial budgets and vendor spend against milestone deliverables.
Data Management holds historical investment. Workflow Automation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance deadlines and EMA's Clinical Trial Information System mandates are accelerating software procurement across major pharmaceutical markets. Cloud migration incentives and CRO outsourcing concentration are reshaping regional demand patterns.
United States
Contract Research Organizations in Boston and the Research Triangle Park drive disproportionate demand for Clinical Trial Management systems. FDA computer software assurance guidance elevates validation documentation requirements for electronic records. The San Francisco Bay Area anchors cloud-native vendor development while mid-tier biotechnology sponsors in San Diego adopt hybrid architectures fastest.
Germany
EMA's structured data exchange protocols force small-to-mid pharmaceutical companies in Munich and Frankfurt to accelerate regulatory submission software procurement. The country's national pharmaceutical regulator enforces strict pharmacovigilance signal detection mandates. Baden-Württemberg's biotechnology cluster modernizes Laboratory Information Management infrastructure to meet cross-border transfer protocols.
Switzerland
Swissmedic's evolving digital submission requirements create replacement demand for legacy validated systems across Basel's pharmaceutical headquarters concentration. The regulator's data integrity standards align with FDA and EMA frameworks. Geneva's Contract Research Organizations prioritize scalable platforms for multi-site trial coordination.
India
CDSCO's clinical trial approval digitization initiatives drive regulatory submission software demand among domestic CROs in Hyderabad and Bangalore. The national pharmaceutical regulator's pathway modernization accelerates infrastructure investment. Maharashtra's biotechnology corridor attracts cloud deployment from sponsors seeking cost-efficient validation engineering.
Japan
PMDA's harmonization with ICH E6(R2) guidelines elevates electronic source data verification requirements for Tokyo-based pharmaceutical manufacturers. The regulator's quality management system expectations align with global GxP standards. Osaka's clinical research organizations adopt SaaS financing models to manage variable trial portfolios.
Pharma Management Software Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: enterprise database incumbents bundling pharma modules, cloud-native vertical specialists, and data service integrators combining software with real-world evidence capabilities. M&A activity concentrates on acquiring validation-ready cloud architectures. Strategic partnerships between CROs and platform vendors accelerate subscription financing adoption.
Within the enterprise software tier, Oracle leverages database dominance to anchor integrated suites across large manufacturers. Veeva Systems exemplifies cloud-native vertical specialization through life sciences application depth. IQVIA occupies a position combining software licensing with real-world data services, extending beyond pure technology provision. These three anchors represent contrasting competitive vectors: infrastructure consolidation, vertical SaaS purity, and service bundling differentiation.
| Leading Market Players |
|---|
| Veeva Systems |
| Oracle |
| McKesson Corporation |
| Cerner Corporation |
| Epic Systems Corporation |
| IQVIA |
| LS Retail |
| Liberty Software |
| Datascan |
| Others |
Supply Flow & Price Mechanics
Validation engineering talent concentrates in the United States and Western Europe, anchoring margin pools with systems integrators and specialized consultancies rather than software vendors themselves. This upstream concentration forces buyers to absorb implementation cost inflation that vendors cannot fully capture in license fees.
Pricing Analysis
Certification level (FDA 21 CFR Part 11-grade) creates the primary spread between audit-ready enterprise configurations and standard cloud deployments. Subscription-based SaaS financing dominates among Contract Research Organizations, while perpetual licensing persists in large pharmaceutical manufacturers with captive IT infrastructure. Price differentiation stems from validation documentation depth and embedded compliance engineering hours. Cost compression in mid-tier SaaS tiers is intensifying because enterprise database vendors bundle competing modules at discounted rates. Biotechnology firms exhibit highest price sensitivity due to grant-dependent budgets; large manufacturers with consolidated vendor relationships show lowest sensitivity.
Supply Chain Analysis
Cloud infrastructure feeds from hyperscaler data centers concentrated in the United States, Ireland, and Singapore, with secondary nodes expanding in India and Switzerland. Software development draws from engineering talent pools in the United States, India, and Germany, while validation documentation rests on specialized consultant networks in the United States and United Kingdom. Single-source vulnerability concentrates in FDA-qualified validation engineer scarcity, where talent competition inflates implementation timelines. Distribution runs through direct enterprise sales for large manufacturers and channel partners serving mid-tier biotechnology sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on interoperability standards tightening around EMA's Clinical Trial Information System and FDA's evolving computer software assurance guidance, favoring vendors with modular API architectures over monolithic suites.
For Market Incumbents: Insulate installed base relationships by embedding validation documentation services that increase switching costs for large pharmaceutical manufacturers. Deepen backward integration into real-world data assets to differentiate against enterprise database competitors bundling generic modules. Prioritize certification investment in emerging pharmacovigilance automation standards before specialized entrants capture signal detection whitespace. For New Entrants and Emerging Players: Mid-tier biotechnology sponsors in the United States and domestic CROs in India represent the most penetrable entry points, as these segments prioritize rapid deployment over enterprise suite consolidation. Cloud-native modular applications with pre-validated configurations address the unmet demand for compressed implementation timelines. A channel partnership strategy with regional systems integrators accelerates access to validation engineering resources without building captive consulting capacity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical SaaS specialists possessing FDA-validated cloud architectures but limited geographic footprint. Long-term viability favors platforms demonstrating sustained R&D productivity across regulatory jurisdictions rather than single-market concentration. Watch EMA's structured data exchange protocol adoption rates as the inflection indicator for replacement demand acceleration in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies clinical, regulatory, and quality workflows through validated APIs, reducing multi-vendor audit trail fragmentation. |
| Acquisition of Specialist Firm | Adds pharmacovigilance automation capabilities that address EMA's evolving signal detection requirements. |
| Strategic Partnership | Links trial management systems with electronic health record networks for real-world evidence convergence. |
| Geographic Expansion | Establishes validation engineering presence in India to capture CDSCO digitization-driven procurement. |
| Product Launch | Introduces edge computing architectures for decentralized trial data capture with real-time protocol monitoring. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, EMA Clinical Trial Information System specifications, and ClinicalTrials.gov protocol registries. Primary interviews engaged drug development executives, regulatory affairs leads, CRO technology procurement officers, and validation engineering consultants across the United States, Germany, Switzerland, and India. Secondary sources encompassed SEC filings from publicly traded vendors, hyperscaler cloud infrastructure disclosures, and national pharmaceutical regulator policy announcements. Bottom-up demand modeling triangulated against top-down market sizing derived from pharmaceutical R&D expenditure patterns.
Forecast inputs considered deployment model migration rates, outsourcing intensity shifts among sponsor organizations, and regulatory deadline schedules across the analysis window. Segmentation dimensions modeled include product type, end user scale, deployment architecture, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted adoption curves applied to validated system replacement cycles. Industry-specific inputs incorporated FDA computer software assurance guidance implementation timelines and EMA structured data exchange protocol adoption trajectories.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D funding levels, biotechnology venture capital availability, or regulatory approval pathway timelines would shift the trajectory. Forecasts reflect assumptions about sustained outsourcing concentration and cloud migration incentives without accounting for potential data sovereignty restrictions or validation standard harmonization failures. Cross-checking against external benchmarks from healthcare IT expenditure surveys and CRO technology investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Healthcare Survey Software Market