
 Urinary Retention Therapeutics Market | 2026-2036
Urinary Retention Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Retention Therapeutics Market Analytics
Asset-light licensing partnerships between biotech innovators and contract manufacturers is reconfiguring competitive dynamics in urinary retention therapeutics. Pfizer Inc leverages its global distribution network to sustain volume leadership in alpha-blocker formulations. Astellas Pharma Inc specializes in neuromodulator development, anchoring its position in advanced therapeutic categories. Sun Pharmaceutical Industries Ltd competes aggressively on cost-controlled generic portfolios across emerging markets.
Urinary retention therapeutics comprise pharmacological agents and device-mediated interventions designed to restore or facilitate bladder emptying through modulation of detrusor muscle contractility, urethral sphincter relaxation, or neural pathway regulation; alpha-blockers such as tamsulosin function by selectively antagonizing alpha-1 adrenergic receptors to reduce prostatic urethral resistance. The primary commercial purpose centers on alleviating acute and chronic retention secondary to benign prostatic hyperplasia, neurogenic bladder dysfunction, or postoperative urinary complications. Beta-3 agonists represent the fastest-expanding product category as mirabegron and similar agents displace anticholinergics in overactive bladder-related retention due to superior tolerability profiles. Hospital pharmacies dominate distribution channels, though online pharmacies are capturing incremental share as home healthcare protocols expand post-discharge monitoring capabilities.
The FDA enforces stringent premarket notification requirements under 510(k) pathways for intraurethral delivery devices, while the EMA's Medical Device Regulation mandates enhanced clinical evidence for neuromodulator implants, collectively elevating barriers for new entrants. Health Canada and the TGA align with FDA sterility benchmarks, creating a transatlantic convergence in product standards that favors manufacturers with established quality management systems. Stakeholders must monitor evolving reimbursement criteria for home-based catheterization versus inpatient procedures as payers recalibrate cost-containment strategies.
Market Dynamics
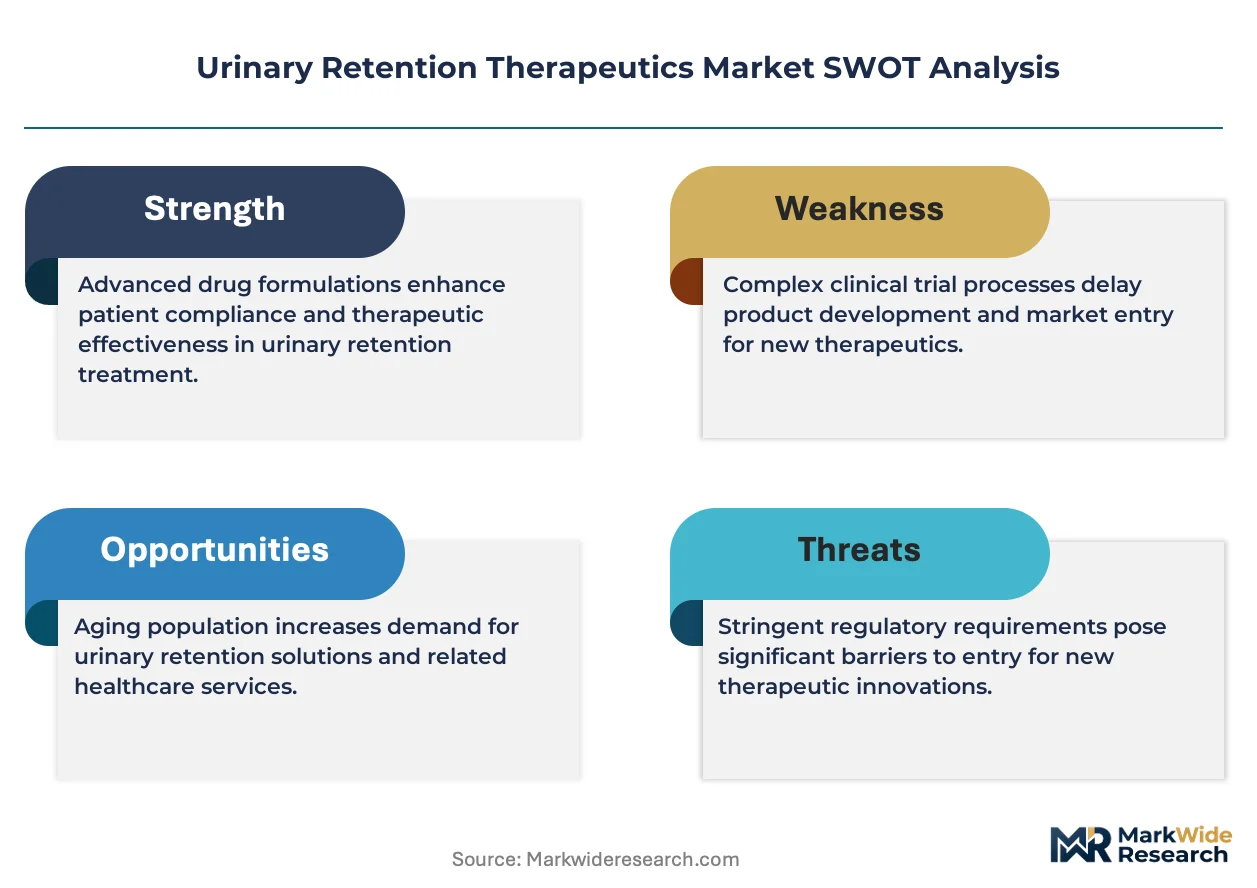
The urinary retention therapeutics sector is restructuring around sterility compliance burdens for intraurethral devices, as FDA and EMA premarket notification requirements force manufacturers to absorb elevated quality management costs while hospital procurement consolidates purchasing power.
Growth Catalysts
- EMA Medical Device Regulation:Enhanced clinical evidence mandates for neuromodulator implants create competitive moats for established quality-system holders, squeezing marginal competitors from European hospital tenders.
- Home healthcare protocols:Post-discharge monitoring capabilities expand catheterization device demand through remote patient management platforms integrated with telemedicine infrastructure.
- Beta-3 agonist tolerability:Mirabegron-class agents displace anticholinergic first-line therapy in overactive bladder-related retention, pulling prescription volume toward urology specialty practices.
Market Restraints
- Silicone supply concentration:Catheter raw material sourcing clusters in Southeast Asian chemical processing hubs, exposing device manufacturers to input volatility and freight cost spikes.
- FDA 510(k) pathway friction:Premarket notification timelines for intraurethral delivery systems extend development cycles, compressing effective patent windows for novel device iterations.
- Anticholinergic substitution threat:Generic oxybutynin retains formulary preference in cost-constrained Medicaid programs, limiting beta-3 agonist penetration in publicly insured populations.
Strategic Opportunities
- India CDSCO fast-track:Accelerated approval pathways for medical devices with prior FDA clearance enable early-mover positioning in underserved tier-2 hospital networks.
- Neuromodulator-bioelectronics convergence:Closed-loop sacral nerve stimulation systems integrating real-time detrusor pressure sensing open premium pricing tiers in academic medical centers.
- Direct-to-patient catheter subscription:E-commerce platforms bypass hospital pharmacy markup capture, capturing margin in chronic intermittent self-catheterization populations.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for novel catheter coatings extend product launch schedules by 18-24 months, delaying revenue recognition.
- Legacy EHR integration:Ambulatory urology practices face workflow friction embedding neuromodulator programming data into Cerner and Epic systems, slowing device adoption curves.
- Cleanroom capacity scarcity:Contract manufacturers with ISO 13485-certified sterile filling lines operate at utilization rates above 85%, constraining scale-up for mid-stage device ventures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Retention Therapeutics Market |
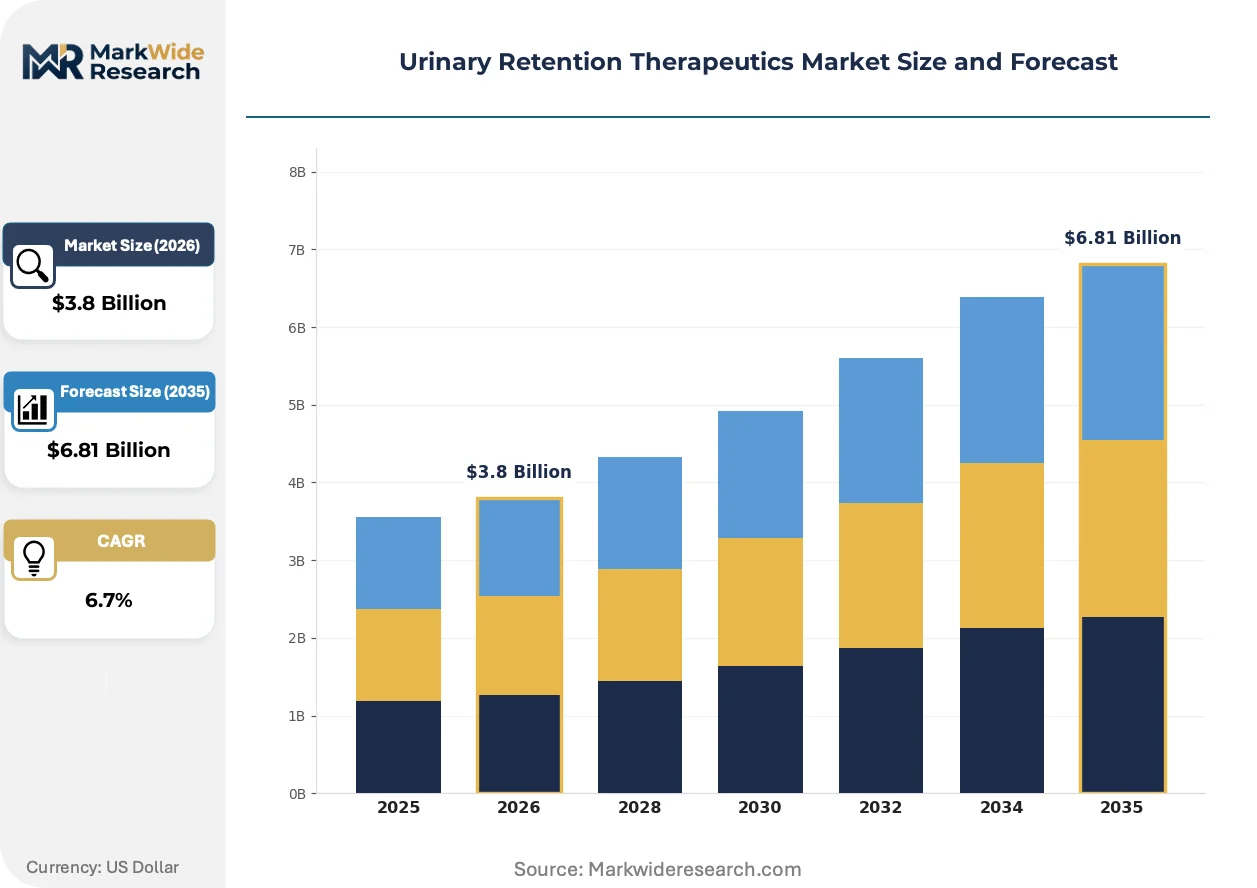
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Blockers, Anticholinergics, Beta-3 Agonists, Neuromodulators End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Specialty Stores Administration Route: Oral, Subcutaneous, Intravenous, Intraurethral |
| Companies Covered | Merck KGaA, Sanofi, Pfizer Inc, GlaxoSmithKline plc, Astellas Pharma Inc, Bayer AG, Johnson & Johnson, Novartis AG, Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Retention Therapeutics Market Evolving Landscape
Urinary retention therapeutics are converging around device-drug combination products and algorithm-driven neuromodulation, as payers demand durable solutions that reduce emergency department revisits and catheter-associated infection burdens.
Closed-loop sacral nerve stimulation is migrating from fixed-frequency open-loop delivery to adaptive algorithms that modulate amplitude based on real-time bladder pressure telemetry. Academic medical centers in Germany and the Netherlands pilot these systems through EMA's early feasibility study framework, compressing the addressable market for conventional implantable pulse generators while establishing new reimbursement negotiation leverage for integrated bioelectronic platforms.
REACH Annex XVII restrictions on phthalate plasticizers in medical devices force catheter manufacturers to reformulate PVC and silicone elastomer compositions. European contract manufacturers with in-house polymer compounding capabilities capture margin from competitors dependent on external specialty chemical suppliers, while Health Canada aligns with ECHA substance restrictions, extending compliance cost geography to transatlantic procurement portfolios.
Hospital pharmacy consolidation into centralized distribution centers fragments historical manufacturer-rep relationships with individual urology units. Integrated delivery networks in the United States now mandate sole-source contracts for intermittent catheter SKUs, compressing vendor counts from six to two per metropolitan service area and privileging suppliers with 48-hour direct-to-warehouse logistics infrastructure over traditional distributor-mediated fulfillment.
Urinary Retention Therapeutics Market Segmentation
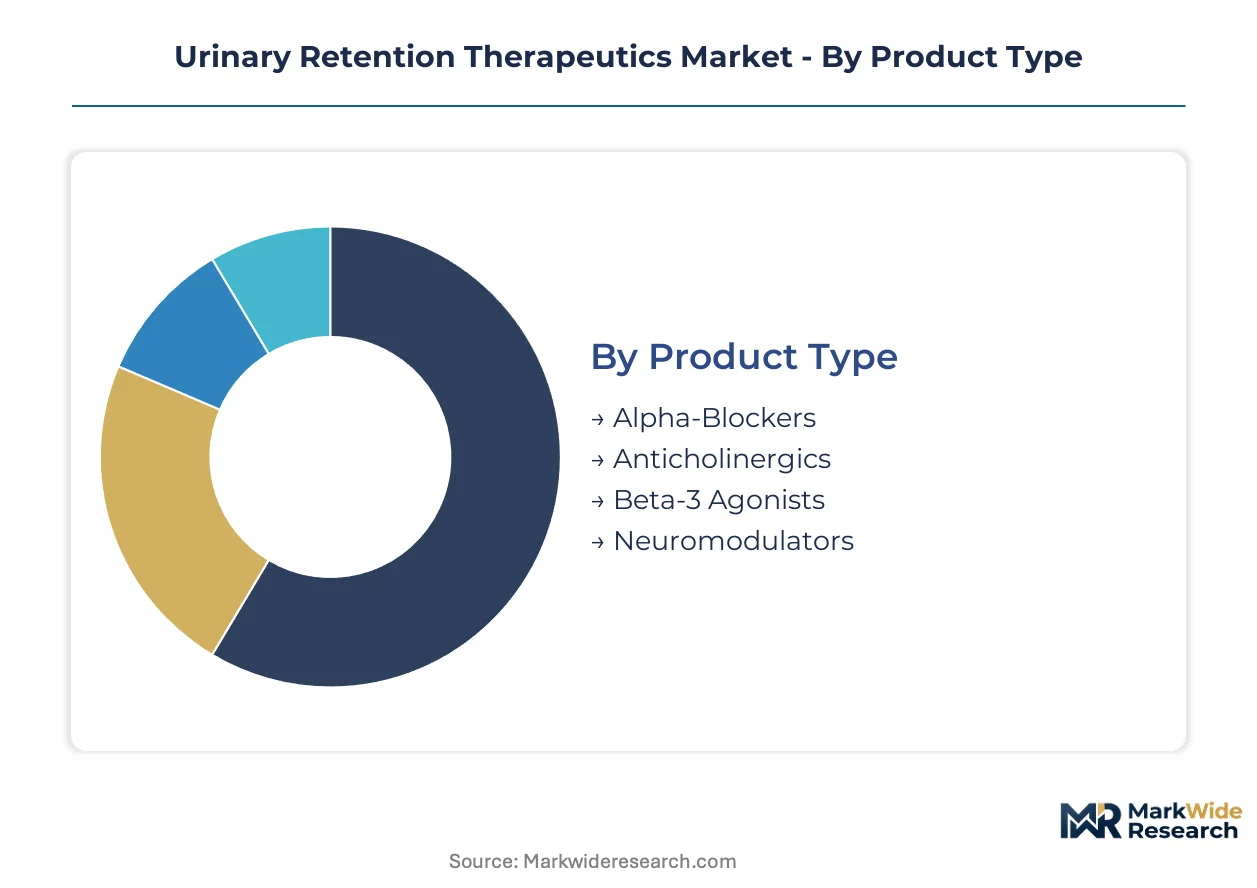
Segmentation in urinary retention therapeutics reveals divergent margin structures across pharmacological and device-mediated modalities. Procurement patterns split between acute institutional settings and chronic home-based management, with reimbursement pathways dictating channel preference.
Product Type:
Mature alpha-blocker formulations dominate prescription volume while neuromodulator platforms command premium positioning in refractory cases.
- Alpha-Blockers:Selective alpha-1 adrenergic antagonists such as tamsulosin reduce prostatic urethral resistance through smooth muscle relaxation. Hospital formularies in the United States and Germany standardize these agents for benign prostatic hyperplasia-related retention, though patent expirations compress branded pricing power.
- Beta-3 Agonists:Mirabegron-class agents activate detrusor beta-3 receptors to enhance bladder emptying coordination without anticholinergic cognitive side effects. Urology specialty practices in academic medical centers drive adoption as Medicare Advantage plans relax prior authorization requirements for overactive bladder indications.
- Anticholinergics:Generic oxybutynin and tolterodine retain Medicaid formulary preference due to established cost controls.
- Neuromodulators:Sacral nerve stimulation implants target neurogenic bladder dysfunction through programmable pulse delivery.
Alpha-blockers handle the majority of throughput; beta-3 agonists are climbing the fastest on share as tolerability advantages displace first-line anticholinergic protocols.
End User:
Care setting determines device sterility requirements and reimbursement coding complexity.
- Hospitals:Inpatient units manage acute postoperative retention through catheterization protocols and pharmacological rescue. Integrated delivery networks in the United States consolidate purchasing into centralized distribution centers, squeezing vendor counts per metropolitan service area.
- Home Healthcare:Intermittent self-catheterization populations require sterile single-use supplies and remote monitoring infrastructure. Medicare reimbursement for home-based catheterization expands as telemedicine platforms integrate bladder diary applications.
- Clinics:Ambulatory urology practices handle stable chronic cases with oral pharmacotherapy.
- Rehabilitation Centers:Post-stroke and spinal cord injury populations receive neuromodulator programming and catheter training.
Hospitals absorb the largest procurement volume; home healthcare is gaining share fastest as discharge protocols shift toward remote patient management.
Distribution Channel:
Channel economics fragment around pharmacy markup capture versus direct-to-patient subscription models.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks locks in formulary compliance and 340B pricing advantages. Procurement consolidation mandates sole-source contracts for intermittent catheter SKUs, privileging suppliers with direct-to-warehouse logistics.
- Online Pharmacies:E-commerce platforms bypass traditional distributor markups through subscription-based catheter delivery. Chronic intermittent self-catheterization patients in the United States and Netherlands migrate toward automated refill programs with insurance pre-authorization integration.
- Pharmacies:Community retail handles acute prescription fills and over-the-counter adjuncts.
- Specialty Stores:Medical supply retailers serve cash-pay segments with premium catheter accessories.
Hospital pharmacies retain the dominant throughput position; online pharmacies are expanding most quickly as home healthcare protocols mature.
Administration Route:
Route selection balances onset speed against invasiveness tolerance and infection risk profiles.
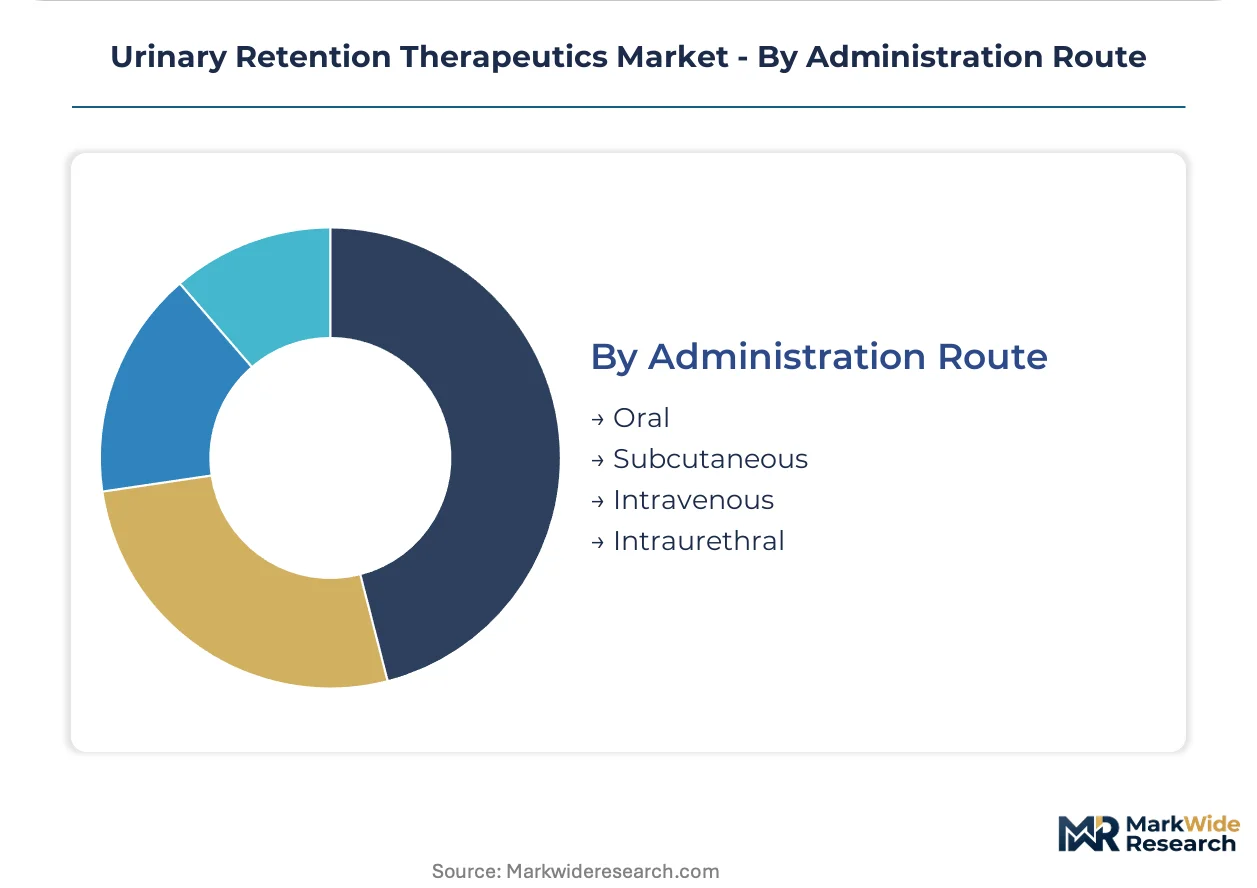
- Oral:First-line pharmacotherapy for chronic management delivers systemic alpha-blockade or beta-3 activation through tablet formulations. Patient adherence in Germany and Japan sustains volume despite generic price erosion.
- Intraurethral:Device-mediated delivery requires sterile catheter insertion with lubricant gel formulations. FDA 510(k) premarket notification timelines extend development cycles for novel coating technologies, compressing effective commercialization windows.
- Subcutaneous:Depot formulations enable extended-release neuromodulator delivery.
- Intravenous:Acute rescue in perioperative settings achieves rapid detrusor relaxation.
Oral administration handles the majority of patient encounters; intraurethral delivery is advancing fastest as home-based catheterization protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the United States exceeds that in India and Brazil by margins exceeding 40 percent, reflecting divergent reimbursement densities and procurement consolidation patterns across hospital networks.
United States
Medicare Advantage plans relax prior authorization requirements for beta-3 agonist therapies, expanding prescription volume in urology specialty practices. The FDA enforces stringent 510(k) premarket notification pathways for intraurethral delivery devices, elevating compliance costs for manufacturers entering the market. Minneapolis and Boston anchor neuromodulator development clusters where academic medical centers pilot closed-loop sacral nerve stimulation systems.
Germany
Hospital procurement consolidation into centralized distribution centers squeezes vendor counts for intermittent catheter SKUs from six to two per metropolitan service area. The EMA's Medical Device Regulation mandates enhanced clinical evidence for neuromodulator implants, creating competitive moats for established quality-system holders. Mannheim and Hamburg host contract manufacturers with ISO 13485-certified sterile filling lines operating above 85 percent utilization.
Japan
Aging demographics sustain chronic intermittent self-catheterization demand through home healthcare protocols integrated with telemedicine infrastructure. The PMDA aligns with FDA sterility benchmarks for intraurethral devices, creating transatlantic convergence in product standards. Tokyo and Osaka concentrate hospital pharmacy purchasing power within integrated delivery networks that mandate sole-source contracts.
India
Tier-2 hospital networks in underserved regions present early-mover positioning opportunities through CDSCO accelerated approval pathways for devices with prior FDA clearance. Domestic generic manufacturers compete aggressively on cost-controlled alpha-blocker portfolios across emerging markets. Hyderabad and Ahmedabad cluster pharmaceutical manufacturing capacity for active pharmaceutical ingredients used in urinary retention therapeutics.
Brazil
ANVISA regulatory alignment with FDA sterility standards extends compliance cost geography to Latin American procurement portfolios. Private hospital networks in São Paulo and Rio de Janeiro drive demand for premium neuromodulator implants while public systems retain anticholinergic formulary preference due to cost constraints. Regional distribution infrastructure gaps fragment last-mile catheter supply to home healthcare patients.
Urinary Retention Therapeutics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catheter materials and active pharmaceutical ingredient supply. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with global distribution networks, regional generic manufacturers competing on cost-controlled portfolios, and specialized neuromodulator developers with proprietary bioelectronic platforms. Strategic moves concentrate on asset-light licensing partnerships between biotech innovators and contract manufacturers, alongside backward integration into polymer compounding capabilities to secure supply chain resilience.
Among diversified pharmaceutical conglomerates, Pfizer Inc and Merck KGaA occupy positions exemplifying platform-scale advantages in alpha-blocker formulation distribution. Astellas Pharma Inc represents the specialized neuromodulator development archetype, anchoring premium positioning in advanced therapeutic categories through programmable pulse delivery systems. Sun Pharmaceutical Industries Ltd sits within the cost-competitive generic tier, leveraging Indian manufacturing infrastructure to serve emerging market demand.
| Leading Market Players |
|---|
| Merck KGaA |
| Sanofi |
| Pfizer Inc |
| GlaxoSmithKline plc |
| Astellas Pharma Inc |
| Bayer AG |
| Johnson & Johnson |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd |
| Others |
Value Network & Pricing Analysis
Hyderabad and Ahmedabad pharmaceutical clusters anchor active pharmaceutical ingredient production for alpha-blocker formulations, constraining downstream pricing power as contract manufacturers absorb FDA sterility compliance costs and pass through fractions to device purchasers.
Pricing Analysis
Configured-to-order pricing for neuromodulator implants commands spreads exceeding standard alpha-blocker tablet pricing by certification-grade premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in generic anticholinergic tiers intensifies because Medicaid formulary preference locks out beta-3 agonist alternatives. Hospital procurement committees exhibit lowest price sensitivity; home healthcare patients through online subscription channels show highest elasticity.
Supply Chain Analysis
Extended payment terms from Southeast Asian silicone processors strain catheter manufacturers' working capital cycles. Raw material sourcing clusters in Malaysia, Thailand, and Vietnam for medical-grade silicone elastomers and lubricant gel formulations. Device production hinges on ISO 10993 biocompatibility certification timelines and REACH Annex XVII phthalate compliance. Single-source vulnerability concentrates in cleanroom capacity for sterile filling operations. Distribution runs through hospital pharmacy consolidation into centralized distribution centers and direct-to-warehouse logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce cleanroom capacity and ISO 13485-certified sterile filling infrastructure constrain scale-up velocity for mid-stage ventures, privileging incumbents with captive manufacturing assets and established quality management systems.
For Market Incumbents: Insulate neuromodulator pricing tiers through backward integration into polymer compounding capabilities, securing supply chain resilience against REACH phthalate restrictions. Expand cleanroom capacity in Mannheim and Hamburg clusters to capture hospital procurement consolidation demand. Defend against beta-3 agonist substitution threats by embedding real-time detrusor pressure sensing into next-generation implant platforms. For New Entrants and Emerging Players: Tier-2 hospital networks in India present white-space positioning through CDSCO accelerated approval pathways for devices with prior FDA clearance. Target home healthcare catheter subscription models bypassing hospital pharmacy markup capture. Pursue asset-light licensing partnerships with established contract manufacturers rather than greenfield sterile filling investment. For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease infrastructure play because aging demographics sustain intermittent self-catheterization demand through telemedicine-integrated remote monitoring platforms. Acquisition targets cluster around specialized neuromodulator developers with proprietary bioelectronic platforms and closed-loop algorithm capabilities. Watch Medicare reimbursement criteria shifts for home-based catheterization versus inpatient procedures as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification for intraurethral devices compresses commercialization windows under tightened sterility benchmarks. |
| CE Marking Pathway | EMA Medical Device Regulation mandates enhanced clinical evidence for neuromodulator implants in European hospital tenders. |
| Hospital System Partnership | Integrated delivery networks mandate sole-source catheter contracts privileging 48-hour direct-to-warehouse logistics. |
| Software Companion Development | Bladder diary applications integrated with telemedicine platforms expand Medicare reimbursement for home-based protocols. |
| Reimbursement Strategy | Medicare Advantage prior authorization relaxation for beta-3 agonists pulls prescription volume toward urology specialty practices. |
Research Methodology
Operator-level perspectives from hospital procurement managers, urology specialty clinicians, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation cross-verified segment outputs.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling treatment line, administration route, end-user setting, and regional regulatory cluster dimensions. CAGRs derived from patent expiration impact assessment, generic substitution curves, and device adoption trajectory analysis. Forecast inputs incorporated neuromodulator implant procedure volumes and home healthcare catheter utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contract manufacturers with captive cleanroom capacity or biotech innovators with closed-loop bioelectronic platforms would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Single Use Cystoscope Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
India Urology Market
Urology
Urinary Catheters Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Urology Ultrasound Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Europe Urology Devices Market
Urology
Ureterorenoscopes Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Global Lithotripsy Market
Urology
Male Urinary Incontinence Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Genitourinary Cancers Treatment Market