
 Obsessive Compulsive Disorder (OCD) Drug Market | 2026-2036
Obsessive Compulsive Disorder (OCD) Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Obsessive Compulsive Disorder (OCD) Drug Market Analysis
Capital-intensity divergence between late-stage CNS pipeline specialists and generic SSRI manufacturers is redrawing competitive boundaries in the OCD drug landscape. Eli Lilly and Company leverages its deep neuropsychiatry research infrastructure to sustain innovation in serotonin modulation. H. Lundbeck AS anchors its position through specialized European regulatory expertise and prescriber loyalty in Nordic and German markets. Pfizer Inc. competes via broad commercial scale across hospital and retail pharmacy channels.
Obsessive Compulsive Disorder drug therapy encompasses selective serotonin reuptake inhibitors, serotonin-norepinephrine reuptake inhibitors, tricyclic antidepressants, and adjunctive antipsychotics formulated as oral tablets, capsules, or liquid suspensions for chronic administration in psychiatric care. The pharmacotherapy segment dominates current prescribing patterns through established SSRI protocols, while the combination therapy category integrates cognitive behavioral therapy with drug regimens to address treatment-resistant cases. Injectable formulations represent a faster-growing structural pocket as clinicians seek depot delivery options for medication adherence in severe OCD populations.
The FDA maintains stringent requirements for CNS drug approvals through controlled clinical trial designs, while the EMA's centralized neuropsychiatry assessment shapes market access across European member states and the WHO's essential medicines framework influences procurement in lower-income health systems. Regulatory scrutiny of pediatric OCD indications and digital therapeutic adjuncts continues to intensify across these agencies. Stakeholders must monitor how FDA guidance on biomarker-enriched trial designs and EMA real-world evidence requirements reshape development economics for novel mechanisms.
Market Dynamics
Treatment-resistant OCD populations are driving clinicians toward combination protocols that pair pharmacotherapy with cognitive behavioral interventions, fragmenting the historical dominance of standalone SSRI prescribing.
Growth Catalysts
- FDA digital therapeutics guidance:The agency's evolving framework for software-based adjuncts enables psychiatric clinics to integrate app-based exposure therapy with drug regimens, expanding addressable patient pools.
- German prescriber concentration:Lundbeck and European neuropsychiatry specialists maintain entrenched relationships with German psychiatrists, creating durable demand anchors for novel serotonin modulators.
- Depot formulation adoption:Injectable long-acting antipsychotics are gaining traction among severe OCD populations with adherence challenges, opening new structural pockets in chronic care protocols.
Market Restraints
- SSRI generic commoditization:Massive price compression in first-line selective serotonin reuptake inhibitors constrains revenue capture for novel mechanism developers.
- Pediatric indication scrutiny:FDA and EMA intensified safety monitoring for childhood OCD approvals extends trial timelines and inflates development economics.
- CNS clinical trial failure rates:Placebo response volatility in obsessive compulsive disorder studies elevates Phase III attrition beyond other psychiatric indications.
Strategic Opportunities
- Biomarker-enriched trial designs:FDA guidance on neuroimaging and genetic stratification allows developers to identify responder subpopulations, improving signal detection in heterogeneous patient bases.
- Specialty psychiatric clinic expansion:United States treatment centers are building dedicated pharmacotherapy units for refractory cases, creating concentrated prescriber access points.
- Real-world evidence pathways:EMA acceptance of registry data and post-market surveillance is compressing confirmatory study requirements for follow-on indications.
Industry Challenges
- Psychiatric trial recruitment:Patient retention in long-term OCD studies suffers from high dropout rates, inflating per-subject costs and timeline risk.
- Legacy SSRI switching friction:Established fluoxetine and sertraline protocols create prescriber inertia that novel mechanisms must overcome with differentiated efficacy signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Obsessive Compulsive Disorder (OCD) Drug Market |
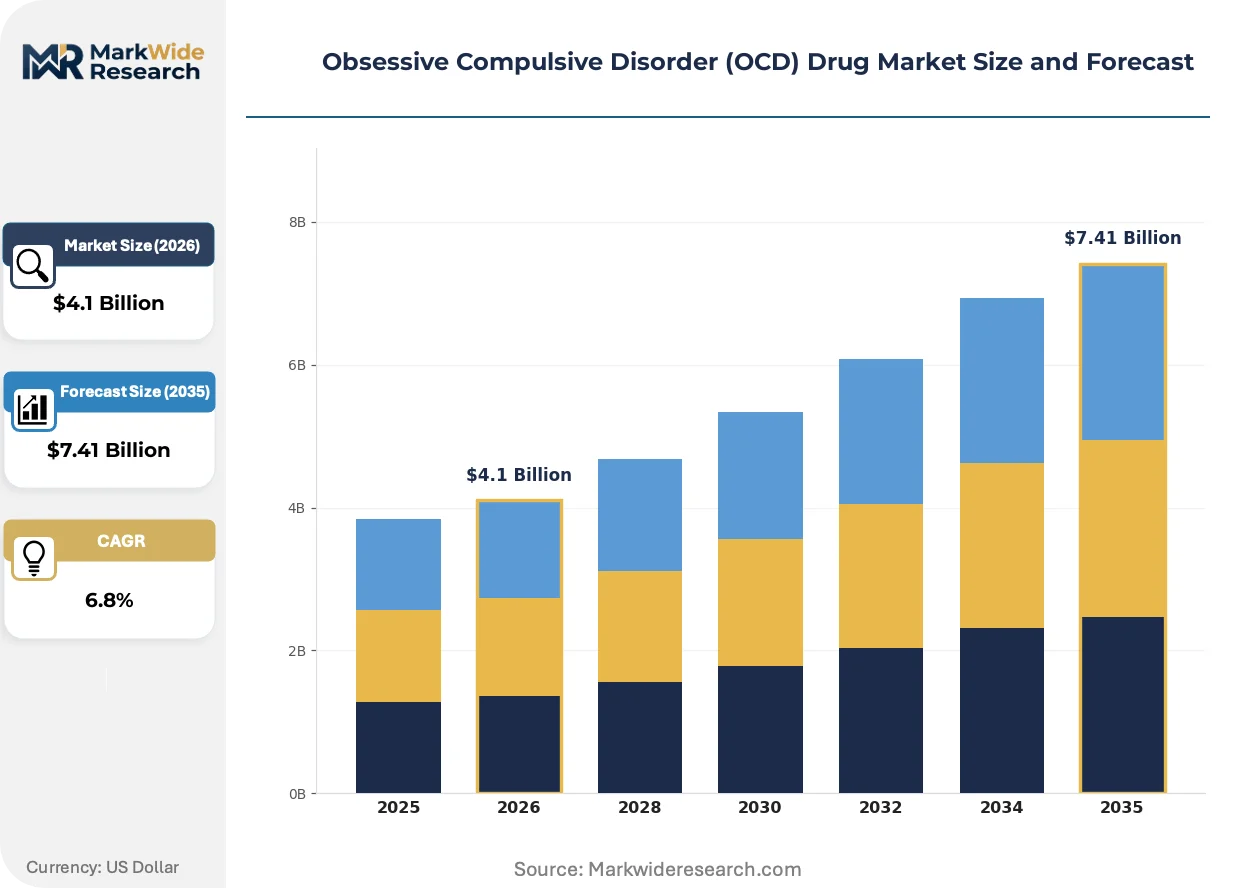
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: SSRIs, SNRIs, Tricyclics, Antipsychotics Formulation: Tablets, Capsules, Injectable, Liquid End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Approach: Cognitive Behavioral Therapy, Pharmacotherapy, Combination Therapy, Personalized Medicine |
| Companies Covered | Novartis AG, AstraZeneca, Eli Lilly and Company, Johnson & Johnson, Merck & Co. Inc, Pfizer Inc., H. Lundbeck AS, Takeda Pharmaceutical, GlaxoSmithKline Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Obsessive Compulsive Disorder (OCD) Drug Market Emerging Trajectories
Digital measurement-based care tools are penetrating psychiatric workflows, creating parallel demand for drug-adjunct platforms that track symptom severity and medication response in real time.
Glutamate-modulating agents targeting NMDA receptor pathways are fragmenting the serotonin-centric development landscape. Early-stage biotech sponsors and academic medical centers are advancing ketamine derivatives and rapastinel analogs through Phase II trials. These mechanisms are compressing the addressable market for incremental SSRI improvements by promising faster onset in treatment-resistant cohorts.
EMA centralized neuropsychiatry assessment procedures are harmonizing market access requirements across European member states. The agency's strengthened pediatric investigation plan mandates are forcing sponsors to embed childhood OCD cohorts earlier in development programs. German and Nordic regulators are responding with accelerated access schemes for drugs addressing high unmet need in refractory populations.
Specialty pharmacy distribution is displacing traditional retail channels for high-cost OCD adjuncts and injectable formulations. Payers are consolidating reimbursement decisions through pharmacy benefit managers, concentrating bargaining power. This channel shift is most visible in United States commercial insurance markets, where prior authorization requirements for branded CNS drugs have tightened substantially.
Obsessive Compulsive Disorder (OCD) Drug Market Segmentation
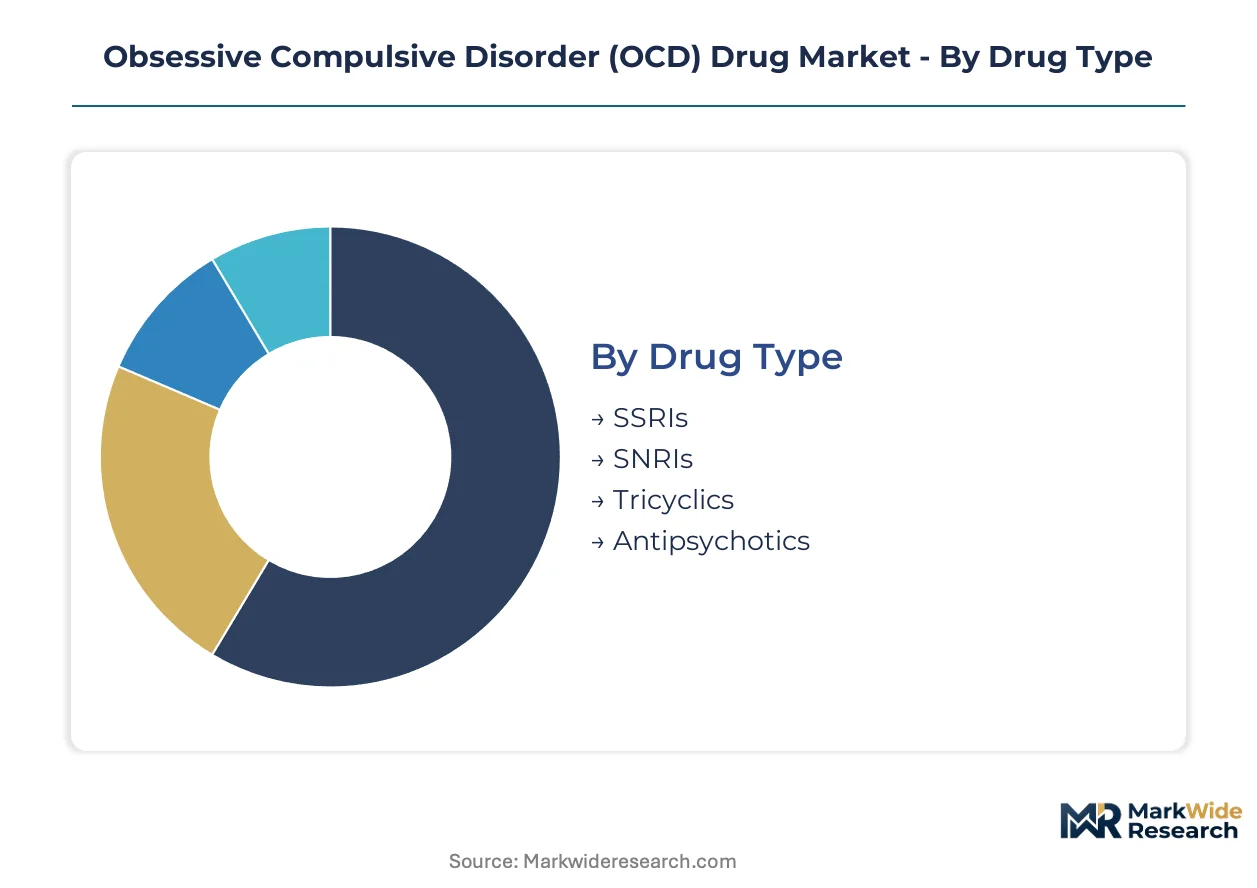
OCD drug segmentation reveals how regulatory pathways and clinical settings fragment commercial opportunity. Each dimension—molecular mechanism, delivery format, care setting, and therapeutic protocol—carries distinct FDA and EMA requirements that shape development economics and prescriber access.
Drug Type:
FDA's CNS division applies differentiated safety thresholds across mechanistic classes, with pediatric OCD indications triggering enhanced pharmacovigilance mandates for novel targets.
- SSRIs:First-line serotonergic agents dominate prescribing volume through established fluoxetine and sertraline protocols. German psychiatrists and Nordic specialists anchor demand for branded escitalopram formulations, though generic commoditization compresses margins across retail pharmacy channels.
- Antipsychotics:Aripiprazole and risperidone adjuncts address treatment-resistant populations through dopamine-serotonin modulation. United States specialty psychiatric clinics drive off-label utilization, with depot formulations gaining traction for adherence-challenged severe cases.
- SNRIs:Venlafaxine and duloxetine variants offer noradrenergic augmentation for comorbid anxiety presentations.
- Tricyclics:Clomipramine retains niche utilization in refractory cohorts despite cardiovascular monitoring requirements.
SSRIs handle the majority of throughput; antipsychotics are expanding most quickly on share as combination protocols proliferate.
Formulation:
Cost tier differentiation separates chronic oral maintenance from high-value acute interventions, with injectable formats commanding premium reimbursement through specialty pharmacy channels.
- Tablets:Immediate-release and extended-release oral solid dosages constitute the standard of care for maintenance therapy. United States commercial payers increasingly require prior authorization for branded tablet formulations, driving consolidation toward generic sertraline and fluoxetine.
- Injectable:Long-acting depot antipsychotics and investigational ketamine derivatives target severe, treatment-resistant populations. EMA centralized assessment procedures and FDA breakthrough therapy designations accelerate access for depot formulations addressing medication non-adherence.
- Capsules:Encapsulated SSRIs and SNRIs offer formulation flexibility for titration protocols.
- Liquid:Oral suspensions serve pediatric populations and patients with swallowing difficulties per FDA pediatric investigation plan mandates.
Tablets retain dominant volume position; injectable formats are gaining share fastest as adherence-focused protocols expand.
End User:
Customer type concentration shifts toward institutional settings as reimbursement complexity and prior authorization requirements intensify.
- Clinics:United States specialty psychiatric clinics and German neuropsychiatry centers concentrate prescriber relationships for novel mechanisms. These settings integrate digital therapeutic adjuncts with pharmacotherapy, creating bundled reimbursement opportunities.
- Homecare:Direct-to-patient delivery models expand for stable maintenance patients, though DEA scheduling and state-level pharmacy regulations constrain mail-order distribution of controlled substances.
- Hospitals:Inpatient psychiatric units handle acute exacerbations and medication initiation under close monitoring.
- Pharmacies:Retail and specialty pharmacy channels fragment based on formulary tier placement and payer contracting.
Clinics command the highest value per patient; homecare is climbing the fastest as remote monitoring technologies mature.
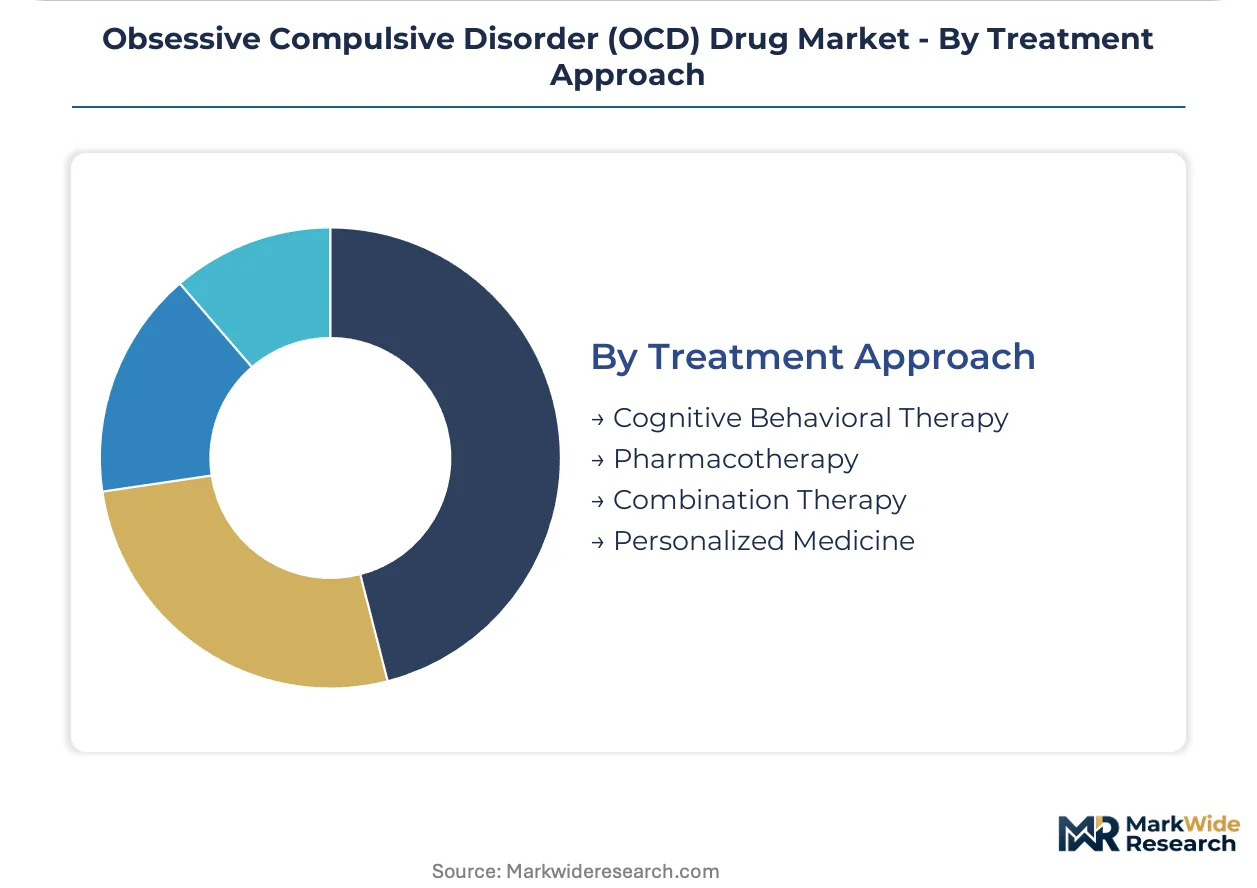
Treatment Approach:
Maturity gradients separate established pharmacotherapy from emerging personalized protocols, with regulatory frameworks lagging clinical innovation.
- Pharmacotherapy:Standalone SSRI and SNRI regimens remain the reimbursement baseline, with FDA-approved indications concentrated in adult and pediatric OCD populations. EMA essential medicines framework and WHO procurement guidelines sustain volume in lower-income health systems.
- Personalized Medicine:Pharmacogenomic stratification and biomarker-enriched prescribing gain traction through FDA guidance on neuroimaging-assisted trial designs. Academic medical centers in Germany and the United States pilot CYP450 genotyping to guide SSRI selection and dosing.
- Cognitive Behavioral Therapy:Exposure and response prevention protocols integrate with drug regimens through digital therapeutic platforms.
- Combination Therapy:Integrated pharmacotherapy and psychotherapy approaches address treatment-resistant cases per evolving clinical guidelines.
Pharmacotherapy sustains the dominant patient volume; personalized medicine shows the steepest expansion trajectory as biomarker validation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers show the least price sensitivity for novel serotonin modulators, while Indian procurement through WHO essential medicines frameworks anchors the most elastic demand tier. German psychiatrists concentrate prescribing loyalty around established European neuropsychiatry specialists. China's hospital-centric reimbursement creates intermediate elasticity, with urban tertiary centers absorbing premium therapies faster than provincial facilities.
United States
Specialty psychiatric clinics in Boston, New York, and California are expanding dedicated pharmacotherapy units for treatment-resistant OCD populations. FDA breakthrough therapy designations for glutamate-modulating agents accelerate access pathways for investigational compounds. The Cleveland Clinic and Mayo Clinic anchor clinical trial recruitment for biomarker-enriched study designs.
Germany
Lundbeck and European neuropsychiatry specialists maintain entrenched prescriber relationships with psychiatrists in Munich, Berlin, and Hamburg. EMA centralized neuropsychiatry assessment procedures harmonize market access across German federal states. The Heidelberg-Mannheim medical cluster pilots pharmacogenomic stratification for SSRI selection protocols.
India
WHO essential medicines procurement through the National Mental Health Programme sustains volume demand for generic fluoxetine and sertraline. CDSCO streamlined approval pathways for drugs with prior FDA or EMA clearance compress regulatory timelines. Mumbai and Delhi psychiatric institutes concentrate specialist capacity for refractory case management.
China
NMPA priority review vouchers for CNS drugs with high unmet need accelerate market entry for novel mechanisms. Shanghai and Beijing tertiary hospitals concentrate prescribing authority for branded OCD therapies. The Yangtze River Delta medical corridor pilots digital therapeutic adjuncts integrated with pharmacotherapy protocols.
Japan
PMDA Sakigake designation system fast-tracks innovative psychiatric drugs addressing treatment-resistant populations. Tokyo and Osaka academic medical centers anchor post-marketing surveillance for pediatric OCD indications. METI healthcare technology assessments influence reimbursement pricing for combination therapy protocols.
Obsessive Compulsive Disorder (OCD) Drug Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the OCD drug market. Large-cap pharmaceutical conglomerates with deep neuropsychiatry research infrastructure occupy the upper tier, while mid-sized CNS specialists and generic manufacturers populate the lower strata. Three archetypes dominate: serotonin modulation innovators, depot formulation specialists, and digital therapeutic integrators. Competitive moves concentrate on M&A for late-stage CNS pipelines and strategic partnerships with psychiatric clinic networks.
Within the integrated leader tier, Eli Lilly and Company and Pfizer Inc. exemplify scale-driven commercial archetypes with broad hospital and retail pharmacy channel presence. H. Lundbeck AS occupies a distinct position as a European neuropsychiatry specialist with concentrated prescriber loyalty in Nordic and German markets. These three entities represent contrasting strategic postures: Lilly anchors innovation in serotonin modulation, Pfizer leverages commercial scale across reimbursement tiers, and Lundbeck sustains regional regulatory expertise.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca |
| Eli Lilly and Company |
| Johnson & Johnson |
| Merck & Co. Inc |
| Pfizer Inc. |
| H. Lundbeck AS |
| Takeda Pharmaceutical |
| GlaxoSmithKline Plc |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough therapy designation and EMA centralized neuropsychiatry assessment procedures gate both supply qualification and price differentiation simultaneously, with accelerated regulatory pathways commanding premium reimbursement tiers while standard generic SSRI manufacturers compete on procurement efficiency through WHO essential medicines frameworks.
Pricing Analysis
After-sales revenue from long-acting depot administration services and digital therapeutic platform subscriptions drives lifetime value capture for severe OCD populations. Three-tier pricing structure across premium, standard, and economy levels separates branded glutamate modulators with biomarker stratification from established SNRIs and generic fluoxetine formulations. Pricing pressure stems from SSRI generic commoditization in retail pharmacy channels. United States commercial payers exhibit least price sensitivity for novel mechanisms, while Indian National Mental Health Programme procurement anchors the most elastic demand tier.
Supply Chain Analysis
Inventory lead times for NMDA receptor-active compounds and ketamine derivatives extend clinical trial supply planning cycles beyond standard SSRI manufacturing schedules. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing in Germany and the United States for European and North American markets. Supply chains draw from specialized CNS contract manufacturing organizations and cold-chain logistics providers for injectable depot formulations. Single-source vulnerability exists for investigational glutamate modulator precursors. Distribution runs through specialty pharmacy channels for high-cost adjuncts and hospital procurement systems for inpatient psychiatric units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA pediatric investigation plan mandates and EMA centralized assessment procedures create multi-year barriers to competitive replication.
For Market Incumbents: Fortify prescriber relationships in German neuropsychiatry centers and United States specialty psychiatric clinics through pharmacogenomic stratification services and digital therapeutic platform integration. Expand backward integration into CNS-focused contract manufacturing to secure capacity for depot formulation scale-up. Address emerging threat from glutamate-modulating biotech entrants by accelerating biomarker-enriched trial designs. For New Entrants and Emerging Players: Lead with pharmacogenomic-guided SSRI selection protocols in academic medical centers piloting CYP450 genotyping, where prescriber inertia against legacy fluoxetine protocols is weakest. Target treatment-resistant populations in United States specialty psychiatric clinics as the most penetrable segment. Deploy direct-to-clinic go-to-market models bypassing consolidated pharmacy benefit manager channels. For Investors and Strategic Acquirers: FDA guidance on digital therapeutics adjuncts reshapes the acquisition landscape toward platform-integrated pharmacotherapy developers. Five-to-ten year viability favors sponsors with late-stage glutamate modulator pipelines and established European regulatory affairs infrastructure. Target acquisition archetype: mid-cap CNS specialists with depot formulation capabilities and German prescriber network access. Monitor EMA real-world evidence acceptance rates as inflection indicator for follow-on indication economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Enriched Trial Design | FDA neuroimaging guidance enables responder subpopulation identification in heterogeneous OCD patient bases. |
| Depot Formulation Scale-Up | Long-acting injectable capacity addresses adherence challenges in severe treatment-resistant populations. |
| Digital Therapeutic Integration | App-based exposure therapy adjuncts expand addressable pools through FDA software guidance pathways. |
| Pharmacogenomic Platform Development | CYP450 genotyping services differentiate prescribing protocols in academic medical center networks. |
| Specialty Clinic Network Partnership | Bundled reimbursement opportunities emerge through United States psychiatric pharmacotherapy unit expansion. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA centralized assessment procedures, ClinicalTrials.gov entries, and formulary databases through structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient population modeling triangulates against top-down pharmaceutical revenue aggregation across the analysis window.
Segmentation dimensions modeled span drug mechanism class, formulation type, care setting intensity, treatment protocol approach, and regional regulatory cluster across the projection horizon. CAGRs derive from epidemiological prevalence projections, pricing elasticity coefficients by payer archetype, and therapy penetration assumptions for treatment-resistant cohorts. Forecast inputs incorporate FDA breakthrough therapy designation velocity and EMA pediatric investigation plan completion rates.
Forecasts assume regulatory continuity in FDA CNS division review timelines and EMA centralized neuropsychiatry assessment procedures; material policy shifts toward accelerated real-world evidence pathways or tightened pediatric safety mandates would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market