
 Medical Injection Molding Machine Market | 2026-2036
Medical Injection Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Injection Molding Machine Market Intelligence
ISO 13485 certification is bifurcating the competitive landscape into qualified suppliers and excluded entrants. ENGEL AUSTRIA GmbH leverages its all-electric platform dominance to anchor premium positioning in European medical device manufacturing. Haitian International Holdings Limited competes on manufacturing scale across Asia, while Husky Injection Molding Systems Ltd specializes in integrated hot-runner systems for high-cavity medical applications.
A medical injection molding machine is a precision clamping and injection unit designed to process medical-grade polymers within validated temperature windows, typically holding dimensional tolerances within micrometers for sterile component production. These systems serve primarily to manufacture disposable and implantable devices where material traceability and particulate control are mandatory. Electric technology leads the technology segment due to its repeatability and cleanroom compatibility, while hybrid systems represent the fastest-growing category as mid-tier manufacturers seek energy efficiency without full electric capital outlay. Within product type, syringes and IV components occupy the largest volume positions, though catheters command higher margin pools given multi-lumen complexity and silicone processing requirements.
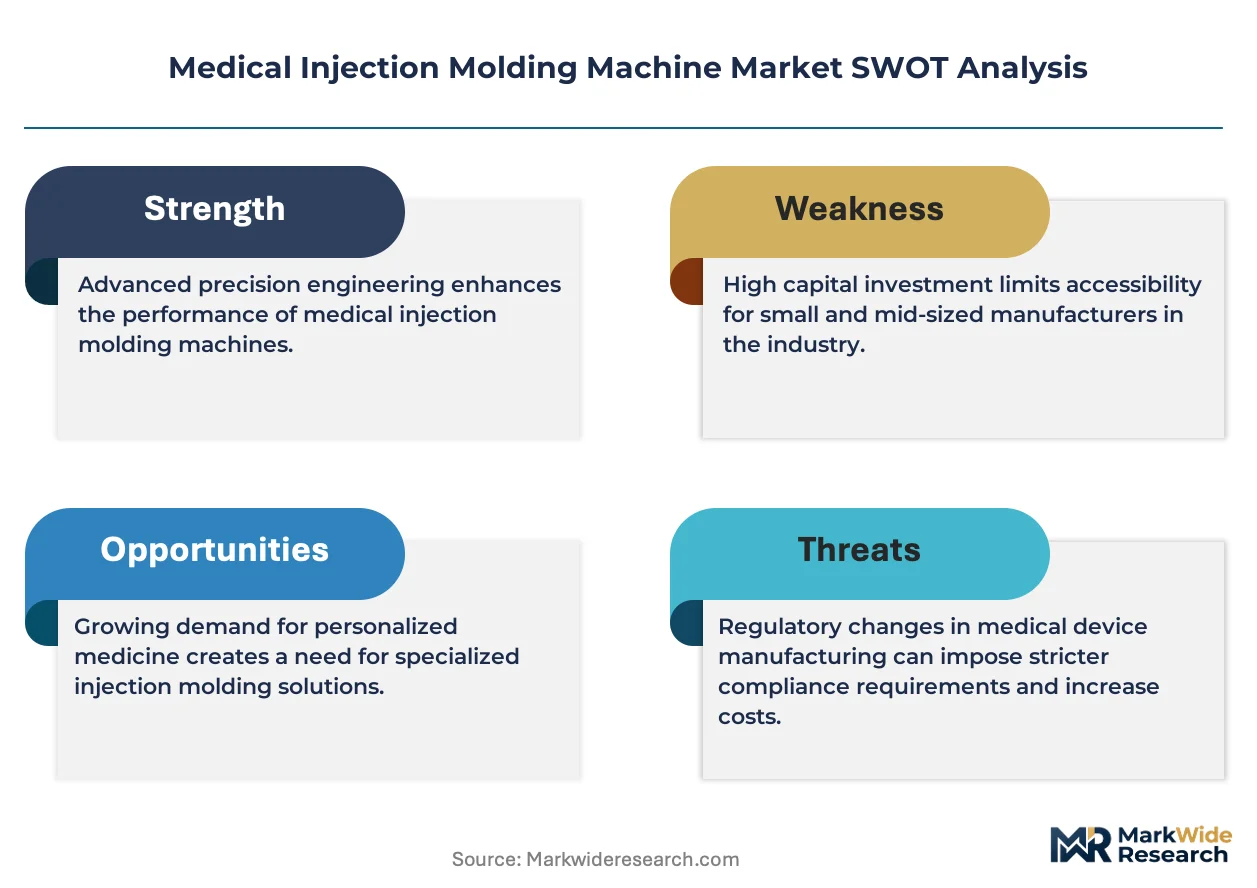
FDA 21 CFR Part 820 Quality System Regulation and EU MDR (Medical Device Regulation) impose validation protocols that directly extend machine procurement cycles and favor suppliers with documented compliance histories. The EPA and EMA jointly influence material selection through restrictions on phthalate plasticizers and sterilization residue limits, reshaping retrofit demand for compatible barrel and screw configurations. Stakeholders must monitor evolving polymer biocompatibility standards and energy efficiency benchmarks as dual criteria for capital allocation decisions.
Market Dynamics
Electric servo-hydraulic hybrid architectures are compressing the technology tiering that once separated premium European suppliers from Asian volume manufacturers, forcing recalibration of capital deployment strategies across the installed base.
Growth Catalysts
- FDA 21 CFR Part 820 validation protocols:Device manufacturers must document machine qualification for every production line changeover, extending procurement cycles and locking in supplier relationships for multi-year horizons.
- Silicone multi-lumen catheter processing:Complex drug delivery systems require specialized barrel and screw configurations that resist material degradation during extended residence times.
- German precision manufacturing clusters:Concentrated medical device OEM presence in Baden-Württemberg and Bavaria sustains localized demand for all-electric platforms with documented cleanroom compatibility.
Market Restraints
- Medical-grade polymer feedstock concentration:Specialty resin supply chains cluster among three dominant chemical conglomerates, exposing molders to allocation risk during capacity constraints.
- ISO 13485 certification timeline:The 12-18 month qualification window for new machine suppliers excludes emergent entrants from active tender processes.
- Phthalate plasticizer substitution costs:EPA and EMA restrictions on DEHP in IV components force capital-intensive screw and barrel retrofits for legacy hydraulic equipment.
Strategic Opportunities
- India CDSCO medical device rules:Domestic production incentives for syringes and diagnostic consumables create first-mover positioning for suppliers establishing local assembly.
- Connected machine platforms:Integration of injection process monitoring with MES systems enables predictive maintenance contracts that capture lifetime value beyond initial equipment sales.
- Bioresorbable polymer processing:PLA and PGA formulations for implantable scaffolds demand temperature control precision that electric machines uniquely deliver.
Industry Challenges
- Validation engineering talent scarcity:Qualified professionals capable of executing IQ/OQ/PQ documentation for FDA submissions command premium compensation that strains mid-tier manufacturer margins.
- Legacy hydraulic fleet integration:Retrofitting existing machines for EU MDR traceability requirements demands software architecture upgrades that conflict with obsolete control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Injection Molding Machine Market |
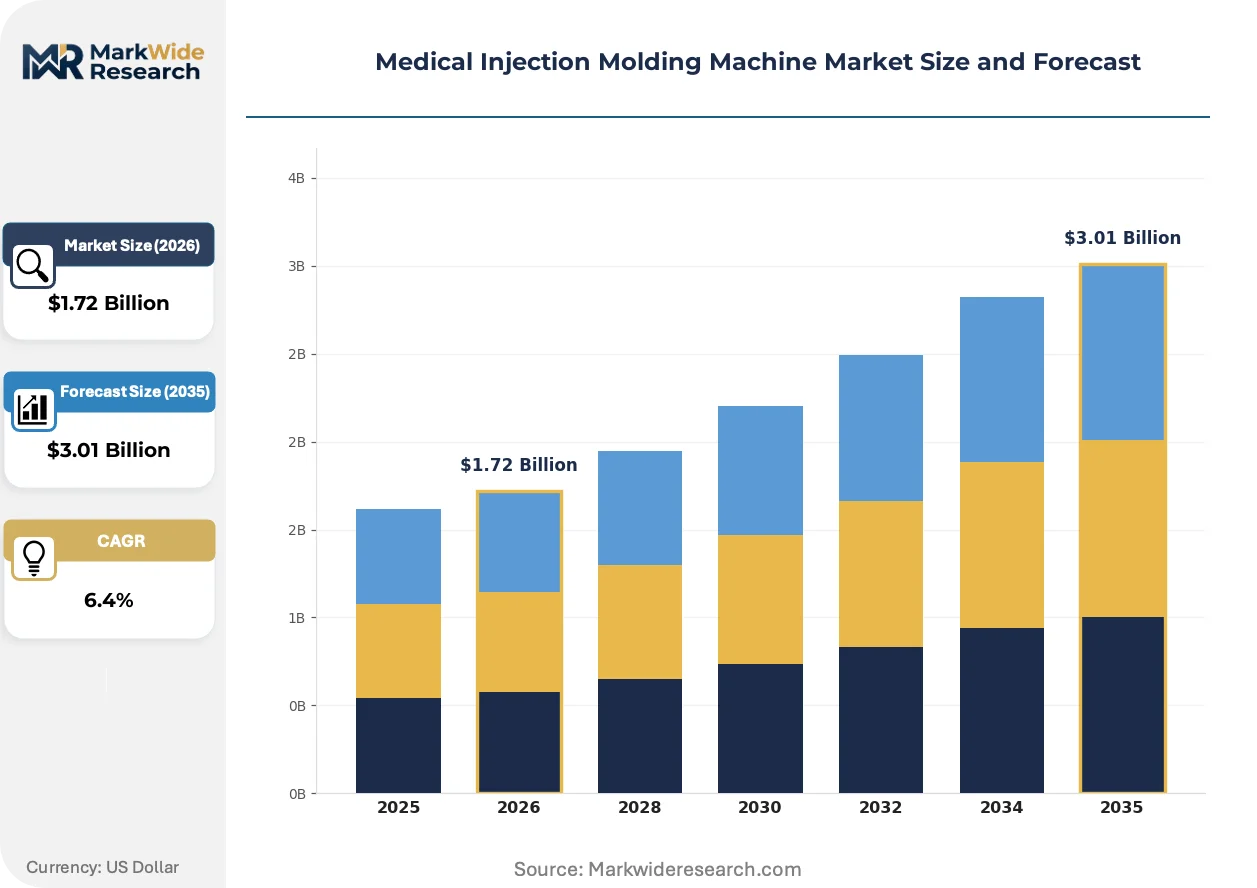
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, IV Components, Catheters, Surgical Instruments Technology: Electric, Hydraulic, Hybrid, Pneumatic End User: Hospitals, Clinics, Pharmaceutical Companies, Contract Manufacturers Application: Drug Delivery, Diagnostics, Surgery, Research |
| Companies Covered | Arburg GmbH + Co KG, Haitian International Holdings Limited, Sumitomo Heavy Industries Ltd., ENGEL AUSTRIA GmbH, KraussMaffei Group, Husky Injection Molding Systems Ltd, Nissei Plastic Industrial Co., Limited, The Japan Steel Works Ltd., Wittmann Battenfeld, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Injection Molding Machine Market Strategic Shifts & Innovations
Digital thread implementation across the molding workflow is collapsing the information latency between design iteration and production validation, compressing development timelines for complex device geometries.
Multi-component overmolding with liquid silicone rubber is fragmenting the traditional single-material paradigm that dominated disposable device manufacturing for decades. Cardiovascular device OEMs in Switzerland and Massachusetts are adopting these platforms to integrate soft-tissue interfaces with rigid structural elements in single-cycle production. The capability spread is fragmenting supplier tiers, as regional molders without LSR expertise lose access to high-margin catheter and implant contracts.
EMA's tightened sterilization residue limits under the EU MDR are forcing material qualification protocols that extend machine validation timelines by 40-60 percent for new polymer introductions. Steam and gamma sterilization compatibility now gates material selection before mold design begins, reshaping R&D roadmaps for drug delivery system manufacturers. German and Irish contract manufacturers are responding by consolidating supplier relationships with resin houses that pre-validate medical grades against the revised Annex I requirements.
Service contract unbundling is displacing the traditional bundled maintenance model that dominated capital equipment procurement for two decades. Large pharmaceutical device manufacturers in the United States now separate process optimization consulting from spare parts and field service, awarding these elements to distinct specialized providers. The disintermediation is most pronounced among diabetes care and auto-injector producers seeking to internalize process expertise while outsourcing commodity maintenance functions.
Medical Injection Molding Machine Market Segmentation
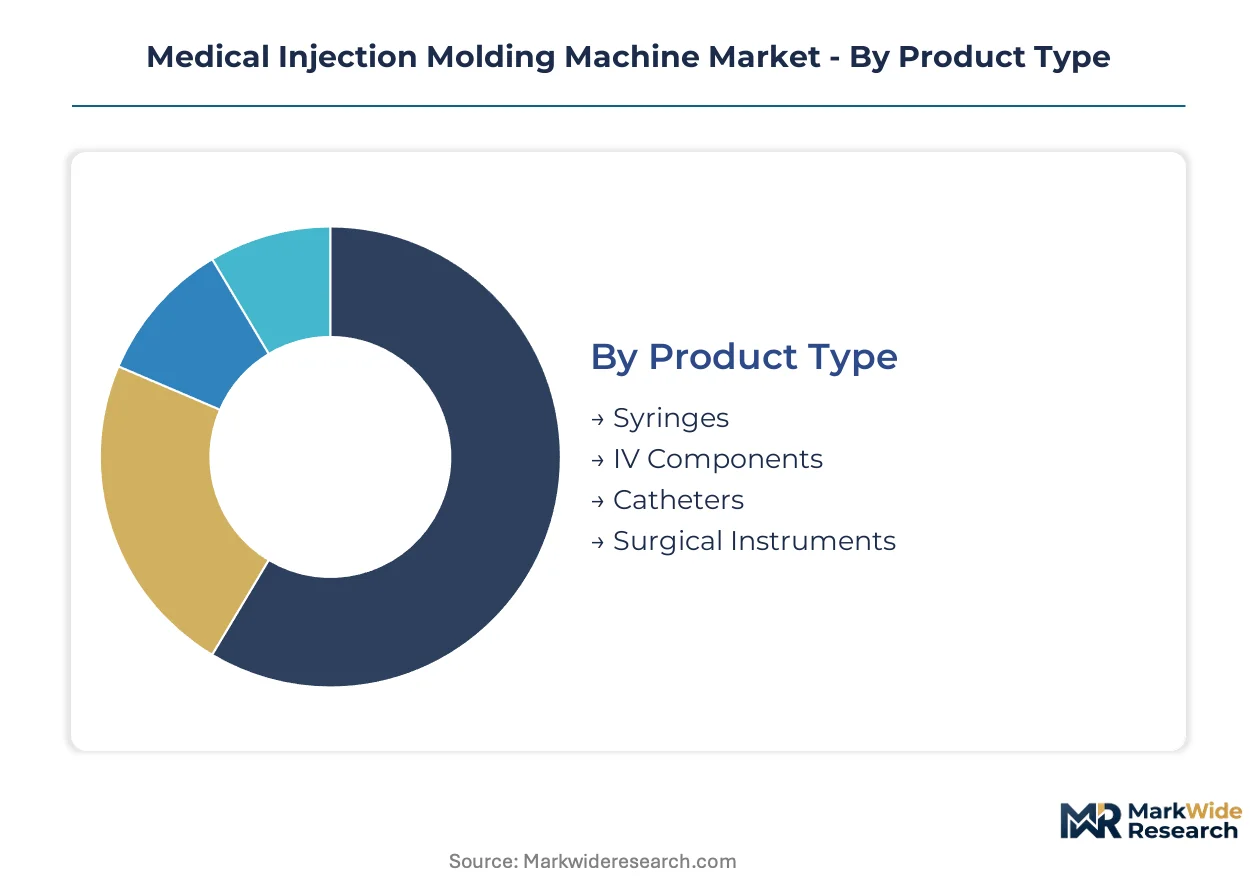
Medical injection molding machines serve heterogeneous demand profiles across sterile consumables, implantable devices, and diagnostic platforms. Segmentation reveals where capital deployment concentrates and which technology configurations command procurement priority under evolving FDA and EMA validation protocols.
Product Type:
Margin pools concentrate in multi-cavity, multi-material applications where tooling complexity and polymer traceability requirements sustain premium pricing.
- Catheters:Multi-lumen silicone processing demands specialized barrel and screw geometries that resist material degradation during extended residence times. Swiss and Massachusetts cardiovascular OEMs drive specification intensity for integrated soft-tissue interfaces with rigid structural elements.
- Syringes:High-volume disposable production runs on all-electric platforms with documented cleanroom compatibility. German precision manufacturing clusters in Baden-Württemberg sustain localized demand for validated production lines serving pharmaceutical device tenders.
- IV Components:DEHP substitution mandates under EPA and EMA restrictions force capital-intensive retrofits for legacy hydraulic equipment.
- Surgical Instruments:Reusable and single-use variants split between stainless steel overmolding and all-polymer disposable designs.
Catheters hold installed capacity. Syringes are rotating up the share rankings.
Technology:
Cost tier stratification separates capital-intensive all-electric platforms from mid-tier hybrid alternatives and legacy hydraulic fleets facing regulatory obsolescence.
- Electric:Servo-driven clamp and injection units deliver micrometer-level repeatability with zero hydraulic oil contamination risk. Cleanroom compatibility and energy efficiency position these systems for FDA 21 CFR Part 820 validation in pharmaceutical company facilities.
- Hybrid:Electric screw drive with hydraulic clamping compresses the technology tiering between premium European suppliers and Asian volume manufacturers. Mid-tier contract manufacturers in India and China adopt these configurations to balance precision requirements against capital constraints.
- Hydraulic:Legacy installed base faces EU MDR traceability retrofit costs that conflict with obsolete control system architectures.
- Pneumatic:Limited to low-force applications in research settings and prototype molding where precision requirements remain relaxed.
Electric systems anchor pharmaceutical company procurement. Hybrid configurations are climbing the fastest among contract manufacturers.
End User:
Customer type determines validation burden intensity and supplier relationship duration, with pharmaceutical companies imposing the most extensive qualification protocols.
- Pharmaceutical Companies:Internal device manufacturing operations demand documented machine qualification for every production line changeover, extending procurement cycles and locking in multi-year supplier relationships. FDA submission requirements drive preference for vendors with established IQ/OQ/PQ documentation libraries.
- Contract Manufacturers:Irish and German medical device contractors consolidate supplier relationships with resin houses that pre-validate medical grades against revised EU MDR Annex I requirements.
- Hospitals:Limited direct procurement concentrates on point-of-care diagnostic device production in academic medical center settings.
- Clinics:Minimal capital equipment ownership; indirect exposure through contract manufacturer supply chains.
Pharmaceutical companies hold installed capacity. Contract manufacturers are gaining share fastest as OEMs outsource sterile component production.
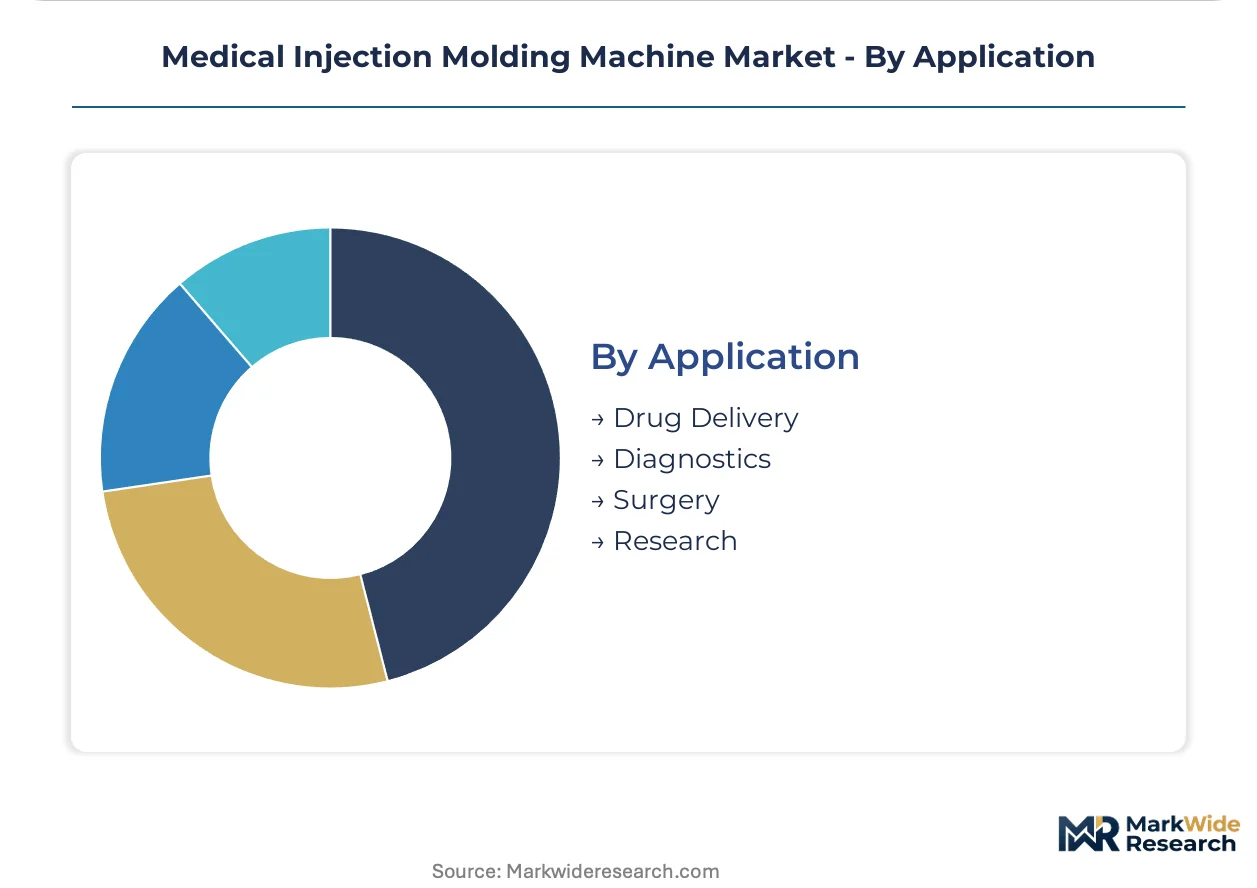
Application:
Volume concentration in drug delivery contrasts with margin intensity in surgical applications where bioresorbable polymer processing creates technology barriers.
- Drug Delivery:Auto-injectors, pen injectors, and inhalation devices require tight dimensional tolerances for dose accuracy. Diabetes care producers in the United States unbundle service contracts to internalize process optimization while outsourcing commodity maintenance.
- Surgery:Implantable scaffolds from PLA and PGA formulations demand temperature control precision that electric machines uniquely deliver. EMA sterilization residue limits extend validation timelines for new polymer introductions.
- Diagnostics:PCR consumables and microfluidic cartridges scale through high-cavity tooling with integrated hot-runner systems.
- Research:Low-volume prototyping and clinical trial material production tolerates broader machine specifications.
Drug delivery holds installed capacity. Surgery is expanding most quickly on bioresorbable material adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors German polymer import flows for medical-grade resin processing. German precision manufacturing clusters in Baden-Württemberg and Bavaria sustain localized demand for validated all-electric production lines.
United States
Diabetes care and auto-injector producers in Massachusetts and Minnesota drive specification intensity for tight dimensional tolerances. FDA 21 CFR Part 820 validation protocols extend procurement cycles for pharmaceutical device tenders. Greater Boston's cardiovascular OEM concentration demands integrated soft-tissue interface molding capabilities.
Germany
Multi-lumen silicone catheter processing for drug delivery systems requires specialized barrel geometries that resist material degradation. EMA sterilization residue limits under EU MDR reshape R&D roadmaps for contract manufacturers. Baden-Württemberg's medical device OEM density sustains premium positioning for cleanroom-compatible platforms.
China
Domestic syringe and diagnostic consumable production scales through mid-tier hybrid configurations balancing precision against capital constraints. NMPA medical device registration rules tighten traceability requirements for sterile component exports. Yangtze River Delta molding clusters adopt connected machine platforms for predictive maintenance integration.
Switzerland
Cardiovascular device manufacturers in the Lake Geneva region adopt multi-component liquid silicone rubber overmolding for soft-tissue interfaces. Swissmedic pre-market notification timelines align with extended machine qualification protocols. Zürich's precision engineering ecosystem concentrates bioresorbable polymer processing expertise for implantable scaffolds.
India
CDSCO medical device rules create first-mover positioning for suppliers establishing local assembly for syringes and diagnostic consumables. Domestic production incentives accelerate contract manufacturer capacity expansion. Maharashtra and Gujarat pharmaceutical zones concentrate demand for validated cleanroom production lines.
Medical Injection Molding Machine Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and certification depth. The supplier base stratifies into three tiers: premium European platforms with documented FDA validation libraries, Asian volume manufacturers scaling through hybrid architectures, and specialized hot-runner integrators. Competitive moves concentrate on M&A for regional service networks and strategic partnerships for resin pre-validation against evolving EMA Annex I requirements.
Within the premium-tier vector, ENGEL AUSTRIA GmbH and KraussMaffei Group exemplify European platform dominance anchored in validated cleanroom compatibility. Haitian International Holdings Limited occupies a position among scale-driven Asian manufacturers competing on manufacturing footprint across India and China. Husky Injection Molding Systems Ltd represents the specialized integrator archetype, with Sumitomo Heavy Industries Ltd. and Nissei Plastic Industrial Co., Limited sitting within the precision machinery tier serving multi-cavity medical applications.
| Leading Market Players |
|---|
| Arburg GmbH + Co KG |
| Haitian International Holdings Limited |
| Sumitomo Heavy Industries Ltd. |
| ENGEL AUSTRIA GmbH |
| KraussMaffei Group |
| Husky Injection Molding Systems Ltd |
| Nissei Plastic Industrial Co., Limited |
| The Japan Steel Works Ltd. |
| Wittmann Battenfeld |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, bifurcating the competitive landscape into premium-validated European platforms and cost-optimized Asian alternatives. Pharmaceutical device manufacturers absorb extended procurement cycles and validation costs that compress margin pools for mid-tier contract manufacturers lacking documented compliance histories.
Pricing Analysis
Volume-discount tiering structures separate all-electric platforms with FDA-validated documentation libraries from hybrid configurations serving mid-tier Asian contract manufacturers. Price differentiation centers on certification grade—ISO 13485 plus FDA 21 CFR Part 820 validation commands substantial premiums—and after-sales service bundling, with unbundled maintenance contracts eroding traditional bundled pricing. Pricing pressure stems from hybrid architecture adoption compressing technology tiering between premium European and volume Asian suppliers. Contract manufacturers in India and China exhibit highest price sensitivity; pharmaceutical companies with locked-in validation protocols show lowest.
Supply Chain Analysis
Specialty medical-grade polymer feedstock concentration among German, American, and Japanese chemical conglomerates creates allocation vulnerability during capacity constraints. Barrel and screw configurations for silicone multi-lumen catheter processing draw from precision-machined component suppliers clustered in Switzerland and Germany. Single-source vulnerability runs through resin pre-validation partnerships with EMA-compliant houses. Distribution runs through regional service networks anchored by Hamburg's polymer import flows and Yangtze River Delta molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified validation engineering talent capable of executing IQ/OQ/PQ documentation for FDA submissions commands premium compensation that strains mid-tier manufacturer margins, creating structural capability scarcity across the supplier base.
For Market Incumbents: Secure resin pre-validation partnerships with EMA-compliant houses before Annex I requirements tighten further. Deepen backward integration into barrel and screw manufacturing for silicone processing configurations to defend against Asian hybrid platform encroachment. Consolidate regional service networks through selective M&A in India and China where CDSCO rules accelerate domestic production incentives. For New Entrants and Emerging Players: Predictive maintenance software integration with MES systems represents an underserved service layer where incumbents rely on legacy field service models. Target contract manufacturers in Maharashtra and Gujarat pharmaceutical zones seeking validated cleanroom production lines without full electric capital outlay. Lead with connected machine platforms offering subscription-based process optimization consulting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid machine architectures as manufacturing scale economies compress unit economics. Long-term viability favors precision machinery specialists with documented FDA validation libraries over undifferentiated hydraulic fleet operators. Watch bioresorbable polymer processing adoption rates as inflection indicator for electric platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Pre-Validation Partnership | EMA Annex I compliance accelerates machine qualification timelines for drug delivery system manufacturers. |
| Connected Machine Platform Launch | MES integration enables predictive maintenance contracts capturing lifetime value beyond initial equipment sales. |
| Regional Service Network Expansion | CDSCO medical device rules in India create first-mover positioning for localized assembly and support. |
| Bioresorbable Processing Capability Investment | PLA and PGA scaffold demand requires temperature control precision that electric machines uniquely deliver. |
| Hybrid Architecture Manufacturing Scale-Up | Mid-tier contract manufacturers in Asia balance precision requirements against capital constraints. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with biomedical engineers, GPO contracts managers, pharmaceutical device procurement leads, and aftermarket service heads. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, hospital procurement contract repositories, and customs trade records for medical-grade polymer flows. Bottom-up installed base estimates triangulated against top-down pharmaceutical capital expenditure disclosures.
Across the analysis window, forecasts modeled technology segment splits, product type volume intensity, end-user validation burden tiers, and geographic regulatory cluster differentiation. CAGRs derived from polynomial trend fitting against historical pharmaceutical device production indices and polymer processing energy efficiency benchmarks. Silicone multi-lumen catheter capacity expansion and bioresorbable polymer adoption curves served as industry-specific demand drivers.
Underlying assumptions cover sustained FDA 21 CFR Part 820 enforcement intensity and EMA sterilization residue limit stability, with deviation risk concentrated in phthalate plasticizer substitution timeline acceleration and hybrid platform technology leapfrogging. Practitioners should keep alternative scenarios live as EU MDR traceability retrofit cost burdens and India CDSCO domestic production incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Arthroscopy Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Eye Socket Implants Market