
 Advanced Parenteral Drug Market | 2026-2036
Advanced Parenteral Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Parenteral Drug Market Intelligence
A preference for single-source qualified suppliers for complex biologics is hardening supply chain relationships. Pfizer leverages its extensive manufacturing scale to offer a broad portfolio of injectable solutions. Amgen specializes in novel biologic therapies, particularly for autoimmune conditions and oncology. Hoffmann-La Roche differentiates through its dedicated focus on personalized medicine and companion diagnostics for its parenteral drugs.
Advanced parenteral drugs are sterile preparations administered by injection, bypassing the gastrointestinal tract. These formulations, such as lyophilized powders, often require reconstitution and are designed for precise dosing and rapid bioavailability. Within therapy areas, oncology applications command the largest share due to the high volume of biologic treatments. Prefilled syringes represent the fastest-growing delivery technology, driven by the shift towards self-administration and reduced medication errors in hospitals.
Regulatory oversight from bodies like the US FDA, the European EMA, and China's NMPA dictates stringent standards for product sterility, stability, and manufacturing practices. These regulations directly influence market access and require extensive clinical data for drug approval. Navigating the evolving requirements for combination products, where the drug and delivery device are integrated, will be critical for future product strategy.
Market Dynamics
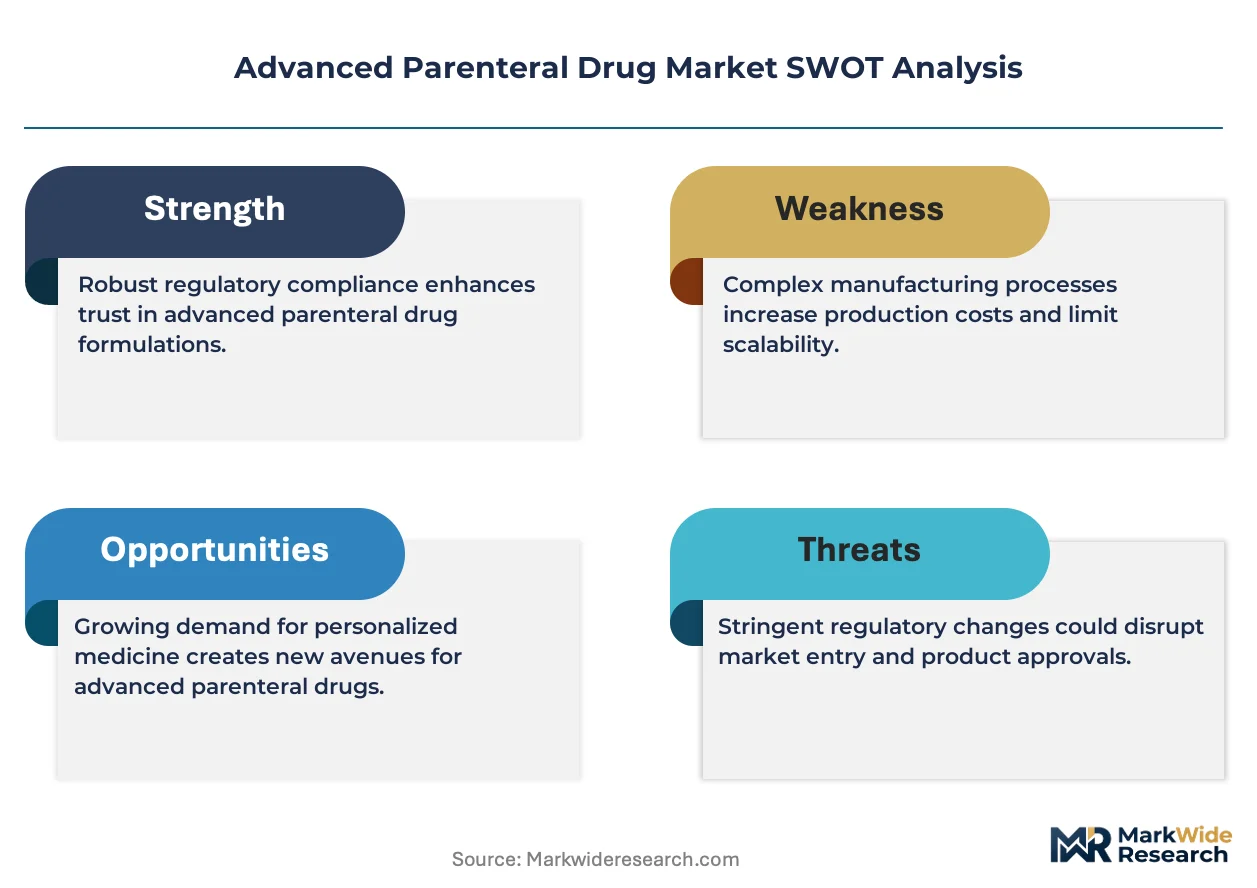
The convergence of complex biologic drug substances with sophisticated delivery devices defines the market's central dynamic. This integration creates new manufacturing complexities and regulatory pathways, particularly for combination products like autoinjectors, forcing a tighter coupling between pharmaceutical formulation and device engineering.
Growth Catalysts
- Innovations in Drug Delivery:Prefilled syringes and autoinjectors are enhancing patient safety by reducing dosing errors and enabling self-administration for chronic conditions, driving their adoption in home care settings.
- Oncology Therapy Expansion:The high volume of biologic treatments for various cancers, which require parenteral administration for optimal bioavailability, continues to stimulate new product development and market expansion.
- Favorable Regulatory Designations:Incentives such as the Orphan Drug Act in the United States encourage development of parenteral drugs for rare diseases, creating new, targeted therapeutic categories.
Market Restraints
- Manufacturing Complexity:Lyophilized powders and other complex formulations require specialized, capital-intensive sterile manufacturing capabilities, creating high barriers to entry and increasing production costs.
- Stringent Regulatory Hurdles:Navigating the rigorous and lengthy approval processes for combination products, as enforced by the FDA and EMA, delays market entry and increases development expenses. -
- Supply Chain Vulnerability:A dependency on a limited number of qualified suppliers for critical components, such as specialized glass vials or device parts, exposes manufacturers to significant disruption risks.
Strategic Opportunities
- Self-Administration Devices:Developing smart injectors and on-body delivery systems with digital connectivity offers opportunities to improve patient adherence and provide real-world data for healthcare providers.
- Emerging Market Penetration:Expanding into geographies like Brazil and China, where healthcare spending and infrastructure are improving, presents a significant opportunity for market growth.
- Novel Therapeutic Modalities:Applying advanced parenteral formulation and delivery technologies to emerging fields like cell and gene therapy can open new, high-value market segments.
Industry Challenges
- Specialized Talent Scarcity:The industry faces a shortage of personnel with expertise in aseptic processing, quality control for biologics, and the specific regulatory affairs concerning combination products.
- Regulatory Harmonization Gaps:Discrepancies in compliance requirements for drug-device combination products between the US FDA, European EMA, and China's NMPA complicate global product launch strategies.
- High Capital Investment:The significant capital expenditure needed to construct and validate cGMP-compliant sterile manufacturing facilities poses a substantial financial challenge for new entrants and smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Parenteral Drug Market |
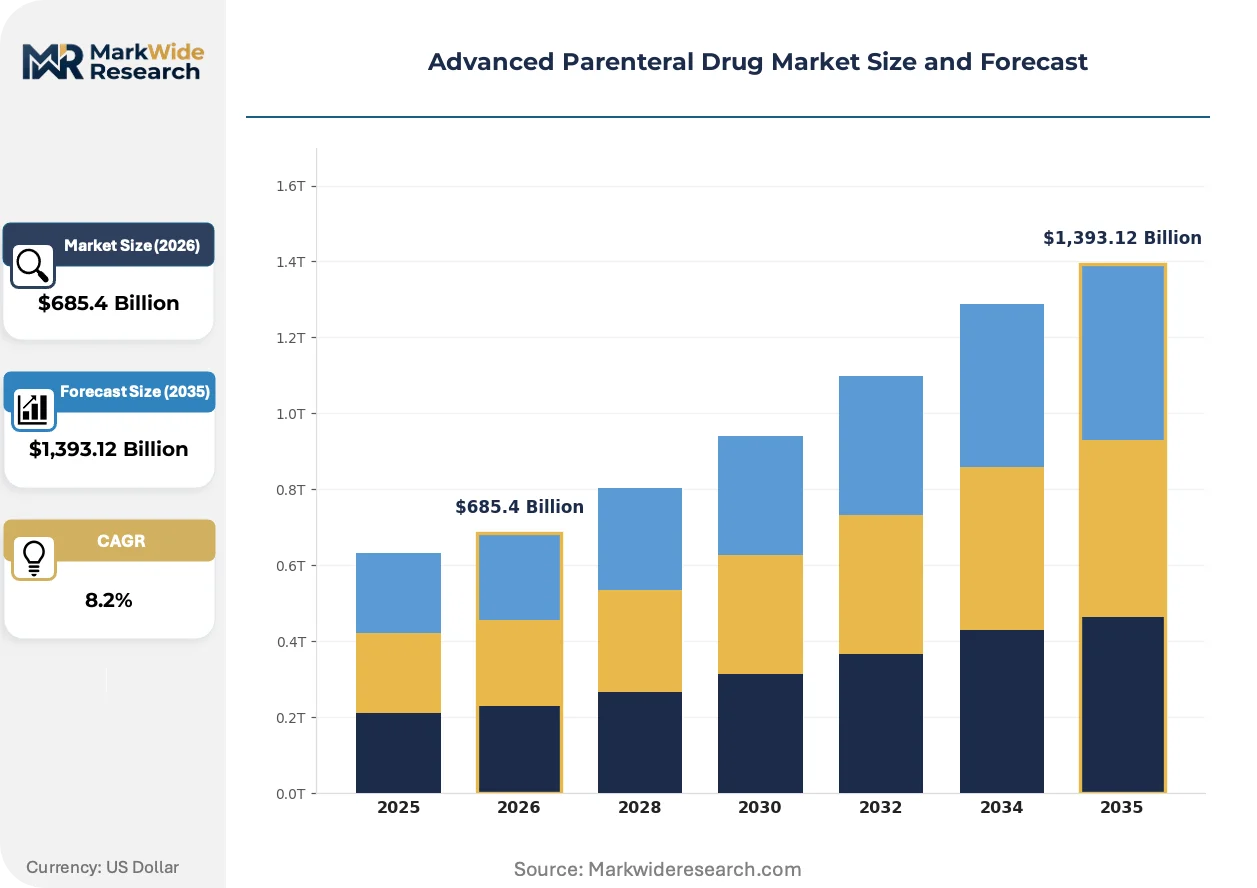
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,393.12 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solutions, Injectable Suspensions, Emulsions, Lyophilized Powders Therapy Area: Oncology, Cardiovascular Disorders, Infectious Diseases, Autoimmune Conditions Care Setting: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Diagnostic Laboratories Delivery Technology: Prefilled Syringes, Vials, Infusion Pumps, Disposable Needles |
| Companies Covered | Hoffmann-La Roche, Baxter International, Abbott Laboratories, Boston Scientific, Becton Dickinson, Amgen, AstraZeneca, Novartis, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Parenteral Drug Market Strategic Shifts & Innovations
A fundamental shift toward patient-centric care is redefining the market, elevating the importance of the delivery system to equal that of the drug itself. This focus influences everything from formulation science to regulatory strategy, with an emphasis on safety, convenience, and adherence.
Prefilled syringes provide a platform for safe and accurate dosing of injectable medicines. Biopharmaceutical companies and hospitals are rapidly adopting these systems to minimize medication errors and streamline administration. This delivery technology is expanding into more complex, high-viscosity biologic drugs for chronic conditions, which were previously difficult to administer outside a clinical setting.
New guidance from regulatory bodies like the US FDA and the European EMA is reshaping the development of combination products. These evolving rules demand more extensive human factors testing and device-specific data, treating the delivery system as an integral part of the therapeutic approval. Oncology and autoimmune drug developers are most impacted, now integrating device engineering into early-stage pharmaceutical R&D to ensure compliance.
A preference for consolidated purchasing is altering procurement patterns for high-value biologics. Large hospital networks and specialized treatment centers are moving away from fragmented sourcing to establish long-term partnerships with manufacturers who can guarantee supply chain integrity for critical parenteral drugs. This demand for single-source qualified suppliers is most visible in advanced oncology clinics across the United States and Germany.
Advanced Parenteral Drug Market Segmentation
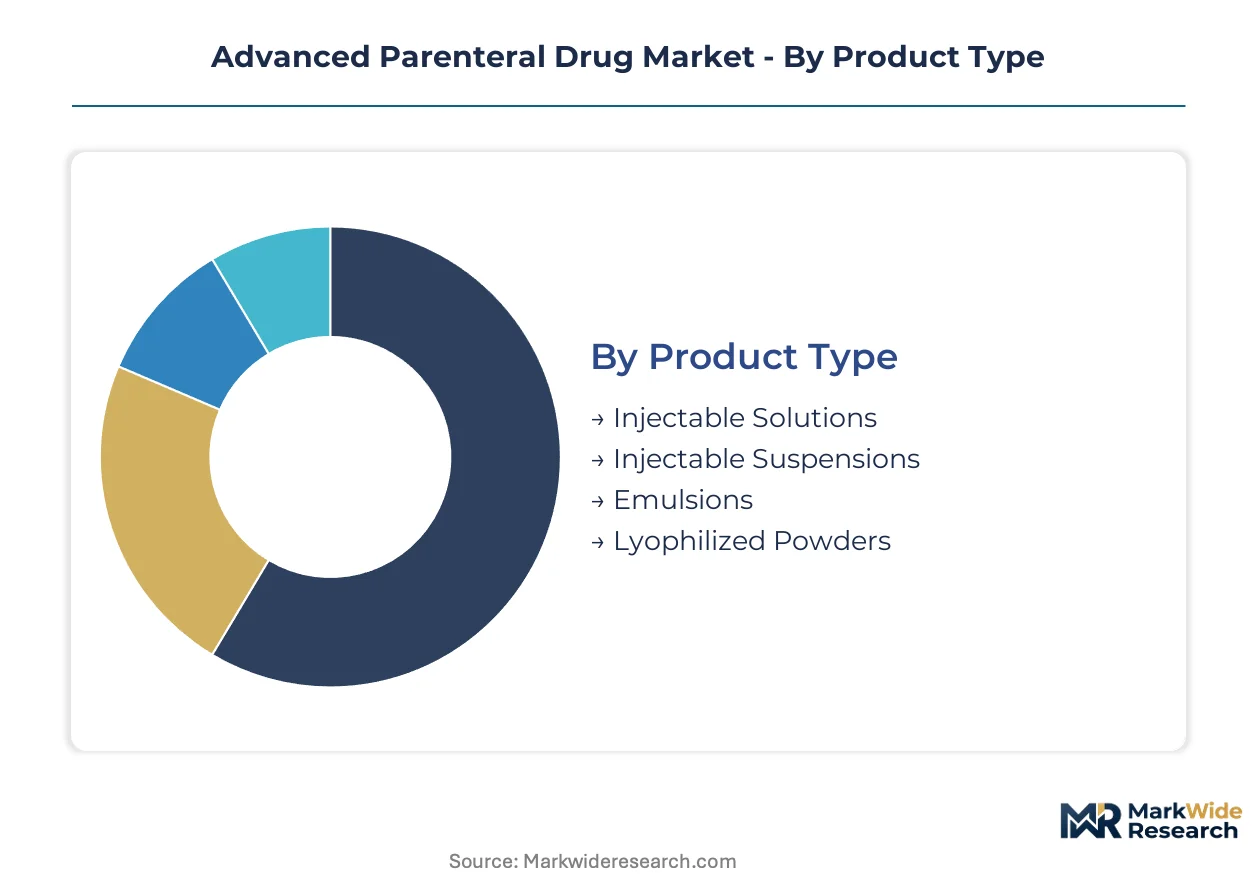
The Advanced Parenteral Drug Market segmentation highlights distinct product forms, therapeutic applications, care delivery models, and administration technologies. Understanding these categories reveals specific regulatory challenges and commercial opportunities across the complex pharmaceutical landscape. Each segment demands tailored manufacturing processes and distribution strategies.
Product Type:
Regulatory bodies like the US FDA and European EMA impose distinct approval pathways for different parenteral product types, especially concerning sterility and stability.
- Lyophilized Powders:These formulations require specialized freeze-drying processes to ensure drug stability and extended shelf life. Demand for lyophilized powders concentrates in oncology treatment centers, where complex biologic therapies often necessitate reconstitution at the point of care.
- Injectable Solutions:These sterile liquid preparations are directly administered, offering precise dosing and rapid bioavailability. Hospitals and clinics across Germany and the United States frequently use injectable solutions for immediate therapeutic effect in critical care settings.
- Injectable Suspensions:These formulations contain finely divided drug particles suspended in a liquid medium, suitable for sustained release applications.
- Emulsions:Comprising immiscible liquids dispersed as droplets, emulsions deliver poorly soluble drugs with enhanced absorption profiles.
Injectable Solutions sits at the top of the volume ranking, with Lyophilized Powders climbing the fastest.
Therapy Area:
Market value in therapy areas is heavily influenced by the prevalence of chronic diseases and the development of high-cost biologic treatments.
- Oncology:This therapy area commands the largest market share due to the high volume of biologic treatments for various cancers. Specialized cancer treatment centers in the United States and Germany drive demand for advanced parenteral oncology drugs.
- Autoimmune Conditions:Amgen specializes in novel biologic therapies for autoimmune conditions, often requiring chronic parenteral administration. Patient preference for self-administration devices influences product development in this segment.
- Cardiovascular Disorders:Parenteral drugs for cardiovascular disorders address acute cardiac events and chronic conditions, requiring rapid and controlled drug delivery.
- Infectious Diseases:Advanced parenteral formulations provide critical treatment options for severe infectious diseases, particularly in hospital settings.
The oncology segment consistently generates the highest revenue, while autoimmune conditions show significant expansion.
Care Setting:
Procurement patterns for advanced parenteral drugs vary significantly across different care settings, reflecting diverse operational needs and patient populations.
- Hospitals:Hospitals represent the largest care setting segment, driven by high-volume patient admissions and complex treatment regimens. Large hospital networks in the United States prioritize suppliers who can guarantee supply chain integrity for critical parenteral drugs.
- Specialty Clinics:These centers, particularly cancer treatment facilities, show concentrated demand for advanced biologic therapies. Specialized clinics in Germany often adopt innovative delivery technologies like autoinjectors for patient convenience.
- Ambulatory Surgery Centers:These facilities use parenteral drugs for anesthesia, pain management, and short-procedure interventions, emphasizing efficiency and rapid patient turnover.
- Diagnostic Laboratories:Parenteral drugs find application in diagnostic procedures, primarily for imaging agents and functional tests requiring precise administration.
Hospitals maintain the dominant share of parenteral drug consumption, with Specialty Clinics demonstrating robust growth in high-value biologics.
Delivery Technology:
The maturity of delivery technologies ranges from established vial systems to innovative self-administration devices, impacting patient convenience and market adoption.
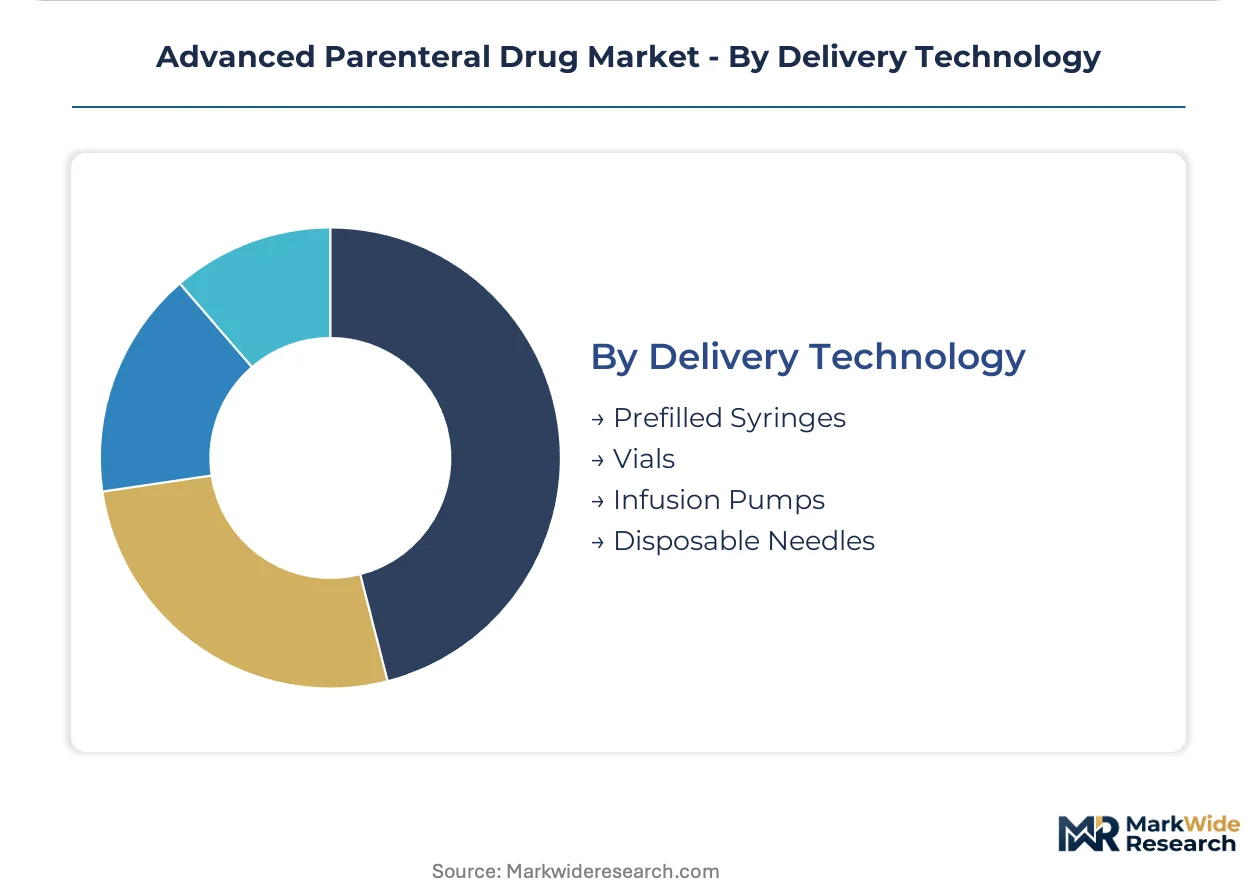
- Prefilled Syringes:These systems provide safe and accurate dosing, minimizing medication errors and streamlining administration. The shift towards home care settings drives adoption of prefilled syringes for chronic conditions.
- Vials:Traditional glass vials remain a foundational delivery method for many parenteral drugs, particularly for multi-dose applications in clinical environments. Pharmaceutical companies maintain extensive manufacturing capabilities for vial-based products.
- Infusion Pumps:These devices enable controlled and continuous administration of parenteral drugs, crucial for critical care and long-term therapies.
- Disposable Needles:Essential components in parenteral drug administration, disposable needles ensure sterility and patient safety across all care settings.
Prefilled Syringes are expanding most quickly, while Vials continue to hold the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cancer treatment centers across the United States and Germany drive the demand for advanced parenteral drugs. These regions exhibit robust healthcare infrastructure and high adoption rates for innovative biologic therapies. Regulatory bodies like the US FDA and European EMA shape market access and product development. Emerging markets such as China and Brazil also present significant growth opportunities.
United States
The United States market sees strong demand for oncology biologics and self-administration devices. The US FDA enforces stringent standards for product sterility, stability, and manufacturing practices. Major pharmaceutical clusters in the Northeast and California concentrate R&D and specialized manufacturing capabilities for parenteral drugs.
Germany
Germany demonstrates high consumption of advanced biologic therapies, often requiring parenteral administration. The European EMA's rigorous approval processes guide market entry for complex combination products. Specialized clinics in Bavaria and North Rhine-Westphalia are early adopters of innovative delivery technologies like autoinjectors.
China
Market expansion in China is fueled by improving healthcare spending and an increasing patient base for chronic conditions. China's NMPA dictates stringent standards for drug approval and manufacturing practices. Pharmaceutical manufacturing hubs in the Yangtze River Delta are developing advanced parenteral drug production capabilities.
Japan
Japan's advanced healthcare system drives demand for high-value parenteral drugs, particularly for an aging population. The PMDA ensures strict quality control and efficient approval pathways for novel biologic therapies. Research and development centers in Tokyo and Osaka focus on personalized medicine applications.
Brazil
Brazil represents a significant growth opportunity due to expanding healthcare access and a rising prevalence of chronic diseases. ANVISA oversees the registration and post-market surveillance of all parenteral drug products. Pharmaceutical production facilities near São Paulo are increasing local manufacturing capacity.
Advanced Parenteral Drug Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and specialized therapeutic focus. The market structure is characterized by a mix of large pharmaceutical companies with extensive portfolios and specialized biotech firms focusing on niche areas. Three strategic archetypes include integrated pharmaceutical giants, novel biologic developers, and personalized medicine innovators. Companies primarily engage in strategic partnerships and portfolio diversification to maintain market position.
Within the large-scale manufacturing and specialized biologic segments, Pfizer leverages its extensive manufacturing scale to offer a broad portfolio of injectable solutions, anchoring a significant portion of the market. Amgen exemplifies a focus on novel biologic therapies, particularly for autoimmune conditions and oncology, often requiring chronic parenteral administration. Hoffmann-La Roche differentiates through its dedicated focus on personalized medicine and companion diagnostics for its parenteral drugs, representing a specialized innovator archetype that integrates device engineering into early-stage R&D.
| Leading Market Players |
|---|
| Hoffmann-La Roche |
| Baxter International |
| Abbott Laboratories |
| Boston Scientific |
| Becton Dickinson |
| Amgen |
| AstraZeneca |
| Novartis |
| Pfizer |
| Others |
Cost & Logistics Intelligence
Specialized aseptic manufacturing talent, particularly in advanced processing hubs like Germany and the United States, creates significant labor-cost differentials. These differentials directly influence the premium pricing observed for complex lyophilized powders and novel biologic injectable solutions.
Pricing Analysis
Input cost fluctuations, particularly for specialized excipients and sterile packaging components, directly impact the final pricing of advanced parenteral drugs. The dominant pricing model involves contract-based long-term offtake agreements, often incorporating value-based pricing for novel biologic therapies. Price differentiation stems from the specific FDA or EMA approval status and the level of customization required for personalized medicine applications. Pricing pressure trends upwards due to stringent manufacturing requirements, with specialized cancer treatment centers showing lower price sensitivity than general hospitals for high-value biologics.
Supply Chain Analysis
Dual-sourcing requirements for critical components, mandated by large hospital networks and pharmaceutical companies, aim to mitigate supply chain vulnerabilities for parenteral drugs. Supply concentration for advanced manufacturing capabilities resides primarily in the United States, Germany, and increasingly China. The market relies heavily on specialized glass vials and prefilled syringe components, alongside complex biologic active pharmaceutical ingredients. Single-source vulnerability for highly specialized device parts poses a structural risk, while distribution runs through direct channels to hospitals and specialized clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Parenteral Drug Market acts as a regulatory compounder, with initiatives like the US Orphan Drug Act significantly driving demand for specialized treatments. This regulatory environment fosters development in niche therapeutic areas, ensuring sustained market expansion.
For Market Incumbents: Acquire specialized aseptic manufacturing facilities to consolidate production expertise and expand global cGMP-compliant capacity. This strategy helps mitigate the threat from emerging biotech entrants with novel delivery technologies and addresses rising production costs. Incumbents must also invest in R&D for advanced combination products, leveraging their global regulatory affairs teams to navigate complex approval pathways efficiently.
For New Entrants and Emerging Players: EMA's evolving Medical Device Regulation (MDR) in Europe opens a window for new entrants focusing on sophisticated combination products like smart autoinjectors. Target under-penetrated segments within autoimmune conditions, leveraging patient preference for self-administration devices. A focused go-to-market strategy involves partnering with established hospital networks and specialized clinics to ensure efficient market access and clinical adoption.
For Investors and Strategic Acquirers: Large pharmaceutical conglomerates are the most active acquirers in this space, seeking to bolster their parenteral drug portfolios and manufacturing footprints. The market offers long-term viability, driven by sustained demand for biologics and personalized medicine over the next decade. Identify niche biotech firms with proprietary delivery technologies or specialized aseptic manufacturing capabilities as prime acquisition targets. A key signal to watch is the increasing number of FDA and EMA approvals for complex combination products.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expanding sterile manufacturing capacity addresses rising demand for oncology biologics across global markets. |
| Regulatory Approval Pathway | Navigating complex US FDA and European EMA requirements ensures timely market entry for novel combination products. |
| Pipeline Diversification | Investing in gene and cell therapies expands parenteral applications into high-value emerging therapeutic modalities. |
| Strategic Partnership | Collaborating with device manufacturers integrates advanced delivery systems into pharmaceutical R&D for patient safety. |
| Geographic Expansion | Penetrating emerging markets like Brazil and China captures new patient populations and healthcare spending growth. |
Research Approach
Bottom-up patient population and therapy area modeling reconciled against top-down manufacturing capacity and regulatory approval tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and device engineers provided qualitative insights. Secondary validation utilized FDA filings, EMA submissions, clinical trial databases, and specialized industry reports. This approach ensured comprehensive data triangulation and robust market sizing.
An input-output matrix framework underpinned the quantitative market forecasting, correlating key drivers with segment-specific growth trajectories. The analysis modeled market dynamics across product type, therapy area, care setting, delivery technology, and regional regulatory clusters over the projection horizon. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Key forecast inputs included biologic drug pipeline progression and prefilled syringe adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or significant supply chain disruptions. This study's projections reflect current market dynamics and regulatory landscapes, acknowledging that global pandemic impacts and geopolitical trade tensions represent key risk factors. Deviation in regulatory policy shifts or significant manufacturing capacity changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Urticaria Drugs Market