
 Urinary Incontinence Devices Market | 2026-2036
Urinary Incontinence Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Incontinence Devices Market Intelligence
The rising preference for home care settings is recalibrating the end-user mix away from traditional long-term care facilities. Essity Aktiebolag leverages its extensive distribution network to serve the retail and home care channels effectively. Coloplast A/S specializes in intermittent catheters and related urology products, sustaining a strong clinical reputation. Boston Scientific Corporation focuses on advanced, implantable solutions for severe incontinence, differentiating itself through technological innovation in the surgical segment.
Urinary incontinence devices are medical aids designed to manage involuntary urine leakage, utilizing materials such as medical-grade silicone for external catheters or super-absorbent polymers for pads. They function to contain urine, support pelvic organs, or occlude the urethra, thereby improving a patient's quality of life. Among product types, absorbent pads command the largest volume, though pessary devices and urethral inserts offer higher margins. The management of stress induced leakage represents the most common application, driving innovation in non-invasive solutions.
Device approval and post-market surveillance are governed by stringent frameworks, including the US FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR). These regulations mandate rigorous clinical data and risk management protocols, directly influencing development timelines and market entry costs. Stakeholder success will hinge on developing devices that balance clinical efficacy with user discretion and comfort, meeting evolving patient expectations for an active lifestyle.
Market Dynamics
The central structural force shaping the market is the regulatory tightening under frameworks like the EU's Medical Device Regulation. This pressure mandates higher standards for clinical evidence and material biocompatibility, directly influencing product development priorities and market access strategies.
Growth Catalysts
- Aging Demographics:The rapidly aging populations in developed economies, particularly in Japan and Western Europe, create a consistent and expanding user base for urinary incontinence management products.
- Product Discretion:Innovation in materials and design is leading to more discreet and comfortable devices, such as low-profile absorbent pads and soft silicone pessaries, reducing stigma and encouraging adoption.
- Home Care Expansion:A systemic shift in healthcare delivery toward home-based settings increases demand for devices that are easy for patients or non-professional caregivers to use without clinical supervision.
Market Restraints
- Reimbursement Hurdles:Inconsistent or low reimbursement rates for disposable products in many national health systems place a significant cost burden on users, limiting access and consistent use.
- Regulatory Compliance Costs:The EU's MDR and similar stringent regulations in other regions require extensive clinical data and post-market surveillance, increasing development costs and time-to-market.
- Social Stigma:Persistent social stigma associated with incontinence acts as a significant barrier, preventing individuals from seeking diagnosis and treatment, thereby suppressing overall market potential.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand exists in large, developing countries like Brazil and India, where rising healthcare expenditure and growing awareness present significant long-term growth prospects.
- Smart Device Integration:Incorporating sensor technology into pads or wearable devices to monitor leakage, track usage, and provide data to caregivers or clinicians offers a new frontier for product differentiation.
- Direct-to-Consumer Channels:Developing robust e-commerce and subscription-based models allows manufacturers to bypass traditional distribution gatekeepers and build direct relationships with end-users.
Industry Challenges
- Material Sourcing Volatility:The supply chains for key raw materials, such as super-absorbent polymers and medical-grade silicone, are subject to price fluctuations and potential disruptions.
- Clinical Education Gap:A lack of sufficient training for non-specialist healthcare providers on the full range of available device options can lead to suboptimal product recommendations for patients.
- Inter-Regulatory Navigation:Manufacturers face operational complexity in designing and documenting products to simultaneously meet the divergent requirements of the US FDA and the EU's MDR framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Incontinence Devices Market |
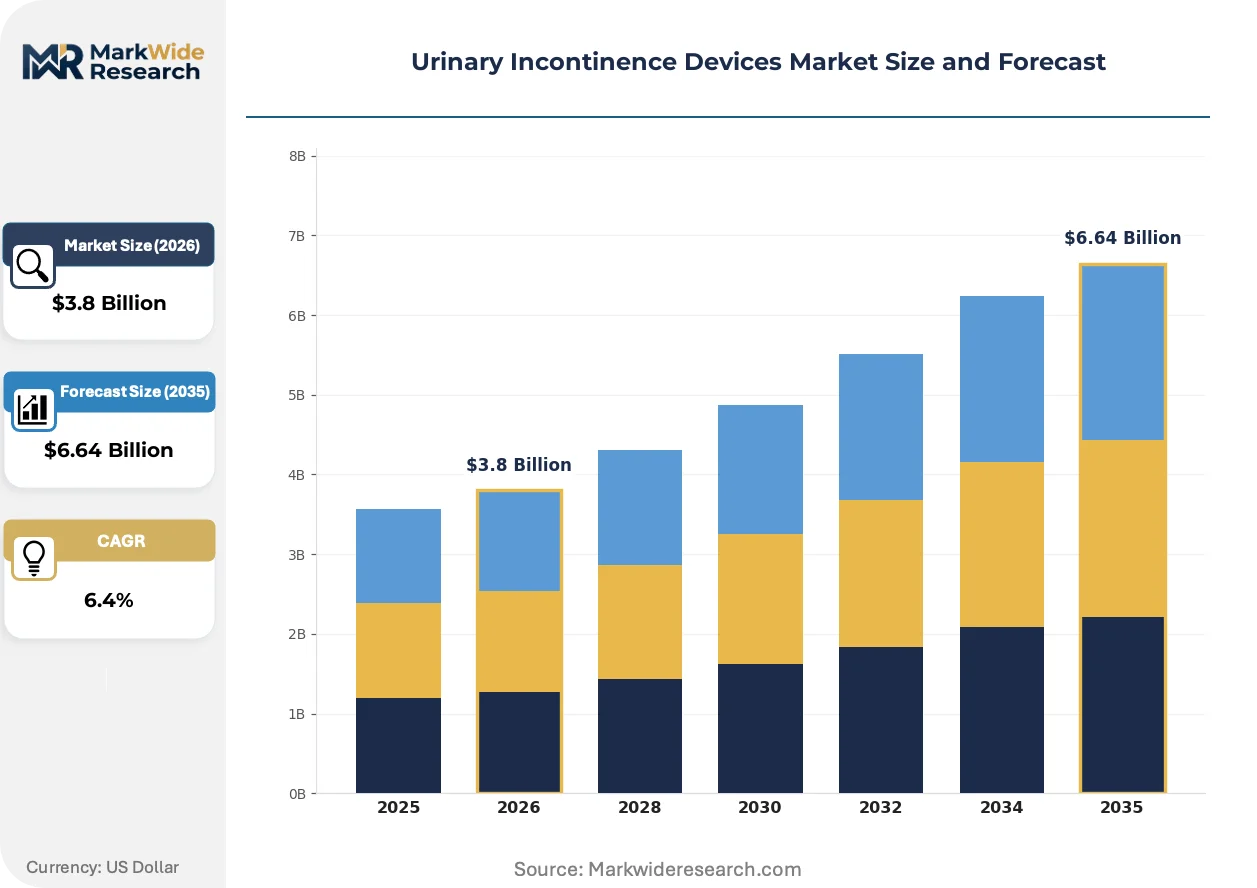
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, External Catheters, Urethral Inserts, Penile Clamp, Pessary Devices Technology: Magnetic Valve, Sensor-Integrated, Disposable, Reusable, Non-Invasive Application: Stress Induced Leakage, Urge Incontinence, Overflow Incontinence, Functional Incontinence, Mixed Symptoms End User: Home Care, Long-Term Care Facilities, Rehabilitation Centers, Assisted Living, Specialty Clinics |
| Companies Covered | Coloplast A/S, B. Braun SE, Johnson & Johnson Services, Inc., Medtronic, Boston Scientific Corporation, Essity Aktiebolag, Teleflex Incorporated, ConvaTec Group plc, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Incontinence Devices Market Strategic Shifts & Innovations
Patient-centricity is the core theme driving product evolution, with a focus on enhancing user discretion, comfort, and lifestyle compatibility. This emphasis is compelling a shift away from purely clinical function toward holistic solutions that address the user's quality of life.
Advanced biocompatible materials, such as specialized medical-grade silicones and breathable nonwoven fabrics, are improving the wear-time and skin-friendliness of devices. Long-term users in home care settings are the primary adopters of these next-generation products. This focus on material science is unifying the previously separate goals of clinical efficacy and user comfort into a single, integrated design principle.
The European Union's Medical Device Regulation (MDR) establishes a more rigorous regulatory landscape, demanding higher levels of clinical evidence for market approval. This forces manufacturers to invest more heavily in clinical trials and robust post-market surveillance systems. Products at the higher end of the risk classification, including certain implantable devices and some reusable catheters, are most affected, often requiring redesigns to meet the new standards.
A consumerization of healthcare is altering purchasing behaviors, with patients increasingly selecting devices based on personal research and lifestyle needs rather than solely on clinician recommendation. This behavior disrupts the traditional institutional procurement model, giving rise to direct-to-consumer e-commerce and subscription services. The trend is most visible in the absorbent product and external catheter segments within North American and European markets.
Urinary Incontinence Devices Market Segmentation
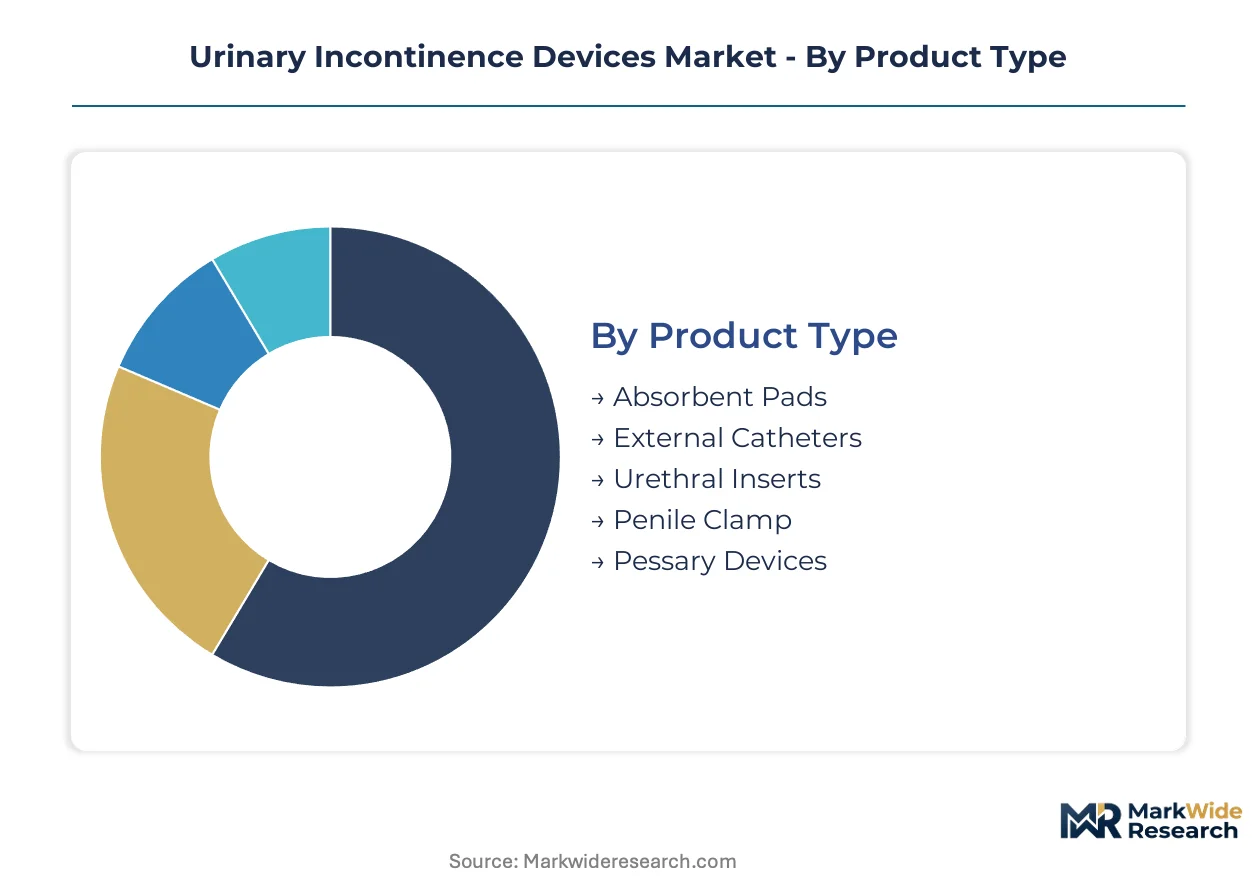
Understanding the varied requirements of patients and healthcare providers drives the segmentation of the urinary incontinence devices market. This granular analysis provides clarity on product adoption patterns, technological preferences, and the evolving landscape of care delivery models. Each segment reflects distinct user needs and commercial opportunities for manufacturers.
Product Type:
The upfront capital investment required for device manufacturing varies significantly across product types, influencing market entry barriers and competitive dynamics. More complex devices, especially implantable ones, demand substantial R&D and regulatory compliance expenditures.
- Absorbent Pads:These disposable products consist of super-absorbent polymers and nonwoven fabrics designed to contain urine leakage discreetly. Demand concentrates in home care settings across North America due to ease of use and widespread availability.
- External Catheters:These devices, often made from medical-grade silicone, are applied externally to collect urine, preventing skin irritation and infection. Their use is expanding most quickly in Europe's aging population as a non-invasive management option.
- Urethral Inserts:Small, disposable devices temporarily placed in the urethra to prevent leakage, offering an active solution for stress incontinence.
- Penile Clamp:A mechanical device applied externally to the penis to compress the urethra, providing temporary control for male incontinence.
- Pessary Devices:Silicone devices inserted into the vagina to support pelvic organs, primarily managing stress incontinence by altering bladder neck position.
Absorbent pads absorb the bulk of installed capacity; external catheters are expanding most quickly.
Technology:
The value proposition of different technologies ranges from basic containment to advanced monitoring, impacting pricing tiers and customer acquisition strategies. Technologies offering enhanced comfort or data insights command higher price points.
- Sensor-Integrated:These advanced devices incorporate embedded sensors to detect leakage, monitor usage patterns, and transmit data to users or caregivers. Their adoption is accelerating in Western European markets due to a focus on proactive patient management.
- Non-Invasive:Technologies that do not penetrate the body, such as external catheters and absorbent products, prioritize user comfort and minimize infection risk. Demand for non-invasive solutions is particularly high in Japan's elderly demographic seeking discreet management.
- Magnetic Valve:Implantable devices that utilize magnetic forces to control urinary flow, offering a long-term solution for severe incontinence.
- Disposable:Products designed for single use, emphasizing convenience and hygiene, forming the foundation of high-volume segments.
- Reusable:Devices that can be cleaned and re-used, offering a cost-effective and environmentally conscious option for some patient groups.
Disposable technologies dominate the current market landscape; sensor-integrated solutions are gaining traction among tech-forward users.
Application:
The prevalence of various incontinence types dictates the volume demand for specific device functionalities, shaping product development priorities. Solutions for common conditions attract broader market penetration.
- Stress Induced Leakage:This common application refers to involuntary urine leakage during physical activity like coughing, sneezing, or exercising. Innovation in non-invasive solutions for stress-induced leakage is particularly concentrated in the US market.
- Urge Incontinence:Characterized by a sudden, intense urge to urinate followed by involuntary leakage, often managed with absorbent products or specific behavioral therapies. European healthcare systems are increasingly focused on improving device efficacy for urge incontinence.
- Overflow Incontinence:Occurs when the bladder does not empty completely, leading to frequent leakage of small amounts of urine.
- Functional Incontinence:Inability to reach the toilet in time due to physical or cognitive impairments, requiring adaptable and easy-to-use devices.
- Mixed Symptoms:Patients experiencing a combination of incontinence types, necessitating a versatile range of management devices.
Management of stress-induced leakage represents the most common application; solutions for mixed symptoms require comprehensive device portfolios.
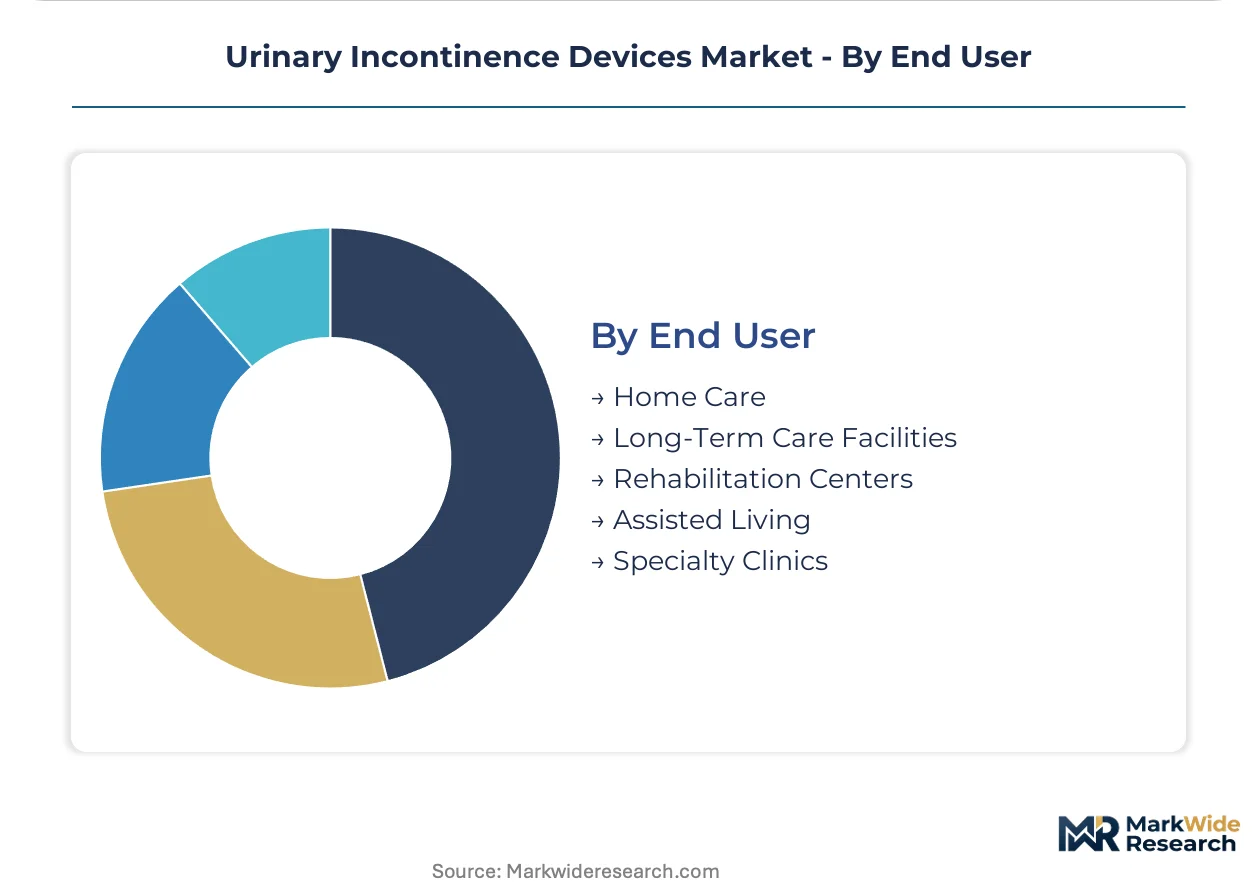
End User:
The shifting landscape of healthcare delivery models impacts device distribution channels and design requirements. Home care settings are rapidly gaining prominence, altering traditional procurement patterns.
- Home Care:Patients managing incontinence in their own residences, driving demand for user-friendly, discreet, and readily available devices. This segment is experiencing significant expansion in North America, supported by robust e-commerce channels.
- Long-Term Care Facilities:Institutional settings providing continuous care for residents, where bulk purchasing and ease of application for caregivers are paramount. These facilities in Germany consistently demonstrate high volume demand for basic absorbent products.
- Rehabilitation Centers:Facilities focused on restoring functional abilities, where devices support patient mobility and independence during recovery.
- Assisted Living:Residential communities offering support with daily activities, requiring devices that maintain resident dignity and ease of use.
- Specialty Clinics:Medical facilities specializing in urology or gynecology, often prescribing advanced or custom-fit devices for complex cases.
Home care settings are rapidly expanding their share of device consumption; specialty clinics focus on advanced diagnostic and interventional device prescriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global urinary incontinence devices market exhibits a notable divide between established production hubs and regions experiencing accelerated consumption. Western economies often lead in device innovation and manufacturing. Rapidly aging populations in specific countries drive significant end-user demand for these essential medical aids.
United States
The United States market sees robust demand for non-invasive solutions and home care devices, driven by patient preference. US FDA's 510(k) pathway mandates rigorous safety and efficacy data for new products. The Boston medical technology cluster actively develops advanced incontinence management devices, integrating sensor technology.
Germany
Germany consistently demonstrates high volume demand for basic absorbent products from its extensive network of long-term care facilities. The EU Medical Device Regulation (MDR) influences product design and approval processes for devices sold here. Munich's medtech firms concentrate on developing high-quality absorbent products.
Japan
Japan's rapidly aging population creates a consistent user base for urinary incontinence management products. The PMDA oversees stringent approval processes for medical devices, ensuring safety and efficacy. Tokyo-based manufacturers innovate discreet, comfortable non-invasive solutions, particularly for the elderly demographic.
India
India presents significant long-term growth prospects, fueled by rising healthcare expenditure and increasing awareness. The CDSCO regulates medical devices, focusing on quality standards and market access. Bengaluru's medical device sector attracts investment for localized production, targeting unmet patient needs.
United Kingdom
The United Kingdom exhibits consistent demand for urinary incontinence devices, driven by its aging demographic and a shift towards home-based care. The UK MHRA governs device safety and performance, aligning with international standards. London's healthcare technology ecosystem supports innovation in digital health and wearable solutions.
Urinary Incontinence Devices Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized mid-market players focus on niche product categories. The market structure exhibits a tiered consolidation, with a few large multinational corporations dominating significant product segments. Strategic archetypes include diversified healthcare conglomerates and focused urology device specialists. Companies are increasingly pursuing portfolio diversification into smart device integration and geographic expansion into emerging markets.
Specialists in urology and incontinence management, such as Coloplast A/S, exemplify companies with a strong clinical reputation in intermittent catheters. Boston Scientific Corporation, a US-based entity, anchors the advanced implantable solutions segment, distinguishing itself through technological innovation for severe incontinence. Essity Aktiebolag, a Swedish public limited company, represents diversified players leveraging extensive distribution networks to serve retail and home care channels effectively. These entities occupy distinct positions across the product type and end-user spectrums, influencing market dynamics through their focused strategies.
| Leading Market Players |
|---|
| Coloplast A/S |
| B. Braun SE |
| Johnson & Johnson Services, Inc. |
| Medtronic |
| Boston Scientific Corporation |
| Essity Aktiebolag |
| Teleflex Incorporated |
| ConvaTec Group plc |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
European Medical Device Regulation (MDR) compliance mandates for higher clinical evidence and material biocompatibility are pushing manufacturers to absorb elevated development costs. This demand-side pressure translates into increased supply-side investment, ultimately influencing product pricing across the market.
Pricing Analysis
Premium pricing for devices with short lead times often reflects specialized manufacturing and stringent regulatory approvals like the EU MDR. The market primarily operates on a hybrid per-unit transactional model for disposables and contract-based long-term agreements for institutional supplies. Price differentiation stems from medical-grade silicone quality and advanced sensor integration capabilities. Pricing pressure stems from rising regulatory compliance costs, making home care consumers for disposable products more price sensitive than specialty clinics for advanced devices.
Supply Chain Analysis
Certification and qualification requirements, particularly under US FDA and EU MDR frameworks, gate access to the urinary incontinence device supply chain. Manufacturing concentrates in China for high-volume disposables and in Germany and the US for specialized components. The industry relies on super-absorbent polymers and medical-grade silicone as key raw materials, with material sourcing volatility representing a structural risk. Distribution runs through retail, e-commerce, and institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary incontinence devices market is navigating a technology-transition phase, as sensor-integrated solutions increasingly displace traditional passive absorbent products. This shift emphasizes proactive management and data-driven patient care over basic containment.
For Market Incumbents: Anchor extensive distribution networks in retail and home care channels to maintain market share against emerging digital platforms. Pursue strategic acquisitions of specialized technology firms to integrate sensor-integrated capabilities into core product lines. Invest in advanced material science R&D to enhance discretion and comfort, offsetting the threat from innovative new entrants in smart device integration. Control over established clinical relationships remains a critical lever. For New Entrants and Emerging Players: E-commerce platforms offer a direct route to market for specialized devices, bypassing traditional distribution gatekeepers. Target underpenetrated emerging markets like India and Brazil with cost-effective, discreet solutions tailored for local preferences. Focus on smart device integration for home care, providing data insights for proactive patient management. Develop direct-to-consumer subscription models to build brand loyalty and predictable revenue streams. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with robust intellectual property in sensor technology or advanced biocompatible materials. Long-term viability in this market is underpinned by rapidly aging demographics and continuous technological innovation in non-invasive solutions. Identify acquisition targets that demonstrate strong clinical efficacy and user-centric design, particularly those with established direct-to-consumer channels. A shift in reimbursement policies to cover smart incontinence devices will serve as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Higher clinical evidence is crucial for EU MDR compliance and market approval in Europe. |
| Direct-to-Consumer Channel Launch | Bypassing traditional distribution channels builds direct relationships with North American end-users. |
| Sensor Integration Investment | Developing smart devices offers product differentiation and proactive patient management capabilities. |
| Emerging Market Penetration | Targeting untapped demand in countries like India unlocks significant long-term growth prospects. |
| Biocompatible Material R&D | Innovating with specialized silicones and fabrics enhances user comfort and wear-time. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with clinicians, hospital purchasing committees, home care providers, and device engineers provided qualitative insights. This approach combined bottom-up market sizing with top-down validation against industry reports and patent databases. US FDA filings and EU MDR guidelines were crucial secondary sources.
Data-stream reconciliation across multiple sources underpinned the quantitative analytical framework for this study. The model segmented the market by product type, technology, application, end-user, and geographic region across the analysis window. Compound annual growth rates were derived from historical trends and projected demand, integrating insights from aging population demographics and healthcare expenditure trends.
Caveats apply where significant shifts in regulatory frameworks or raw material supply disruptions could materially shift the outlook. Forecasts reflect current market dynamics and documented assumptions regarding technological adoption rates. A model refresh is warranted upon material change in reimbursement policies or major demographic shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Biliary Catheters Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Digital Phoropter Market
Medical Devices
Pectus Bar System Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Diabetes Devices Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
US C-Arms Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Vibrating Mesh Nebulizer Market