
 Zimbabwe Pharmaceutical Market | 2026-2036
Zimbabwe Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Zimbabwe Pharmaceutical Market Analytics
Unit-dose packaging is shifting toward blister-strip configurations for chronic disease medications, altering how pharmacies manage inventory and patient adherence programs. NatPharm anchors public-sector distribution through its central procurement mandate, while GlaxoSmithKline PLC leverages its respiratory and vaccine portfolio to sustain institutional contracts. B. Braun SE differentiates through infusion therapy systems that integrate with hospital pharmaceutical workflows.
Zimbabwe pharmaceuticals encompass chemically synthesized or biologically derived therapeutic agents formulated for disease prevention, diagnosis, or treatment, typically manufactured under current Good Manufacturing Practice standards requiring validated sterility assurance and dissolution profiles. Generics command volume leadership as cost-containment pressures reshape procurement tenders, while biologics represent the fastest-expanding margin pool despite cold-chain infrastructure constraints. Prescription drugs dominate hospital formularies, whereas over-the-counter categories concentrate in urban retail pharmacy networks.
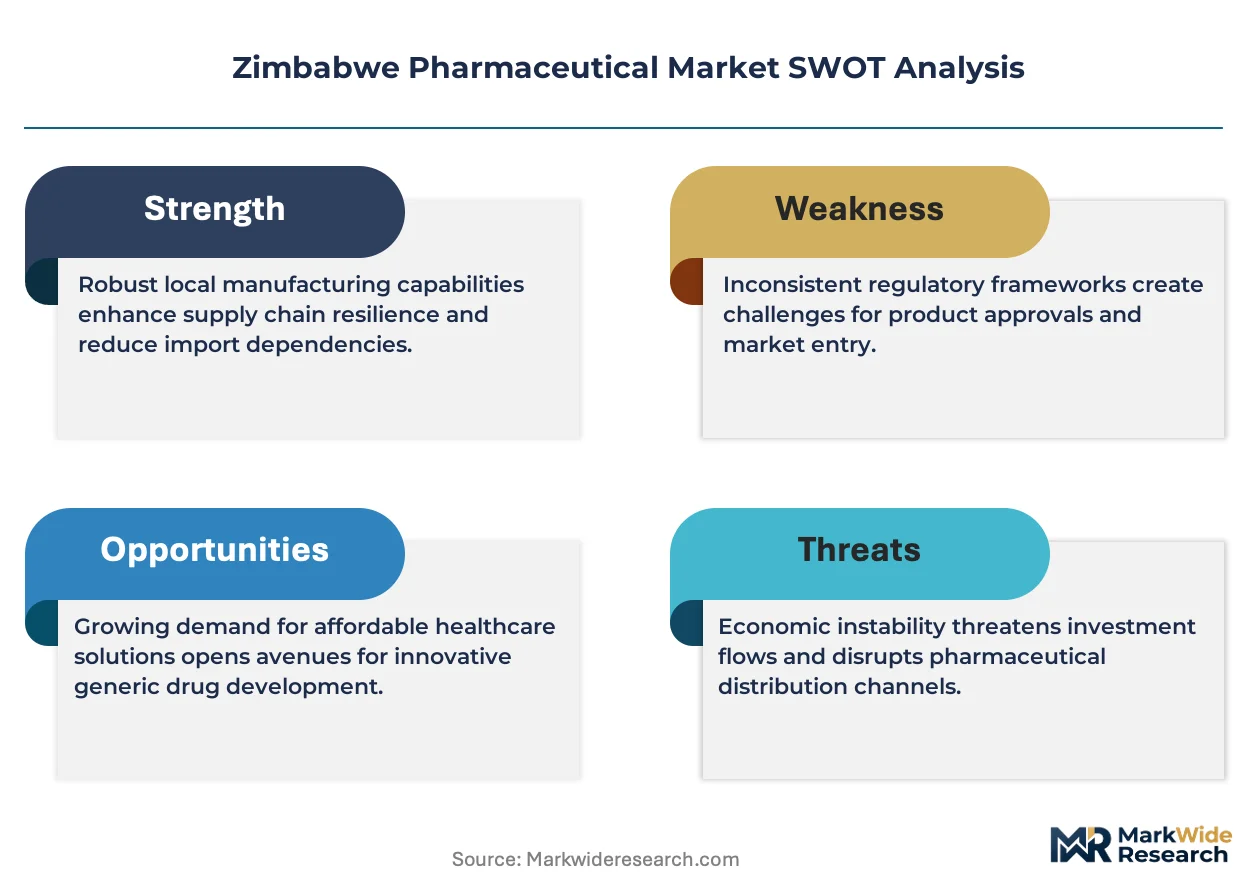
The Medicines Control Authority of Zimbabwe enforces product registration and quality surveillance, while the Pharmacy Council of Zimbabwe regulates practitioner licensing and dispensing standards; both frameworks elevate compliance costs for imported formulations. The country's national essential medicines list shapes public procurement scope and reimbursement eligibility. Stakeholders must monitor regulatory harmonization with the Southern African Development Community's pharmaceutical protocols and assess local manufacturing incentives against import dependency risks.
Market Dynamics
NatPharm's central procurement mandate is concentrating public-sector pharmaceutical distribution, while private clinic networks in Harare's urban corridor drive specialty consumption patterns that reshape inventory management across retail pharmacy chains.
Growth Catalysts
- Essential Medicines List Expansion:Zimbabwe's national essential medicines list revision is broadening reimbursement eligibility for chronic disease therapies, pulling volume through public hospital procurement channels.
- Blister-Strip Packaging Adoption:Unit-dose configuration for antiretroviral and diabetes medications is automating patient adherence tracking and reducing dispensing errors in retail pharmacy networks.
- SADC Regulatory Harmonization:Alignment with Southern African Development Community pharmaceutical protocols is streamlining cross-border registration pathways for imported formulations.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient sourcing concentrates on Indian and Chinese suppliers, exposing formulators to currency volatility and shipping disruptions.
- Cold-Chain Infrastructure Gaps:Biologics distribution faces temperature excursion risks outside Harare's urban healthcare corridor, limiting margin pool expansion for temperature-sensitive therapies.
- Registration Timeline Compression:Medicines Control Authority of Zimbabwe updated protocols are extending import compliance timelines, delaying market entry for new molecular entities.
Strategic Opportunities
- Bulawayo Regional Hub Development:Zimbabwe's second-largest city presents underpenetrated specialty pharmaceutical demand as private clinic networks expand beyond Harare's urban corridor.
- Local Manufacturing Incentives:Government industrial policy frameworks are creating fiscal advantages for domestic formulation facilities serving public procurement tenders.
- Telepharmacy Channel Emergence:Remote consultation platforms are enabling rural patient access to prescription fulfillment, bypassing traditional brick-and-mortar pharmacy density constraints.
Industry Challenges
- Qualified Pharmacist Scarcity:Pharmacy Council of Zimbabwe licensing requirements exceed supply of trained practitioners, constraining dispensing capacity expansion in emerging urban zones.
- Legacy Inventory System Integration:Hospital pharmaceutical workflows depend on paper-based stock management that conflicts with automated procurement platforms NatPharm is deploying.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zimbabwe Pharmaceutical Market |
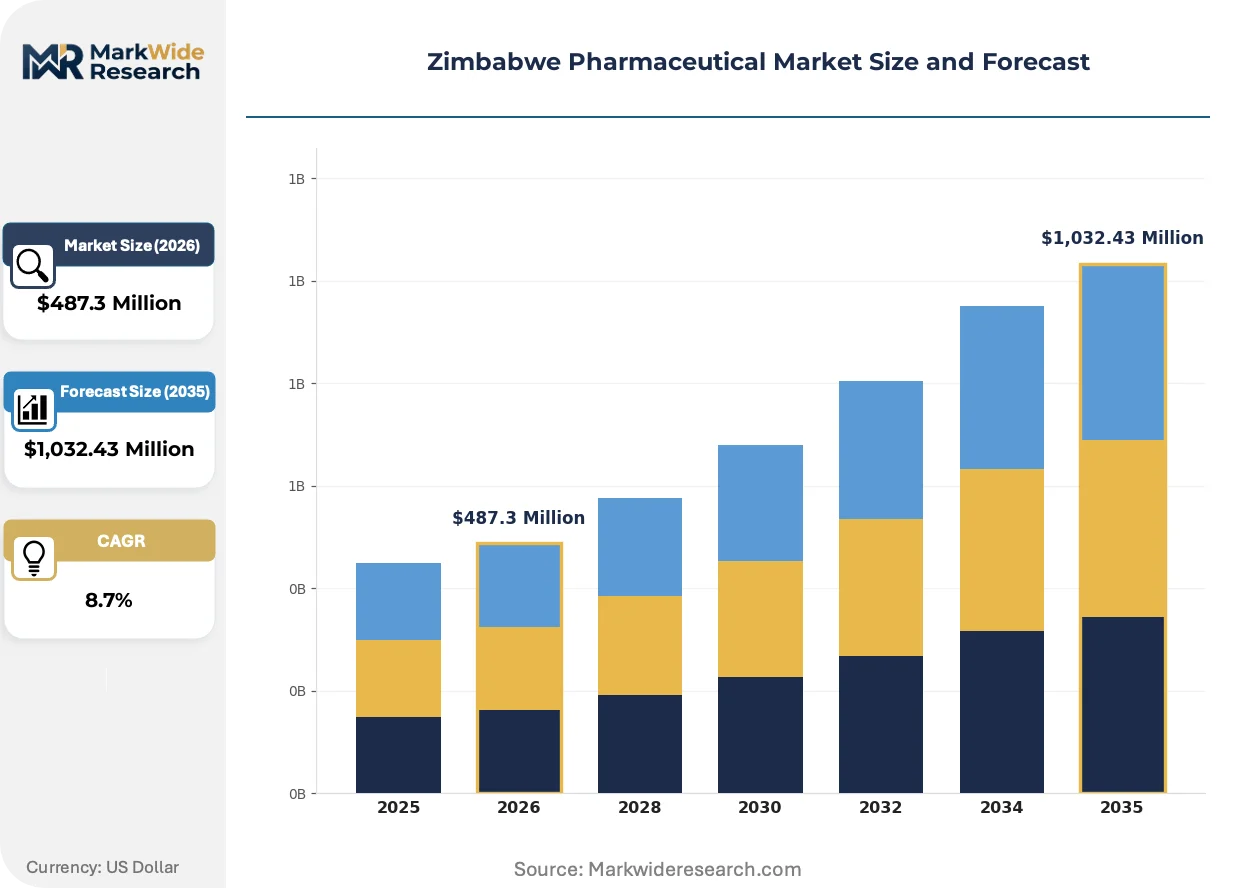
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics Therapy Area: Cardiovascular, Oncology, Infectious Diseases, Diabetes End User: Hospitals, Pharmacies, Clinics, Healthcare Providers Distribution Channel: Retail, Wholesale, Direct, Online |
| Companies Covered | Caps (Pvt) Ltd, National Pharmaceutical Company (NatPharm), Pharmanova, Viatris Inc, CosPharma, Zim Laboratories Limited, B. Braun SE, GlaxoSmithKline PLC, Datlabs (Pvt) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zimbabwe Pharmaceutical Market Evolving Landscape
Automation is penetrating Zimbabwe's pharmaceutical supply chain at multiple nodes, from manufacturing quality control through retail dispensing workflows. Three developments are restructuring competitive capabilities and procurement patterns.
Track-and-trace serialization technology is automating batch verification and counterfeit detection across distribution channels. Wholesale distributors serving private clinic networks are adopting barcode authentication systems at accelerating pace. This technology is automating regulatory compliance documentation and compressing investigation timelines for quality incidents.
The Medicines Control Authority of Zimbabwe's updated registration protocols are mandating enhanced stability data submissions for imported formulations. Manufacturers must now demonstrate validated dissolution profiles under local climate conditions. Generic suppliers targeting public hospital procurement are responding by establishing local storage partnerships to generate region-specific stability datasets.
Patient-directed pharmacy selection is displacing physician-tied dispensing in chronic disease management. Retail chains in Harare's urban healthcare corridor are capturing refill loyalty through adherence program enrollment. This pattern concentrates prescription volume in networks offering integrated diagnostic services, particularly for diabetes and hypertension monitoring.
Zimbabwe Pharmaceutical Market Segmentation
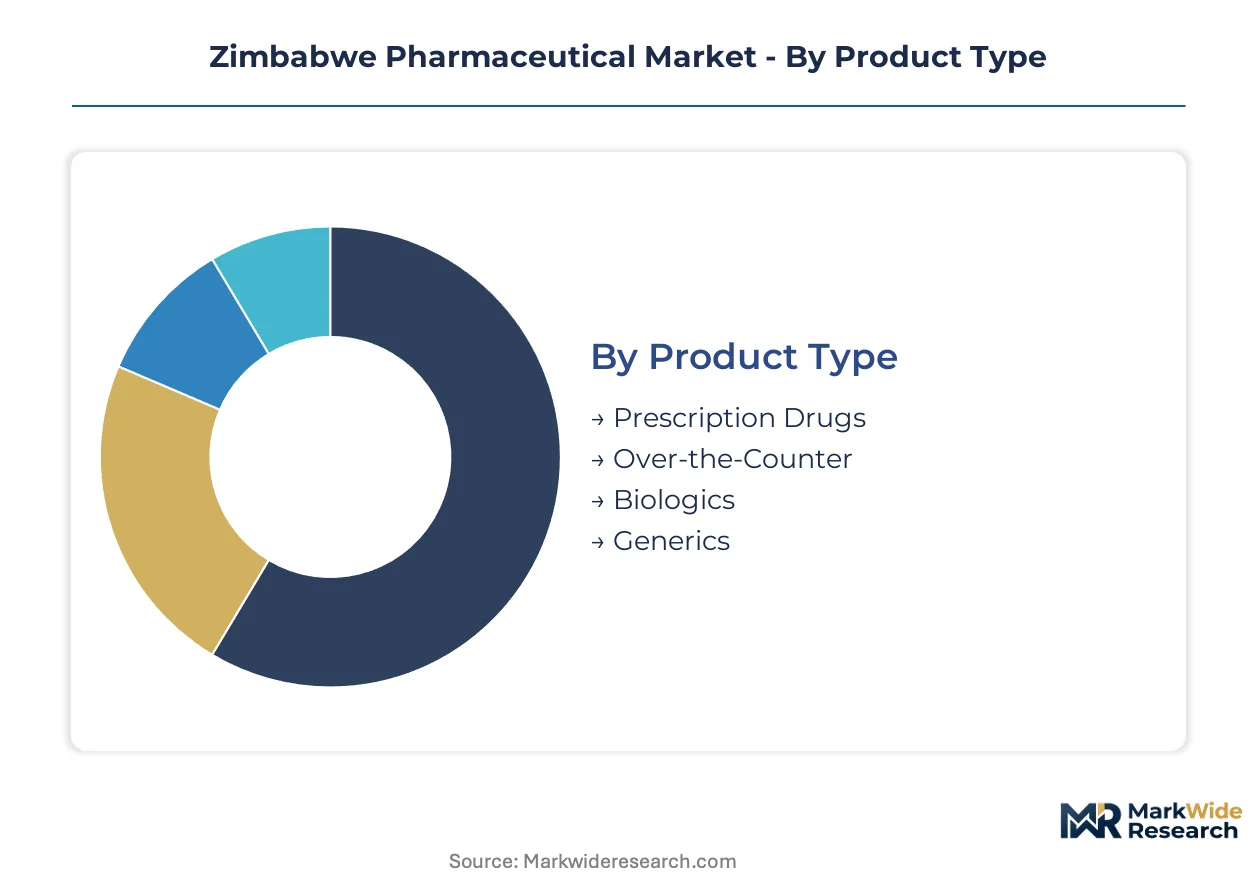
Segmentation in Zimbabwe's pharmaceutical market reveals how procurement power, regulatory pathways, and patient access patterns fragment across product categories and delivery channels. Understanding these divisions exposes where NatPharm's central mandate intersects with private-sector flexibility, and where cold-chain limitations constrain biologics penetration against generic volume dominance.
Product Type:
Customization intensity varies sharply across this spectrum, from mass-produced generics calibrated to essential medicines list specifications to biologics requiring patient-specific cold-chain protocols and specialized handling infrastructure.
- Prescription Drugs:Chemically synthesized therapeutic agents requiring practitioner authorization under Pharmacy Council of Zimbabwe dispensing protocols. Hospital formularies in Harare's urban corridor concentrate demand for antimicrobial and cardiovascular prescriptions, with NatPharm tenders prioritizing these categories for public procurement scale.
- Generics:Bioequivalent formulations manufactured post-patent expiry under current Good Manufacturing Practice standards. Volume leadership in Zimbabwe reflects cost-containment pressures reshaping procurement tenders, with Indian and Chinese active pharmaceutical ingredient suppliers anchoring formulation economics.
- Over-the-Counter:Non-prescription medications for self-diagnosed conditions distributed through retail pharmacy networks. Urban pharmacy chains in Harare capture refill loyalty through adherence program enrollment for chronic symptom management.
- Biologics:Temperature-sensitive protein-based therapeutics derived from living cells requiring validated sterility assurance. Cold-chain infrastructure gaps outside Harare's urban healthcare corridor limit margin pool expansion despite representing the fastest-growing trajectory for specialty pharmaceutical consumption.
Most installed capacity flows through Generics. Expansion is steepest in Biologics.
Therapy Area:
Clinical burden and reimbursement eligibility reshape priority across this dimension, with communicable disease programs competing against rising non-communicable disease prevalence for procurement budget allocation.
- Infectious Diseases:Antimicrobial, antiretroviral, and antiparasitic formulations targeting HIV, tuberculosis, and malaria. Public hospital procurement channels pull volume through essential medicines list expansion, with blister-strip packaging adoption automating patient adherence tracking.
- Cardiovascular:Antihypertensive, anticoagulant, and lipid-modifying agents for ischemic and hypertensive conditions. Private clinic networks in Harare's urban corridor drive specialty consumption as diagnostic capability expands.
- Diabetes:Insulin formulations and oral hypoglycemic agents for glucose management. Retail pharmacy chains capture chronic refill volume through integrated diagnostic services and adherence program enrollment.
- Oncology:Cytotoxic and targeted therapies for malignant disease management. Limited availability concentrates in private healthcare providers with infusion therapy capability, constraining access against rising cancer incidence.
Procurement volume concentrates in Infectious Diseases. Patient-directed pharmacy selection is climbing fastest in Diabetes.
End User:
Institutional scale versus individual access creates divergent compliance requirements and inventory turnover economics across this category.
- Hospitals:Acute care institutions with centralized pharmaceutical procurement and formulary management. NatPharm's central mandate concentrates public-sector distribution, while legacy paper-based stock management conflicts with automated procurement platform deployment.
- Pharmacies:Licensed dispensing facilities regulated under Pharmacy Council of Zimbabwe standards. Urban retail networks in Harare manage inventory through patient adherence programs, with qualified pharmacist scarcity constraining capacity expansion.
- Clinics:Outpatient facilities providing primary and specialty care with limited pharmaceutical storage. Private clinic networks beyond Harare's urban corridor present underpenetrated specialty demand as diagnostic capability expands.
- Healthcare Providers:Individual practitioners and group practices with direct prescribing authority. Telepharmacy platform emergence enables rural patient access to prescription fulfillment, bypassing traditional brick-and-mortar density constraints.
Public procurement flows predominantly through Hospitals. Private specialty consumption is gaining share fastest in Clinics.
Distribution Channel:
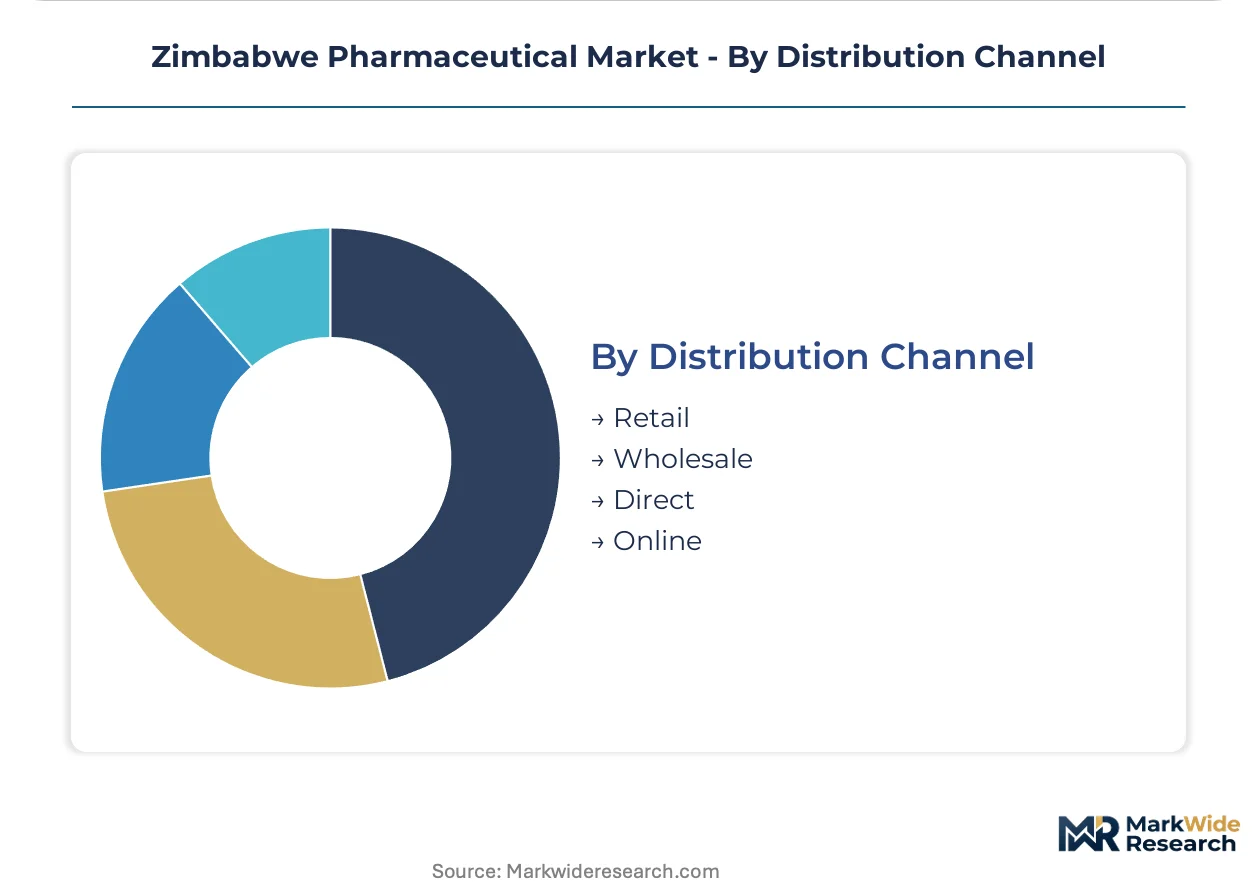
Physical infrastructure requirements and regulatory documentation intensity separate traditional wholesale from emerging direct-to-patient models.
- Wholesale:Bulk pharmaceutical distribution through licensed intermediaries with validated storage and transport capability. Track-and-trace serialization technology adoption automates batch verification and counterfeit detection across this channel.
- Retail:Patient-facing dispensing through pharmacy storefronts with point-of-sale inventory management. Harare's urban healthcare corridor concentrates prescription volume in networks offering integrated diagnostic services.
- Direct:Manufacturer-to-institution supply relationships bypassing intermediary markup. Hospital pharmaceutical workflows depend on direct contracts for infusion therapy systems and specialized equipment.
- Online:Digital platforms enabling remote consultation and prescription fulfillment. Telepharmacy channel emergence is reshaping rural access patterns beyond traditional geographic constraints.
Current pharmaceutical volume moves primarily through Wholesale. Digital infrastructure investment is expanding most quickly in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distribution in Zimbabwe traces its institutional roots to the 1980s post-independence period, when centralized procurement systems replaced colonial supply chains. The current market structure reflects decades of public-sector investment in essential medicines access, overlaid with private-sector expansion in urban healthcare corridors.
Harare Metropolitan Province
Private clinic networks and retail pharmacy chains concentrate demand for specialty pharmaceuticals and chronic disease therapies. The Medicines Control Authority of Zimbabwe maintains its headquarters here, streamlining registration compliance for importers targeting the urban corridor. Cold-chain infrastructure investments in Harare's industrial zones enable biologics distribution that remains unavailable elsewhere.
Bulawayo Metropolitan Province
Zimbabwe's second-largest city presents underpenetrated specialty pharmaceutical demand as diagnostic capability expands beyond the capital. Local manufacturing incentives under national industrial policy frameworks are attracting formulation facilities to serve western regional procurement. The Bulawayo-Gweru corridor is emerging as a secondary distribution hub for temperature-stable generics.
Manicaland Province
Border proximity to Mozambique creates cross-border pharmaceutical trade flows through Mutare's commercial channels. The province's hospital network relies on NatPharm's central procurement mandate for essential medicines list compliance. Rural telepharmacy platforms are bypassing traditional brick-and-mortar pharmacy density constraints in the Eastern Highlands.
Masvingo Province
Agricultural employment patterns shape seasonal demand for occupational health pharmaceuticals and trauma care supplies. Provincial hospital procurement operates under legacy paper-based stock management systems that conflict with NatPharm's automated platform deployment. The Great Zimbabwe University medical school is expanding qualified pharmacist training to address regional scarcity.
Mashonaland West Province
Chinhoyi's healthcare corridor serves mining community pharmaceutical needs through employer-sponsored clinic networks. The province's distribution infrastructure depends on wholesale channels from Harare, creating lead-time vulnerabilities for urgent therapies. Local storage partnerships are generating region-specific stability datasets for generic suppliers targeting public hospital procurement.
Zimbabwe Pharmaceutical Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the cold-chain capability and regulatory compliance spectrum. The market exhibits tiered concentration, with a handful of multinational subsidiaries commanding institutional contracts while domestic formulators compete on public tender pricing. Three archetypes dominate: global pharmaceutical majors with respiratory and vaccine portfolios, regional generic suppliers leveraging Indian and Chinese active pharmaceutical ingredient sourcing, and specialized infusion therapy equipment providers. Competitive moves center on local manufacturing incentives utilization and telepharmacy platform partnerships.
Within the public procurement anchor tier, National Pharmaceutical Company (NatPharm) exemplifies centralized distribution mandate execution, while GlaxoSmithKline PLC represents multinational institutional contract maintenance. Among specialized equipment providers, B. Braun SE occupies a position integrating infusion therapy systems with hospital pharmaceutical workflows.
| Leading Market Players |
|---|
| Caps (Pvt) Ltd |
| National Pharmaceutical Company (NatPharm) |
| Pharmanova |
| Viatris Inc |
| CosPharma |
| Zim Laboratories Limited |
| B. Braun SE |
| GlaxoSmithKline PLC |
| Datlabs (Pvt) Ltd |
| Others |
Value Network & Pricing Analysis
NatPharm's central procurement mandate concentrates buyer power in Zimbabwe's public hospital system, compressing margins for generic suppliers while enabling volume-based contract structures that favor scale over differentiation. This procurement concentration feeds directly into supply chain decisions, with formulators prioritizing Indian and Chinese active pharmaceutical ingredient partnerships to meet tender pricing floors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Zimbabwe's pharmaceutical market, with price differentiation driven by Medicines Control Authority of Zimbabwe registration tier and cold-chain certification status. Cost compression in the economy tier is intensifying because of essential medicines list expansion and public tender volume aggregation. Private clinic networks in Harare's urban corridor show least price sensitivity for biologics and specialty therapies, while rural pharmacy chains face acute margin pressure from generic substitution policies.
Supply Chain Analysis
Qualified pharmacist scarcity in Zimbabwe's manufacturing zones constrains local formulation capacity, forcing supply chain dependence on Indian and Chinese active pharmaceutical ingredient suppliers. Formulation economics rest on imported raw materials including antiretroviral intermediates, cardiovascular API precursors, and diabetes medication substrates. Single-source vulnerability concentrates in temperature-sensitive biologics requiring validated cold-chain handoffs. Distribution runs through NatPharm's centralized warehouse network for public-sector fulfillment, with private wholesale channels serving retail pharmacy chains in Harare's urban corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zimbabwe's pharmaceutical market compounds steadily through chronic disease prevalence expansion and essential medicines list revision cycles. Government procurement scale provides predictable demand anchors for compliant suppliers.
For Market Incumbents: Anchor institutional contract positions by deepening backward integration into active pharmaceutical ingredient sourcing partnerships with Indian and Chinese suppliers, countering currency volatility exposure. Defend against emerging regional generic entrants by accelerating Medicines Control Authority of Zimbabwe registration timelines for high-volume essential medicines list categories, leveraging existing stability data partnerships. For New Entrants and Emerging Players: Capture underpenetrated specialty pharmaceutical demand in Bulawayo's expanding private clinic network, where diagnostic capability growth outpaces formulary availability. Target telepharmacy platform partnerships as the primary go-to-market angle, bypassing qualified pharmacist scarcity constraints in rural Manicaland and Masvingo provinces through remote consultation infrastructure. For Investors and Strategic Acquirers: Regional pharmaceutical distributors with SADC regulatory harmonization capabilities are the most active acquirer in this space, consolidating cross-border registration assets. Long-term viability frames around local manufacturing incentive utilization and cold-chain infrastructure buildout. Watch NatPharm procurement platform automation milestones as the signal for public-sector margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Scale-Up | Domestic formulation facilities capture fiscal incentives under national industrial policy frameworks serving public tenders. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled distribution networks unlock biologics margin pools beyond Harare's urban healthcare corridor. |
| Telepharmacy Platform Integration | Remote consultation systems bypass brick-and-mortar pharmacy density constraints in rural Eastern Highlands provinces. |
| SADC Regulatory Harmonization | Alignment with Southern African Development Community protocols streamlines cross-border registration for imported formulations. |
| Track-and-Trace Serialization Deployment | Barcode authentication systems automate Medicines Control Authority of Zimbabwe compliance documentation and counterfeit detection. |
Research Methodology
Direct dialogue with hospital procurement managers, Pharmacy Council of Zimbabwe licensing officials, NatPharm distribution executives, and private clinic network administrators grounded this analysis in operational reality. Secondary validation drew from Medicines Control Authority of Zimbabwe registration databases, essential medicines list revision documents, Southern African Development Community pharmaceutical protocol harmonization frameworks, and customs import records. Bottom-up demand modeling triangulated against top-down procurement budget allocations.
Top-down macroeconomic projections anchored analytical frameworks across the analysis window, with segmentation modeling across product type, therapy area, end user, and distribution channel dimensions. Treatment line positioning and regional regulatory cluster status provided additional pharmaceutical-specific granularity. CAGRs derived from historical procurement volume trajectories, adjusted for policy intervention impacts including local manufacturing incentive schemes and essential medicines list expansion schedules.
Currency devaluation, API import disruption, and qualified pharmacist training pipeline gaps are the dominant revision risks to forecast assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Pain Management Drugs Market