
 Global Seasonal Affective Disorder Therapeutics Market | 2026-2036
Global Seasonal Affective Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seasonal Affective Disorder Therapeutics Market Foresight
Psychiatrist availability in northern latitudes is bifurcating market access between well-served urban corridors and underserved peripheral regions. Pfizer Inc. leverages its established antidepressant portfolio to sustain formulary positions across European markets. Johnson & Johnson anchors its presence through diversified neuroscience pipelines spanning pharmacotherapy and digital adjuncts. Eli Lilly and Company differentiates via R&D intensity in novel mechanism antidepressants.
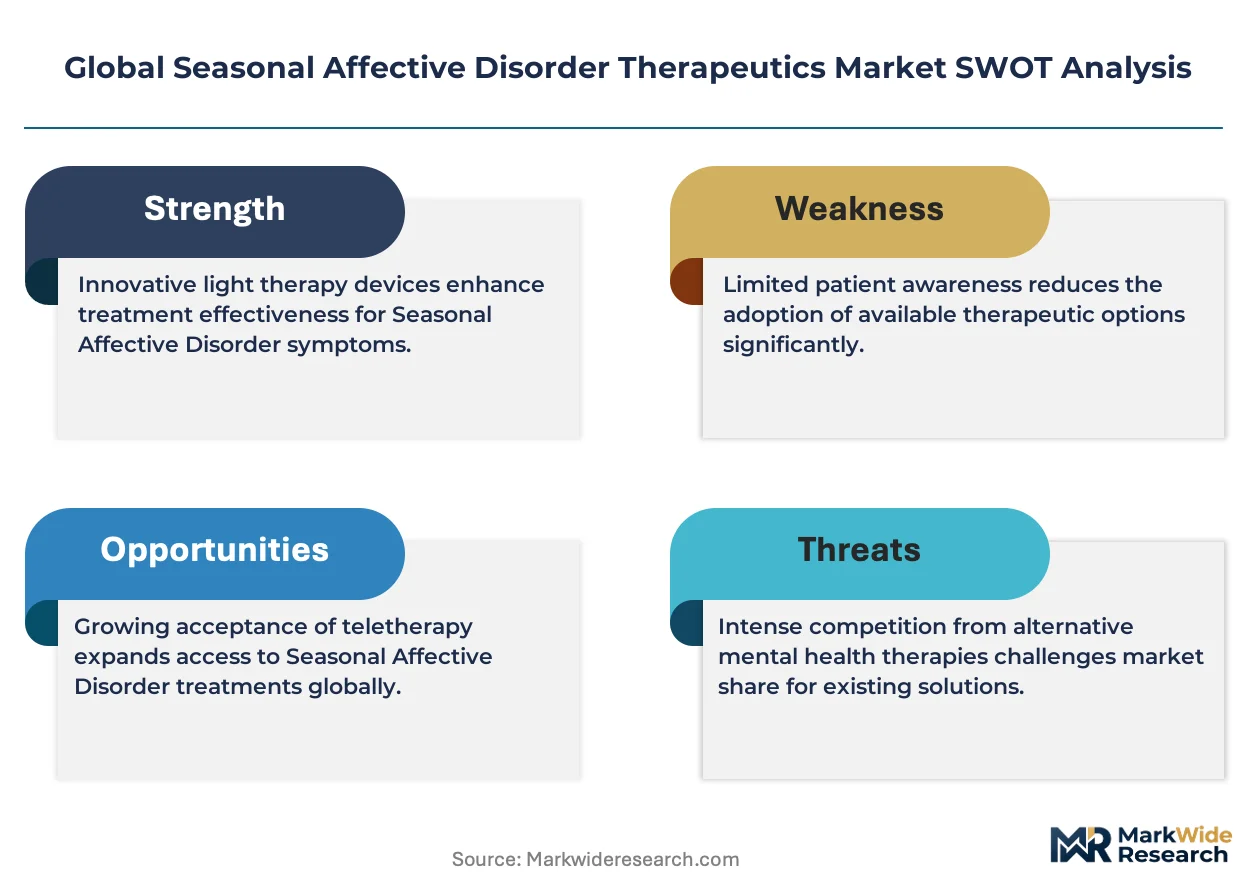
Seasonal Affective Disorder therapeutics comprise clinical interventions targeting recurrent depressive episodes linked to seasonal light variation, primarily employing 10,000-lux light boxes, selective serotonin reuptake inhibitors, and cognitive behavioral protocols adapted for circadian rhythm modulation. Pharmacotherapy retains the largest revenue share given established reimbursement, though telehealth platforms represent the fastest-expanding delivery mode as asynchronous prescribing and remote light therapy monitoring reduce geographic barriers to specialist access. Wearable devices integrating circadian tracking with personalized light dosing protocols are emerging as a concentrated margin pool for technology-enabled entrants.
FDA review standards for antidepressant efficacy endpoints and EMA's MDR framework for light-emitting medical devices jointly determine product classification and commercialization timelines across major markets. The EU AI Act and FDA software-as-medical-device guidance are reshaping regulatory boundaries for algorithm-driven mood monitoring tools. Stakeholders must monitor evolving digital therapeutics reimbursement decisions by CMS and national health technology assessment bodies to calibrate portfolio allocation between hardware, pharmaceutical, and platform-based modalities.
Market Dynamics
Telehealth platforms are compressing the geographic distance between psychiatric specialists and patients in high-latitude regions, fundamentally restructuring how Seasonal Affective Disorder interventions reach underserved populations previously constrained by specialist scarcity.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:The FDA's clarified pathway for algorithm-driven mood monitoring tools is accelerating commercialization timelines for digital therapeutics developers seeking antidepressant adjunct indications.
- Japan's Aging Demographics:METI-funded mental health infrastructure investments in northern prefectures are expanding reimbursed access to light therapy protocols among elderly populations with limited mobility.
- Circadian-Tracking Wearables:Consumer-grade biometric sensors with medical-grade light exposure logging are creating de novo patient data streams that validate personalized dosing algorithms for clinicians.
Market Restraints
- Reimbursement Fragmentation:CMS and Germany's G-BA maintain divergent coverage criteria for light-emitting medical devices, forcing manufacturers to maintain parallel clinical evidence packages for transatlantic market entry.
- Specialist Concentration:Psychiatrist density in rural Canada and Nordic peripheries remains below treatment thresholds, creating persistent access bottlenecks despite telehealth expansion.
- SSRI Substitution Economics:Generic fluoxetine and sertraline formulations command minimal out-of-pocket costs, compressing pricing headroom for novel mechanism antidepressants in seasonal indication trials.
Strategic Opportunities
- Algorithmic Mood Prediction:Convergence of continuous photometry sensors with machine learning-based affective forecasting is opening preventive intervention windows before symptom onset.
- Employer-Sponsored Mental Health:Large self-insured corporations in the United States are adding seasonal depression screening to annual wellness programs, creating direct-to-employer channel bypassing traditional payer gatekeeping.
- EMA MDR Streamlining:The European Medical Device Regulation's consolidated technical documentation requirements for light therapy hardware is reducing regulatory duplication across EU member states.
Industry Challenges
- Digital Therapeutics Credentialing:Platform developers face extended validation timelines demonstrating non-inferiority to established CBT protocols for seasonal depression, straining runway financing.
- Hardware-Software Integration Complexity:Wearable manufacturers encounter firmware synchronization failures between circadian-tracking bands and prescription-grade light boxes, degrading clinical confidence in integrated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seasonal Affective Disorder Therapeutics Market |
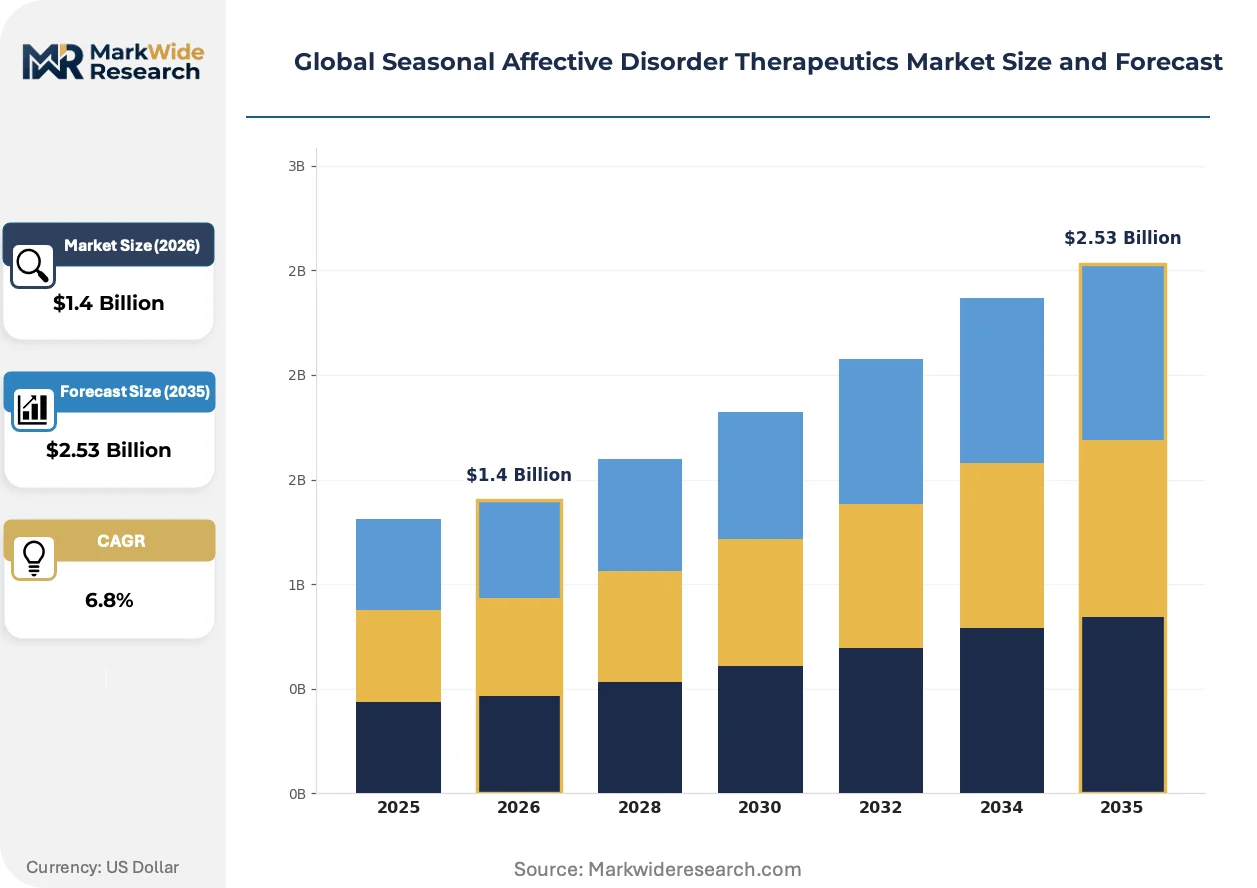
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Light Therapy, Pharmacotherapy, Psychotherapy, Vitamin D Supplementation, Mindfulness-Based Therapy Indication: Winter Depression, Bipolar Depression, Atypical Depression, Anxiety Comorbidities, Sleep Disorders End User: Psychiatric Clinics, Mental Health Centers, Private Practices, Telehealth Platforms, Rehabilitation Facilities Delivery Mode: In-Clinic Sessions, Home Treatment Devices, Mobile Applications, Wearable Devices, Online Counseling |
| Companies Covered | Pfizer Inc., Johnson & Johnson, AbbVie Inc., Novartis AG, GlaxoSmithKline plc, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Bausch Health Companies Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seasonal Affective Disorder Therapeutics Market Shifts & Advancements
Intervention delivery modes are fragmenting across synchronous telepsychiatry, asynchronous prescription platforms, and fully automated light-dosing protocols, creating parallel patient journeys with diverging clinical oversight requirements.
Smart light boxes with embedded photoreceptor-response modeling are bifurcating the hardware segment into clinical-grade 10,000-lux units and consumer-tier variable-intensity devices. Psychiatric clinics in Germany and the United States are adopting the clinical tier for supervised protocols, while direct-to-consumer channels absorb the variable-intensity category for self-managed cases. This technology is bifurcating the prescriber base into specialists who retain hardware oversight and primary care physicians who delegate to patient-controlled systems.
The EU AI Act's risk-classification framework for biometric mood inference algorithms is imposing conformity assessment obligations on wearable manufacturers previously operating under general consumer electronics standards. Developers must now maintain technical documentation demonstrating algorithmic transparency for affective state predictions used in therapeutic recommendations. French and Dutch notified bodies are processing the first wave of CE-mark applications under these expanded requirements, with decisions expected to establish precedent for algorithmic antidepressant adjuncts.
Patients in northern latitudes are consolidating their mental health spending with integrated platforms offering seasonal screening, light therapy hardware subscription, and psychiatric consultation bundles. Traditional discrete reimbursement for hardware purchase and professional service is yielding to annual subscription models in Sweden and Finland. This consolidation is most visible among working-age populations aged 35-55 with employer-sponsored flexible spending accounts, who prefer predictable budgeting over episodic out-of-pocket costs.
Global Seasonal Affective Disorder Therapeutics Market Segmentation
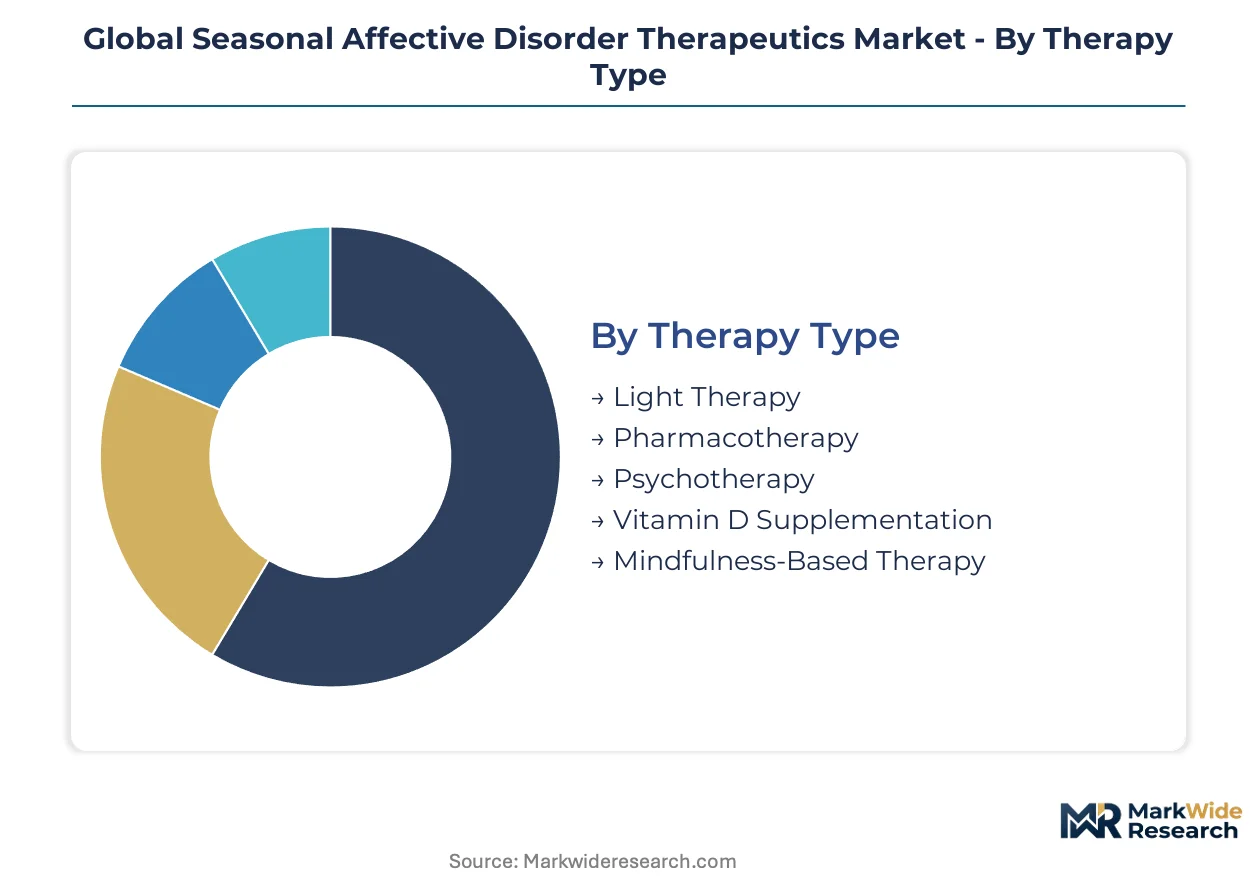
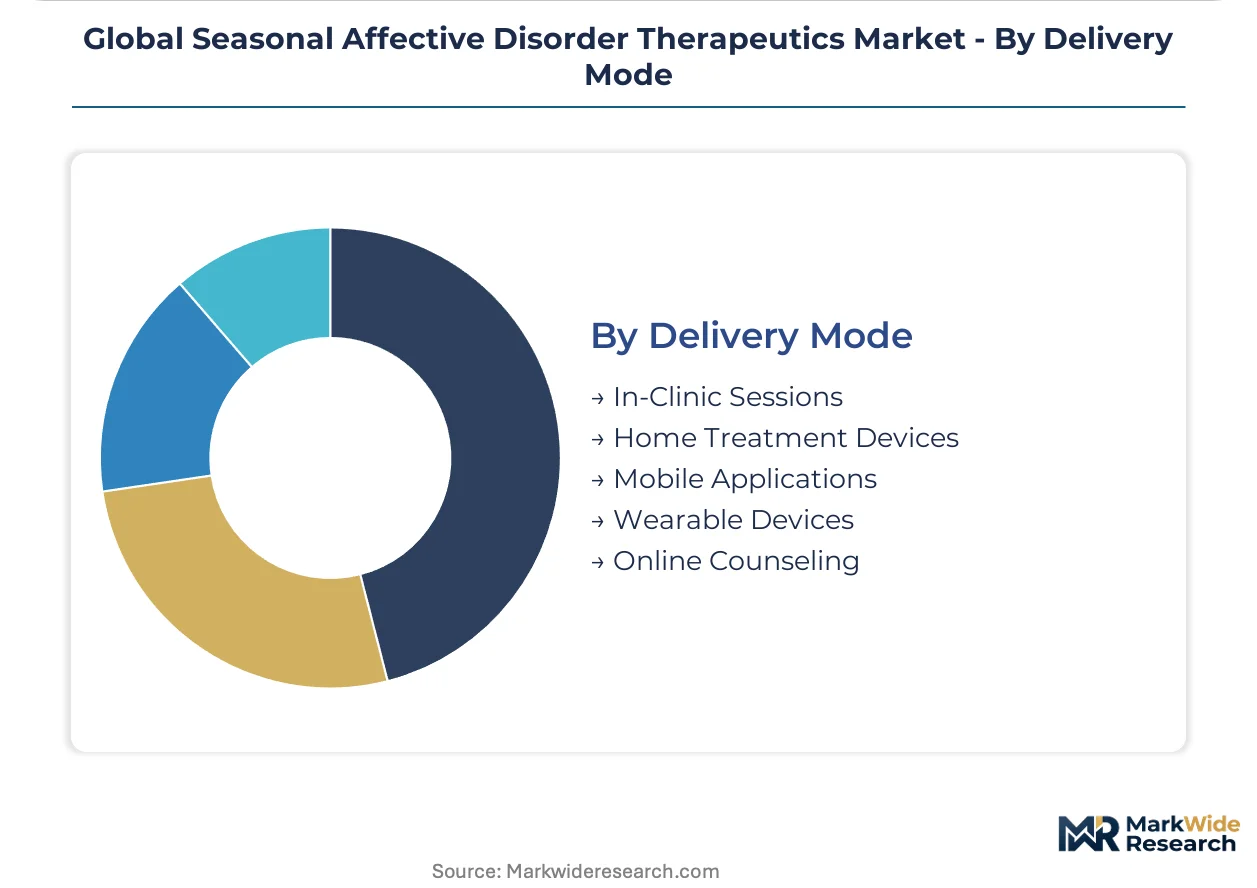
Therapy type and delivery mode configurations determine reimbursement pathways and margin structures across the SAD therapeutics landscape. Channel economics favor integrated platforms over discrete hardware or pharmaceutical transactions.
Therapy Type:
Light therapy and pharmacotherapy command distinct distribution channels, with the former flowing through durable medical equipment suppliers and the latter through pharmacy benefit managers.
- Light Therapy:10,000-lux light boxes with melanopsin-tuned spectra dominate clinical protocols. Psychiatric clinics in Minneapolis, Hamburg, and Sapporo deploy these for supervised morning sessions, though home-use subscriptions are displacing one-time hardware purchases.
- Pharmacotherapy:SSRIs and novel mechanism antidepressants retain the largest reimbursed share. Fluoxetine and bupropion formulations anchor seasonal indication prescribing in the United States and Germany, where formulary placement determines physician preference.
- Psychotherapy:CBT protocols adapted for circadian rhythm modulation require specialist delivery.
- Vitamin D Supplementation:Adjunctive use concentrates in Nordic populations with documented deficiency.
- Mindfulness-Based Therapy:Digital delivery through employer wellness platforms expands reach among working-age cohorts.
By volume, pharmacotherapy leads. By growth pace, light therapy subscriptions are climbing the fastest.
Indication:
Cost tier stratification separates acute episodic intervention from chronic comorbidity management, with the latter commanding sustained reimbursement.
- Winter Depression:Core seasonal affective disorder indication with established DSM-5 criteria drives the majority of clinical trial enrollment and regulatory submissions. United States and Japanese regulators have issued specific guidance for seasonal pattern documentation.
- Bipolar Depression:Seasonal variation in bipolar II disorder represents a high-acuity subset requiring mood stabilizer co-prescription. Specialist psychiatrists in Boston and Zurich academic medical centers manage these complex cases through structured protocols.
- Atypical Depression:Hypersomnia and weight gain phenotypes overlap with seasonal presentation.
- Anxiety Comorbidities:Generalized anxiety disorder with seasonal exacerbation expands addressable population.
- Sleep Disorders:Delayed sleep phase syndrome with seasonal worsening creates diagnostic overlap.
Winter depression captures the greatest patient volume. Bipolar depression shows the steepest expansion trajectory in specialist referral networks.
End User:
Customer type concentration shapes sales force deployment, with telehealth platforms requiring zero field presence compared to clinic-based detailing.
- Psychiatric Clinics:Academic and community-based specialists in Toronto, Manchester, and Stockholm academic centers prescribe multi-modal protocols combining light boxes with pharmacotherapy. These sites generate the highest per-patient revenue through bundled episode-of-care payments.
- Telehealth Platforms:Asynchronous prescribing and remote light therapy monitoring reduce geographic barriers to specialist access. Platforms serving rural Canada and Finnish Lapland report the fastest subscriber acquisition among underserved latitudes.
- Mental Health Centers:County and municipal facilities handle publicly insured populations.
- Private Practices:Solo and group psychiatrists in suburban United States markets drive SSRI prescribing.
- Rehabilitation Facilities:Substance use disorder programs with seasonal depression comorbidity.
Psychiatric clinics retain the highest prescription value per encounter. Telehealth platforms are gaining share fastest among new patient acquisitions.
Delivery Mode:
Maturity gradients separate decades-old in-clinic models from emerging wearable and application-based modalities still seeking reimbursement codes.
- Home Treatment Devices:Prescription-grade light boxes with connected monitoring capabilities anchor the hardware segment. German statutory health insurance funds reimburse these for documented seasonal episodes, while United States patients rely on flexible spending accounts.
- Wearable Devices:Circadian-tracking bands with medical-grade photometry logging create de novo patient data streams. Developers in California and Massachusetts are pursuing FDA software-as-medical-device clearance for algorithm-driven dosing recommendations.
- In-Clinic Sessions:Supervised light therapy with psychiatric oversight retains reimbursement in Japan and Germany.
- Mobile Applications:Mood tracking and CBT delivery tools face credentialing delays.
- Online Counseling:Synchronous and asynchronous psychotherapy delivery expands access.
Home treatment devices lead by installed base. Wearable devices are expanding most quickly as biometric sensor costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the United States substantially exceeds that in peripheral Nordic markets, where generic SSRI saturation and limited reimbursement for light therapy hardware compress margins. This asymmetry drives divergent commercial strategies across major demand centers.
United States
Employer-sponsored flexible spending accounts fund light therapy hardware purchases for seasonal depression protocols in Minneapolis, Boston, and Seattle metropolitan clusters. FDA software-as-medical-device guidance accelerates clearance timelines for algorithm-driven mood monitoring tools developed in California and Massachusetts. Psychiatric clinics in academic medical centers anchor multi-modal prescribing combining pharmacotherapy with supervised light box protocols.
Germany
Statutory health insurance funds reimburse prescription-grade 10,000-lux light boxes for documented seasonal episodes, sustaining higher hardware margins than self-pay markets. EMA's MDR framework for light-emitting medical devices shapes conformity assessment obligations for manufacturers targeting Hamburg and Munich clinical networks. Bavarian and North Rhine-Westphalian psychiatric practices drive bundled episode-of-care payments for combined light therapy and pharmacotherapy interventions.
Japan
METI-funded mental health infrastructure investments in Hokkaido and northern Tohoku prefectures expand reimbursed access to light therapy among elderly populations with limited mobility. PMDA review standards for antidepressant seasonal indications require specific pattern documentation in regulatory submissions. Sapporo academic medical centers manage complex bipolar depression cases with seasonal variation through structured specialist protocols.
Canada
Psychiatrist density in rural Ontario, Quebec, and Prairie provinces remains below treatment thresholds despite telehealth platform expansion into underserved latitudes. Health Canada regulates light-emitting medical devices under the Medical Devices Regulations, parallel to FDA pathways but with distinct clinical evidence requirements. Toronto and Vancouver academic centers generate the highest per-patient revenue through bundled care models, while remote northern communities rely on asynchronous prescribing platforms.
Sweden
Working-age populations aged 35-55 in Stockholm and Gothenburg consolidate mental health spending with integrated platform subscriptions covering seasonal screening, hardware access, and psychiatric consultation. The country's national pharmaceutical regulator maintains reimbursement criteria that favor established SSRI formulations over novel mechanism antidepressants for seasonal indications. Annual subscription models displace discrete hardware purchases and professional service billing among employer-sponsored flexible spending account holders.
Global Seasonal Affective Disorder Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SAD therapeutics landscape. Established pharmaceutical conglomerates with diversified neuroscience pipelines anchor the pharmacotherapy segment, while specialized hardware manufacturers and digital health platforms compete on delivery innovation. Three strategic archetypes dominate: diversified pharma incumbents leveraging antidepressant portfolios, technology-enabled entrants integrating wearable sensors with algorithmic dosing, and telehealth platforms compressing geographic access barriers. Competitive moves concentrate on portfolio diversification into digital adjuncts and strategic partnerships bridging hardware-software integration gaps.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Johnson & Johnson, and Eli Lilly and Company exemplify distinct positioning archetypes. Pfizer occupies a position sustained through established antidepressant formulary placements across European markets. Johnson & Johnson anchors its presence through diversified neuroscience pipelines spanning pharmacotherapy and digital adjunct modalities. Eli Lilly represents R&D intensity in novel mechanism antidepressants, differentiating from generic SSRI substitution economics that dominate seasonal indication prescribing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Bausch Health Companies Inc. |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservation agreements between telehealth platforms and light therapy hardware manufacturers lock in supply access while anchoring predictable unit economics for seasonal depression intervention bundles across United States and German markets.
Pricing Analysis
The customization-premium spread between clinical-grade 10,000-lux light boxes with melanopsin-tuned spectra and consumer-tier variable-intensity devices spans threefold to fivefold at point of purchase. Subscription models favoring annual hardware access plus psychiatric consultation bundles displace discrete transactional pricing among working-age cohorts in Sweden and Finland. Price differentiation hinges on FDA software-as-medical-device clearance tier and bundled after-sales monitoring services. Cost compression in the consumer tier intensifies as generic wearable photometry sensors flood direct-to-consumer channels. Employer-sponsored flexible spending account holders show lowest price sensitivity; self-pay rural patients in Nordic peripheries exhibit highest.
Supply Chain Analysis
Strait of Malacca transit for lithium-ion battery cells and precision photodiode components from Taiwan and South Korea underwrites just-in-time assembly schedules for circadian-tracking wearable manufacturers in California and Massachusetts. German optical engineering houses and Japanese precision electronics suppliers anchor clinical-grade light box production. Raw material dependencies span rare-earth phosphors for spectrum tuning, medical-grade polymers for housing biocompatibility, and semiconductor wafers for sensor integration. Single-source vulnerability concentrates in Taiwanese foundry capacity for photoreceptor-response modeling chipsets. Distribution runs through durable medical equipment suppliers for clinical channels and direct-to-consumer logistics for subscription hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Seasonal Affective Disorder therapeutics is approaching an inflection where interoperability between wearable circadian sensors, prescription light boxes, and asynchronous psychiatric consultation determines patient retention and lifetime value capture.
For Market Incumbents: Consolidate formulary positions by deepening backward integration into melanopsin-tuned LED supply chains and securing exclusive capacity reservation agreements with telehealth platforms serving high-latitude underserved regions. Generic SSRI substitution economics and algorithm-driven mood monitoring entrants threaten established pharmacotherapy margins. Certification investment in FDA software-as-medical-device clearance for companion algorithms represents the critical defensive lever. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-track for algorithm-driven light dosing protocols opens regulatory pathways with compressed validation timelines compared to full antidepressant trials. White-space targets center on bipolar depression with seasonal variation in academic medical center networks and employer-sponsored mental health programs at self-insured corporations. Rural Canadian and Finnish Lapland telehealth subscriber acquisition offers the most penetrable geography. Go-to-market execution should anchor in direct-to-employer channel partnerships bypassing traditional payer gatekeeping. For Investors and Strategic Acquirers: Specialized digital therapeutics developers with validated non-inferiority data against CBT protocols for seasonal depression represent the priority acquisition archetype. Long-term viability over a multi-year horizon hinges on CMS reimbursement code attainment for algorithm-driven mood monitoring and EMA MDR conformity assessment completion for integrated hardware-software systems. The signal to watch is Health Technology Assessment body decisions in Germany and Sweden establishing precedent for platform-based seasonal depression intervention reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates commercialization timelines for algorithm-driven mood monitoring tools in California development clusters. |
| EMA MDR Conformity Assessment | Unlocks bundled hardware-software reimbursement in German statutory health insurance funds. |
| Telehealth Platform Partnership | Compresses geographic barriers to specialist access in rural Canadian and Nordic peripheries. |
| Employer Wellness Program Integration | Bypasses traditional payer gatekeeping through direct-to-corporation seasonal depression screening contracts. |
| Circadian-Tracking Wearable Development | Creates de novo patient data streams validating personalized light dosing algorithms for clinicians. |
Research Methodology
A standing panel of psychiatric clinic directors, telehealth platform executives, formulary access specialists, and biomedical engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov seasonal depression protocol registrations, and German G-BA reimbursement decision records. Bottom-up patient volume modeling by therapy type and delivery mode converged with top-down pharmaceutical and medical device revenue triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by therapy type, indication severity tier, end-user channel, and delivery mode maturity gradient. CAGRs were derived from regression analysis of historical adoption curves and regulatory approval timeline distributions. Forecast inputs incorporated PMDA seasonal indication guidance evolution and METI-funded mental health infrastructure investment trajectories in northern Japanese prefectures.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement code expansion for digital therapeutics or hardware-software integration reliability thresholds would require recalibration. Forecasts reflect assumptions regarding regulatory pathway clarity and employer-sponsored mental health program penetration. Revision becomes warranted when CMS national coverage determination for algorithm-driven mood monitoring crosses threshold decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Japan Generic Drug Market