
 Medicinal Fungi Market | 2026-2036
Medicinal Fungi Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Fungi Market Analytics
The capability gap between indoor-cultivated and wild-harvested supply chains is collapsing as extraction standardization becomes the decisive cost driver. Host Defense leverages USDA-certified organic mycelium to anchor premium positioning across North American wellness channels. Nammex competes through deep backward integration into Chinese fruiting body cultivation, controlling raw material quality from substrate to finished extract. Aloha Medicinals specializes in liquid fermentation systems that sustain pharmaceutical-grade output for contract manufacturing clients.
Medicinal fungi comprise macroscopic basidiomycetes and ascomycetes cultivated or wild-harvested for bioactive compounds including beta-glucans, triterpenoids, and erinacines, with primary commercial purpose centered on immune modulation, cognitive support, and metabolic health applications. Extracts dominate value capture due to higher bioactive concentration and dosing precision, while functional foods represent the fastest-expanding application as beverage and snack brands incorporate lion's mane and reishi into mainstream formulations. Capsule delivery formats lead pharmacy and homecare channels, whereas tinctures occupy growing shelf space in wellness centers seeking customizable dosing protocols.
FDA Current Good Manufacturing Practice regulations for dietary supplements and EFSA novel food authorization requirements shape product development timelines and cross-border market access for concentrated extracts. China's NMPA traditional medicine standards and SAMR food safety frameworks further dictate export eligibility for mycelium-based ingredients entering Asian pharmaceutical supply chains. Stakeholders must monitor evolving pharmacopeial monographs and adapt extraction documentation to preempt compliance barriers in priority destination markets.
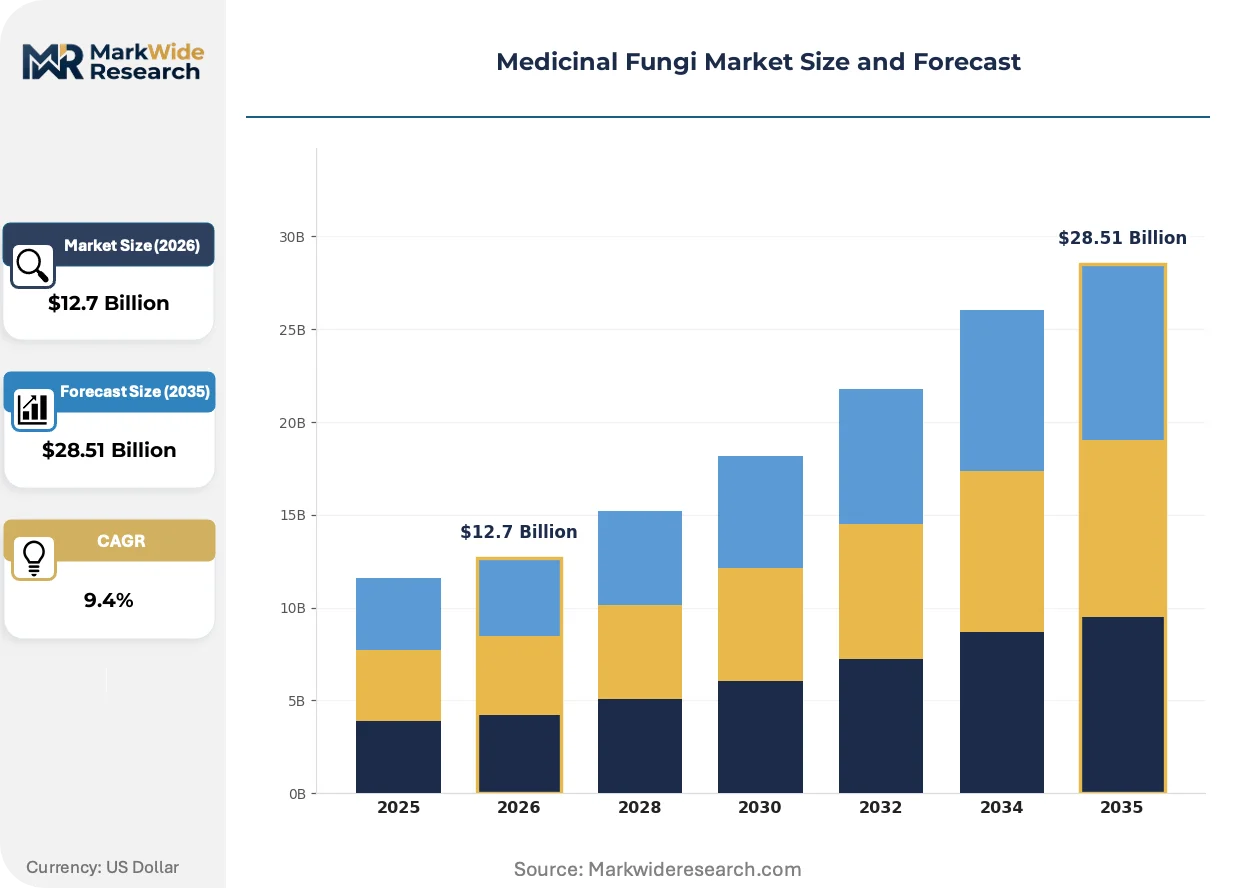
Market Dynamics
Extraction standardization is collapsing the historical capability gap between indoor-cultivated and wild-harvested supply chains, compressing cost structures and redistributing margin capture toward processors with pharmaceutical-grade documentation systems.
Growth Catalysts
- NMPA Traditional Medicine Integration:China's pharmaceutical regulator accelerates bulk extract consumption through hospital formulary inclusion and reimbursement coding for polysaccharide-based immune therapies.
- EFSA Novel Food Pathway:The European framework's clarified safety assessment protocols for concentrated fungal extracts reduce market entry timelines for lion's mane and reishi ingredients in functional beverages.
- Liquid Fermentation Scale-Up:Bioreactor-based mycelium production achieves pharmaceutical-grade consistency at costs below fruiting body cultivation, attracting contract manufacturing demand from nutraceutical brands.
Market Restraints
- Wild-Harvest Input Volatility:Cordyceps sinensis collection from Tibetan highlands faces climate-induced yield fluctuations and strict harvest quotas, creating raw material price spikes that propagate through premium extract tiers.
- FDA cGMP Documentation Burden:Dietary supplement identity testing requirements for fungal materials impose analytical costs that disproportionately constrain small-batch tincture producers lacking in-house chromatography capabilities.
- Plant-Based Substitute Encroachment:Synthetic beta-glucan from yeast fermentation and algae-derived immune modulators capture formulation slots in cost-sensitive supplement SKUs, pressuring commodity fungal extract pricing.
Strategic Opportunities
- South Korean Functional Food Pipeline:MFDS regulatory recognition of erinacine compounds for cognitive health claims creates first-mover positioning for lion's mane extract suppliers targeting the country's $2.3 billion brain health supplement retail channel.
- Precision Fermentation Convergence:Integration of CRISPR-edited fungal strains with continuous bioprocessing enables custom bioactive profiles unattainable through conventional extraction, opening pharmaceutical partnership channels.
- Direct-to-Practitioner Distribution:Wellness centers and integrative medicine clinics seek customizable dosing protocols bypassing retail markup structures, creating margin-rich B2B channels for analytical-grade tincture suppliers.
Industry Challenges
- Phytochemist Talent Scarcity:Extraction facilities struggle to recruit analytical chemists with dual competency in HPLC method development and fungal taxonomy, delaying pharmacopeial monograph compliance documentation.
- Dual-Use Export Classification Complexity:Concentrated triterpenoid extracts face controlled substance screening in multiple jurisdictions, requiring legal specialization that smaller processors cannot maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Fungi Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reishi, Lion's Mane, Chaga, Cordyceps Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Functional Foods End User: Hospitals, Wellness Centers, Pharmacies, Homecare Form: Extracts, Powders, Capsules, Tinctures |
| Companies Covered | Host Defense, Real Mushrooms, Nammex, Four Sigmatic, Monterey Mushrooms, Hirano Mushroom LLC, Mitoku Company Ltd, Aloha Medicinals, Hokkaido Reishi Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Fungi Market Evolving Landscape
Bioprocessing automation and analytical standardization are compressing production timelines while regulatory clarity in major jurisdictions enables cross-border formulation partnerships previously blocked by novel food uncertainty.
Submerged liquid fermentation systems producing pharmaceutical-grade mycelium biomass are displacing traditional solid-state cultivation for high-value compounds like erinacines and hericenones. Nutraceutical contract manufacturers in North America and Europe are adopting these bioreactor platforms to secure batch-to-batch consistency for clinical trial supply. The technology is displacing artisan-scale fruiting body suppliers from premium cognitive health formulations where bioactive standardization outweighs organic certification appeal.
EFSA's 2023 updated guidance on fungal novel food safety assessments establishes clearer toxicity testing thresholds for concentrated extracts entering European functional food applications. The framework mandates full compositional characterization including secondary metabolite profiling, extending development timelines but reducing post-market withdrawal risk. Botanical extract houses in Italy and Germany are responding by building dedicated mycology analytical divisions to preempt authorization delays.
Ingredient sourcing decisions now pivot on certificate-of-analysis transparency rather than geographic provenance claims. Large supplement brands are consolidating vendor panels to processors offering triple-tested beta-glucan content verification with batch-level QR traceability. This specification compression is most visible in United States direct-to-consumer channels where Amazon review systems amplify quality discrepancy penalties and reward documented purity investments.
Medicinal Fungi Market Segmentation
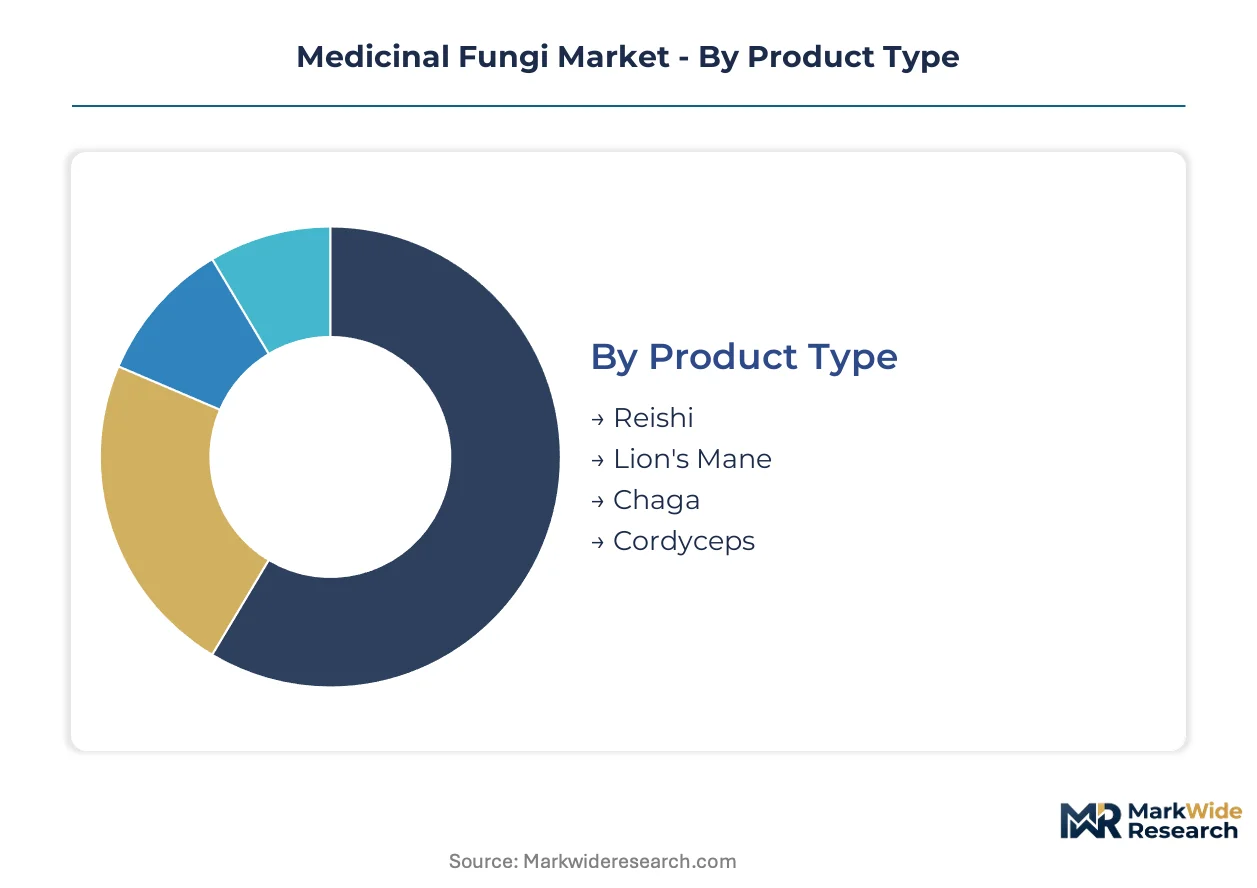
Medicinal fungi segmentation reflects divergent regulatory pathways across end-use categories. Product type selection determines applicable pharmacopeial standards, while form factor dictates documentation burdens for cross-border trade.
Product Type:
FDA dietary supplement identity requirements and NMPA traditional medicine monographs create divergent compliance profiles across species.
- Reishi:Triterpenoid-rich fruiting body extracts dominate immune-modulation formulations. Hospital procurement in China absorbs bulk polysaccharide concentrates under NMPA reimbursement codes for adjuvant cancer therapy.
- Lion's Mane:Erinacine and hericenone compounds drive cognitive health applications. South Korean MFDS recognition of nootropic claims accelerates extract demand through Seoul's functional food retail network.
- Chaga:Wild-harvested betulinic acid sources face sustainability constraints. Finnish and Russian suppliers control premium tier access through boreal forest concession agreements.
- Cordyceps:Climate volatility in Tibetan harvest zones propagates price instability. Liquid fermentation alternatives from Aloha Medicinals and Host Defense capture pharmaceutical contract manufacturing slots.
Established volume favors Reishi; emerging adoption favors Lion's Mane.
Application:
End-use category determines analytical documentation depth and batch release protocols.
- Nutraceuticals:Dietary supplement brands dominate procurement volume. EFSA novel food assessments for concentrated extracts extend European market entry timelines but reduce post-market withdrawal exposure.
- Pharmaceuticals:Polysaccharide-based immune therapies require pharmacopeial compliance. NMPA hospital formulary inclusion in China drives bulk extract consumption through state procurement channels.
- Cosmetics:Topical adaptogen claims face minimal regulatory barriers. Korean and Japanese beauty brands incorporate fermented mycelium filtrates into premium skincare lines.
- Functional Foods:Beverage and snack formulations represent the steepest expansion trajectory. Lion's mane and reishi integration into ready-to-drink products accelerates through North American and European wellness retail.
Pharmaceutical applications command specification premiums; functional foods gain share fastest through mainstream distribution.
End User:
Channel selection determines dosing protocol flexibility and margin capture structure.
- Hospitals:Injectable polysaccharide concentrates require sterile manufacturing certification. Chinese public hospital procurement absorbs volume through centralized tender mechanisms.
- Wellness Centers:Customizable tincture dosing protocols attract integrative medicine practitioners. Direct-to-practitioner distribution bypasses retail markup structures for analytical-grade suppliers.
- Pharmacies:Capsule formats lead shelf space allocation. FDA cGMP documentation requirements constrain small-batch supplier participation.
- Homecare:Direct-to-consumer channels amplify quality transparency demands. Amazon review systems reward batch-level QR traceability with purchase conversion premiums.
Hospital procurement anchors volume stability; wellness center channels offer margin expansion.
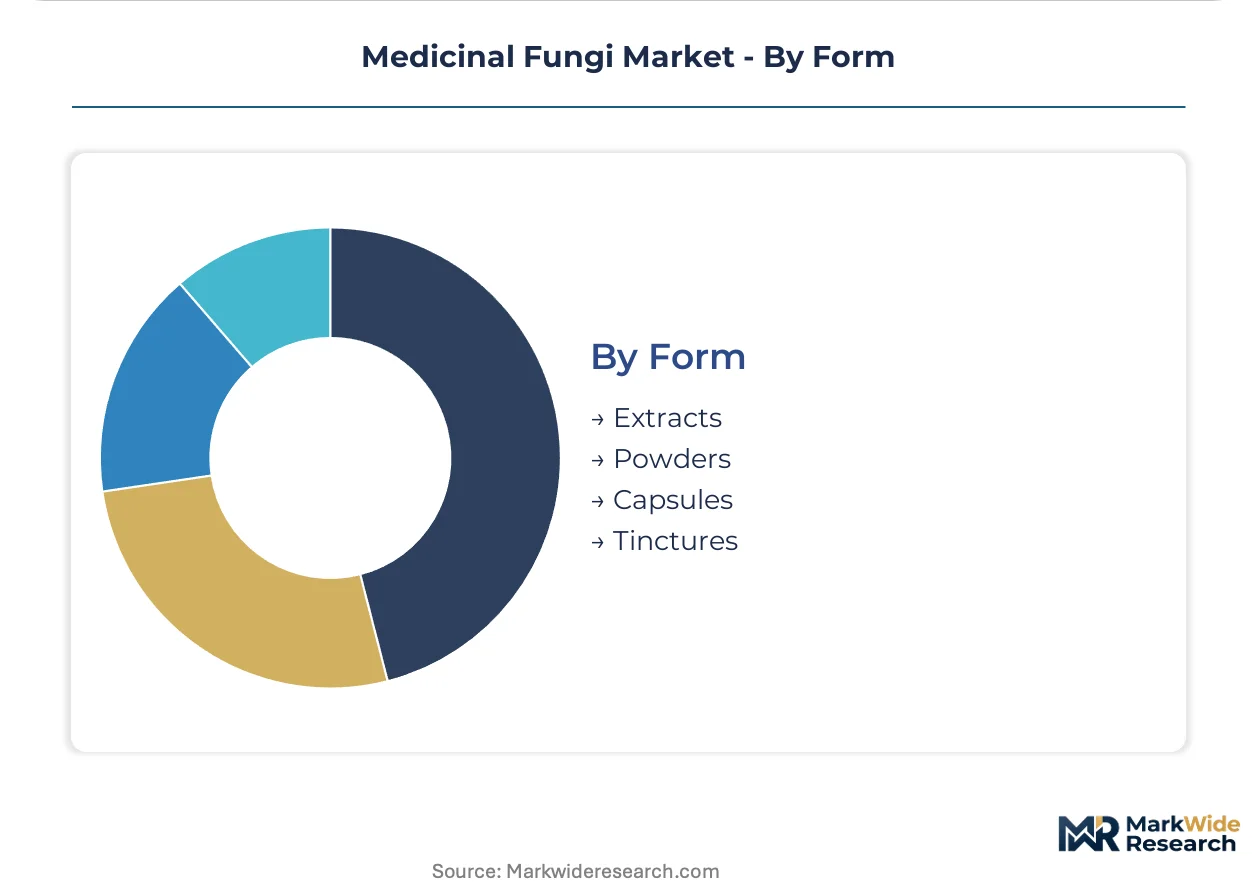
Form:
Processing intensity determines bioactive concentration and cross-border shipping classification.
- Extracts:Standardized beta-glucan and triterpenoid concentrates dominate value capture. Triple-tested verification protocols separate premium suppliers from commodity competitors.
- Powders:Whole fruiting body milling serves cost-sensitive bulk applications. Limited bioavailability drives formulation into combination products.
- Capsules:Precise dosing supports pharmacy and homecare distribution. Gelatin and vegetarian shell options address dietary restriction segments.
- Tinctures:Alcohol-based extraction preserves heat-sensitive compounds. Wellness centers favor customizable concentration protocols for patient-specific protocols.
Extracts concentrate revenue; tinctures expand through practitioner-directed channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Chinese extract processors commanding bulk pharmaceutical procurement, while European functional food brands absorb premium markups for EFSA-compliant novel food authorizations.
China
NMPA hospital formulary inclusion drives bulk polysaccharide concentrate demand through state procurement channels for adjuvant cancer therapy. SAMR food safety frameworks dictate export eligibility for mycelium-based ingredients entering pharmaceutical supply chains. Zhejiang and Fujian provinces host concentrated extraction facilities serving both domestic hospital networks and international nutraceutical contract manufacturers.
United States
FDA dietary supplement cGMP enforcement tightens identity testing requirements for fungal materials, constraining small-batch tincture participation. Amazon review systems amplify quality transparency demands, rewarding batch-level QR traceability with purchase conversion premiums. Pacific Northwest cultivation clusters around Washington and Oregon supply organic-certified fruiting bodies to premium wellness channels.
Germany
EFSA novel food authorization requirements extend development timelines for concentrated extracts entering European functional food applications. Botanical extract houses in Bavaria and Baden-Württemberg build dedicated mycology analytical divisions to preempt authorization delays. Munich-based formulation labs serve as gatekeepers for pan-European supplement brand distribution.
South Korea
MFDS regulatory recognition of erinacine compounds for cognitive health claims accelerates lion's mane extract demand through Seoul's functional food retail network. Direct-to-consumer channels amplify quality verification requirements for brain health supplement positioning. Gyeonggi-do biotech clusters host fermentation facilities supplying pharmaceutical-grade mycelium biomass.
Japan
PMDA pharmaceutical standards and traditional medicine integration sustain demand for reishi and maitake extracts through hospital and clinic channels. Fermented mycelium filtrates penetrate premium skincare lines through Tokyo and Osaka beauty brand partnerships. Hokkaido Reishi anchors domestic supply chains through controlled cultivation rather than wild harvest dependence.
Medicinal Fungi Market Competitive Landscape
Concentration sits with vertically integrated extract processors controlling substrate-to-finished-product documentation. The vendor base stratifies across three tiers: pharmaceutical-grade fermentation specialists, organic-certified fruiting body cultivators, and commodity powder millers. Strategic moves center on backward integration into captive cultivation and pharmacopeial monograph pre-submission to secure hospital procurement eligibility.
Within the fermentation-specialist tier, Aloha Medicinals and Host Defense exemplify pharmaceutical-grade positioning through bioreactor-based mycelium production. Nammex anchors the fruiting body cultivation archetype through Chinese backward integration. Monterey Mushrooms represents scale-driven commodity supply serving cost-sensitive bulk applications. Each occupies distinct pricing tiers based on extraction standardization depth and regulatory documentation completeness.
| Leading Market Players |
|---|
| Host Defense |
| Real Mushrooms |
| Nammex |
| Four Sigmatic |
| Monterey Mushrooms |
| Hirano Mushroom LLC |
| Mitoku Company Ltd |
| Aloha Medicinals |
| Hokkaido Reishi Co. Ltd |
| Others |
Value Network & Pricing Analysis
FDA dietary supplement cGMP regulations gate both supplier qualification and price differentiation simultaneously, as pharmaceutical-grade documentation systems command 40-60% premiums over artisan-scale competitors while excluding small-batch tincture producers from pharmacy and institutional channels.
Pricing Analysis
Configured-to-order pricing for analytical-grade tinctures commands substantial premiums over standardized capsule formats, with triple-tested beta-glucan verification and batch-level QR traceability driving differentiation. Three-tier pricing structure across pharmaceutical-grade, organic-certified, and commodity bulk levels separates Host Defense and Aloha Medicinals from Nammex and powder millers. Pricing pressure stems from yeast-derived synthetic beta-glucan and algae immune modulators capturing cost-sensitive supplement SKUs. Homecare direct-to-consumer channels exhibit highest price sensitivity, while hospital procurement demonstrates lowest sensitivity due to reimbursement coding and formulary inclusion protocols.
Supply Chain Analysis
Tibetan highland cordyceps harvest quotas create a chokepoint propagating volatility through premium extract tiers, with climate-induced yield fluctuations amplifying raw material price spikes. Supply concentration centers on China for fruiting body cultivation and extraction, the United States for organic-certified mycelium fermentation, and Finland for wild-harvested chaga concessions. The chain draws from specific substrate formulations, sterile bioreactor infrastructure, and pharmacopeial reference standards. Single-source vulnerability runs through Tibetan wild-harvest dependence for cordyceps sinensis. Distribution runs through nutraceutical contract manufacturers, direct-to-practitioner wellness centers, and Amazon direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as EFSA novel food authorization frameworks and NMPA hospital formulary systems create interoperable regulatory ecosystems, enabling cross-border formulation partnerships previously blocked by compliance uncertainty.
For Market Incumbents: Consolidate backward integration into captive cultivation and pharmacopeial monograph pre-submission to defend against precision fermentation disruptors. Secure NMPA reimbursement coding eligibility through polysaccharide standardization investments. Channel control through direct-to-practitioner distribution networks anchors margin retention against retail markup compression. For New Entrants and Emerging Players: Direct-to-practitioner service-layer gaps in customizable tincture dosing protocols offer white-space entry, as incumbents under-serve integrative medicine clinics seeking patient-specific formulations. South Korean functional food retail channels present the most penetrable geography given MFDS erinacine recognition. Go-to-market execution should leverage analytical-grade certification as the primary positioning lever against commodity competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid fermentation bioreactor deployments, favoring scaled pharmaceutical-grade output over artisan fruiting body cultivation. Long-term viability across the analysis window favors processors with dual NMPA and FDA documentation capabilities. Acquisition targets should demonstrate pharmacopeial monograph pre-submission progress. The signal to watch is EFSA novel food authorization grant velocity as inflection indicator for European functional food formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Monograph Pre-Submission | Secures NMPA hospital formulary eligibility and FDA dietary supplement identity compliance simultaneously. |
| Liquid Fermentation Scale-Up | Bioreactor-based mycelium production achieves pharmaceutical-grade consistency below fruiting body cultivation costs. |
| Direct-to-Practitioner Distribution Buildout | Bypasses retail markup structures for wellness centers seeking customizable dosing protocols. |
| EFSA Novel Food Authorization Pathway | Reduces European functional beverage market entry timelines for lion's mane and reishi extracts. |
| Triple-Tested Verification Investment | Batch-level QR traceability rewards Amazon review systems with purchase conversion premiums. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction facility operators, nutraceutical contract manufacturing executives, hospital procurement managers, and integrative medicine practitioners; and secondary validation through FDA cGMP inspection records, EFSA novel food submission databases, NMPA reimbursement coding directories, and customs trade data for fungal extract categories. Bottom-up volume modeling triangulated against top-down market sizing from identified producer capacity.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning species type, application category, end-user channel, and geographic regulatory cluster. CAGRs derived from historical volume trajectories adjusted for policy inflection points and technology substitution curves. Forecast inputs incorporated liquid fermentation yield improvements, EFSA authorization velocity, and NMPA traditional medicine integration pace.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement, EFSA novel food assessment protocols, and NMPA hospital formulary systems; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as precision fermentation cost curves and plant-based substitute formulation adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Rupatadine Fumarate API Market