
 Global Aromatase Inhibitors Drug Market | 2026-2036
Global Aromatase Inhibitors Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aromatase Inhibitors Drug Market Intelligence
Capital-intensity divergence between large pharmaceutical conglomerates and mid-size generic specialists is rotating competitive dynamics across the aromatase inhibitors landscape. Pfizer leverages its integrated manufacturing footprint to sustain cost leadership on legacy molecules. AstraZeneca anchors its position through specialized oncology channel relationships and differentiated patient-support programs. Teva Pharmaceutical Industries Ltd competes aggressively on price across multiple geographies while navigating complex tender environments.
Aromatase inhibitors constitute a class of systemic endocrine therapeutics that functionally block the cytochrome P450 enzyme complex responsible for peripheral and tumor-site conversion of androgens to estrogens, with third-generation agents exhibiting sub-nanomolar inhibitory concentration values against the aromatase target. These compounds serve as foundational interventions in hormone receptor-positive breast cancer protocols, operating through estrogen deprivation to arrest malignant cell proliferation. Anastrozole and letrozole occupy the dominant volume positions within the product-type dimension, reflecting their established adjuvant therapy protocols and extensive generic availability. The oral tablet delivery mode captures the principal margin pool due to manufacturing simplicity and patient compliance advantages, while sustained-release formulations represent the fastest-growing innovation trajectory as manufacturers seek patent-protected lifecycle extensions.
FDA oncology drug evaluation standards, EMA centralized marketing authorization procedures, and WHO essential medicines list inclusion criteria collectively govern product registration, reimbursement eligibility, and clinical adoption benchmarks across major markets. These frameworks compel manufacturers to generate robust cardiovascular and bone-density safety data, directly influencing trial design investments and label expansion strategies. Stakeholders must monitor evolving biosimilar substitution policies and real-world evidence requirements as determinants of portfolio prioritization and geographic resource allocation.
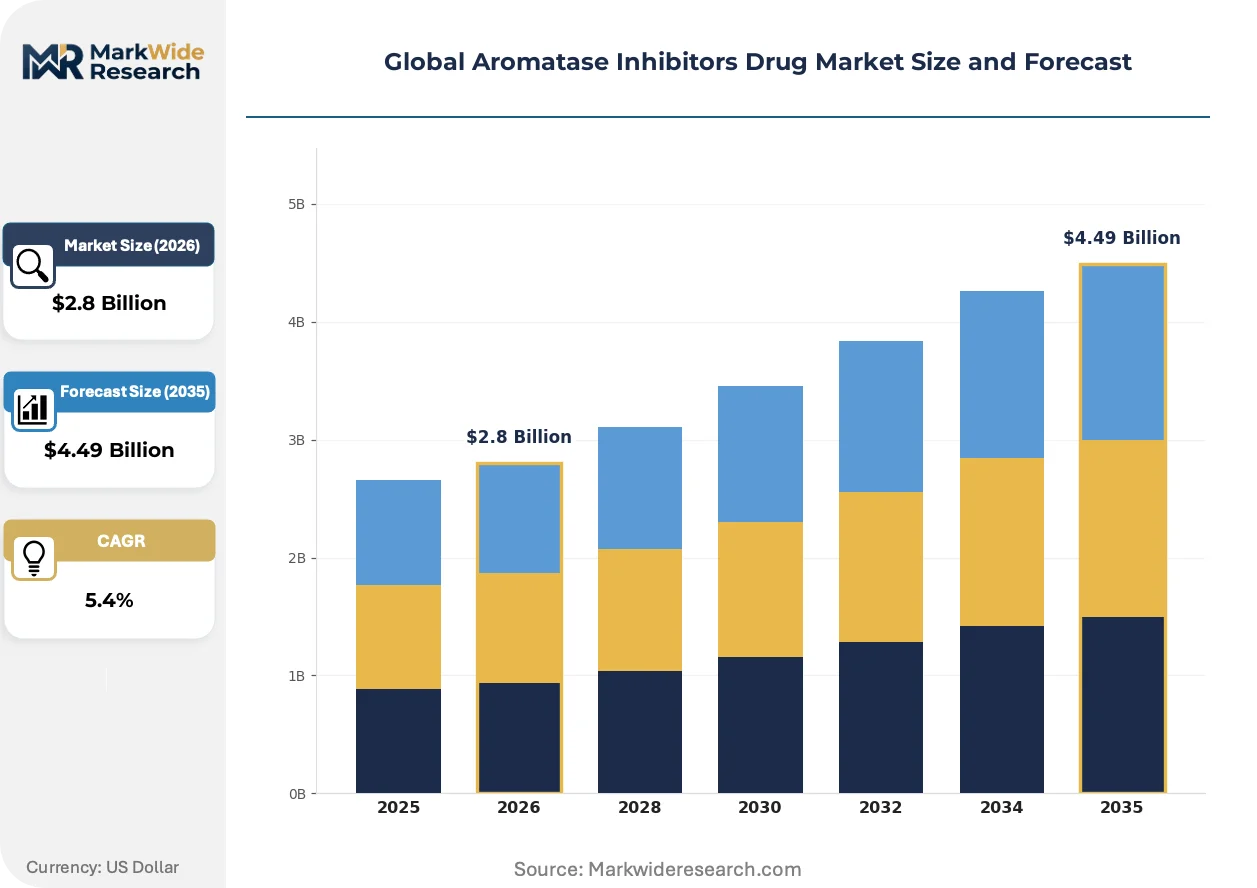
Market Dynamics
Generic substitution pressure is compressing margins on legacy aromatase inhibitors while manufacturers redirect R&D toward sustained-release formulations and companion diagnostics to defend pricing power.
Growth Catalysts
- FDA Accelerated Approval:Oncology manufacturers leverage expedited pathways to bring novel aromatase inhibitor formulations to market faster, compressing development timelines for hormone receptor-positive breast cancer therapies.
- Japan's Expanded Screening Mandates:Population-wide mammography programs in Tokyo and Osaka drive earlier-stage diagnoses, expanding the addressable patient pool for adjuvant endocrine therapy initiation.
- Third-Generation Oral Formulations:Sub-nanomolar potency agents replace earlier-generation compounds in first-line protocols across German oncology centers.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient manufacturing clusters in coastal China create single-source dependency for anastrozole and letrozole precursors.
- Bone Density Monitoring Burden:EMA post-authorization safety requirements mandate extensive cardiovascular and skeletal adverse event tracking, inflating post-market surveillance costs.
- Biosimilar Substitution Threats:Automatic pharmacy-level substitution policies in several US states erode brand loyalty and prescriber control over product selection.
Strategic Opportunities
- India's Tier-2 City Penetration:Underdiagnosed hormone receptor-positive breast cancer cases in Chennai and Hyderabad present expansion vectors for oral endocrine therapy access programs.
- EMA Adaptive Licensing:Conditional approval frameworks enable earlier revenue recognition for sustained-release depot formulations while confirmatory trials continue.
- Telemedicine Integration:Virtual oncology consultations in rural Australia and Canada reduce specialist access barriers, expanding prescription initiation outside traditional academic medical centers.
Industry Challenges
- Real-World Evidence Generation:Payers in Germany and Japan increasingly demand post-marketing comparative effectiveness data, forcing manufacturers to fund expensive patient registry infrastructure.
- Formulation Complexity:Sustained-release polymer engineering requires specialized process analytical technology expertise that mid-size generic houses struggle to acquire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aromatase Inhibitors Drug Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anastrozole, Letrozole, Exemestane, Vorozole Therapy Area: Breast Cancer, Endometrial Cancer, Ovarian Cancer, Gynecologic Conditions End User: Oncology Clinics, Specialized Cancer Centers, Research Institutions, Diagnostic Labs Delivery Mode: Oral Tablets, Injectable Solutions, Sustained Release Formulations, Combination Therapies |
| Companies Covered | Novartis AG, AstraZeneca, Pfizer, Teva Pharmaceutical Industries Ltd, ANI Pharmaceuticals, Hikma Pharmaceuticals, Bristol-Myers Squibb and Company, Viatris, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aromatase Inhibitors Drug Market Strategic Shifts & Innovations
Formulation science and diagnostic integration are rewriting competitive boundaries in endocrine oncology, with manufacturers racing to pair biomarker-guided selection with delivery innovations that extend patent protection.
Polymeric sustained-release depot technologies are bifurcating the oral tablet dominance that has defined aromatase inhibitor administration for two decades. Specialty oncology clinics in the United States and Switzerland are piloting quarterly injectable formulations that improve adherence in elderly populations. This delivery shift is compressing the margin pool available to commoditized oral generic manufacturers while creating protected revenue streams for innovators.
EMA's evolving companion diagnostic co-development guidelines are reshaping trial design requirements for new molecular entities. Manufacturers must now validate biomarker assays concurrently with drug candidates, doubling regulatory submission complexity. Hormone receptor testing laboratories in France and the Netherlands are consolidating to meet heightened certification standards, concentrating diagnostic service provision.
Oncology procurement committees at US integrated delivery networks are unbundling drug acquisition from adherence support services, forcing manufacturers to price components separately. Hospital systems in Texas and Florida now negotiate oral oncology medications through centralized pharmacy benefit managers while sourcing patient education programs from third-party vendors. This purchasing fragmentation is most advanced in Medicare Advantage–dominated markets where total cost of care contracts dominate reimbursement design.
Global Aromatase Inhibitors Drug Market Segmentation
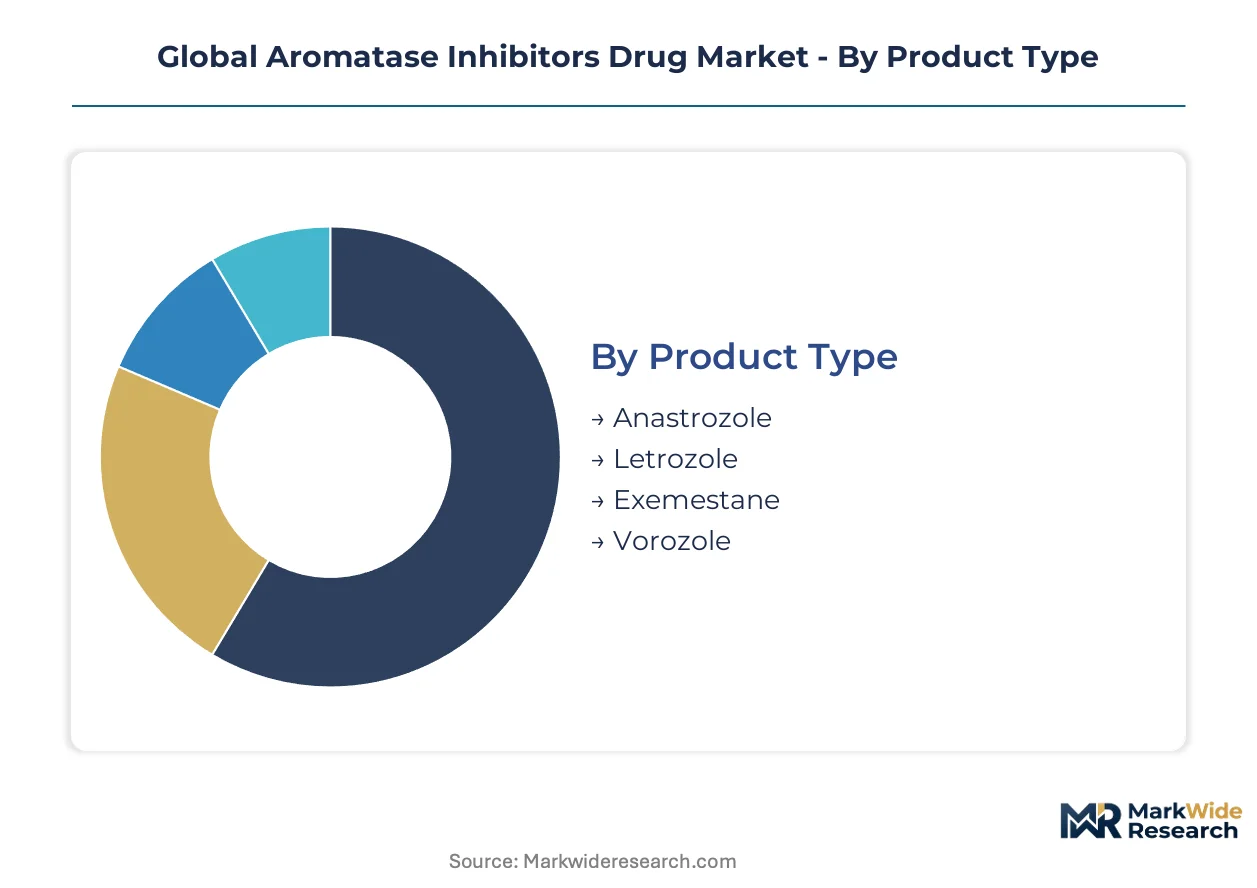
Segmentation in the aromatase inhibitors market reveals how regulatory pathways, clinical protocols, and delivery innovations partition commercial opportunity. Manufacturers align portfolio investments with the specific reimbursement and prescriber dynamics governing each category.
Product Type:
FDA bioequivalence standards and EMA centralized marketing authorization procedures create divergent competitive barriers across molecular variants.
- Anastrozole:This non-steroidal triazole derivative achieves sub-nanomolar aromatase inhibition through reversible competitive binding. German oncology centers and US academic medical centers standardize on this agent for postmenopausal adjuvant therapy, driven by extensive generic availability and established cardiovascular safety databases.
- Letrozole:A potent third-generation triazole with extended terminal half-life enabling once-daily dosing. Demand concentrates in Japan's expanded screening catchment areas and US Medicare Advantage networks where prior authorization pathways favor established molecules with real-world evidence repositories.
- Exemestane:Steroidal suicide inhibitor with irreversible binding kinetics and distinct metabolic profile.
- Vorozole:Earlier-generation compound with limited contemporary utilization in hormone receptor-positive protocols.
Anastrozole handles the majority of throughput; Letrozole is the fastest mover on share.
Therapy Area:
Clinical adoption patterns track the expansion of hormone receptor testing infrastructure and guideline revisions across major markets.
- Breast Cancer:Dominant indication encompassing adjuvant, neoadjuvant, and metastatic settings for hormone receptor-positive subtypes. US integrated delivery networks and French cancer centers drive prescription volumes through standardized endocrine therapy protocols.
- Endometrial Cancer:Off-label utilization in selected estrogen-dependent malignancies with emerging biomarker-defined patient subsets.
- Ovarian Cancer:Limited but growing investigation in hormone-sensitive subpopulations within gynecologic oncology trials.
- Gynecologic Conditions:Non-malignant applications including endometriosis and uterine fibroids with restricted regulatory approval scope.
Breast Cancer commands the principal revenue pool; Endometrial Cancer represents the steepest expansion trajectory as biomarker testing penetrates gynecologic oncology practices.
End User:
Procurement centralization and care delivery restructuring are redistributing volume across institutional categories.
- Oncology Clinics:Community-based infusion centers and medical oncology practices managing long-term adjuvant therapy. Texas and Florida health systems consolidate purchasing through pharmacy benefit managers, compressing margin capture for manufacturers.
- Specialized Cancer Centers:NCI-designated comprehensive cancer centers and European comprehensive cancer networks conducting clinical trials. These institutions influence protocol standardization and subsequent community adoption.
- Research Institutions:Academic medical centers with investigator-initiated trial programs.
- Diagnostic Labs:Hormone receptor testing facilities with expanding companion diagnostic co-development mandates under EMA guidelines.
Oncology Clinics process the highest prescription volumes; Specialized Cancer Centers are gaining share fastest through protocol influence and trial enrollment expansion.
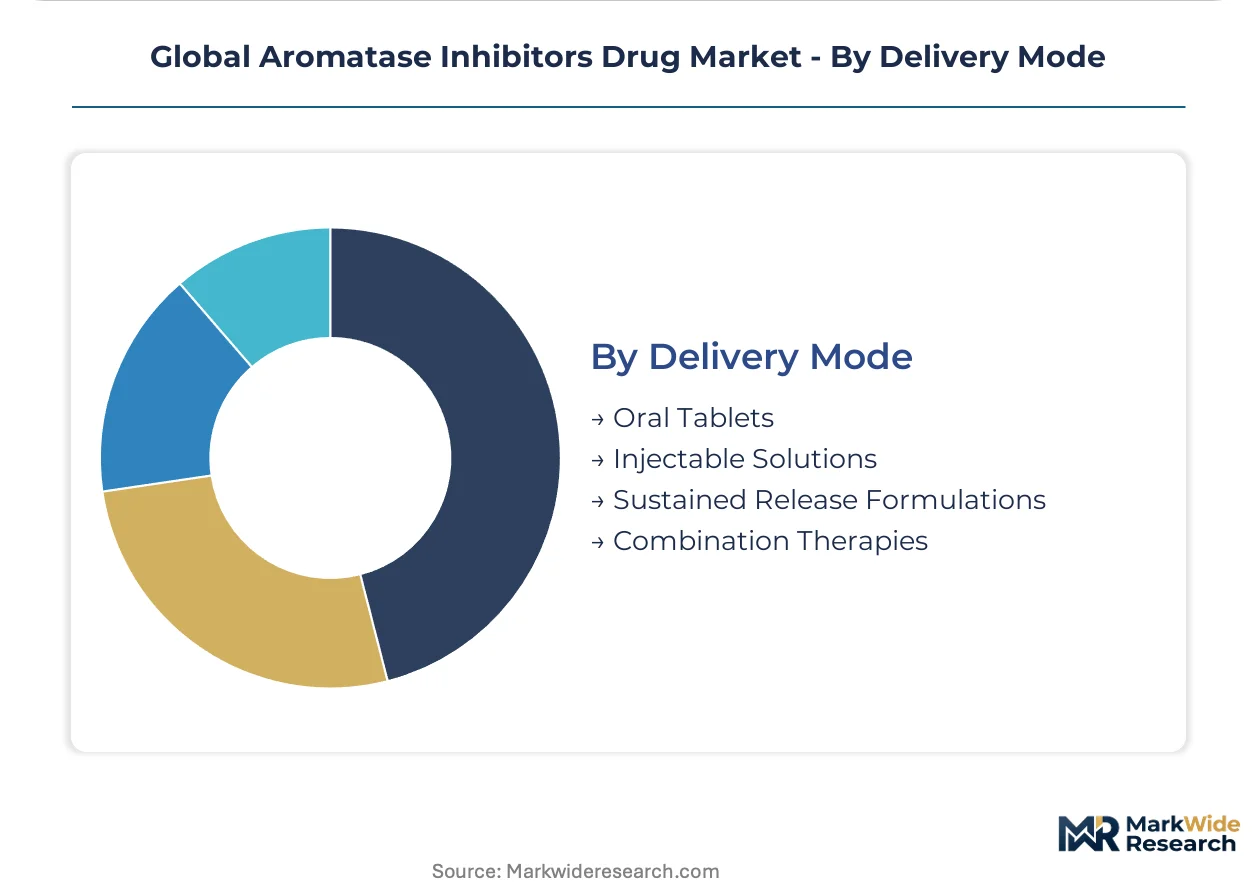
Delivery Mode:
Formulation complexity requirements and patent lifecycle strategies segment manufacturing capabilities and competitive positioning.
- Oral Tablets:Immediate-release solid dosage forms dominating adjuvant therapy with established bioequivalence pathways. Manufacturing concentrates among Indian and Chinese API-integrated generic houses serving cost-sensitive tender markets.
- Sustained Release Formulations:Polymeric depot technologies enabling quarterly administration. Swiss and US specialty clinics pilot these formulations for elderly populations with adherence challenges, creating protected revenue streams.
- Injectable Solutions:Parenteral formulations with limited current market presence.
- Combination Therapies:Fixed-dose or sequential regimens pairing aromatase inhibitors with CDK4/6 inhibitors or other targeted agents.
Oral Tablets handle the majority of throughput; Sustained Release Formulations are expanding most quickly as manufacturers seek lifecycle extensions beyond generic erosion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in aromatase inhibitors reflect concentrated API manufacturing in coastal China against formulation and distribution dominance in Western markets. Import dependency for precursor chemicals shapes procurement strategies across German, Japanese, and US pharmaceutical networks. Regulatory divergence between FDA accelerated pathways and EMA adaptive licensing creates distinct market access timelines.
United States
Medicare Advantage networks in Texas and Florida drive prescription volumes through centralized pharmacy benefit managers. FDA oncology drug evaluation standards mandate extensive cardiovascular safety databases for label expansions. Oncology procurement committees at Houston and Dallas integrated delivery networks unbundle drug acquisition from adherence services.
Germany
Academic medical centers in Munich and Heidelberg standardize third-generation oral formulations for postmenopausal adjuvant therapy. EMA centralized marketing authorization procedures require robust bone-density monitoring protocols. The Rhine-Ruhr pharmaceutical cluster concentrates generic formulation manufacturing for European tender markets.
Japan
Population-wide mammography programs in Tokyo and Osaka expand early-stage diagnosis pools for endocrine therapy initiation. PMDA guidelines align with EMA post-authorization safety requirements for skeletal adverse event tracking. The Kansai region houses specialized cancer centers influencing protocol standardization across Asia-Pacific.
India
Underdiagnosed hormone receptor-positive breast cancer cases in Chennai and Hyderabad present access program expansion vectors. CDSCO regulatory frameworks govern generic bioequivalence certification for export-oriented manufacturers. The Hyderabad-Visakhapatnam corridor clusters API production for anastrozole and letrozole precursors.
Switzerland
Specialty oncology clinics in Zurich and Geneva pilot quarterly injectable sustained-release formulations for elderly adherence. Swissmedic licensing procedures enable early conditional approval for depot technologies. The Basel pharmaceutical hub anchors European clinical trial infrastructure for lifecycle extension strategies.
Global Aromatase Inhibitors Drug Market Key Industry Players
Concentration sits with large pharmaceutical conglomerates holding integrated manufacturing footprints and mid-size generic specialists competing on tender price. The market structure tiers between innovators defending patent-protected formulations and commodity producers serving cost-sensitive procurement. Three archetypes dominate: vertically integrated research-based multinationals, API-integrated Indian and Chinese generic houses, and specialty oncology-focused mid-caps. Competitive moves center on sustained-release polymer engineering investments and companion diagnostic co-development partnerships.
Among research-based multinationals, Novartis AG and AstraZeneca exemplify the innovator archetype through specialized oncology channel relationships. Pfizer occupies a position representing manufacturing scale advantages on legacy molecules. Teva Pharmaceutical Industries Ltd anchors the mid-size generic specialist tier competing across multiple geographies. These three company profiles illustrate how capital-intensity divergence rotates competitive dynamics between patent-protected lifecycle extensions and commoditized oral tablet markets.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca |
| Pfizer |
| Teva Pharmaceutical Industries Ltd |
| ANI Pharmaceuticals |
| Hikma Pharmaceuticals |
| Bristol-Myers Squibb and Company |
| Viatris |
| Cipla |
| Others |
Cost & Logistics Intelligence
API batch-scale economies in coastal China determine cost floors for anastrozole and letrozole precursors, concentrating upstream margin capture while downstream formulators in Germany and the United States absorb price volatility through inventory buffers. This structural asymmetry between precursor manufacturing and finished-dose formulation shapes competitive positioning across generic and innovator tiers.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through centralized pharmacy benefit managers in Texas and Florida Medicare Advantage networks. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification status and companion diagnostic bundling. Pricing pressure stems from automatic biosimilar substitution policies in multiple US states. Community oncology clinics exhibit highest price sensitivity; NCI-designated comprehensive cancer centers demonstrate lowest sensitivity due to trial revenue offsets.
Supply Chain Analysis
Strategic stockpiling of aromatase inhibitor precursors prevails among German and Japanese formulators facing API concentration risk, while just-in-time inventory management dominates commoditized oral tablet manufacturers in India. Active pharmaceutical ingredient production draws from coastal China, the Hyderabad-Visakhapatnam corridor, and select Italian specialty chemical clusters. Key inputs include triazole intermediates, steroidal backbones, and polymeric depot excipients. Single-source vulnerability concentrates in precursor synthesis steps. Distribution runs through regional pharmaceutical wholesalers serving hospital systems and specialty oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient adherence support programs and companion diagnostic co-development services expand faster than oral tablet hardware, creating recurring-revenue layers that sustain margins beyond generic erosion timelines.
For Market Incumbents: Secure backward integration into API precursor manufacturing to reduce coastal China dependency exposure. Deepen specialized oncology channel relationships through differentiated patient-support programs that pharmacy benefit managers cannot unbundle. Prioritize sustained-release polymer engineering investments to defend pricing power against oral generic commoditization.
For New Entrants and Emerging Players: Anchor in India's tier-2 city diagnostic infrastructure gaps, where underdiagnosed hormone receptor-positive breast cancer cases in Chennai and Hyderabad outpace specialist access. Target telemedicine-integrated virtual oncology platforms in rural Australia and Canada as the most penetrable delivery channel. Pursue EMA adaptive licensing pathways for depot formulations to accelerate revenue recognition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty oncology-focused mid-caps with companion diagnostic co-development capabilities and protected formulation patents. Long-term viability over a multi-year horizon rests on sustained-release innovation pipelines and biomarker-guided therapy selection platforms. Acquisition candidates should demonstrate validated polymer engineering expertise and active investigator-initiated trial programs. Watch for inflection when real-world evidence mandates from German and Japanese payers trigger patient registry infrastructure investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Release Formulation Development | Quarterly depot injections in Swiss and US specialty clinics improve elderly adherence while extending patent protection. |
| Companion Diagnostic Co-Development | EMA guidelines now mandate concurrent biomarker assay validation, doubling regulatory submission complexity for new molecular entities. |
| API Precursor Backward Integration | In-house production of triazole intermediates reduces single-source dependency on coastal China manufacturing clusters. |
| Telemedicine Platform Partnership | Virtual oncology consultations in rural Canada and Australia reduce specialist access barriers outside academic medical centers. |
| Patient Registry Infrastructure Investment | German and Japanese payer demands for post-marketing comparative effectiveness data require expensive longitudinal tracking systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocols, and formulary databases. Bottom-up prescription volume modeling triangulated against top-down market size estimates from trade flow analysis.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, therapy area, end user, and delivery mode dimensions. CAGRs were derived from regression analysis of historical prescription trends against demographic and screening expansion drivers. Modeled inputs included hormone receptor testing penetration rates, generic substitution policy intensities, and sustained-release formulation adoption curves.
Material uncertainties — regulatory pathway delays, API supply disruptions, and biosimilar acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued EMA and FDA alignment on post-authorization safety requirements. Revision becomes warranted when automatic substitution policy adoption crosses thresholds in additional US state jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Neurological Disorder Drugs Market