
 Pharmaceutical Grade Lactose Market | 2026-2036
Pharmaceutical Grade Lactose Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Grade Lactose Market Outlook
Direct procurement channels between excipient manufacturers and pharmaceutical formulators is reshaping how pharmaceutical grade lactose reaches end users. DFE Pharma leverages its specialized milling technology to secure long-term supply agreements with European inhalation product developers. MEGGLE GmbH anchors its position through backward integration into dairy sourcing across Central European cooperatives. Kerry Group competes by extending its excipient portfolio into high-purity anhydrous grades for moisture-sensitive formulations.
Pharmaceutical grade lactose is a refined carbohydrate excipient derived from whey, typically meeting purity standards of 99% or higher lactose content with controlled particle size distribution between 10 and 300 microns for specific pharmacopeial grades. It functions primarily as a diluent, binder, and carrier in solid and inhaled dosage forms, with its compressibility and flow properties determining suitability for direct compression tableting. Monohydrate grades dominate volume due to established use in tablet manufacturing, while inhalation-grade lactose commands premium positioning because particle engineering requirements for dry powder inhalers create narrower supplier qualification. Granulated lactose represents the fastest-expanding product type as contract manufacturers seek ready-to-compress excipients that reduce processing steps.
FDA's Inactive Ingredient Database and EMA's excipient quality guidelines jointly determine which lactose grades gain formulary acceptance in regulated markets. USP-NF and European Pharmacopoeia monograph revisions on residual protein and endotoxin limits are forcing suppliers to upgrade purification trains. India's CDSCO alignment with ICH Q3D guidelines on elemental impurities is raising entry barriers for regional excipient producers. Stakeholders must monitor pharmacopeial harmonization timelines to anticipate which purity tiers will become mandatory versus differentiated.
Market Dynamics
Pharmacopeial harmonization between USP-NF and European Pharmacopoeia is compressing supplier qualification timelines while simultaneously elevating purity thresholds, forcing excipient manufacturers to retool purification infrastructure ahead of formal mandate adoption.
Growth Catalysts
- Inhalation-grade particle engineering:Dry powder inhaler developers demand lactose with sub-10-micron particle fractions, creating dedicated supply lanes for respiratory drug formulators.
- CDSCO alignment with ICH Q3D:India's elemental impurity standards are accelerating domestic excipient upgrades to serve export-oriented pharmaceutical manufacturing.
- Direct compression tableting:Contract manufacturers favor ready-to-compress granulated lactose to eliminate milling and blending steps from production workflows.
Market Restraints
- Whey supply volatility:Dairy commodity price swings transmit directly to lactose input costs, compressing margin predictability for excipient producers without captive milk sourcing.
- Central European supplier concentration:Backward integration into dairy cooperatives by established players limits new entrant access to pharmaceutical-grade whey streams.
- Residual protein limits:Tightening USP-NF monograph specifications on proteinaceous impurities require additional chromatographic purification stages, extending capital recovery timelines.
Strategic Opportunities
- India pharmaceutical export corridors:Domestic formulation growth for regulated markets creates demand for locally manufactured excipient-grade lactose meeting FDA and EMA standards.
- Anhydrous high-purity grades:Moisture-sensitive biologic formulations require specialized lactose variants with sub-0.5% moisture content, commanding technical premium positioning.
- Direct manufacturer-formulator channels:Bypassing traditional distributor networks enables particle specification co-development and long-term offtake agreements.
Industry Challenges
- Pharmacopeial certification timelines:Multi-year qualification processes for new lactose grades delay market entry and tie up technical resources in documentation.
- Particle size distribution control:Maintaining tight PSD specifications across production batches demands specialized milling equipment and real-time monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Lactose Market |
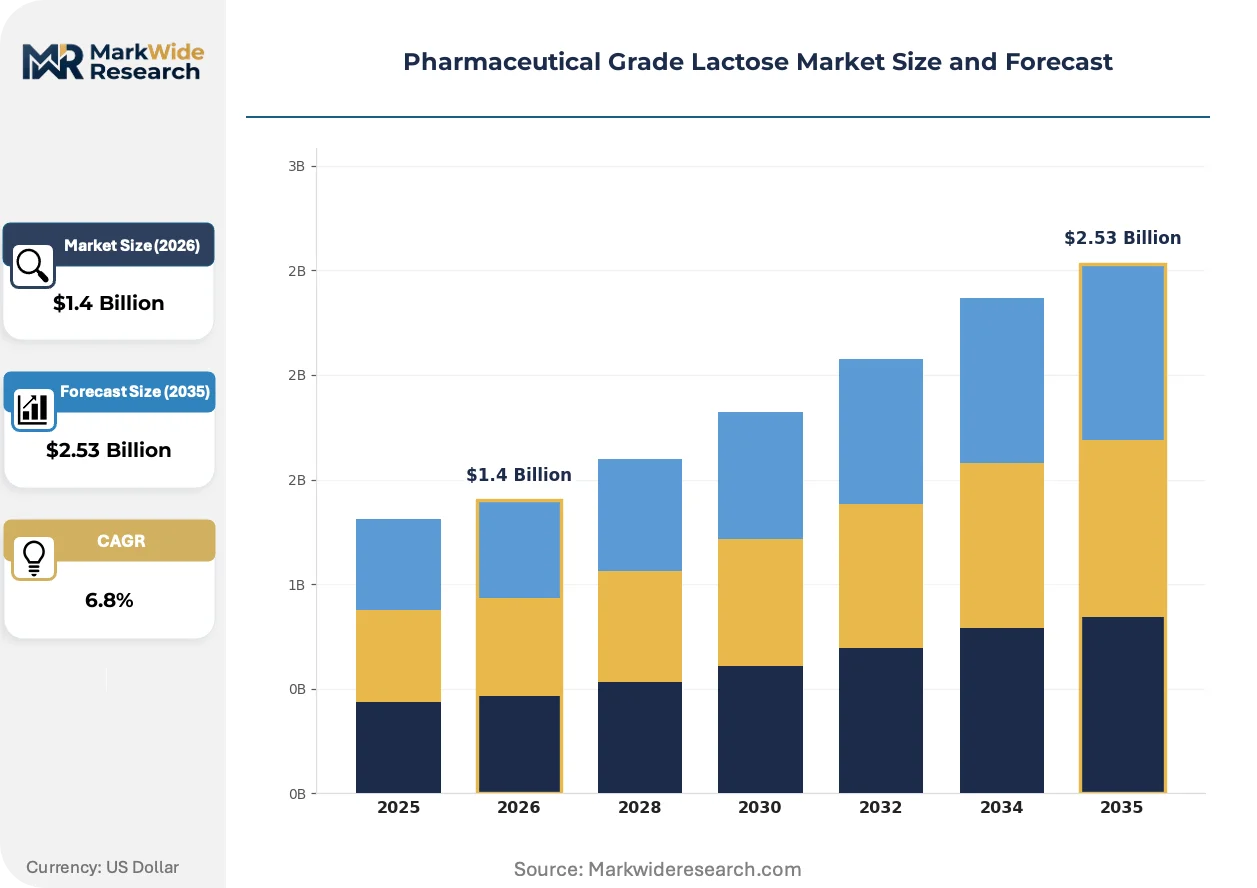
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Anhydrous, Granulated, Powdered Application: Tablets, Capsules, Oral Solutions, Inhalation Products End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Biotech Firms Packaging Type: Bulk, Sachets, Pouches, Drums |
| Companies Covered | BASF, FrieslandCampina, DFE Pharma, Fonterra Co-operative Group, Armor Pharma, MEGGLE GmbH, Kerry Group, JRS Pharma, DMV-Fonterra Excipients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Lactose Market Strategic Shifts
Particle engineering and pharmacopeial digitization are restructuring how excipient quality is specified, verified, and transmitted across pharmaceutical supply chains, with direct implications for supplier qualification protocols.
Spray-dried lactose with engineered particle morphology is rendering obsolete traditional crystalline grades for high-shear direct compression applications. European tablet manufacturers are adopting these engineered particles at accelerating rates. The technology is rendering obsolete multi-step granulation processes that previously dominated solid dosage form production.
EMA's excipient quality guidelines revision is mandating enhanced nitrosamine impurity testing across all carbohydrate excipients. Suppliers must implement additional analytical capabilities or risk formulary exclusion. Inhalation-grade lactose producers face the steepest compliance burden due to higher patient exposure risk classification.
Formulator procurement teams now require excipient manufacturers to provide real-time certificate of analysis data through integrated ERP portals. Traditional paper-based qualification documentation is being displaced by API-connected quality systems. This shift is most visible among North American and European contract development and manufacturing organizations managing multi-site production networks.
Pharmaceutical Grade Lactose Market Segmentation
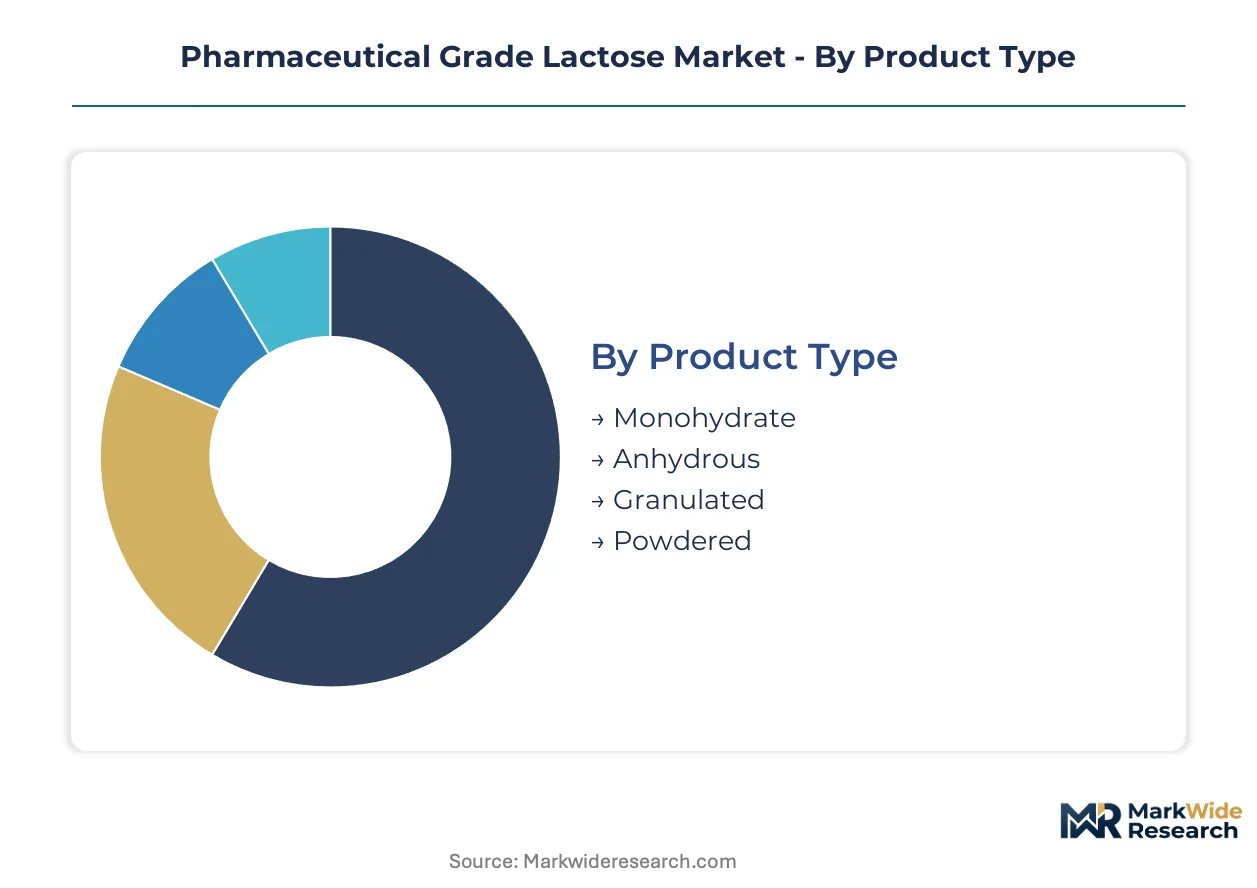
Segmentation in pharmaceutical grade lactose reveals how purity tiers, particle engineering requirements, and packaging configurations align with distinct value chains across solid dosage and respiratory drug production.
Product Type:
The use-case spectrum spans moisture-sensitive biologics requiring anhydrous stability through conventional tablet formulations tolerating hydrated crystalline structures.
- Monohydrate:Crystalline lactose containing one water molecule per lactose unit, valued for compressibility and flow in direct compression tableting. Demand concentrates among European and Indian contract manufacturers serving generic oral solid dosage markets, with established pharmacopeial monographs reducing qualification friction for new suppliers.
- Granulated:Pre-processed agglomerates engineered for immediate tableting without intermediate milling steps. Adoption is accelerating among North American CDMOs seeking to eliminate blending operations and reduce batch-to-batch variability in high-volume production runs.
- Anhydrous:Low-moisture grades below 0.5% water content, essential for moisture-labile active pharmaceutical ingredients in biologic formulations.
- Powdered:Fine-milled crystalline lactose with broad particle size distribution, serving as economical diluent in wet granulation processes.
The dominant share belongs to Monohydrate, while Granulated is closing the gap fastest.
Application:
Cost tiers separate commodity tablet excipients from premium inhalation-grade materials commanding specialized particle engineering and endotoxin controls.
- Inhalation Products:Respiratory-grade lactose with sub-10-micron particle fractions and tight PSD specifications, functioning as carrier in dry powder inhaler formulations. Demand concentrates among specialty respiratory drug developers in Germany, Switzerland, and the United Kingdom, with EMA's enhanced nitrosamine testing requirements raising analytical compliance costs.
- Tablets:The largest volume application encompassing direct compression and granulation processes across immediate-release and modified-release formulations.
- Capsules:Lactose fills for hard gelatin and HPMC capsules, requiring specific flow and lubrication properties distinct from tableting grades.
- Oral Solutions:Highly soluble lactose grades serving as bulking agents in reconstitutable powders and liquid suspensions.
Tablets retain volume leadership, though Inhalation Products exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with large pharmaceutical companies driving qualification standards that cascade through contract manufacturing networks.
- Pharmaceutical Companies:Multinational drug developers with captive formulation expertise and direct supplier qualification protocols. Procurement concentrates in Germany, the United States, and Switzerland, where backward-integrated excipient manufacturers secure long-term offtake agreements through collaborative particle specification development.
- Contract Manufacturers:CDMOs and CMOs serving multiple clients with standardized excipient portfolios to minimize inventory complexity and regulatory documentation burden.
- Research Institutions:Academic and government laboratories requiring small-batch, high-purity lactose for preclinical formulation development.
- Biotech Firms:Emerging drug developers prioritizing anhydrous and specialized grades for novel therapeutic modalities.
Pharmaceutical Companies command the largest procurement volumes, while Contract Manufacturers are expanding their share most rapidly.
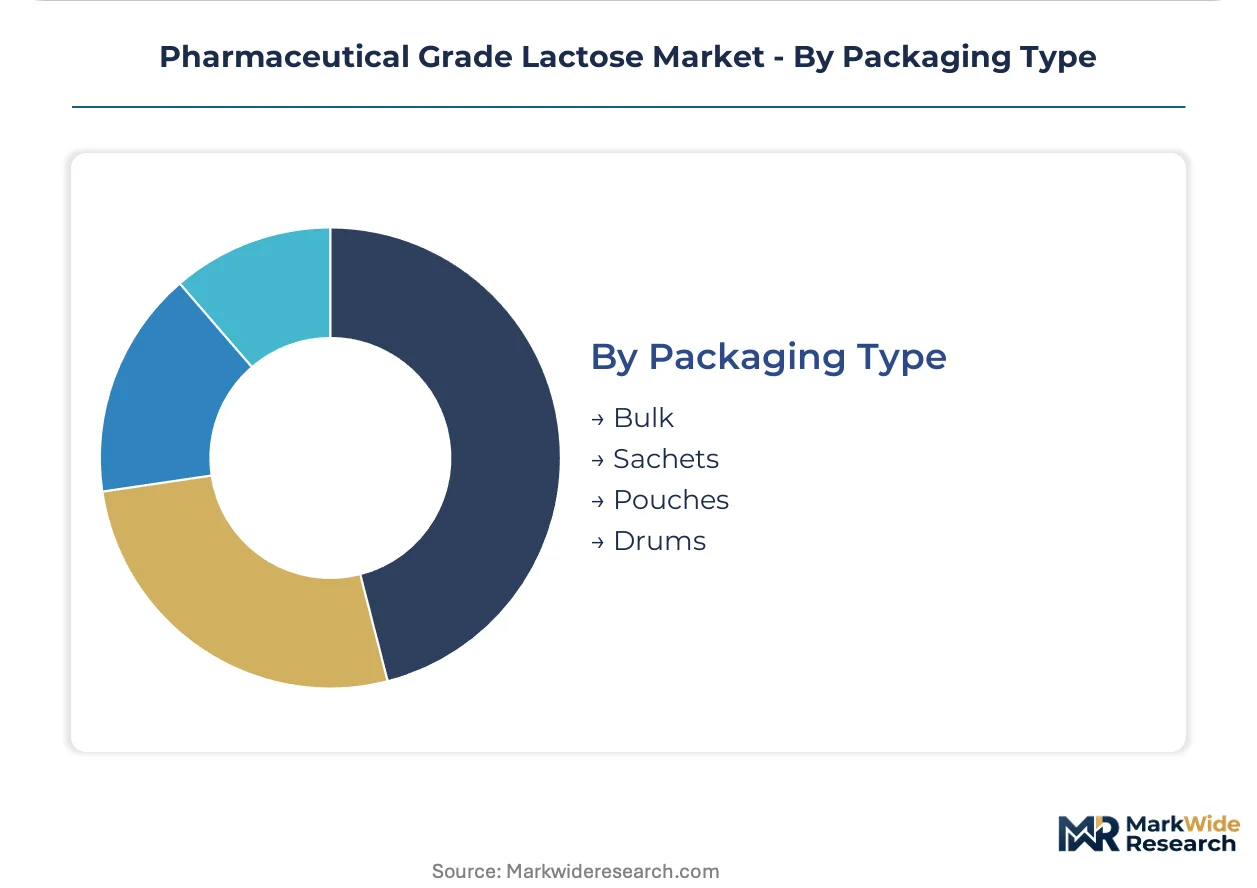
Packaging Type:
Supply chain configuration varies from bulk tanker deliveries for integrated manufacturing sites to unitized packaging for distributed production networks.
- Bulk:Tanker and silo deliveries for high-volume manufacturers with dedicated excipient handling infrastructure, minimizing per-kilogram packaging costs and environmental waste.
- Drums:Standard 25-50 kg fiber or steel drums for mid-scale production, balancing handling efficiency with contamination control.
- Sachets:Pre-weighed unit doses for clinical trial manufacturing and small-batch production, reducing weighing errors and cross-contamination risk.
- Pouches:Flexible multi-layer packaging for moisture-sensitive grades, extending shelf stability in humid climates.
Bulk shipments dominate tonnage, though Sachets are gaining adoption fastest among distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals handle whey protein concentrates flowing into European excipient manufacturing, underwriting the continent's pharmaceutical-grade lactose production capacity.
Germany
Inhalation-grade lactose demand from respiratory drug developers in Baden-Württemberg and Bavaria drives specialized particle engineering requirements. EMA's excipient quality guidelines revision mandates enhanced nitrosamine testing, forcing analytical capability upgrades. The Rhine-Main pharmaceutical cluster around Frankfurt anchors backward-integrated supply relationships with Central European dairy cooperatives.
India
Domestic pharmaceutical production scaling for FDA and EMA export markets concentrates excipient demand in Maharashtra and Gujarat. CDSCO alignment with ICH Q3D guidelines on elemental impurities raises entry barriers for regional producers. The Hyderabad-Pune corridor hosts contract manufacturers seeking locally sourced pharmacopeial-grade lactose to reduce import dependency.
United States
Contract development and manufacturing organizations in North Carolina and Massachusetts drive procurement of ready-to-compress granulated lactose. FDA's Inactive Ingredient Database determines formulary acceptance for new excipient grades entering regulated markets. The Research Triangle Park cluster exhibits accelerating adoption of spray-dried engineered particles for high-shear direct compression applications.
Switzerland
Specialty respiratory drug developers in Basel demand sub-10-micron particle fractions with tight PSD specifications. Swissmedic maintains alignment with EMA excipient standards while operating independent certification protocols. The Basel-Zurich pharmaceutical corridor secures dedicated supply lanes through long-term collaborative specification development with qualified excipient manufacturers.
United Kingdom
Generic oral solid dosage manufacturers in the Midlands and Northern England favor established monohydrate grades with reduced qualification friction. MHRA post-Brexit regulatory autonomy maintains substantive equivalence with European Pharmacopoeia requirements. The Manchester-Leeds manufacturing belt concentrates demand for drum-packaged excipients serving mid-scale production runs.
Pharmaceutical Grade Lactose Market Competitive Environment
On the supply side, the industry is consolidating around dairy-origin excipient specialists with captive whey sourcing and pharmaceutical-dedicated processing infrastructure. Three strategic archetypes dominate: backward-integrated dairy processors controlling upstream milk supply, specialized excipient houses with dedicated milling and particle engineering capabilities, and diversified ingredient conglomerates extending portfolio coverage into high-purity grades. Competitive moves concentrate on long-term offtake agreements with direct manufacturer-formulator channels and purification train upgrades ahead of pharmacopeial mandate adoption.
Within the specialized excipient tier, DFE Pharma and MEGGLE GmbH represent the particle engineering archetype, while Kerry Group exemplifies portfolio diversification into anhydrous high-purity grades. FrieslandCampina anchors the dairy-origin integrated processor position. These three occupy distinct competitive vectors without direct segment overlap, allowing coexistence through differentiation rather than price confrontation.
| Leading Market Players |
|---|
| BASF |
| FrieslandCampina |
| DFE Pharma |
| Fonterra Co-operative Group |
| Armor Pharma |
| MEGGLE GmbH |
| Kerry Group |
| JRS Pharma |
| DMV-Fonterra Excipients |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main pharmaceutical cluster around Frankfurt anchors European inhalation-grade lactose capacity, with DFE Pharma and MEGGLE GmbH commanding premium positioning through specialized particle engineering capabilities that downstream respiratory drug developers cannot easily substitute.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade lactose into three distinct price bands: inhalation-grade sub-10-micron fractions commanding technical premiums, standard monohydrate grades for commodity tablet production, and economy powdered variants for wet granulation processes. Price differentiation rests on certification level (USP-NF versus European Pharmacopoeia monograph compliance) and particle size distribution control. Cost compression in economy tiers is intensifying because Indian contract manufacturers are scaling domestic production for export markets. Large pharmaceutical companies with direct procurement channels exhibit lowest price sensitivity, while mid-scale CDMOs face acute margin pressure from inventory complexity.
Supply Chain Analysis
Upstream whey feedstock draws from Central European dairy cooperatives concentrated in Germany, the Netherlands, and France, with FrieslandCampina and Fonterra anchoring captive milk sourcing relationships that insulate against commodity volatility. Raw material dependencies include liquid whey permeate, specialized milling equipment, and chromatographic purification resins for endotoxin removal. Single-source vulnerability concentrates in inhalation-grade particle engineering capabilities, where qualified suppliers number fewer than six globally. Distribution runs through direct manufacturer-formulator channels for premium grades, while commodity monohydrate flows through regional distributors serving fragmented CDMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward contract manufacturers as pharmaceutical companies consolidate formulation outsourcing, concentrating procurement volumes among CDMOs with standardized excipient portfolios that reduce supplier qualification overhead.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into Central European dairy cooperatives before whey supply volatility transmits to input costs. Invest in real-time certificate of analysis ERP portals to defend against emerging particle engineering specialists offering API-connected quality systems. Prioritize pharmacopeial certification ahead of USP-NF monograph revisions on residual protein limits. For New Entrants and Emerging Players: Pursue white-space opportunities in India's Hyderabad-Pune corridor, where CDSCO alignment with ICH Q3D guidelines is raising entry barriers for regional producers but creating demand for FDA-qualified local supply. Target anhydrous high-purity grades for moisture-sensitive biologic formulations, where technical premium positioning remains undercontested. Establish go-to-market partnerships with North American spray-dried particle engineering specialists. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dairy-origin excipient specialists with captive whey sourcing and pharmaceutical-dedicated processing infrastructure command irreplaceable supply positions. Acquisition targets should display backward integration into milk supply cooperatives and active pharmacopeial certification pipelines. Monitor EMA excipient quality guideline revision timelines as inflection signals for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperatives | Captive whey sourcing insulates margin predictability against commodity price swings from FrieslandCampina and Fonterra supply dominance. |
| Pharmacopeial Certification Investment | Pre-positioning for USP-NF and European Pharmacopoeia monograph revisions secures formulary acceptance before mandate adoption. |
| Particle Engineering Capability Buildout | Sub-10-micron fraction control for dry powder inhaler developers creates dedicated supply lanes with long-term offtake agreements. |
| Direct Manufacturer-Formulator Channels | Bypassing distributor networks enables collaborative specification development with respiratory drug developers in Basel and Baden-Württemberg. |
| Real-Time Quality System Integration | API-connected ERP portals displace paper-based qualification documentation for North American contract development organizations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical formulation scientists, CDMO procurement directors, excipient quality assurance managers, and respiratory drug development executives. Secondary validation drew from FDA Inactive Ingredient Database filings, EMA excipient quality guideline revisions, USP-NF monograph documentation, and European Pharmacopoeia certification records. Bottom-up volume estimates from individual production facilities were triangulated against top-down market sizing from trade flow analysis.
Calibration approaches anchored volume projections to disclosed capacity expansions at major processing sites and announced long-term supply agreements. Segmentation dimensions modeled include product type (monohydrate, granulated, anhydrous, powdered), application (inhalation products, tablets, capsules, oral solutions), and end user category (pharmaceutical companies, contract manufacturers, research institutions, biotech firms). CAGRs were derived from fitted growth curves against historical pharmaceutical production indices and regional regulatory alignment timelines. Forecast inputs incorporated ICH Q3D elemental impurity implementation schedules and dry powder inhaler pipeline advancement rates.
Sensitivities concentrate around pharmacopeial harmonization timelines, whey commodity price volatility, and respiratory drug approval success rates that could accelerate or delay inhalation-grade demand. Forecasts reflect documented assumptions on regulatory adoption speed and dairy supply stability. Quarterly review of CDSCO certification progress, EMA excipient guideline revision announcements, and Central European milk production statistics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market