
 Urinary Retention Market | 2026-2036
Urinary Retention Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Retention Market Intelligence
The gap between premium antimicrobial catheters and commodity latex devices is broadening as reimbursement tiers harden and infection-risk protocols tighten. Pfizer Inc anchors its position through R&D intensity in urological pharmaceutical portfolios. Johnson & Johnson dominates advanced surgical device segments with proprietary benign prostatic hyperplasia platforms. Sun Pharmaceutical Industries Ltd competes on cost-structured generic medications across emerging markets.
Urinary retention denotes the incomplete emptying of the bladder due to obstruction, detrusor underactivity, or neurogenic dysfunction, typically managed through catheterization, pharmacotherapy with alpha-blockers or anticholinergics, or surgical intervention such as transurethral resection; catheter materials now specify silicone or hydrophilic-coated polymers to reduce urethral trauma and bacteriuria incidence. Catheters command the largest product type position as indwelling and intermittent formats sustain hospital procurement volumes, while home care represents the fastest-growing end user segment as payors shift reimbursement toward outpatient settings and patients manage chronic retention outside acute facilities. Diagnostic tools remain a narrower margin pool concentrated in urodynamics equipment for specialized clinics.
FDA 510(k) pathways and EPA antimicrobial coating claims govern device commercialization in the United States, while the EU MDR and REACH substance restrictions shape European catheter material compliance. These frameworks elevate validation costs for novel coatings but simultaneously filter out lower-tier suppliers unable to sustain clinical documentation. Stakeholders must weigh catheter portfolio allocation between premium infection-prevention formats and commodity volume plays as reimbursement compression intensifies across hospital and home channels.
Market Dynamics
Medicare reimbursement compression for intermittent self-catheterization supplies is forcing manufacturers to restructure portfolio economics between premium antimicrobial formats and commodity latex alternatives.
Growth Catalysts
- Home care migration:Outpatient management protocols endorsed by payors accelerate catheter adoption outside acute facilities. Aging populations in Japan and Germany drive volume in reimbursed self-catheterization programs.
- EU MDR antimicrobial claims:Stricter clinical documentation requirements for coated devices elevate barriers against low-tier competitors. Validated infection-prevention coatings command procurement preference in German and French hospital systems.
- Silicone material substitution:Hydrophilic-coated silicone catheters reduce urethral trauma incidence compared to standard latex. Urology clinics in the United States and United Kingdom upgrade specifications to polymer-based portfolios.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical-derived silicone precursor costs fluctuate with energy markets. Device manufacturers absorb margin compression or pass through to hospital procurement.
- Single-source coating chemistry concentration:Silver-ion and chlorhexidine antimicrobial formulations rely on concentrated specialty chemical suppliers. Disruption risks concentrate in German and Swiss coating compounders.
- Substitution by transurethral resection:Surgical intervention for benign prostatic hyperplasia eliminates chronic catheter dependence in eligible patients. Urologists in tertiary centers prioritize definitive procedural solutions.
Strategic Opportunities
- Underpenetrated Indian outpatient infrastructure:Government health insurance expansion creates reimbursement pathways for intermittent catheterization. Domestic manufacturers scale production for price-sensitive public procurement.
- Telehealth-integrated remote monitoring:Connected catheter systems with volume sensors enable clinician oversight of home-based patients. Technology convergence between urological devices and digital health platforms opens subscription revenue models.
- Japan's PMDA fast-track pathway:Accelerated review for infection-prevention devices reduces time-to-market for novel coatings. Multinational manufacturers prioritize Tokyo regulatory submissions for antimicrobial innovations.
Industry Challenges
- Clinical evidence generation timelines:FDA 510(k) and EU MDR require prospective bacteriuria reduction studies. Startups face capital requirements exceeding typical Series B medtech financing.
- Legacy hospital supply chain integration:Electronic health record procurement systems resist SKU proliferation. New entrants must navigate group purchasing organization certification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Retention Market |
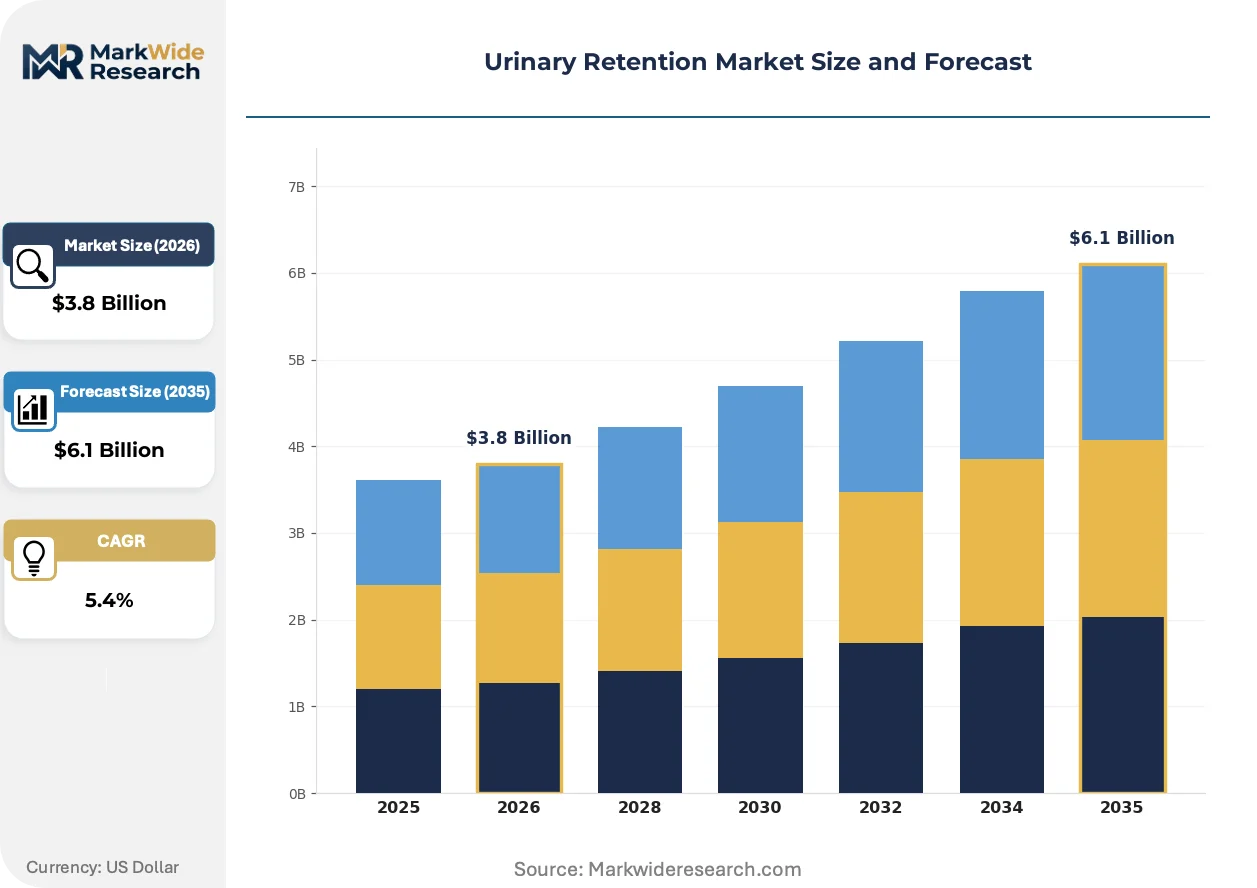
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Medications, Surgical Devices, Diagnostic Tools Application: Chronic Conditions, Surgical Procedures, Emergency Care, Preventive Measures End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Distribution Channel: Direct Sales, Retail Pharmacies, Online Stores, Distributors |
| Companies Covered | Pfizer Inc, Sanofi, Astellas Pharma Inc, Merck KGaA, GlaxoSmithKline plc, Johnson & Johnson, Sun Pharmaceutical Industries Ltd, Teva Pharmaceutical Industries Ltd, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Retention Market Strategic Shifts & Innovations
Antimicrobial coating validation standards and connected device architectures are restructuring competitive requirements across catheter manufacturing. These shifts favor capital-intensive players capable of sustaining clinical documentation and digital infrastructure investment.
Silicone-based hydrophilic coatings is overtaking standard latex in indwelling catheter specifications due to reduced encrustation and lower urethral trauma incidence. Hospital procurement committees in the United States and United Kingdom now mandate polymer portfolios for long-term placements. This material transition compresses margins for latex-focused manufacturers while enabling premium pricing for validated silicone alternatives.
EU MDR substance restrictions and EPA antimicrobial claims enforcement are elevating clinical data requirements for coated devices. Manufacturers must demonstrate bacteriuria reduction in prospective trials rather than rely on in-vitro testing. European urology clinics delay procurement decisions pending notified body certification, compressing near-term revenue recognition for novel coating submissions.
Patient-directed purchasing through durable medical equipment suppliers is fragmenting traditional hospital-centric distribution. Medicare beneficiaries in the United States select home delivery vendors for intermittent catheterization supplies based on insurance network participation. This channel shift disintermediates acute-care procurement teams and elevates direct-to-patient logistics capabilities as a competitive differentiator.
Urinary Retention Market Segmentation
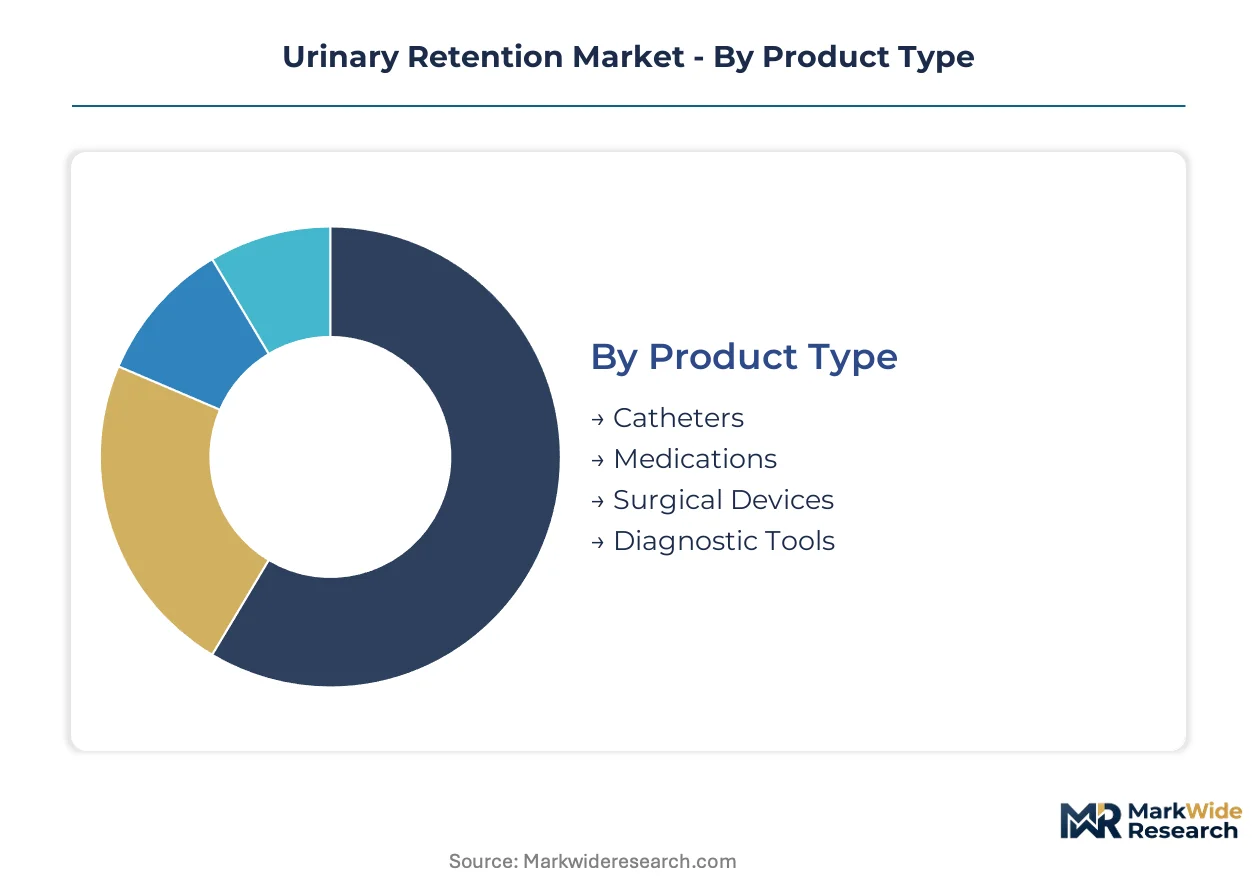
Segmentation in urinary retention reveals divergent margin structures across acute versus chronic care pathways. Material specifications and reimbursement tiers fragment procurement decisions, forcing manufacturers to calibrate portfolio depth against channel economics.
Product Type:
Catheters dominate procurement volumes while surgical devices capture premium pricing in tertiary settings.
- Catheters:Silicone and hydrophilic-coated polymers now specify standard-of-care for indwelling and intermittent formats. Hospital systems in the United States and United Kingdom mandate polymer portfolios to reduce encrustation and urethral trauma incidence.
- Medications:Alpha-blockers and anticholinergics manage functional retention through outpatient prescription channels. Generic competition from Indian manufacturers compresses margin structures in emerging markets.
- Surgical Devices:Transurethral resection platforms and laser ablation systems serve definitive BPH intervention. Johnson & Johnson proprietary platforms anchor high-value procedural segments in tertiary urology centers.
- Diagnostic Tools:Urodynamics equipment concentrates in specialized clinics with narrower margin pools. Equipment procurement cycles extend replacement timelines outside academic medical centers.
Today's leader: Catheters. Tomorrow's challenger: Surgical Devices.
Application:
Chronic condition management drives recurring revenue while emergency applications concentrate in acute throughput.
- Chronic Conditions:Neurogenic bladder and BPH-related retention sustain long-term catheter dependence. Medicare reimbursement for intermittent self-catheterization programs in the United States secures predictable volume streams.
- Surgical Procedures:Perioperative retention management requires short-term indwelling catheterization. Ambulatory surgery centers in Germany and France prioritize rapid-turnover protocols with same-day removal specifications.
- Emergency Care:Acute urinary retention presents in emergency departments requiring immediate decompression. Throughput pressure in United Kingdom NHS trusts compresses device selection to lowest-cost compliant options.
- Preventive Measures:Postoperative protocols in Japanese hospitals specify prophylactic catheterization for high-risk surgical populations. PMDA infection-prevention guidelines elevate coated device specifications.
Chronic Conditions anchor current revenue. Emergency Care offers volume expansion through protocol standardization.
End User:
Channel migration from inpatient facilities to home settings restructures logistics requirements and pricing sensitivity.
- Hospitals:Group purchasing organization contracts dominate high-volume indwelling catheter procurement. Electronic health record integration resists SKU proliferation from novel coating entrants.
- Clinics:Urology specialty practices specify premium hydrophilic-coated intermittent catheters for self-catheterization training. Reimbursement verification staff consume administrative bandwidth.
- Home Care:Patient-directed purchasing through durable medical equipment suppliers fragments traditional distribution. Medicare beneficiaries select vendors based on insurance network participation, disintermediating acute-care procurement teams.
- Long-term Care Facilities:Nursing homes balance infection prevention protocols against per-diem cost constraints. Silver-ion coated catheters command procurement preference in German and French eldercare systems.
Home Care climbs the fastest as payor migration accelerates. Hospitals defend volume concentration through contract consolidation.
Distribution Channel:
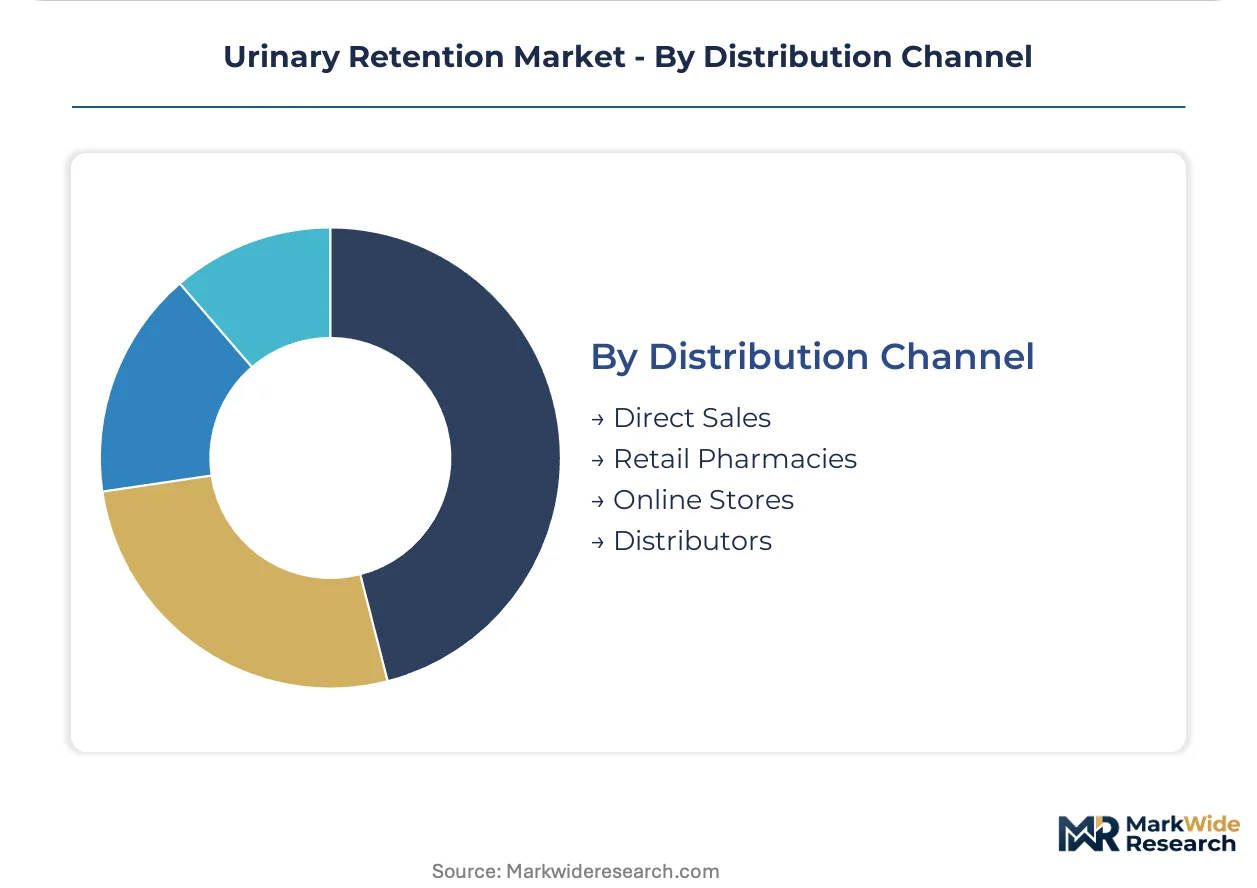
Direct relationships with procurement committees yield premium positioning while retail and online channels serve price-sensitive self-pay segments.
- Direct Sales:Manufacturer representatives navigate hospital value analysis committees for coated catheter approvals. Clinical evidence packages support infection-prevention claims in United States IDN negotiations.
- Retail Pharmacies:Over-the-counter intermittent catheters serve cash-pay patients outside reimbursed pathways. German pharmacy chains stock economy latex formats for price-sensitive consumers.
- Online Stores:Direct-to-patient logistics capabilities emerge as competitive differentiators. Subscription models for intermittent catheterization supplies capture recurring revenue in United States Medicare Advantage networks.
- Distributors:Regional medical-surgical distributors aggregate fragmented clinic demand. Inventory carrying costs concentrate working capital requirements for silicone catheter portfolios.
Direct Sales commands margin concentration. Online Stores reshape patient access economics fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urology specialists and catheter manufacturing engineers concentrate in Germany, the United States, and Japan, anchoring regional innovation clusters. These workforce pools shape procurement standards and coating validation protocols across their respective markets.
United States
Medicare reimbursement for intermittent self-catheterization supplies drives volume concentration among home care patients. FDA 510(k) pathways govern antimicrobial coating commercialization, elevating clinical documentation requirements for novel devices. Boston and Minneapolis medical device clusters host catheter coating validation laboratories serving national hospital procurement networks.
Germany
Aging demographics sustain demand for infection-prevention catheter protocols in eldercare systems. EU MDR substance restrictions and REACH compliance reshape silicone material sourcing for device manufacturers. Freiburg and Tübingen urology research centers advance hydrophilic coating biocompatibility studies for European hospital procurement committees.
Japan
PMDA fast-track pathways for infection-prevention devices accelerate regulatory review timelines for coated catheter innovations. Government health insurance expansion supports outpatient catheterization program reimbursement. Tokyo and Osaka medical device manufacturing corridors concentrate silicone molding capacity for domestic and Asia-Pacific distribution.
India
Government health insurance schemes create reimbursement pathways for intermittent catheterization in price-sensitive public procurement. CDSCO medical device regulations align with international standards for imported coating technologies. Ahmedabad and Hyderabad manufacturing zones scale latex and silicone catheter production for domestic volume and export markets.
United Kingdom
NHS procurement frameworks prioritize lowest-cost compliant catheter options for emergency department throughput pressures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards for antimicrobial device claims. London and Manchester urodynamics specialist clinics concentrate diagnostic equipment procurement for complex retention cases.
Urinary Retention Market Key Industry Players
Capital-heavy producers compete with asset-light designers across catheter material and pharmaceutical portfolios. The vendor base stratifies between multinational device manufacturers with integrated coating capabilities and generic pharmaceutical suppliers serving cost-structured markets. Three archetypes dominate: integrated medical device conglomerates with proprietary surgical platforms, specialty pharmaceutical developers with urological therapeutic focus, and regional generic manufacturers scaling volume production. Competitive moves concentrate on antimicrobial coating validation investments and home care distribution network expansion.
Within the integrated device tier, Johnson & Johnson and Pfizer Inc occupy positions spanning surgical intervention and pharmaceutical management of urinary retention. Sanofi and Bayer AG exemplify European-headquartered pharmaceutical developers with urological therapeutic portfolios. Sun Pharmaceutical Industries Ltd represents the cost-structured generic manufacturing archetype emerging from Indian production bases. These anchors illustrate the competitive tension between premium infection-prevention device formats and commodity pharmaceutical alternatives across reimbursement environments.
| Leading Market Players |
|---|
| Pfizer Inc |
| Sanofi |
| Astellas Pharma Inc |
| Merck KGaA |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Sun Pharmaceutical Industries Ltd |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Medical-grade silicone precursor costs fluctuate with petrochemical energy markets, flowing from German and Swiss specialty chemical suppliers through coating compounders to catheter manufacturers, ultimately stratifying into premium antimicrobial, standard hydrophilic, and economy latex pricing tiers at hospital procurement committees and durable medical equipment vendors.
Pricing Analysis
Bundled catheter-plus-coating specifications now dominate hospital procurement, while unbundled commodity latex serves price-sensitive home care cash-pay segments. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) antimicrobial validation tiers and silicone material grades. Pricing pressure stems from Medicare reimbursement compression for intermittent self-catheterization supplies, forcing margin absorption at the premium tier. Home care patients through Medicare Advantage networks show highest price sensitivity, while tertiary urology centers demonstrate lowest sensitivity for infection-prevention protocols.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss silver-ion and chlorhexidine coating compounders, where concentrated specialty chemical suppliers feed antimicrobial formulation production. Device manufacturing draws from China, Malaysia, and Costa Rica for silicone molding and latex processing, with medical-grade polymer feedstock anchored in petrochemical corridors. Tariff exposure on Chinese-sourced hydrophilic coating substrates presents structural risk. Distribution runs through group purchasing organizations for hospital volume, direct-to-patient logistics for home care, and regional medical-surgical distributors for fragmented clinic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary retention market represents a late-cycle quality story as infection-prevention protocols harden and procurement committees mandate validated silicone antimicrobial specifications over commodity latex alternatives.
For Market Incumbents: Anchor portfolio allocation between premium coating R&D and home care distribution infrastructure to defend against transurethral resection substitution and emerging Indian generic manufacturers. Prioritize backward integration into silicone feedstock processing to absorb petrochemical volatility. Deepen vertical control over coating chemistry through captive supply agreements with Swiss and German compounders.
For New Entrants and Emerging Players: Connected catheter volume sensors with telehealth integration offer a technology-first wedge into the Medicare Advantage home care channel, where incumbent logistics capabilities remain underdeveloped. Target underpenetrated Indian outpatient infrastructure through government health insurance reimbursement pathways. Pursue PMDA fast-track submissions in Japan to establish antimicrobial coating credibility before FDA 510(k) entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR clinical documentation requirements exceed Series B medtech capital capacity, stranding coating validation startups. Long-term viability favors integrated device manufacturers with proprietary silicone portfolios and hospital GPO contract concentration. Watch Japanese PMDA approval velocity as inflection indicator for antimicrobial innovation pipeline health.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Validation Investment | EU MDR bacteriuria reduction studies elevate barriers against low-tier competitors in German hospital procurement. |
| Home Care Distribution Network Expansion | Medicare beneficiary vendor selection based on insurance network participation disintermediates acute-care procurement teams. |
| Silicone Material Backward Integration | Captive polymer processing absorbs petrochemical feedstock volatility pressuring latex-focused manufacturers. |
| Telehealth-Integrated Device Development | Connected catheter systems with volume sensors enable subscription revenue models in Medicare Advantage networks. |
| PMDA Fast-Track Regulatory Submission | Accelerated Tokyo review timelines for infection-prevention devices reduce time-to-market for novel coating innovations. |
Research Approach
Bottom-up home care patient volume modeling reconciled against top-down catheter manufacturing capacity tracking forms the analytical core. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, urology clinic administrators, and Medicare reimbursement specialists combined with secondary validation against FDA 510(k) filings, CMS Medicare claims data, EU MDR notified body certifications, and hospital procurement database extracts. Triangulation between demand-side utilization patterns and supply-side production footprints ensures cross-verified estimates.
Input-output matrices segment the market by catheter material grade, coating technology tier, end-user channel, and regional regulatory cluster across the analysis window. CAGRs derive from modeled patient population growth, procedure volume trajectories, and reimbursement rate assumptions. Forecast inputs incorporate silicone feedstock cost indices, antimicrobial coating compounder capacity utilization, and PMDA/FDA regulatory approval velocity for novel device submissions.
The model holds under stable Medicare reimbursement and EU MDR enforcement intensity; deviation in petrochemical energy markets or transurethral resection adoption curves would shift volume projections. Forecasts reflect documented assumptions regarding patient compliance rates and coating validation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Sjogrens Syndrome Market