
 Non-Sterile Compounding Pharmacy Market | 2026-2036
Non-Sterile Compounding Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Sterile Compounding Pharmacy Market Outlook
The US FDA's updated 503A guidance is hardening quality standards for non-sterile compounding, pushing pharmacies toward validated processes and documented beyond-use dating. Empower Pharmacy leverages centralized production models to serve multi-state provider networks. Fagron anchors European supply chains with raw material sourcing and formulation libraries. B. Braun Melsungen AG competes through hospital-integrated compounding services that reduce preparation risk at the point of care.
Non-sterile compounding pharmacy encompasses the preparation of customized medications—creams, ointments, capsules, and solutions—without terminal sterilization, typically for patient-specific prescriptions that commercial manufacturers do not produce in required strengths, dosages, or formulations. These preparations rely on United States Pharmacopeia Chapter 795 standards for stability, potency, and microbial limits, serving therapeutic gaps in pain management, hormone replacement, and pediatric dosing where mass-produced alternatives fail. Oral delivery mode dominates volume due to patient familiarity and formulation flexibility, while topical segments capture margin pools in dermatology and localized pain therapy where insurance reimbursement favors pharmacy-dispensed alternatives. Hospital end users sustain the largest absolute demand, though homecare channels represent the fastest structural expansion as discharge protocols shift medication administration to residential settings.
State boards of pharmacy, the FDA under 503A/503B designations, and USP chapters 795 and 800 collectively govern non-sterile compounding practice, with state-level inspections creating patchwork compliance burdens that favor multi-jurisdiction operators with dedicated quality infrastructure. The Drug Quality and Security Act's compounder registration tiers shape market access by separating traditional 503A patient-specific pharmacies from 503B outsourcing facilities subject to current good manufacturing practice standards. Stakeholders must monitor how FDA enforcement discretion evolves for hospital-affiliated compounders and whether state-level harmonization reduces compliance fragmentation.
Market Dynamics
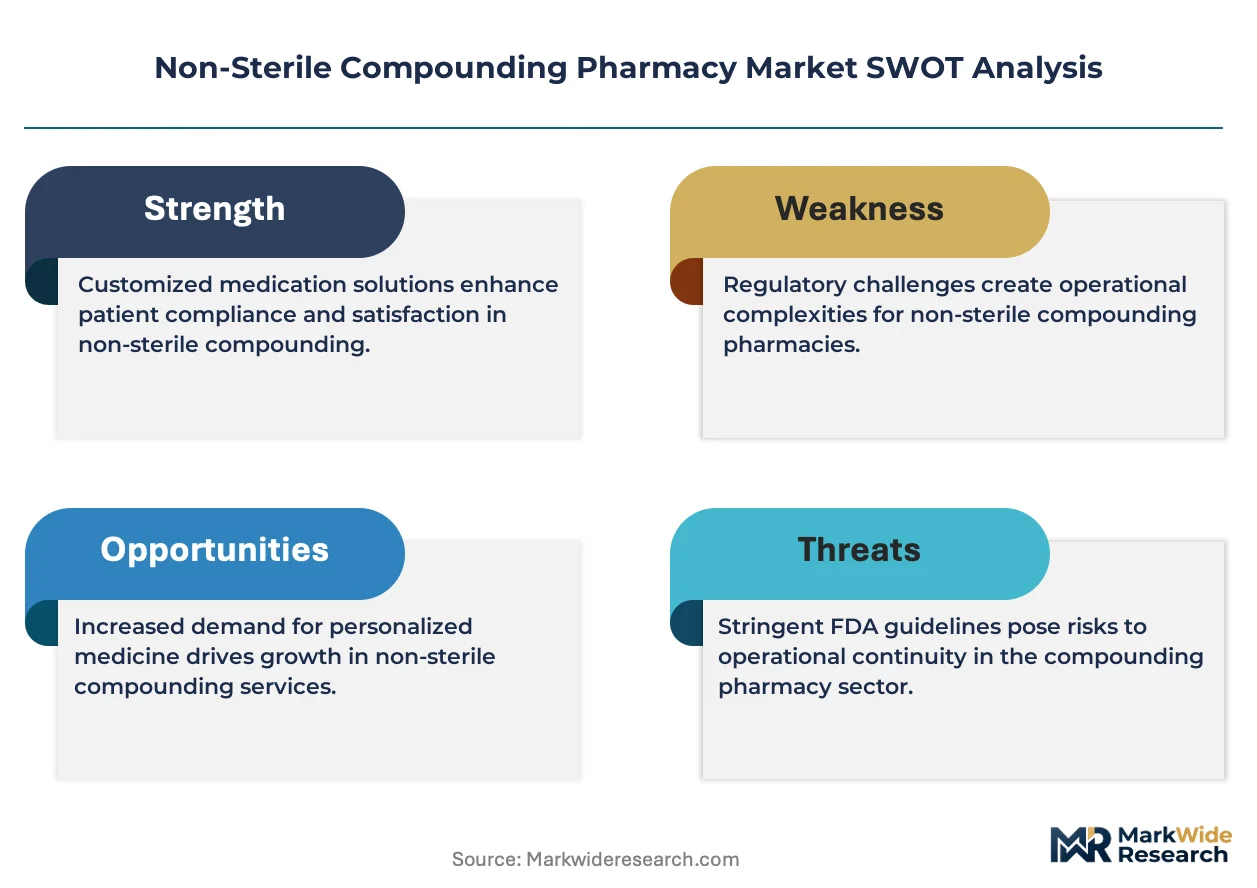
The FDA's updated 503A guidance is hardening quality requirements for non-sterile compounding, forcing pharmacies to invest in validated processes, environmental monitoring, and documented beyond-use dating protocols that raise operational barriers for smaller operators.
Growth Catalysts
- Homecare migration:Discharge protocols in US hospital systems are shifting medication administration to residential settings, expanding the addressable patient base for patient-specific formulations.
- USP Chapter 795 adoption:State boards of pharmacy are harmonizing inspection standards around United States Pharmacopeia stability and microbial limit guidelines, reducing interstate compliance friction for multi-jurisdiction operators.
- API sourcing diversification:Compounders are building redundant supply relationships with European and Indian raw material suppliers to mitigate single-source dependency risks in hormone and pain management APIs.
Market Restraints
- Excipient cost volatility:Prices for specialized bases, penetration enhancers, and sustained-release polymers fluctuate with petrochemical feedstock markets, compressing margin predictability for topical formulation specialists.
- Regulatory friction from 503A/503B tiering:The Drug Quality and Security Act's facility classification creates uneven inspection intensity, placing disproportionate compliance burdens on traditional patient-specific pharmacies versus outsourcing facilities.
- Substitution threat from reformulated commercial products:Pharmaceutical manufacturers are introducing dose-flexible commercial alternatives in hormone therapy and pediatric segments, narrowing the therapeutic gap that compounding addresses.
Strategic Opportunities
- Veterinary compounding expansion:Companion animal practices and exotic pet clinics represent underpenetrated demand for flavored suspensions, transdermal gels, and species-appropriate dosage forms that mass manufacturers rarely supply.
- Integrated e-prescribing workflows:Direct connectivity with electronic health record systems and telehealth platforms enables compounders to capture prescriptions at the point of clinical decision, bypassing traditional retail pharmacy intermediaries.
- State-level harmonization initiatives:The National Association of Boards of Pharmacy is advancing model practice acts that could reduce inspection fragmentation across US jurisdictions, lowering compliance overhead for regional operators.
Industry Challenges
- Pharmaceutical calculation competency gaps:Compounding technicians and pharmacists require specialized training in alligation, percentage strength conversions, and complex dosing mathematics that standard pharmacy curricula inadequately cover.
- Cleanroom and containment capex cycles:USP Chapter 800 hazardous drug handling requirements demand facility upgrades including negative-pressure suites and closed-system transfer devices that strain capital reserves of independent pharmacies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Sterile Compounding Pharmacy Market |
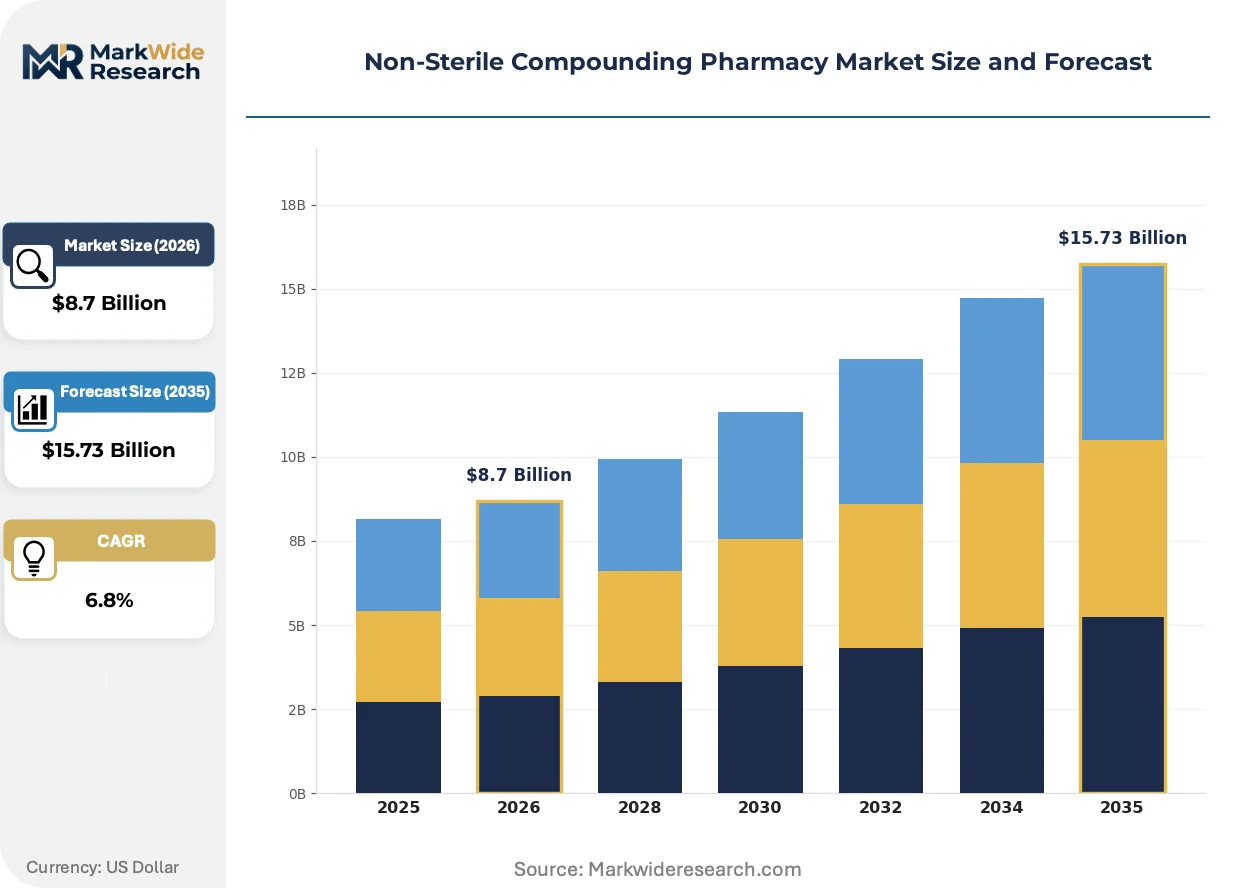
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Ointments, Capsules, Solutions End User: Clinics, Hospitals, Homecare, Outpatient Facilities Therapy Area: Pain Management, Hormone Replacement, Pediatric Care, Dermatology Delivery Mode: Topical, Oral, Injectable, Transdermal |
| Companies Covered | Empower Pharmacy, TRUE NATURE HOLDING, INC, Fagron, QuVa Pharma, Dougherty's Pharmacy Inc., B. Braun Melsungen AG, Baxter, Walgreens Co, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Sterile Compounding Pharmacy Market Strategic Shifts
Digital quality management systems and automated compounding equipment are reshaping how pharmacies document batch records, track environmental conditions, and demonstrate compliance during regulatory inspections.
Workflow automation software is absorbing manual documentation burdens in non-sterile compounding operations. Hospital-affiliated pharmacies and high-volume 503B facilities are adopting these platforms fastest, driven by inspection readiness pressures. This technology is absorbing labor hours previously allocated to paper batch records and logbook maintenance, reallocating pharmacist capacity toward clinical consultation and formulation development.
EMA's tightened guidance on nitrosamine risk assessment is extending analytical requirements to compounded products using chemically synthesized APIs. European compounders must now document supplier qualification and impurity testing protocols that previously applied only to commercial manufacturers. Hormone replacement and cardiovascular therapeutic categories face the steepest compliance ramps, with Dutch and German pharmacies investing in mass spectrometry capabilities to meet documentation expectations.
Direct-to-patient shipping models are displacing traditional brick-and-mortar pickup for maintenance therapies in dermatology and chronic pain management. Patients receiving topical corticosteroid compounds or transdermal analgesic formulations increasingly expect refrigerated delivery to residential addresses within 48 hours. This channel shift concentrates in suburban and rural US markets where specialty pharmacy density remains thin, forcing compounders to build cold-chain logistics partnerships or invest in in-house fulfillment infrastructure.
Non-Sterile Compounding Pharmacy Market Segmentation
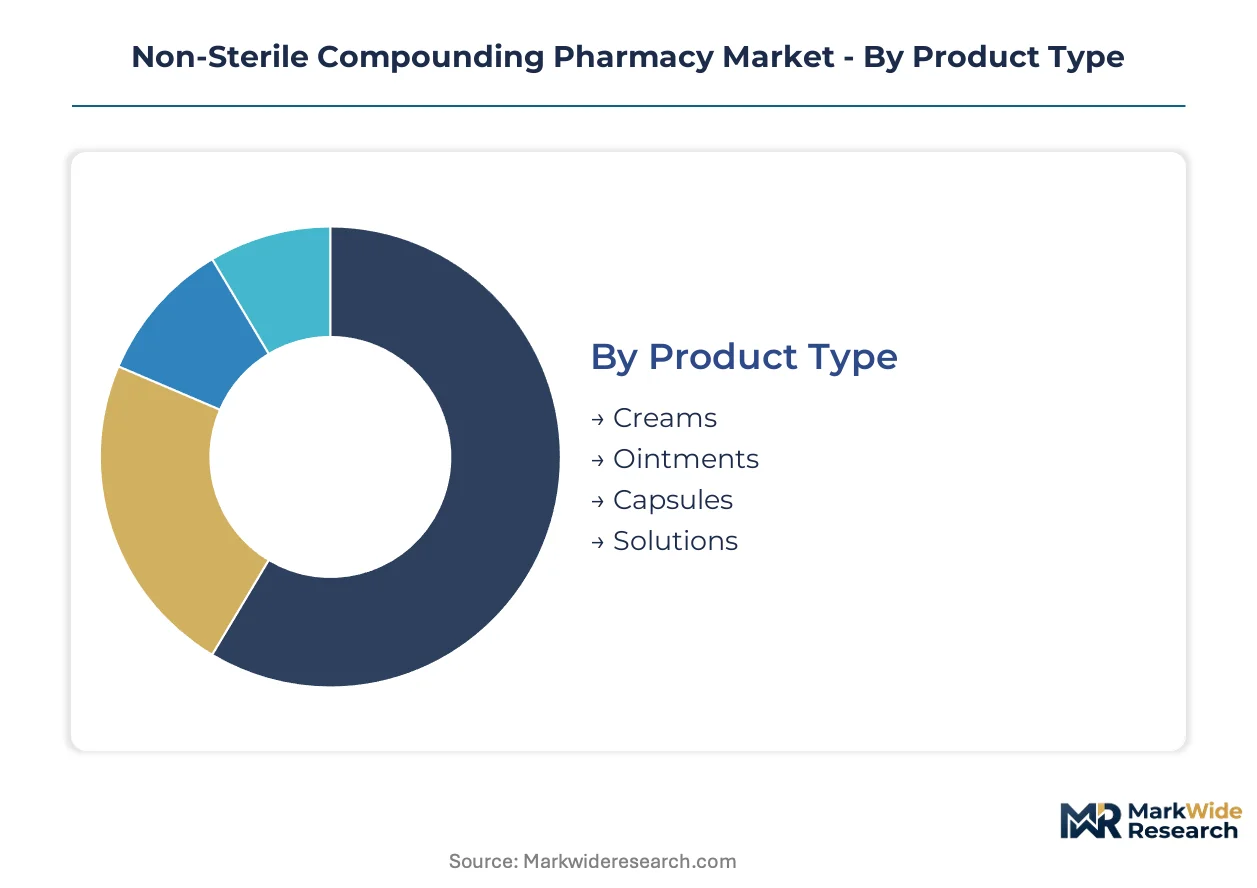
Non-sterile compounding pharmacy segmentation reveals how formulation complexity, patient setting, and therapeutic specialization create distinct operational and margin profiles. Each dimension shapes capital requirements, regulatory exposure, and competitive positioning differently.
Product Type:
Cost tier separates high-touch formulations requiring specialized equipment from commodity preparations pharmacies can produce with standard infrastructure.
- Creams:Oil-in-water emulsions with variable viscosity grades serve dermatology and localized pain applications. Hospital outpatient departments in Texas and Florida generate concentrated demand for topical analgesic creams where insurance reimbursement favors pharmacy-dispensed alternatives over commercial equivalents.
- Ointments:Hydrocarbon-based occlusive preparations with prolonged skin contact properties dominate wound care and psoriasis management. Long-term care facilities in Pennsylvania and Ohio sustain volume for petrolatum-based formulations where occlusion therapy protocols require patient-specific strength adjustments unavailable commercially.
- Capsules:Powder-filled gelatin shells enable precise dosing of hormone therapies and pediatric medications.
- Solutions:Aqueous preparations with documented stability profiles support oral and topical liquid dosing needs.
Creams lead volumes today; capsules are gaining share fastest.
End User:
Volume concentration and reimbursement pathway complexity differentiate institutional buyers from dispersed residential settings.
- Hospitals:Integrated health systems with captive compounding operations or tight 503B outsourcing relationships manage high-throughput perioperative and oncology support formulations. Academic medical centers in Massachusetts and North Carolina maintain internal non-sterile capacity for investigational drug preparation and rare disease protocols where commercial sourcing fails.
- Homecare:Discharge-driven medication administration to residential settings expands addressable patient base for maintenance therapies. Medicare Advantage plans in Arizona and Nevada increasingly authorize compounded transdermal pain formulations for home delivery, bypassing traditional retail pharmacy intermediaries.
- Clinics:Specialty practices in integrative medicine and anti-aging medicine drive cash-pay demand.
- Outpatient Facilities:Ambulatory surgery centers and dialysis clinics require just-in-time preparation support.
Hospitals anchor absolute demand; homecare channels are climbing the fastest.
Therapy Area:
Margin structure and regulatory scrutiny intensity vary sharply across therapeutic categories based on API cost and handling requirements.
- Pain Management:Topical and oral formulations combining multiple active pharmaceutical ingredients address opioid-sparing protocols. Workers compensation networks in California and New York drive volume for compounded topical analgesics where formulary restrictions on commercial products create therapeutic gaps.
- Hormone Replacement:Bioidentical estrogen, progesterone, and testosterone preparations require precise titration unavailable in mass-manufactured doses. Compounding pharmacies in Colorado and Washington specialize in sustained-release hormone pellet formulations for functional medicine practices seeking individualized dosing protocols.
- Pediatric Care:Flavored suspensions and alternate dosage forms improve compliance for young patients.
- Dermatology:Customized topical combinations address resistant conditions and cosmetic applications.
Pain management leads volumes today; hormone replacement shows the steepest expansion trajectory.
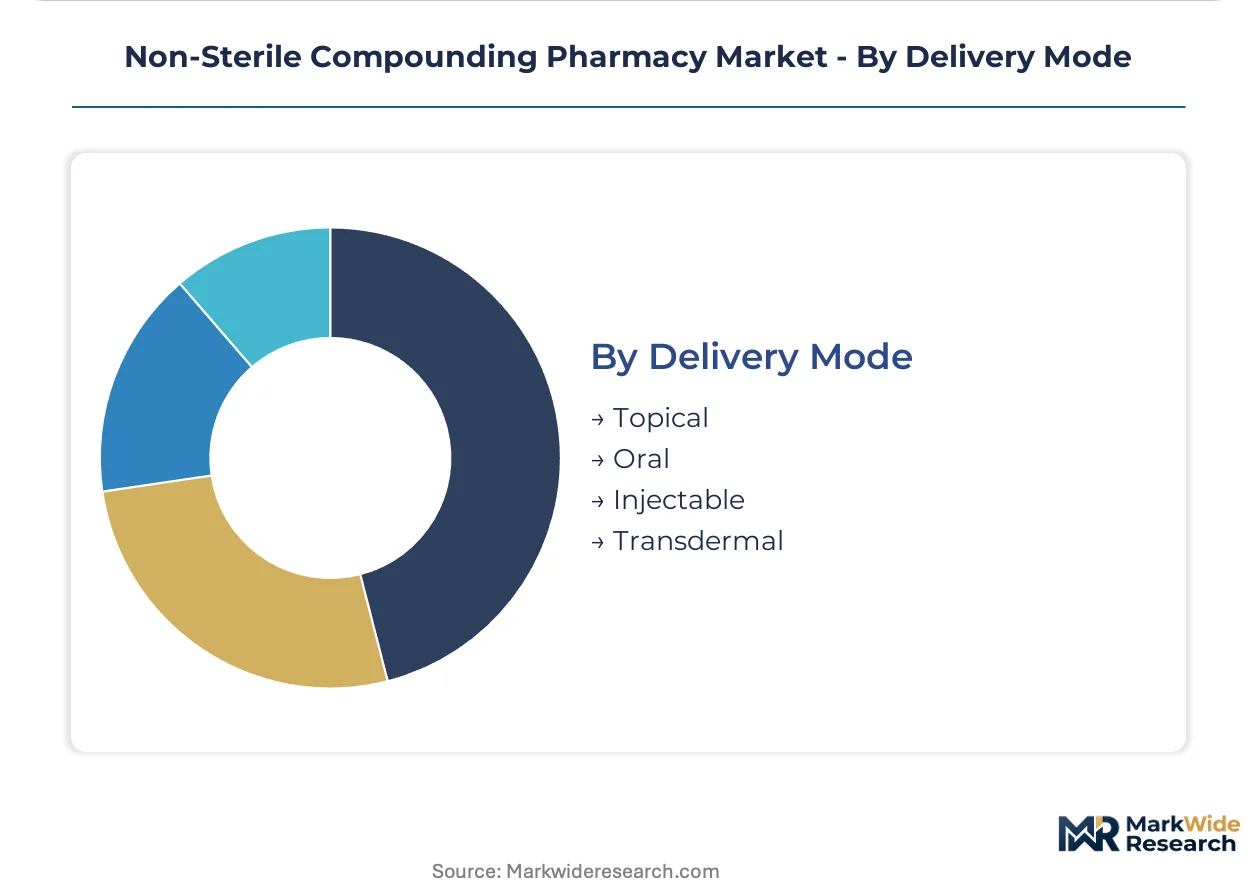
Delivery Mode:
Patient familiarity and formulation flexibility create divergent growth profiles across administration routes.
- Oral:Capsules, solutions, and suspensions leverage established patient compliance patterns and broad insurance coverage. Pediatric formulations in liquid and powder-for-reconstitution formats sustain demand across independent pharmacies in Illinois and Georgia where commercial alternatives lack age-appropriate dosing options.
- Topical:Creams, ointments, and gels enable localized drug delivery with reduced systemic exposure. Veterinary applications in Texas and Florida drive specialized transdermal gel demand for companion animal medication where oral administration proves impractical.
- Transdermal:Patch and gel systems provide sustained release for chronic conditions.
- Injectable:Non-sterile injectable preparations serve specific institutional protocols.
Oral delivery dominates volume today; topical segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-sterile compounding pharmacy emerged from hospital-based preparation units in the United States during the 1970s, then spread to Europe and Asia-Pacific as regulatory frameworks for personalized medicine matured. Today, demand concentrates in jurisdictions with established reimbursement pathways and specialized pharmacy infrastructure.
United States
Hospital discharge protocols and Medicare Advantage expansion drive residential medication delivery demand. The FDA's updated 503A guidance hardens quality standards for patient-specific compounders. Texas and Florida host concentrated networks of topical analgesic specialists serving workers compensation and pain management clinics.
Germany
EMA nitrosamine risk assessment requirements extend analytical obligations to hormone replacement and cardiovascular compounded products. German pharmacies invest in mass spectrometry capabilities to meet documentation expectations. The North Rhine-Westphalia region anchors European supply chain coordination for raw material sourcing.
United Kingdom
NHS specialist commissioning frameworks create institutional demand for pediatric and rare disease formulations unavailable commercially. The General Pharmaceutical Council maintains inspection standards aligned with USP Chapter 795 stability guidelines. London and the Southeast concentrate hospital-affiliated compounding operations serving academic medical centers.
India
CDSCO oversight of active pharmaceutical ingredient quality supports compounder supply chain diversification strategies. Indian manufacturers supply hormone and pain management APIs to European and North American compounders. Maharashtra and Gujarat host concentrated pharmaceutical manufacturing clusters serving export markets.
Australia
TGA guidance on compounded therapeutic goods shapes quality expectations for dermatology and hormone replacement preparations. Telehealth expansion drives direct-to-patient shipping models for maintenance therapies in rural and remote markets. New South Wales and Victoria concentrate compounding pharmacy networks serving metropolitan specialist practices.
Non-Sterile Compounding Pharmacy Market Competitive Environment
Capital-heavy hospital-integrated producers compete with asset-light centralized compounders, creating a tiered market structure where scale advantages diverge sharply. The vendor base separates into three strategic archetypes: multi-state 503B outsourcing facilities with current good manufacturing practice compliance, regional 503A patient-specific pharmacies, and hospital-captive operations serving single health systems. Dominant competitive moves include geographic expansion through licensing agreements and portfolio diversification into veterinary and wellness segments.
Within the centralized production tier, Empower Pharmacy represents the multi-state distribution model, while Fagron anchors European supply chain coordination. B. Braun Melsungen AG exemplifies the hospital-integrated archetype, reducing preparation risk at the point of care through captive service structures.
| Leading Market Players |
|---|
| Empower Pharmacy |
| TRUE NATURE HOLDING, INC |
| Fagron |
| QuVa Pharma |
| Dougherty's Pharmacy Inc. |
| B. Braun Melsungen AG |
| Baxter |
| Walgreens Co |
| Fresenius Kabi AG |
| Others |
Value Chain & Pricing Dynamics
API procurement costs for hormone and pain management compounds cascade through three distinct pricing tiers, with Indian and European raw material sourcing premiums separating 503B outsourcing facilities from independent 503A pharmacies serving cash-pay wellness segments.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing between high-volume 503B facilities and hospital systems, while spot purchasing prevails among independent 503A operators. Price differentiation hinges on USP Chapter 795 compliance certification tier and geographic delivery density, with rural homecare channels exhibiting highest sensitivity to shipping surcharges. Cost compression in topical formulation segments intensifies as petrochemical-derived excipient prices fluctuate, squeezing margin predictability for specialized cream and ointment producers.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian API manufacturers supplying hormone and cardiovascular active ingredients to North American and European compounders. Raw material dependencies center on bioidentical hormone precursors, specialized penetration enhancers, and gelatin capsule shells. Tariff exposure on Chinese-sourced excipients creates margin instability for topical specialists. Distribution runs through regional 503B hubs with validated cold-chain partnerships, bypassing traditional wholesale intermediaries for direct-to-patient residential delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-sterile compounding pharmacy market functions as a stable compounder, with patient-specific medication requirements creating durable demand insulation against commercial substitution.
For Market Incumbents: Deploy centralized production scale to absorb FDA 503A compliance cost escalations that threaten smaller regional operators. Deepen backward integration into API sourcing through European and Indian supplier qualification programs. Capture 503B outsourcing contracts from health systems divesting captive compounding operations under inspection readiness pressures. For New Entrants and Emerging Players: Cash-pay wellness clinics represent the most penetrable buyer archetype, with anti-aging and functional medicine practices seeking direct pharmacy relationships outside insurance networks. Veterinary compounding for companion animal practices offers white-space expansion with lower regulatory barriers than human therapeutics. Establish e-prescribing integrations with telehealth platforms to intercept prescriptions at clinical decision points. For Investors and Strategic Acquirers: Consolidation pressure builds where state-level inspection fragmentation creates compliance overhead disadvantages for single-jurisdiction operators. Mid-scale 503A pharmacies with validated quality systems and multi-state licensing infrastructure present acquisition targets for platform roll-up strategies. Monitor FDA enforcement discretion evolution for hospital-affiliated compounders as an inflection signal for outsourcing facility demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| USP Chapter 800 Facility Upgrade | Negative-pressure suite investments enable hazardous drug handling expansion into oncology support formulations. |
| Direct EHR Integration | Electronic health record connectivity captures prescriptions at point of care, bypassing retail pharmacy intermediaries. |
| Veterinary Formulation Library | Species-appropriate dosage development opens underpenetrated companion animal and exotic pet clinic demand. |
| Multi-State Licensing Expansion | Cross-jurisdiction operations reduce compliance fragmentation exposure under patchwork state board inspection regimes. |
| Mass Spectrometry Capability Investment | Analytical infrastructure satisfies EMA nitrosamine documentation requirements for European hormone API sourcing. |
Study Parameters
Coverage spans the United States, Germany, the United Kingdom, India, and Australia, with primary inputs from each market informing demand segmentation and regulatory trajectory assessments. The research combines structured interviews with compounding pharmacy operators, FDA regulatory affairs specialists, hospital procurement managers, and state board of pharmacy inspectors with secondary validation from USP documentation, FDA 503A/503B guidance releases, EMA nitrosamine risk assessment protocols, and CDSCO API quality circulars. Bottom-up prescription volume modeling and top-down pharmaceutical spending allocation triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from pricing dynamics across delivery mode, end-user setting, and therapy area dimensions. The analytical framework models patient discharge protocol shifts, Medicare Advantage homecare authorization trends, and USP Chapter 795 adoption timelines throughout the forecast period. CAGRs derive from segment-level prescription growth rates cross-referenced with reimbursement pathway evolution and regulatory compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; hospital-affiliated and 503B outsourcing channels carry tighter precision than dispersed independent 503A operations. Forecasts reflect assumptions about FDA enforcement consistency, state-level harmonization progress, and commercial product substitution rates in hormone and pediatric therapeutic categories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market