
 Ceftriaxone Sodium (API) Market | 2026-2036
Ceftriaxone Sodium (API) Market Size, Share, and Industry Trends Forecast 2026-2036
Ceftriaxone Sodium (API) Market Analytics
Chinese bulk API producers is rebalancing output toward sterile-grade ceftriaxone sodium as Western buyers tighten qualification standards. CSPC Pharmaceutical Group leverages backward integration into 7-ACA fermentation to control raw material costs. Aurobindo Pharma Limited anchors its position through FDA-inspected sterile injectable facilities in India. Qilu Antibiotics Pharmaceutical specializes in high-purity powder grades for European hospital formulators.
Ceftriaxone sodium is a third-generation cephalosporin antibiotic active pharmaceutical ingredient, typically supplied as a sterile sodium salt with potency specifications exceeding 900 micrograms per milligram, manufactured through multi-step semi-synthetic conversion from 7-aminocephalosporanic acid followed by crystallization and lyophilization. It serves primarily as the foundational ingredient in parenteral formulations treating severe gram-negative and gram-positive infections in hospital settings. The injection segment dominates value capture due to sterility validation requirements and higher barrier-to-entry manufacturing, while intravenous delivery mode commands the largest volume share because critical care protocols favor controlled infusion over bolus administration. Hospital use applications concentrate procurement power through tender-based purchasing, compressing margins for non-sterile powder suppliers relative to finished sterile injectable providers.
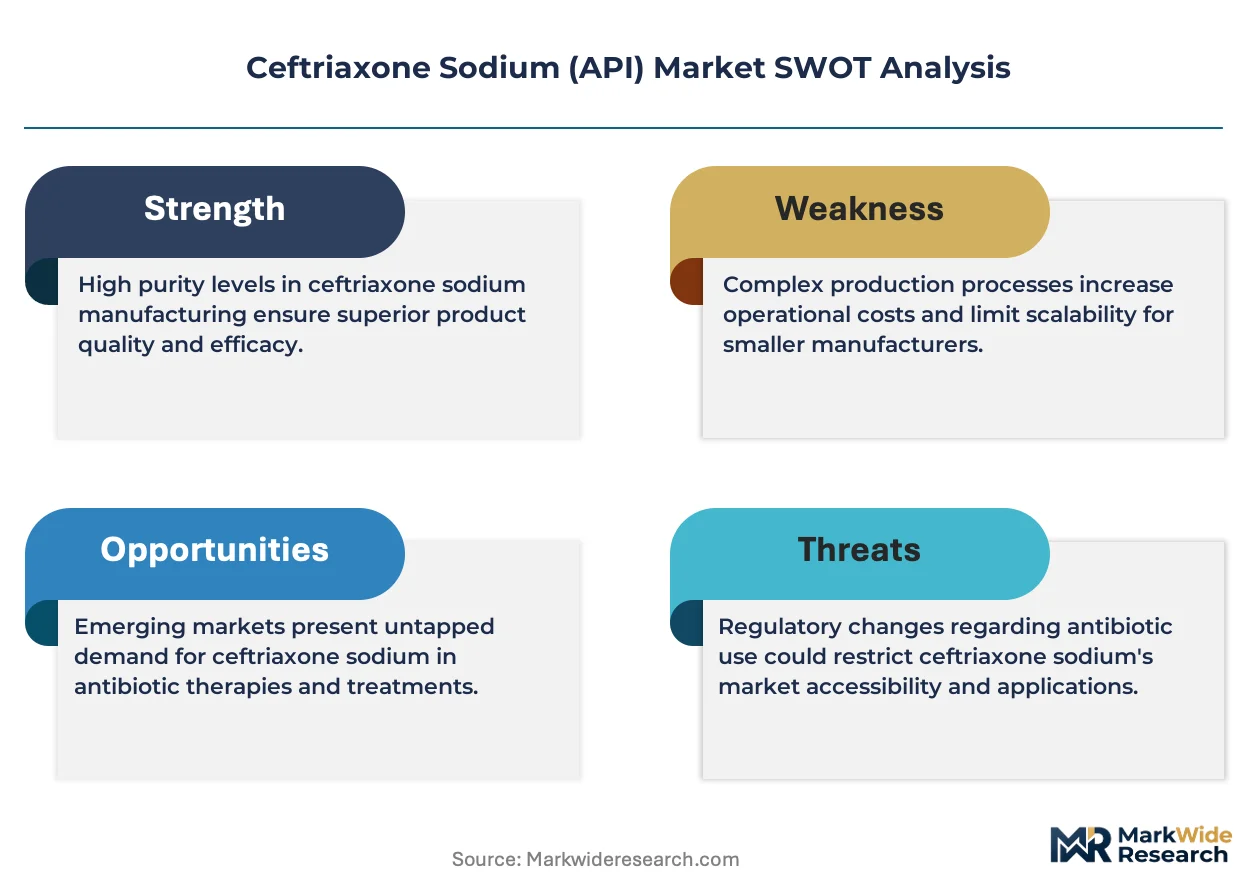
FDA, EMA, and China's NMPA collectively enforce escalating data integrity and sterility assurance standards that determine market access eligibility for ceftriaxone sodium API manufacturers. India's CDSCO and China's NMPA have tightened inspection frequencies for export-oriented facilities, raising compliance capital requirements for mid-tier producers. Stakeholders must monitor regulatory divergence between US and European pharmacopeial sterility test methods, as harmonization gaps threaten batch release timelines and contract manufacturing agreements.
Market Dynamics
Western hospital procurement teams are consolidating ceftriaxone sodium API contracts around qualified sterile injectable suppliers, compressing margins for non-sterile powder traders and forcing capital reinvestment into lyophilization and aseptic filling capabilities.
Growth Catalysts
- Resistant gram-negative infections:Hospital-acquired infections resistant to first-line antibiotics are expanding parenteral cephalosporin protocols in intensive care units across Germany, France, and the United States.
- EMA Annex 1 revision:The 2022 update to sterile manufacturing guidelines is disqualifying legacy facilities, creating replacement demand for EU-GMP-certified API supply.
- Continuous manufacturing adoption:Fluid-bed crystallization and in-line PAT controls are reducing batch-to-batch variability for high-potency ceftriaxone sodium production.
Market Restraints
- 7-ACA feedstock concentration:Three Chinese fermentation houses control over 60 percent of global 7-aminocephalosporanic acid supply, exposing API producers to input cost volatility and allocation risk.
- FDA sterility validation backlog:Extended inspection timelines for pre-approval manufacturing sites are delaying market entry for new sterile API entrants by 18-24 months.
- Carbapenem substitution:Meropenem and ertapenem are displacing ceftriaxone in Pseudomonas coverage protocols, narrowing the addressable infection spectrum.
Strategic Opportunities
- Sub-Saharan Africa tender expansion:WHO prequalification pathways are opening institutional procurement channels for Indian and Chinese sterile API suppliers in Nigeria, Kenya, and Ethiopia.
- Prefilled syringe formulation partnerships:Collaboration with finished-dose formulators on ready-to-administer ceftriaxone products captures value downstream of bulk powder.
- Green chemistry incentives:China's dual carbon goals and the EU Green Deal are subsidizing enzymatic 7-ACA conversion processes that reduce solvent waste and energy intensity.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified personnel for Grade A filling operations and environmental monitoring are in short supply across India and Eastern European manufacturing clusters.
- Data integrity remediation costs:FDA warning letters citing ALCOA+ deficiencies are forcing mid-tier API producers to replace legacy chromatography data systems with compliant informatics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceftriaxone Sodium (API) Market |
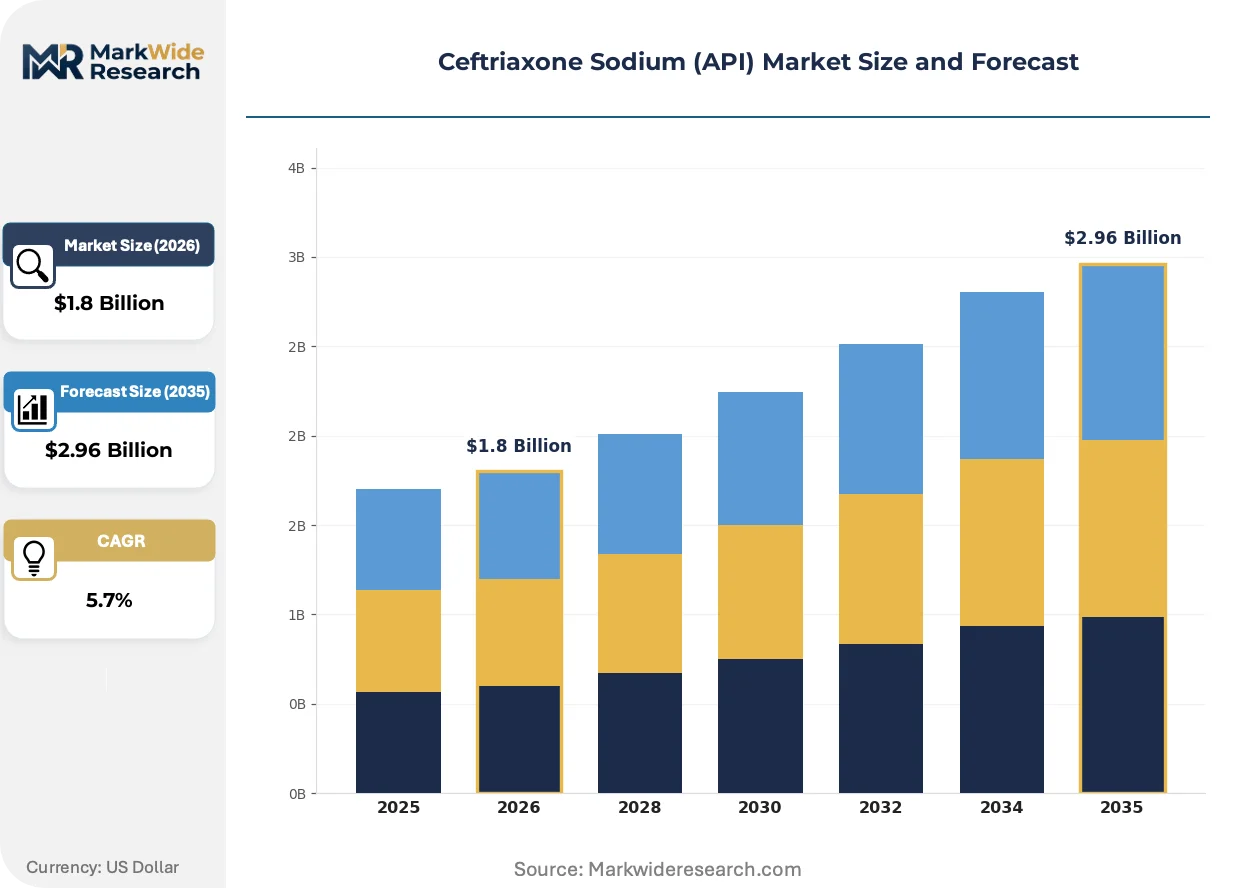
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Powder, Solution, Sterile Application: Infectious Disease Treatment, Prophylaxis, Hospital Use, Outpatient Care Manufacturing Stage: API Production, Formulation, Quality Control, Packaging Delivery Mode: Intravenous, Intramuscular, Oral, Others |
| Companies Covered | Sinopharm Sandwich, Lupin Pharmaceuticals, United Laboratories, Aurobindo Pharma Limited, CSPC Pharmaceutical Group, Union Chempharma, Qilu Antibiotics Pharmaceutical, Zhuhai United Laboratories, NCPC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceftriaxone Sodium (API) Market Evolving Landscape
Process analytical technology and single-use containment systems are displacing fixed stainless-steel trains in cephalosporin API manufacturing, while regulatory divergence between US and European sterility test methods is complicating batch release logistics for multinational suppliers.
Continuous direct compression and real-time release testing are automating powder homogeneity verification for sterile ceftriaxone sodium. European hospital formulators are adopting these in-process controls to reduce finished-goods quarantine periods. The technology is automating quality assurance workflows that previously required offline laboratory analysis and 14-day sterility incubation holds.
China's NMPA has aligned data integrity inspection protocols with FDA and EMA standards, requiring complete audit trails for chromatography and spectroscopy systems in API facilities. Domestic producers seeking export qualification must retrofit legacy electronic systems or risk export license suspension. Sterile injectable specialists with pre-validated informatics infrastructure are capturing contract manufacturing share from commodity powder traders.
Hospital purchasing consortia in Italy, Spain, and the Netherlands are consolidating annual ceftriaxone sodium requirements into multi-year framework agreements with pre-qualified sterile API suppliers. Tender documentation now mandates FDA or EMA inspection history and dedicated manufacturing line allocation. This concentration is squeezing spot-market traders and rewarding vertically integrated producers with captive sterile filling capacity.
Ceftriaxone Sodium (API) Market Segmentation
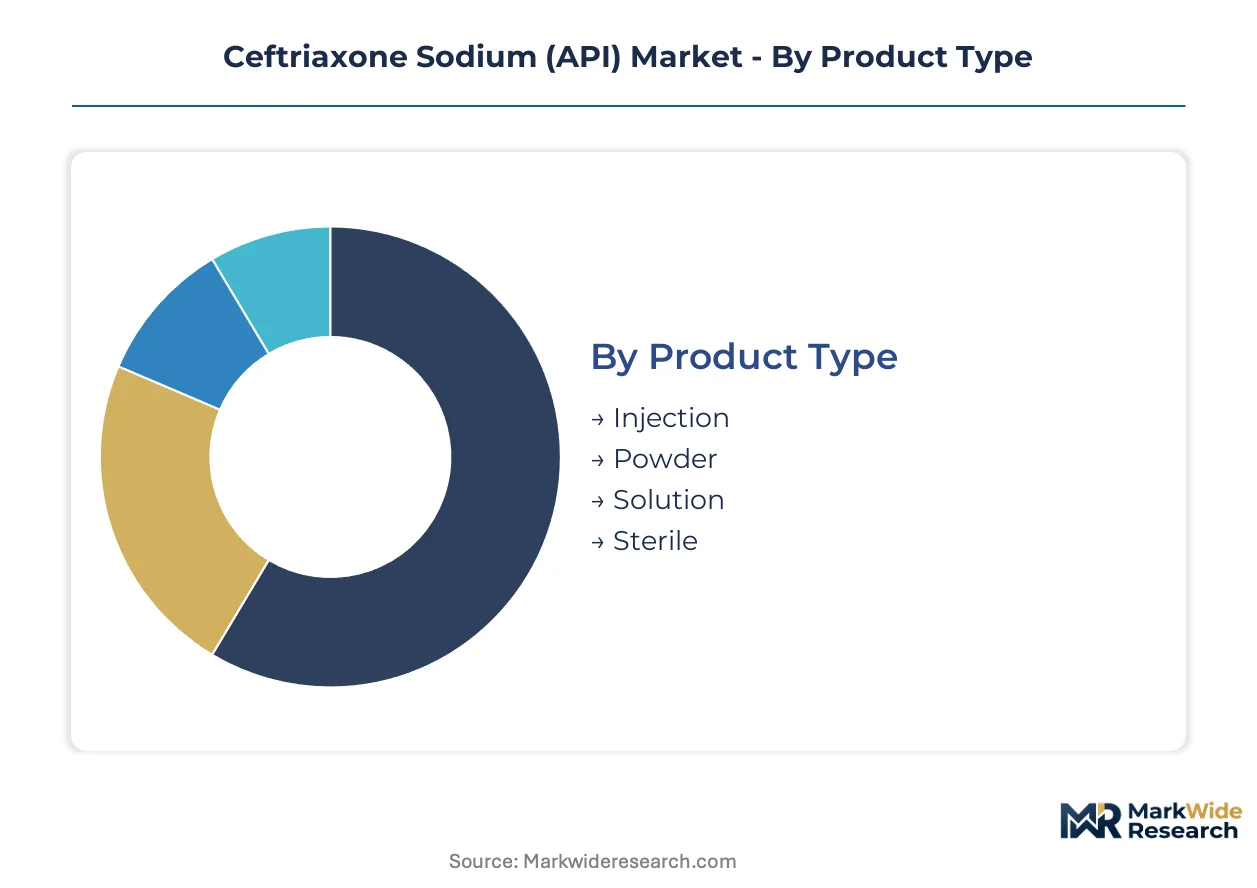
Ceftriaxone sodium API procurement diverges sharply across product forms and clinical settings. Hospital formulators and contract manufacturers prioritize segments that balance sterility assurance with total cost of administration.
Product Type:
Upgrade cycles from non-sterile powder to sterile-grade alternatives are compressing margins for legacy commodity suppliers while rewarding lyophilization-capable producers.
- Injection:Sterile liquid formulations in vials or ampoules require aseptic filling and terminal sterilization validation. Demand concentrates in German and French hospital procurement consortia where EMA Annex 1 compliance disqualifies non-sterile alternatives.
- Powder:Lyophilized or crystalline bulk API with potency specifications exceeding 900 micrograms per milligram serves formulators with captive sterile filling lines. Indian and Chinese exporters dominate spot-market supply, though FDA inspection backlogs constrain new entrants.
- Solution:Pre-reconstituted liquid presentations reduce pharmacy compounding burden in high-volume emergency departments.
- Sterile:Terminal sterilization or aseptic processing certification opens access to WHO prequalification pathways for institutional tenders in Sub-Saharan Africa.
Injection sits at the top of the volume ranking, with Sterile climbing the fastest.
Application:
Cost tier stratification separates premium hospital-grade supply from economy outpatient channels.
- Infectious Disease Treatment:Curative protocols for resistant gram-negative infections in intensive care units demand highest-potency API with validated endotoxin limits. Procurement in the United States and Germany favors suppliers with FDA or EMA inspection history.
- Prophylaxis:Pre-surgical antibiotic regimens in orthopedic and cardiac centers require batch-to-batch consistency for standardized dosing protocols. CDSCO-regulated Indian manufacturers capture share through cost-competitive sterile powder supply.
- Hospital Use:Tender-based purchasing through consortium structures in Italy, Spain, and the Netherlands compresses margins while demanding dedicated manufacturing line allocation.
- Outpatient Care:Home infusion and ambulatory surgical centers drive demand for ready-to-administer presentations with extended stability profiles.
Infectious Disease Treatment commands the largest revenue pool, though Prophylaxis is expanding most quickly as surgical volume rebounds.
Manufacturing Stage:
Volume concentration favors upstream API producers with backward integration into 7-ACA fermentation.
- API Production:Semi-synthetic conversion from 7-aminocephalosporanic acid through multi-step acylation and crystallization. Chinese fermentation houses control feedstock supply, exposing non-integrated formulators to allocation risk.
- Formulation:Sterile filling, lyophilization, and aseptic processing for finished injectable products. European hospital formulators are consolidating contracts around qualified sterile API suppliers with captive filling capacity.
- Quality Control:Chromatographic purity testing, endotoxin assays, and sterility validation per USP and EP monographs. NMPA-aligned data integrity requirements are forcing legacy facility retrofits.
- Packaging:Barrier containment, labeling, and cold-chain distribution for temperature-sensitive sterile products.
API Production anchors the value chain by volume, with Quality Control gaining share fastest as regulatory inspection intensity escalates.
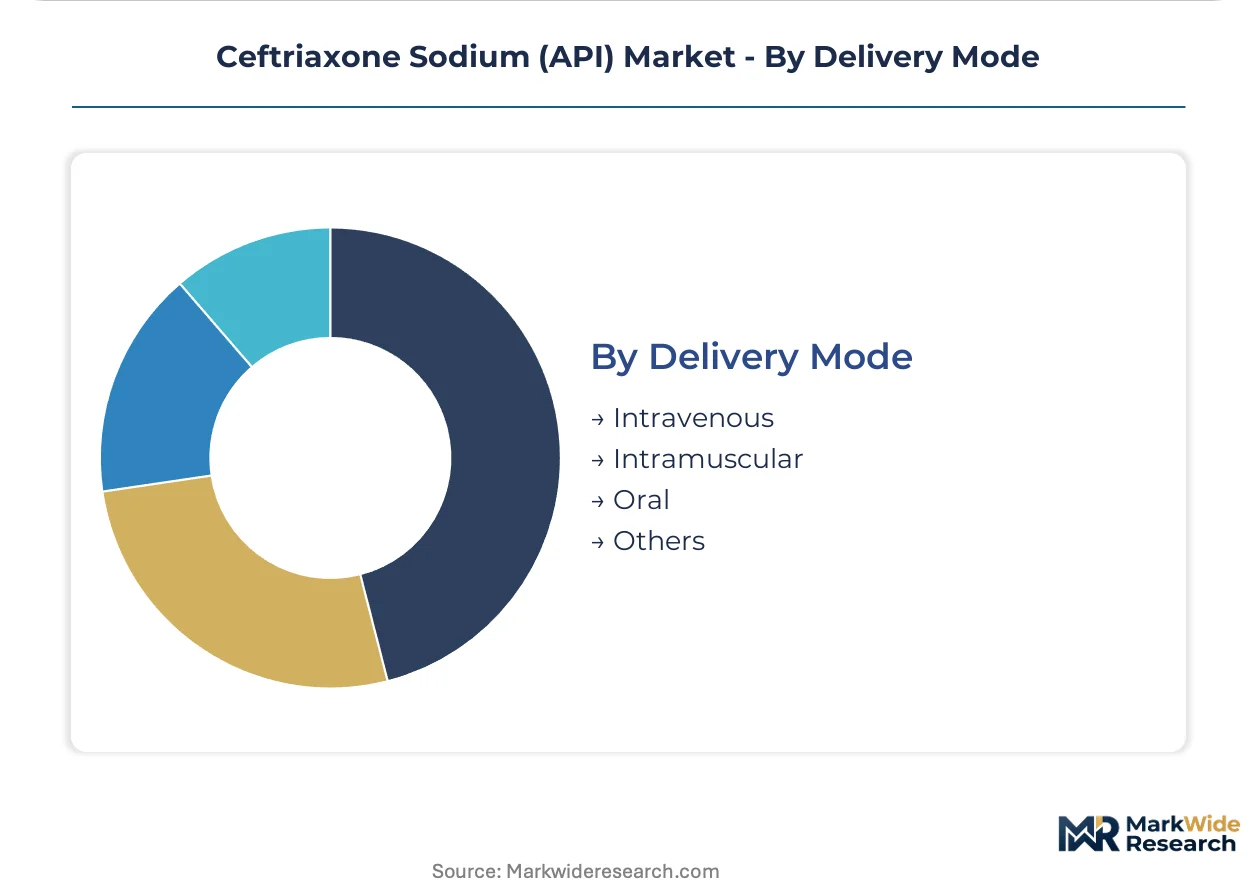
Delivery Mode:
Customer type segmentation separates acute-care infusion protocols from ambulatory injection preferences.
- Intravenous:Controlled infusion over 30 minutes dominates critical care protocols for severe sepsis and meningitis. United States hospital systems specify IV presentations for formulary inclusion.
- Intramuscular:Bolus administration in emergency departments and outpatient settings where vascular access is constrained. African and Latin American procurement channels favor IM-ready formulations for resource-limited settings.
- Oral:Bioavailability limitations restrict ceftriaxone to parenteral routes; oral cephalosporin alternatives serve step-down therapy.
- Others:Subcutaneous and intraosseous routes in specialized pediatric and military medicine applications.
Intravenous holds the dominant volume position, with Intramuscular climbing fastest as ambulatory care expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing ceftriaxone sodium API production toward jurisdictions where compliance costs remain manageable relative to Western standards. Manufacturers in India and China capture contract volume as FDA and EMA inspection backlogs delay qualification timelines for new entrants elsewhere.
United States
Hospital procurement consortia in Texas and Florida are consolidating annual ceftriaxone requirements into multi-year framework agreements with pre-qualified sterile API suppliers. FDA sterility validation backlogs extending 18-24 months are delaying market entry for new manufacturing sites. The New Jersey pharmaceutical corridor hosts formulation specialists with captive sterile filling capacity serving academic medical centers.
Germany
EMA Annex 1 revision implementation is disqualifying legacy facilities, creating replacement demand for EU-GMP-certified API supply from qualified vendors. Hospital purchasing consortia in Bavaria and North Rhine-Westphalia mandate dedicated manufacturing line allocation in tender documentation. The Frankfurt-Rhine-Main cluster concentrates sterile injectable formulators serving intensive care protocols.
China
NMPA-aligned data integrity inspection protocols now require complete audit trails for chromatography systems in API facilities seeking export qualification. The Shandong Peninsula hosts fermentation houses controlling over 60 percent of global 7-ACA feedstock supply. CSPC Pharmaceutical Group leverages backward integration into 7-ACA fermentation to control raw material costs in Hebei province.
India
CDSCO has tightened inspection frequencies for export-oriented facilities, raising compliance capital requirements for mid-tier producers in Telangana and Gujarat. Aurobindo Pharma Limited anchors supply through FDA-inspected sterile injectable facilities serving Western hospital procurement channels. The Hyderabad-Visakhapatnam corridor specializes in high-purity powder grades for European hospital formulators.
Brazil
ANVISA import licensing requirements for sterile APIs are channeling procurement toward pre-qualified Indian and Chinese suppliers with established inspection history. Hospital networks in São Paulo and Rio de Janeiro are expanding parenteral cephalosporin protocols as resistant gram-negative infections climb. The São Paulo state pharmaceutical cluster concentrates finished-dose formulators dependent on imported API supply.
Ceftriaxone Sodium (API) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sterile-grade specialization and prefilled syringe partnerships. The vendor base stratifies across three tiers: integrated fermentation-to-API houses, sterile processing specialists, and commodity powder traders facing margin compression. Two archetypes dominate competitive positioning: backward-integrated Chinese producers controlling 7-ACA supply, and Indian formulators with FDA-inspected sterile filling infrastructure. Capacity expansion and regulatory qualification acceleration represent the dominant competitive moves as Western buyers consolidate procurement.
Within the integrated-fermentation archetype, CSPC Pharmaceutical Group and Qilu Antibiotics Pharmaceutical exemplify producers with captive 7-ACA supply chains. Among Indian sterile processing specialists, Aurobindo Pharma Limited occupies a position representing FDA-validated aseptic filling capability. These three anchors illustrate the bifurcation between feedstock-integrated Chinese houses and compliance-validated Indian formulators.
| Leading Market Players |
|---|
| Sinopharm Sandwich |
| Lupin Pharmaceuticals |
| United Laboratories |
| Aurobindo Pharma Limited |
| CSPC Pharmaceutical Group |
| Union Chempharma |
| Qilu Antibiotics Pharmaceutical |
| Zhuhai United Laboratories |
| NCPC |
| Others |
Value Network & Pricing Analysis
Backward integration into 7-ACA fermentation anchors both supply security and pricing power for CSPC Pharmaceutical Group and Qilu Antibiotics Pharmaceutical, while non-integrated Indian formulators absorb margin compression from feedstock volatility. This structural divide separates price-setters with captive raw material supply from price-takers exposed to Chinese fermentation house allocation decisions.
Pricing Analysis
Direct-to-hospital procurement discounts dominate EMA Annex 1-compliant supply, with three-tier pricing structure across sterile injectable, lyophilized powder, and non-sterile commodity grades differentiating value capture. FDA inspection history commands premium positioning in United States academic medical center contracts, while spot-market Indian powder faces relentless cost compression from consolidated European tender structures. Pricing pressure stems from hospital purchasing consortia in Italy and the Netherlands mandating multi-year framework agreements with dedicated line allocation. Outpatient channels exhibit highest price sensitivity; intensive care formulary directors prioritize sterility assurance over unit cost.
Supply Chain Analysis
Cold-chain freight costs for temperature-sensitive sterile products constrain distribution radius from manufacturing clusters in Shandong Peninsula and Hyderabad-Visakhapatnam corridor. API production concentrates in China and India, with formulation finishing anchored in Germany and the United States for Western hospital markets. Raw material supply draws from 7-aminocephalosporanic acid fermentation, acylation reagents, and lyophilization excipients. Single-source vulnerability pervades 7-ACA feedstock where three Chinese houses control majority supply. Distribution runs through qualified wholesale distributors with GDP certification for sterile pharmaceutical logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceftriaxone sodium API market has entered a late-cycle quality phase where EMA Annex 1 compliance and FDA inspection history now outweigh pure cost positioning in procurement decisions. Hospital formulary shifts toward resistant gram-negative coverage protocols favor suppliers with validated sterile processing infrastructure.
For Market Incumbents: Acquire lyophilization and aseptic filling capacity in EU-GMP-certified facilities to preempt EMA Annex 1 disqualification of legacy powder-only operations. Secure dedicated 7-ACA supply agreements with Shandong fermentation houses before allocation tightening accelerates. Carbapenem substitution in Pseudomonas protocols threatens volume; defend position by embedding into prefilled syringe partnerships with finished-dose formulators capturing downstream value. For New Entrants and Emerging Players: Single-use containment technology offers entry pathway around fixed stainless-steel capital barriers that incumbent houses have already sunk. Target Sub-Saharan Africa WHO prequalification tenders where sterile-grade supply scarcity meets institutional procurement expansion in Nigeria and Kenya. Partner with European hospital formulators on real-time release testing adoption to reduce quarantine periods and differentiate from commodity traders. For Investors and Strategic Acquirers: Roll-up economics work for FDA-inspected sterile injectable specialists because regulatory qualification backlogs create artificial scarcity and pricing power for pre-validated assets. Five-to-ten year viability hinges on enzymatic 7-ACA conversion technology subsidies under China's dual carbon goals and the EU Green Deal. Watch for FDA warning letter resolution velocity at mid-tier Indian producers as inflection signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Investment | Qualifies facilities for German and French hospital consortium tenders displacing legacy suppliers. |
| Backward Integration into 7-ACA Fermentation | CSPC Pharmaceutical Group secures raw material cost control against Shandong supply concentration. |
| Prefilled Syringe Formulation Partnership | Captures value downstream of bulk powder in ready-to-administer emergency department protocols. |
| WHO Prequalification Pathway Execution | Opens institutional procurement channels in Nigeria, Kenya, and Ethiopia for sterile API supply. |
| Real-Time Release Testing Adoption | Reduces finished-goods quarantine periods for Italian and Spanish hospital formulators. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and fermentation capacity tracking — were reconciled through structured primary interviews with sterile manufacturing executives, CDSCO inspection specialists, hospital formulary directors, and EMA quality assessors. Secondary validation drew from FDA warning letter repositories, EMA GMP inspection databases, WHO prequalification listings, and customs trade flow records. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level estimates.
Historical volume trajectories were cross-referenced against panel input from procurement managers at United States academic medical centers and German hospital purchasing consortia. Segmentation modeling spanned product form, sterility grade, delivery mode, and regional regulatory cluster across the projection horizon. CAGRs were derived from infection protocol adoption curves, resistant pathogen surveillance data, and tender award patterns. Forecast inputs incorporated EMA Annex 1 implementation timelines and NMPA data integrity inspection intensity.
The model holds under sustained regulatory divergence between US and European pharmacopeial standards; deviation in harmonization progress or abrupt 7-ACA supply disruption would shift capacity expansion assumptions. Stakeholders should weight assumptions against their own operating context and qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Global Polio Vaccines Market