
 Global Pharmerging Market | 2026-2036
Global Pharmerging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmerging Market Analysis
Hospital procurement is reorganizing around biologics and chronic disease therapies as government tenders in Brazil, India, and China expand formulary access. Pfizer Inc. leverages its manufacturing scale to anchor supply agreements with public health systems across Latin America and Southeast Asia. Sun Pharmaceutical Industries Ltd. competes through backward integration into active pharmaceutical ingredients, sustaining cost advantages in generic oncology. F. Hoffmann-La Roche AG differentiates via technology leadership in companion diagnostics, positioning its portfolio for precision medicine tenders.
Pharmerging encompasses pharmaceutical markets in emerging economies where drug access programs, local production incentives, and expanding health insurance coverage define commercial viability. These markets operate through dual-track regulatory pathways: WHO prequalification for donor-funded procurement alongside national marketing authorization for domestic reimbursement. Biologics and chronic disease therapies command widening margin pools as patent cliffs and biosimilar competition reshape pricing power. E-commerce platforms represent the fastest-growing end user channel, though pharmacies and hospitals still control volume for regulated cold-chain products. Digital therapeutics and mobile health apps are displacing traditional patient support programs, particularly in cardiology and neurology applications where remote monitoring improves adherence.
FDA, EMA, and WHO prequalification standards collectively shape product registration timelines and manufacturing audit requirements for multinational suppliers entering pharmerging territories. India's CDSCO and China's NMPA impose additional local clinical trial and bioequivalence data requirements that extend market access lead times. Brazil's ANVISA enforces good manufacturing practice certifications aligned with PIC/S standards, filtering out subscale competitors. Stakeholders must decide whether to pursue parallel regulatory filings across multiple agencies or sequence entry through priority markets with mutual recognition agreements.
Market Dynamics
Hospital procurement across Brazil, India, and China is reorganizing around biologics and chronic disease therapies as government tenders expand formulary access for oncology and immunology treatments.
Growth Catalysts
- CDSCO bioequivalence mandates:India's tightening standards for generic oncology products filter out subscale competitors and elevate quality benchmarks for surviving manufacturers.
- Chronic disease prevalence:Cardiology and diabetes patient volumes in Southeast Asian public health systems are accelerating demand for long-acting injectable therapies.
- WHO prequalification pathways:Donor-funded procurement programs in sub-Saharan Africa and South Asia create predictable volume commitments for qualified suppliers.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India control upstream supply of oncology API intermediates, exposing formulators to geopolitical disruption risk.
- Cold-chain infrastructure gaps:Last-mile temperature control failures in tropical climates limit biologics penetration outside major urban hospital networks.
- NMPA clinical trial requirements:China's mandatory local bioequivalence studies extend market access timelines by 18-24 months for multinational entrants.
Strategic Opportunities
- Indonesia's national health insurance expansion:Jaminan Kesehatan Nasional formulary inclusions for biosimilars create first-mover advantages for qualified suppliers.
- E-commerce pharmacy platforms:Direct-to-patient delivery models for chronic disease maintenance therapies bypass traditional wholesale distribution markups.
- Companion diagnostic bundling:Precision medicine tenders in Brazil's Sistema Único de Saúde reward integrated test-and-treat offerings.
Industry Challenges
- Bioprocessing talent scarcity:Mammalian cell culture and aseptic fill-finish expertise concentrates in Shanghai, São Paulo, and Hyderabad, driving wage inflation.
- Multi-agency filing complexity:Parallel WHO, FDA, and national regulatory submissions require dedicated regulatory affairs capacity that mid-tier firms lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmerging Market |
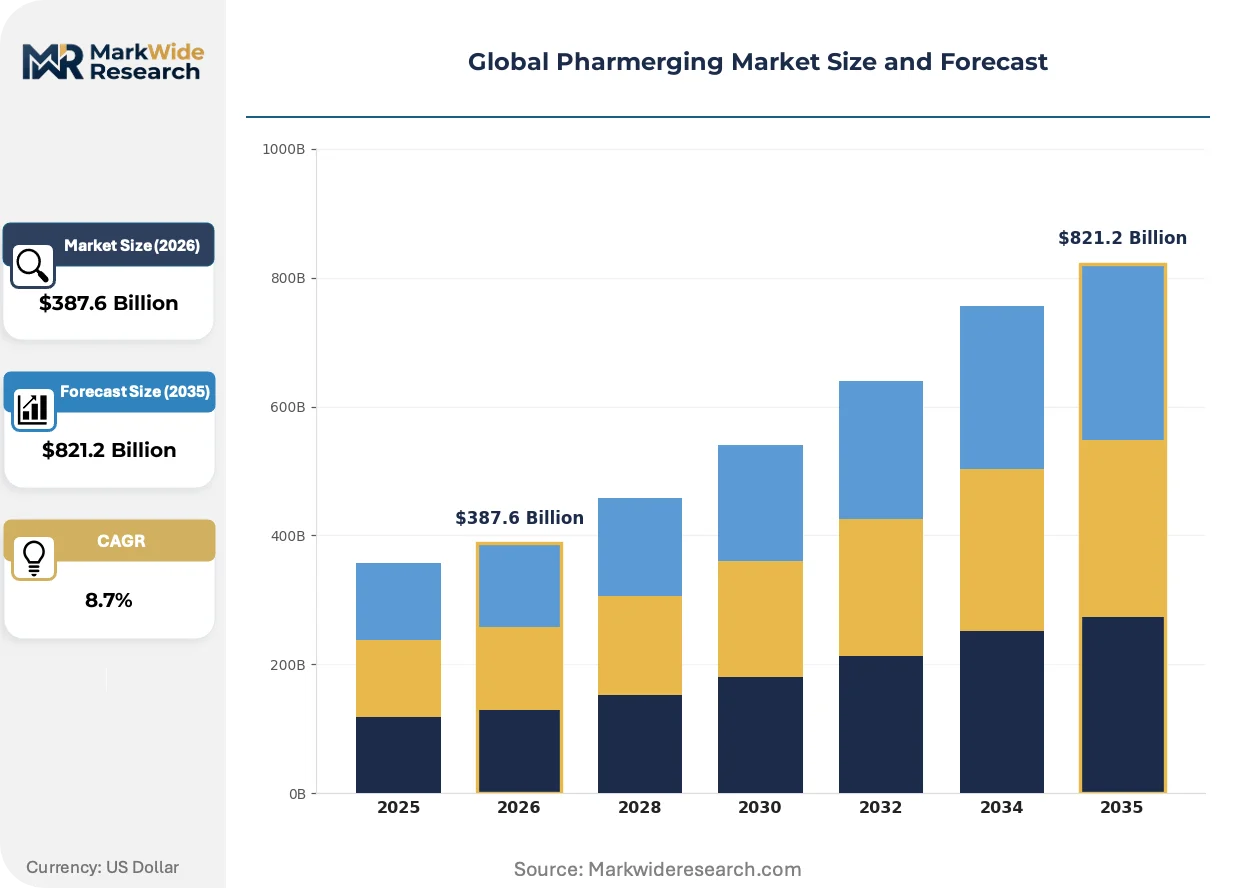
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biologics, Chronic Disease Therapies End User: Pharmacies, Hospitals, Clinics, E-commerce Platforms Application: Cardiology, Oncology, Neurology, Immunology Technology: Telemedicine, Mobile Health Apps, Wearable Devices, Digital Therapeutics |
| Companies Covered | Sanofi S.A., Pfizer Inc., AstraZeneca Plc, GlaxoSmithKline Plc, F. Hoffmann-La Roche AG, Novartis AG, Johnson & Johnson, Eli Lilly and Company, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmerging Market Emerging Trajectories
Digital therapeutics and mobile health applications are compressing traditional patient support programs while biosimilar competition reshapes pricing architectures across public procurement systems.
Continuous manufacturing platforms for oral solid dosages are fragmenting batch-based production economics. Contract development and manufacturing organizations in India and China are adopting single-use bioreactor trains to reduce cross-contamination risk for oncology biologics. This technology is fragmenting the traditional value chain separation between API synthesis and finished dose formulation, enabling integrated campus models that collapse cost structures.
EMA's revised good manufacturing practice Annex 1 for sterile products entered force in 2023, mandating barrier isolation technology and real-time environmental monitoring. European-qualified manufacturers are retrofitting legacy fill-finish lines at capital costs exceeding facility replacement thresholds. Oncology injectables and ophthalmic biologics face the steepest compliance curves, with Indian and Chinese exporters accelerating PIC/S mutual recognition applications to maintain EU market access.
Public hospital consortia in Brazil, Mexico, and Thailand are consolidating tender volumes into multi-year framework agreements with price-volume mechanisms. Traditional distributor networks lose margin to direct manufacturer contracting. This concentration is most visible in oncology procurement, where state purchasing agencies now represent 60-70 percent of national consumption volume and negotiate site-of-manufacture audits into supply contracts.
Global Pharmerging Market Segmentation
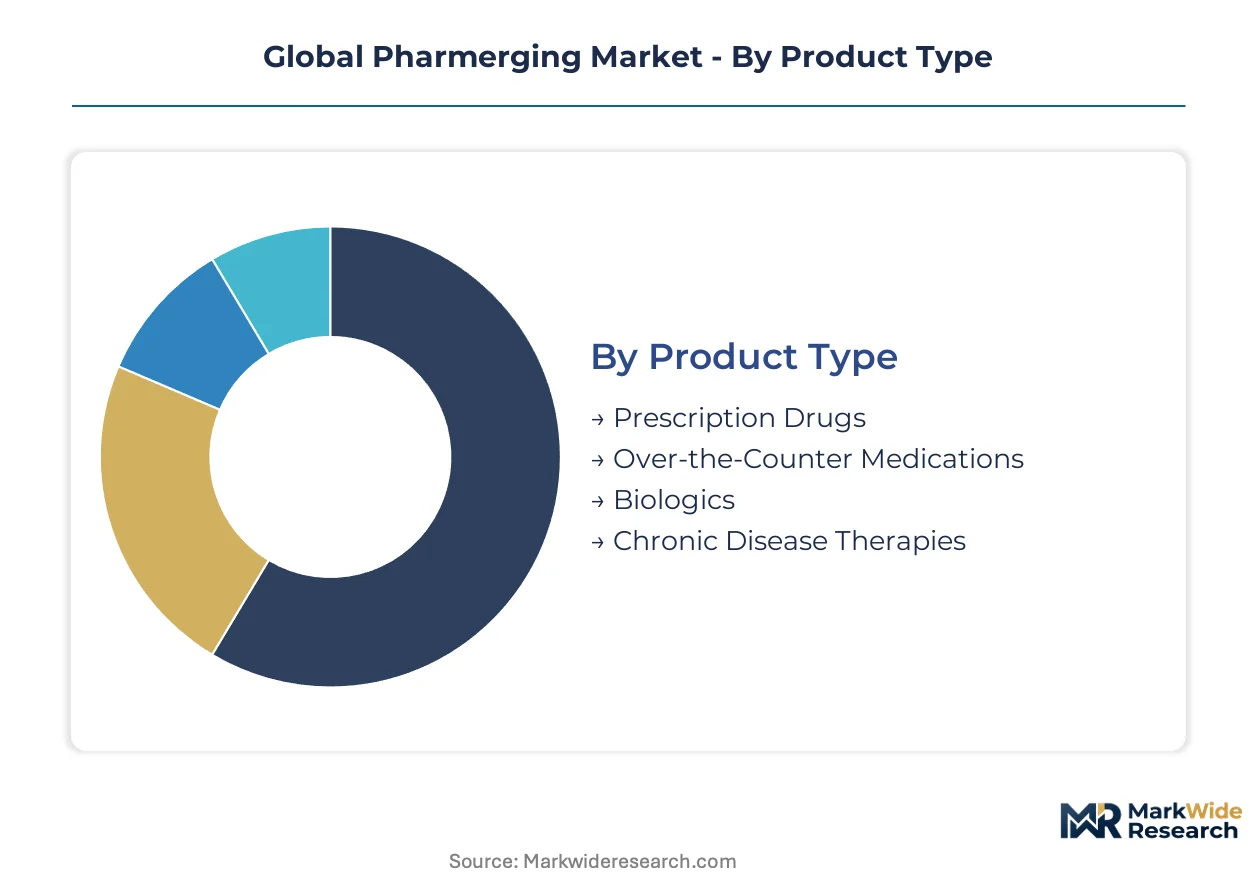
Segmentation in pharmerging markets determines regulatory pathway selection and distribution strategy. Product type dictates whether WHO prequalification or national bioequivalence studies take priority. End user channel shapes cold-chain requirements and last-mile logistics investments.
Product Type:
Biologics and chronic disease therapies concentrate manufacturing partnerships in India and China for export-led supply, while prescription generics serve predominantly domestic tender markets across Brazil and Southeast Asia.
- Biologics:Mammalian cell culture-derived monoclonal antibodies and recombinant proteins require barrier isolation technology under EMA Annex 1 standards. Demand clusters in Brazilian and Indian oncology hospital networks where state purchasing agencies negotiate site-of-manufacture audits into multi-year framework agreements.
- Chronic Disease Therapies:Long-acting injectables for diabetes and cardiovascular conditions command widening margin pools as Jaminan Kesehatan Nasional and Sistema Único de Saúde expand formulary access. Indonesian and Brazilian public health systems drive volume concentration through price-volume mechanisms.
- Prescription Drugs:Small-molecule generics dominate CDSCO and ANVISA tender volumes, with bioequivalence mandates filtering subscale competitors from oncology and anti-infective categories.
- Over-the-Counter Medications:Self-care categories bypass hospital procurement complexity, reaching consumers through pharmacy chains and emerging e-commerce platforms in tropical climate markets.
Chronic disease therapies command the established base. The steepest expansion runs through biologics.
End User:
Channel selection determines margin capture and regulatory burden, with direct-to-patient models disrupting traditional wholesale markups.
- Hospitals:Public hospital consortia in Brazil, Mexico, and Thailand consolidate oncology and immunology procurement into framework agreements with mandatory GMP certifications. These state purchasing agencies now represent the majority of national biologics consumption volume.
- E-commerce Platforms:Direct-to-patient delivery for chronic disease maintenance therapies collapses distributor margins, though cold-chain infrastructure gaps in tropical climates limit biologics penetration outside major urban networks.
- Pharmacies:Traditional retail channels retain control over regulated cold-chain products requiring temperature-controlled last-mile logistics.
- Clinics:Outpatient settings concentrate demand for injectable therapies and companion diagnostic bundling in Brazil's precision medicine tenders.
Hospitals anchor volume concentration. E-commerce platforms are climbing the fastest.
Application:
Therapeutic area focus shapes R&D partnership structures and local clinical trial requirements.
- Oncology:Biosimilar competition and patent cliffs reshape pricing architectures across public procurement systems. CDSCO bioequivalence mandates and NMPA local trial requirements extend market access timelines for multinational entrants.
- Cardiology:Digital therapeutics and mobile health applications displace traditional patient support programs where remote monitoring improves adherence in Southeast Asian public health systems.
- Immunology:Autoimmune and inflammatory conditions drive biologics demand through government tender expansion in Brazil, India, and China.
- Neurology:Chronic disease patient volumes accelerate demand for long-acting formulations and wearable device integration.
Oncology holds the revenue concentration. Cardiology is gaining share fastest through digital integration.
Technology:
Digital health adoption varies by therapeutic complexity and reimbursement pathway maturity.
- Digital Therapeutics:Software-based interventions compress traditional patient support programs, particularly in cardiology and neurology where adherence monitoring justifies reimbursement.
- Mobile Health Apps:Patient-facing platforms bypass traditional distribution for chronic disease maintenance, though regulatory clarity from CDSCO and ANVISA remains fragmented.
- Telemedicine:Remote consultation infrastructure expands access outside major urban hospital networks, bridging cold-chain infrastructure gaps for stable chronic therapies.
- Wearable Devices:Continuous monitoring hardware integrates with companion diagnostic bundling in precision medicine tenders.
Mobile health apps capture the broadest installed base. Digital therapeutics show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nhava Sheva Port corridor underwrites India's pharmaceutical export dominance, connecting API manufacturers in Gujarat and Maharashtra to African and Latin American tender markets. Cold-chain rail links from São Paulo to Brazil's northern hospital networks enable biologics distribution beyond coastal cities.
China
NMPA clinical trial mandates and local bioequivalence requirements extend market access timelines for multinational entrants. The Yangtze River Delta biopharma cluster in Shanghai concentrates mammalian cell culture expertise and aseptic fill-finish capacity for oncology biologics exports.
India
CDSCO bioequivalence standards for generic oncology products filter subscale competitors while elevating quality benchmarks. Hyderabad and Ahmedabad anchor integrated campus models that collapse API synthesis and finished dose formulation cost structures for export-led supply.
Brazil
ANVISA enforces PIC/S-aligned GMP certifications that filter subscale competitors from Sistema Único de Saúde tenders. São Paulo's hospital procurement consortia negotiate site-of-manufacture audits into multi-year framework agreements for oncology and immunology biologics.
Indonesia
Jaminan Kesehatan Nasional formulary expansion for biosimilars and chronic disease therapies creates first-mover advantages for qualified suppliers. Jakarta's public hospital networks drive volume concentration through price-volume mechanisms for diabetes and cardiovascular injectables.
Mexico
COFEPRIS regulatory alignment with FDA standards accelerates parallel filing pathways for multinational entrants. Mexico City Metro hospitals consolidate immunology procurement while northern border states leverage maquiladora infrastructure for cold-chain biologics distribution.
Global Pharmerging Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory capacity. The vendor base organizes around three tiers: integrated multinationals with WHO prequalification portfolios, mid-scale regional formulators with national tender access, and API-backward specialists competing on cost. Consolidation pressures concentrate among mid-tier players lacking dedicated regulatory affairs capacity for parallel multi-agency filings. Dominant competitive moves include local manufacturing partnerships with public hospital systems and companion diagnostic bundling for precision medicine tenders.
Within the integrated multinational tier, Pfizer Inc., F. Hoffmann-La Roche AG, and Sun Pharmaceutical Industries Ltd. occupy distinct positioning archetypes. Pfizer leverages manufacturing scale to anchor supply agreements with Latin American and Southeast Asian public health systems. Roche exemplifies technology leadership in companion diagnostics, positioning its portfolio for precision medicine tenders in Brazil and emerging Asian markets. Sun Pharmaceutical represents API-backward integration, sustaining cost advantages in generic oncology through captive active pharmaceutical ingredient supply.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Pfizer Inc. |
| AstraZeneca Plc |
| GlaxoSmithKline Plc |
| F. Hoffmann-La Roche AG |
| Novartis AG |
| Johnson & Johnson |
| Eli Lilly and Company |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with price-volume mechanisms lock in supply access for Brazilian and Indian hospital consortia while anchoring price visibility for oncology biologics manufacturers. These contracting structures concentrate procurement power in state purchasing agencies that negotiate site-of-manufacture audits into tender terms.
Pricing Analysis
Volume-discount tiering structures stratify across WHO-prequalified, national-authorization, and non-certified supply tiers in public procurement systems. Price differentiation hinges on bioequivalence certification grade under CDSCO or ANVISA standards and manufacturing scale measured in batch volumes. Cost compression in small-molecule generics intensifies as patent cliffs accelerate biosimilar competition. Government tenders in Southeast Asia exhibit highest price sensitivity, while precision medicine bundles in Brazil's Sistema Único de Saúde demonstrate lowest sensitivity due to companion diagnostic integration.
Supply Chain Analysis
Inbound logistics costs through Nhava Sheva Port and Shanghai Yangshan terminals fluctuate with container availability on Asia-Africa and Asia-Latin America trade lanes. Active pharmaceutical ingredient supply concentrates in China's Yangtze River Delta and India's Gujarat-Maharashtra corridor, drawing from fermentation-derived and synthetic chemistry inputs. Single-source vulnerability in mammalian cell culture media exposes formulators to geopolitical disruption risk. Distribution runs through cold-chain rail networks from São Paulo and direct manufacturer contracting with hospital consortia that displace traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pharmerging Market represents early-cycle expansion as national health insurance programs in Indonesia and Brazil extend formulary access for biologics and chronic disease therapies.
For Market Incumbents: Secure manufacturing scale advantages through integrated campus models in Hyderabad and Shanghai that collapse API synthesis and finished dose formulation costs. Anchor multi-year supply agreements with Brazil's Sistema Único de Saúde and Indonesia's Jaminan Kesehatan Nasional before biosimilar competition intensifies in oncology tenders. For New Entrants and Emerging Players: Differentiate on CDSCO bioequivalence certification speed for generic oncology products, targeting India's public hospital procurement where quality mandates filter subscale competitors. Penetrate Indonesia's national health insurance expansion for diabetes and cardiovascular injectables through direct-to-patient e-commerce partnerships that bypass traditional distributor networks. For Investors and Strategic Acquirers: Mid-scale regional formulators with dedicated regulatory affairs capacity for parallel WHO, FDA, and NMPA filings represent attractive acquisition targets. Watch for inflection signals in PIC/S mutual recognition application volumes from Indian and Chinese exporters seeking EU market access under EMA Annex 1 barrier isolation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Bioequivalence Certification | Accelerates market access for generic oncology suppliers in Indian government tenders. |
| Companion Diagnostic Bundling | Positions precision medicine portfolios for Brazil's Sistema Único de Saúde procurement. |
| Integrated Campus Manufacturing | Collapses cost structures by co-locating API synthesis and finished dose formulation in Hyderabad. |
| E-Commerce Pharmacy Partnership | Bypasses wholesale markups for chronic disease maintenance therapies in tropical climate markets. |
| PIC/S Mutual Recognition Application | Maintains EU market access for oncology injectables under EMA Annex 1 sterile product standards. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up modeling of treatment line volumes and top-down macroeconomic triangulation anchored value estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, end user channel, therapeutic application, and regional regulatory cluster. CAGRs derived from historical volume trajectories and penetration rate assumptions for biosimilars and digital therapeutics. Forecast inputs incorporated NMPA clinical trial timeline data and Jaminan Kesehatan Nasional formulary expansion schedules.
The analysis sits within stated boundaries; outcomes outside current WHO prequalification pathways, national bioequivalence standards, and health insurance coverage expansion rates would require recalibration. Forecasts reflect assumptions about regulatory alignment, cold-chain infrastructure development, and chronic disease prevalence trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Carbapenem Market