
 United Kingdom (UK) Diabetes Drugs Market | 2026-2036
United Kingdom (UK) Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom (UK) Diabetes Drugs Market Analytics
Subscription-based access models for biologic insulin and GLP-1 therapies is reconfiguring how hospitals and clinical commissioning groups manage budget volatility. Novo Nordisk A/S leverages its integrated manufacturing footprint in Denmark to secure stable supply chains into NHS procurement frameworks. Eli Lilly and Company anchors its competitive stance through sustained R&D investment in next-generation incretin mimetics. Sanofi competes aggressively on basal insulin analog pricing within the UK's statutory rebate system.
United Kingdom diabetes drugs comprise pharmaceutical agents engineered to modulate glucose homeostasis through insulin supplementation, incretin pathway enhancement, or renal glucose excretion inhibition, with formulations requiring cold-chain distribution at two to eight degrees Celsius and precise bioequivalence thresholds. These therapeutics serve to prevent microvascular complications, reduce cardiovascular mortality, and delay disease progression in diabetic populations. GLP-1 agonists now command the fastest-expanding share of prescribing budgets as cardiometabolic outcome data reshapes clinical guidelines. SGLT2 inhibitors occupy a mature growth trajectory with established heart failure indications extending utility beyond glycemic control. Insulin retains dominant volume share but faces margin compression from biosimilar entry and NHS England's national insulin tariff.
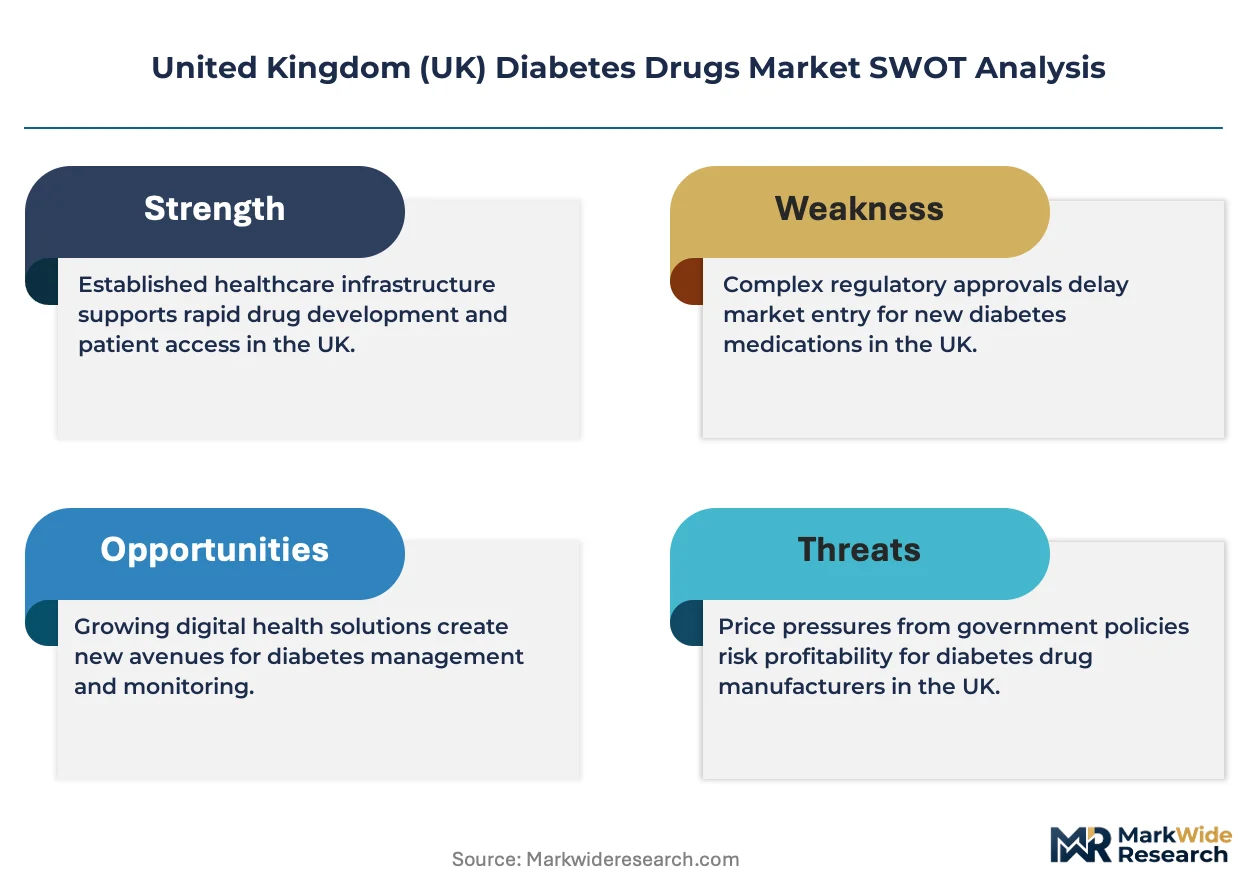
The Medicines and Healthcare products Regulatory Agency enforces post-Brexit pharmacovigilance requirements that extend approval timelines for novel diabetes agents, while NICE cost-effectiveness thresholds constrain premium pricing for new molecular entities entering the UK market. NHS England's national medicines optimisation programme directs prescribing toward clinically and cost-effective therapies, creating formulary gatekeeping that shapes manufacturer market access strategies. Stakeholders must monitor MHRA recognition of foreign regulatory approvals and evolving NICE methodology for multi-indication value assessment as these frameworks determine competitive positioning.
Market Dynamics
NHS England's national medicines optimisation programme is compressing prescribing budgets toward cost-effective therapies while MHRA post-Brexit regulatory autonomy extends approval timelines for novel diabetes agents entering UK distribution channels.
Growth Catalysts
- NICE Technology Appraisals:Expanded access criteria for GLP-1 agonists in Type 2 diabetes management are redirecting formulary investment across integrated care systems in England, Scotland, and Wales.
- Cardiometabolic Outcome Data:Published cardiovascular mortality reductions from SGLT2 inhibitor therapy are extending prescribing indications beyond glycemic control into heart failure populations.
- Cold-Chain Infrastructure Investment:Regional distribution hubs in the Midlands and Greater Manchester are reducing biologic insulin spoilage rates through temperature-controlled last-mile logistics.
Market Restraints
- Biosimilar Entry Compression:Multiple basal insulin analog biosimilars are eroding originator pricing power within NHS England's national insulin tariff framework.
- MHRA Pharmacovigilance Burden:Post-Brexit extended approval timelines for novel molecular entities are delaying market entry by 12-18 months relative to EMA-recognized approvals.
- Statutory Rebate Mechanics:The UK's pharmaceutical price regulation scheme mandates clawbacks that compress net margins on high-volume diabetes therapies regardless of clinical differentiation.
Strategic Opportunities
- Multi-Indication Value Assessment:NICE methodology evolution for therapies spanning diabetes, heart failure, and chronic kidney disease creates pathways for premium pricing justified by cross-disease economic modeling.
- Subscription-Based Procurement Models:Clinical commissioning groups in the West Midlands and Greater London are piloting budget-cap agreements for GLP-1 therapy access that transfer volume risk to manufacturers.
- Integrated Care System Consolidation:The 42 ICS structures operational across England are concentrating purchasing power and creating preferred supplier arrangements for diabetes drug portfolios.
Industry Challenges
- Specialist Endocrinology Workforce Constraints:NHS staffing gaps in diabetes specialist nursing and consultant endocrinology are limiting optimal therapy initiation and dose titration for complex patients.
- Legacy IT System Interoperability:Electronic health record fragmentation across primary care networks and hospital trusts is obstructing real-time prescribing decision support for glucose-lowering therapy selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom (UK) Diabetes Drugs Market |
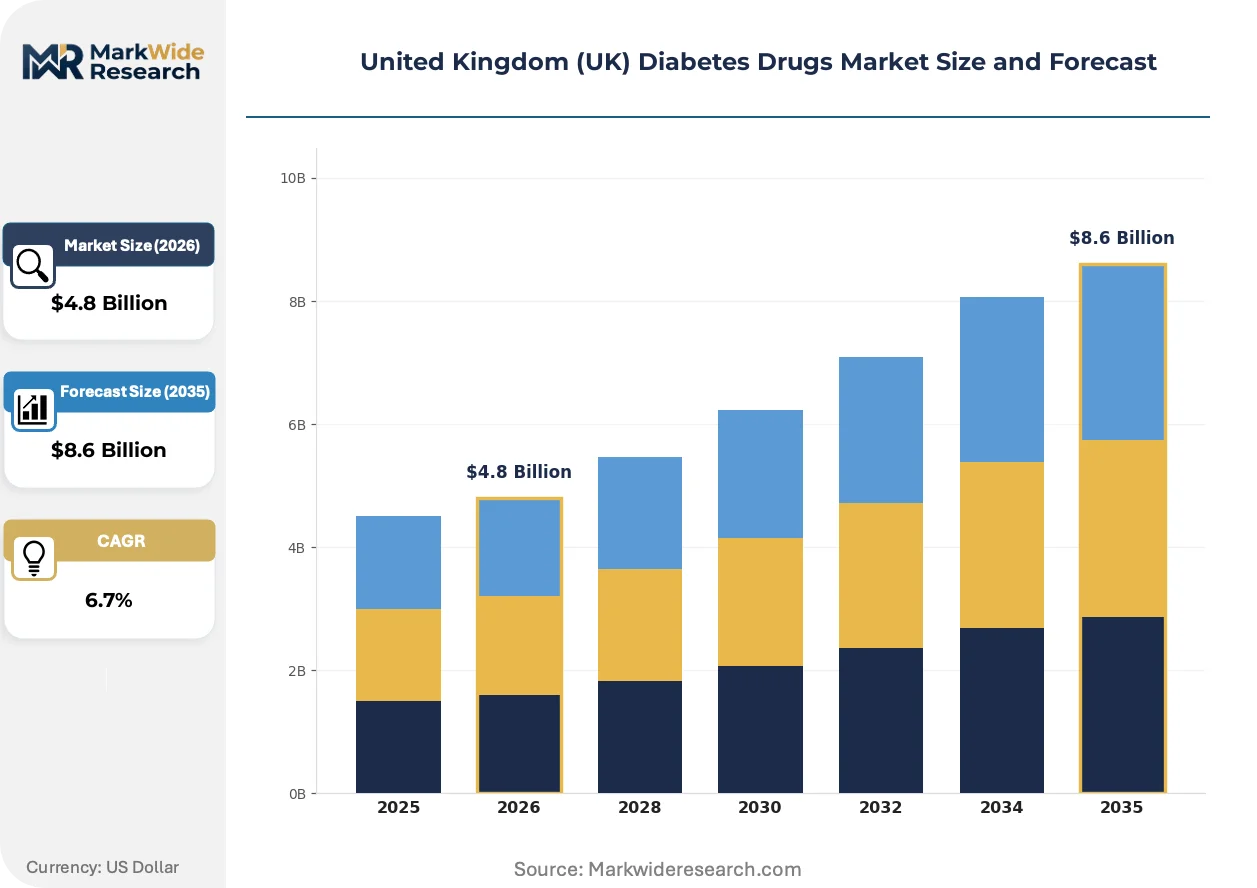
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Injectable, Oral, Inhalable, Patch End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, AstraZeneca, Boehringer Ingelheim, Takeda Pharmaceutical Company Limited, Merck & Co., Inc, Pfizer, Janssen Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom (UK) Diabetes Drugs Market Evolving Landscape
Digital therapeutics and connected delivery devices are reconfiguring how glucose-lowering therapies integrate into patient self-management workflows across NHS and private care pathways.
Continuous glucose monitoring systems paired with algorithm-driven insulin dosing are digitizing the traditional patient-physician titration relationship. Integrated care systems in Greater Manchester and the West Midlands are deploying these paired technologies at scale for Type 1 diabetes populations. The resulting data streams are compressing emergency hypoglycemia admissions while generating real-world evidence that manufacturers leverage in NICE submissions.
MHRA recognition of foreign regulatory approvals is streamlining market entry for diabetes devices and combination products previously authorized by FDA or EMA. The regulator's updated guidance on abridged assessment pathways reduces duplicate clinical trial requirements for established technologies. UK-based manufacturers with Denmark or Germany manufacturing footprints are exploiting this pathway to accelerate biosimilar insulin pen launcher availability.
Clinical commissioning groups are consolidating diabetes drug procurement through framework agreements that bundle glucose monitoring supplies with pharmaceutical supply. NHS England's national medicines optimisation programme is directing these consolidated purchasing decisions toward therapies with proven cardiovascular outcome benefits. The shift is most visible in the South East and East of England ICS regions where formulary restriction lists now exclude non-cardioprotective options for eligible patient populations.
United Kingdom (UK) Diabetes Drugs Market Segmentation
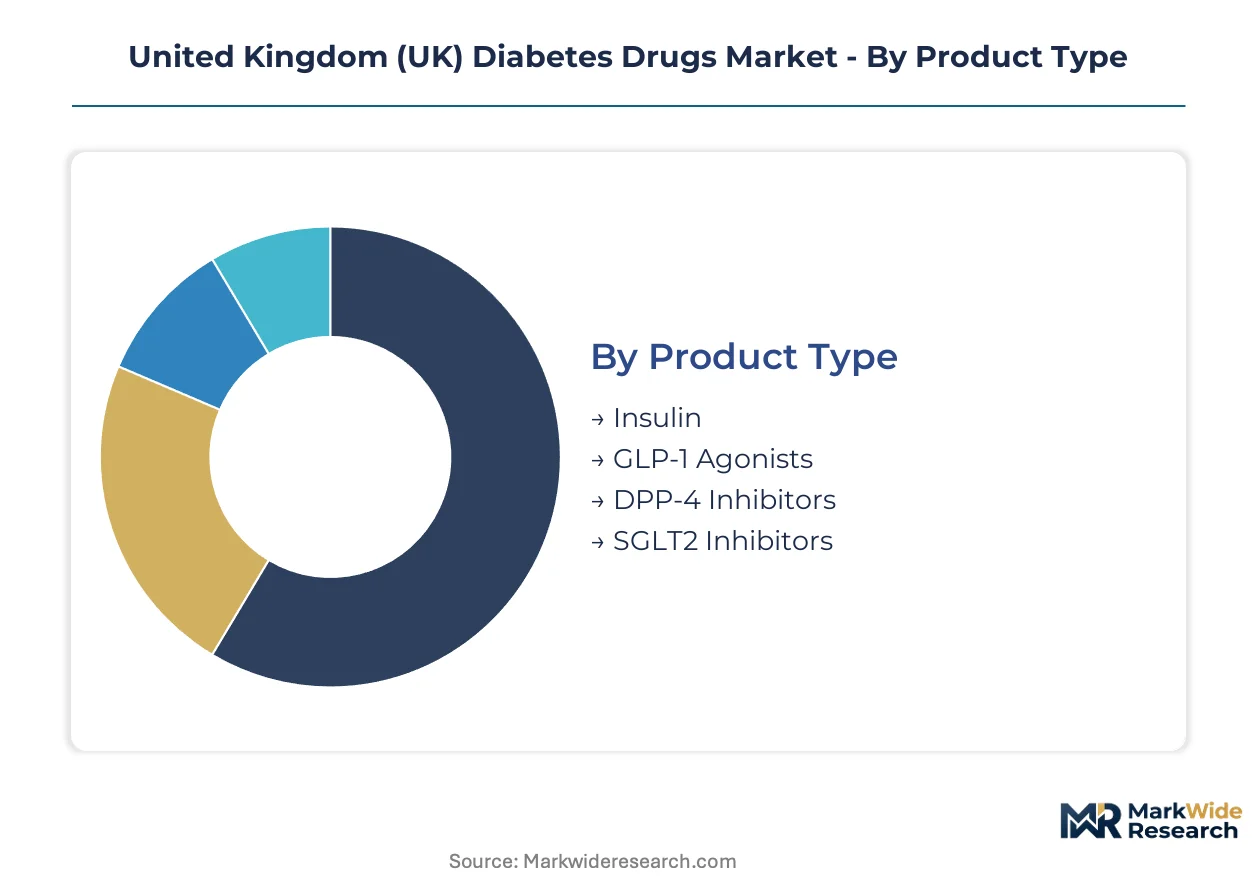
Segmentation in the UK diabetes drugs market reveals how NHS procurement frameworks, patient self-management trends, and clinical pathway redesigns allocate demand across therapeutic modalities. Understanding these divisions exposes where formulary investment concentrates and where manufacturer access strategies face the stiffest gatekeeping.
Product Type:
Cost tier stratification across the UK diabetes pharmacopeia shows NHS England directing premium reimbursement toward agents with proven cardiometabolic benefits while compressing margins on mature categories.
- Insulin:Basal and prandial analog formulations require cold-chain distribution at two to eight degrees Celsius through regional NHS distribution hubs. Volume demand concentrates in Type 1 diabetes populations and advanced Type 2 cases across integrated care systems in the West Midlands and Greater Manchester, where specialist nursing capacity constrains optimal dose titration.
- GLP-1 Agonists:Incretin mimetics administered via weekly subcutaneous injection deliver dual glucose-dependent insulin secretion and glucagon suppression. NICE technology appraisals expanded access criteria across England, Scotland, and Wales, redirecting formulary budgets toward liraglutide and semaglutide prescriptions in obese Type 2 cohorts.
- DPP-4 Inhibitors:Oral gliptin therapies provide weight-neutral glycemic control for patients failing metformin monotherapy.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers now carry heart failure and chronic kidney disease indications beyond diabetes, extending utility into renal and cardiology prescribing.
Insulin commands the established base. The steepest expansion runs through GLP-1 Agonists.
Delivery Mode:
Application context determines delivery technology selection, with patient self-management capabilities and clinical supervision intensity dictating whether injectable, oral, or emerging modalities gain formulary preference.
- Injectable:Pen devices and syringe systems dominate biologic insulin and GLP-1 agonist administration, requiring patient training programs delivered through diabetes specialist nursing networks. NHS England's national insulin tariff framework governs reimbursement across pen and vial presentations, with integrated care systems in Greater London piloting smart pen connectivity for dose tracking.
- Oral:Small-molecule therapies including metformin, DPP-4 inhibitors, and SGLT2 blockers offer patient convenience and pharmacy dispensing efficiency. Primary care networks across the South East and East of England drive volume through protocol-driven first-line prescribing for newly diagnosed Type 2 populations.
- Inhalable:Exubera's market withdrawal left this category dormant, with no active inhaled insulin products approved by MHRA for UK distribution.
- Patch:Transdermal delivery systems remain investigational for diabetes applications, with no commercial products securing NICE recommendation or NHS formulary inclusion.
Injectable modalities anchor therapeutic delivery. The steepest expansion runs through Oral formulations as fixed-dose combinations simplify adherence.
End User:
Customer type segmentation exposes how care setting determines prescribing autonomy, reimbursement pathway, and manufacturer account management strategy across NHS and private channels.
- Hospitals:Acute trusts manage inpatient glycemic control and initiate complex insulin regimens for surgical and critical care populations. Teaching hospitals in London, Manchester, and Birmingham concentrate specialist endocrinology capacity and participate in early access schemes for novel molecular entities.
- Clinics:Community diabetes services and specialist outpatient centers conduct dose titration and complication screening. Integrated care system consolidation across England's 42 structures is concentrating purchasing power into framework agreements that bundle clinic-administered therapies with glucose monitoring supplies.
- Homecare:Patient self-administration of injectable therapies dominates long-term diabetes management, supported by home delivery services from pharmacy contractors.
- Pharmacies:Community pharmacies dispense oral therapies and provide patient counseling, with NHS England's medicines optimisation programme directing toward cost-effective generic and biosimilar substitution where clinically appropriate.
Homecare settings capture the majority of chronic therapy volume. The steepest expansion runs through Clinics as integrated care systems consolidate specialist services.
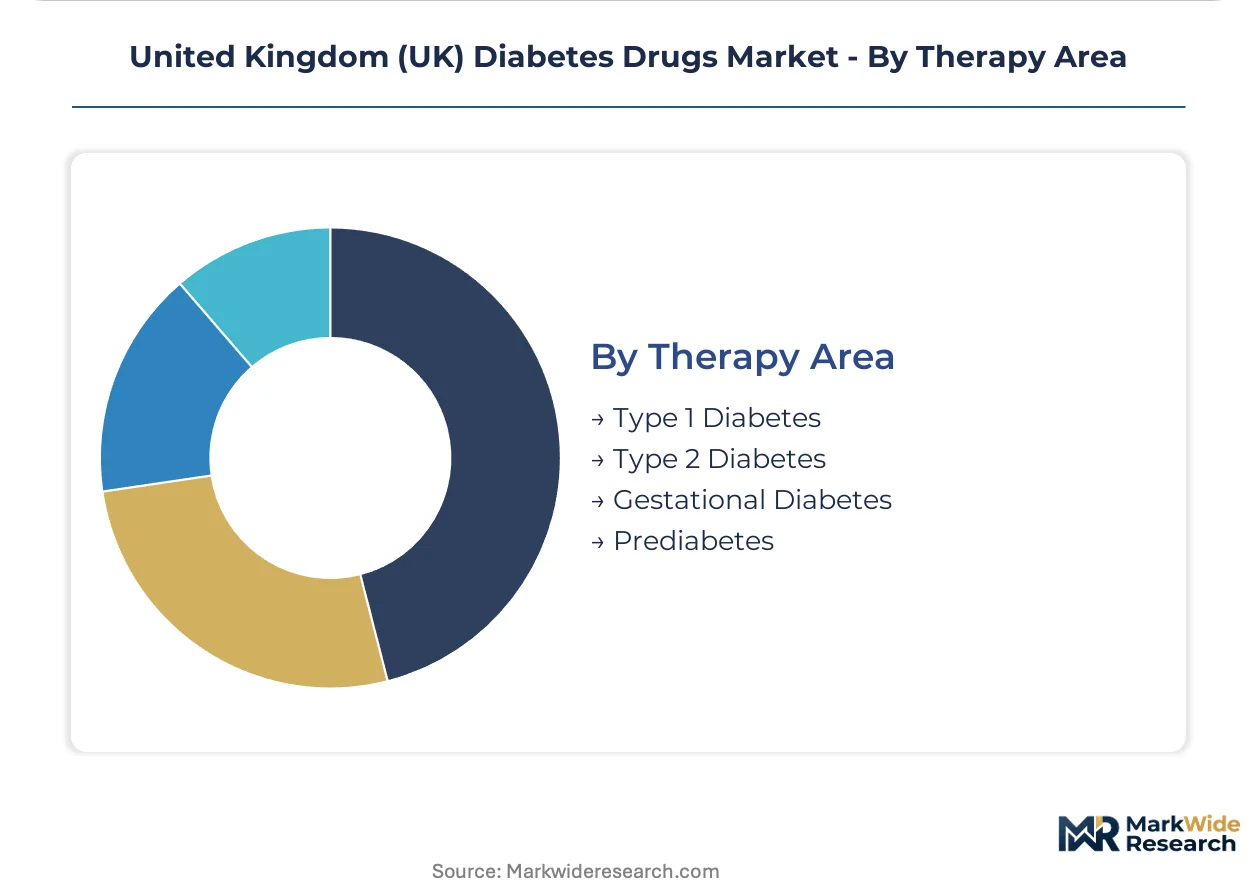
Therapy Area:
Volume distribution across diabetes disease states reflects epidemiological prevalence, clinical guideline evolution, and the expanding preventive treatment of at-risk populations.
- Type 1 Diabetes:Autoimmune insulin deficiency requiring lifelong exogenous replacement therapy. Continuous glucose monitoring paired with algorithm-driven insulin dosing is digitizing care pathways across Greater Manchester and West Midlands integrated care systems, compressing emergency hypoglycemia admissions.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction affecting the vast majority of UK diabetic patients. NICE guideline updates prioritize GLP-1 agonists and SGLT2 inhibitors with cardiovascular outcome benefits, excluding non-cardioprotective options from formularies in eligible populations.
- Gestational Diabetes:Glucose intolerance during pregnancy managed through dietary intervention and insulin when glycemic targets are not met, with oral agents generally avoided due to placental transfer concerns.
- Prediabetes:Impaired glucose tolerance and elevated HbA1c below diabetes thresholds, with pharmacological intervention rarely funded through NHS commissioning and lifestyle modification preferred.
Type 2 Diabetes commands the established base. The steepest expansion runs through Prediabetes identification and preventive intervention as NHS Health Check programmes expand screening coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHS England's integrated care systems are redirecting prescribing budgets toward cardiometabolic-protective therapies while devolved administrations in Scotland, Wales, and Northern Ireland maintain distinct formulary autonomy under their respective health ministries.
England
The 42 integrated care systems concentrate purchasing power for GLP-1 agonists and SGLT2 inhibitors with proven cardiovascular outcomes. NICE technology appraisals mandate cost-effectiveness thresholds that exclude non-cardioprotective options from formularies in eligible populations. The Midlands and Greater Manchester distribution hubs anchor cold-chain logistics for biologic insulin supply into hospital trusts and primary care networks.
Scotland
Scottish Medicines Consortium assessments run parallel to NICE appraisals with accelerated access schemes for medicines addressing unmet need in Type 1 diabetes populations. NHS Scotland's national diabetes improvement plan directs prescribing toward continuous glucose monitoring paired with algorithm-driven insulin dosing. Edinburgh and Glasgow teaching hospitals concentrate specialist endocrinology capacity and early access programmes for novel molecular entities.
Wales
All Wales Medicines Strategy Group formulary decisions emphasize value-based procurement for diabetes therapies across seven health boards. Welsh Government investment in community diabetes specialist nursing addresses workforce gaps constraining optimal GLP-1 agonist initiation. Cardiff and Swansea anchor regional distribution networks for oral glucose-lowering therapies into primary care clusters.
Northern Ireland
The Department of Health's medicines optimisation framework aligns prescribing guidance with NICE appraisals while maintaining distinct procurement arrangements through the Business Services Organisation. Belfast Health and Social Care Trust manages complex insulin regimens for Type 1 populations across Northern Ireland's five health trusts. Regional distribution infrastructure connects to Republic of Ireland supply chains for certain biosimilar insulin products.
London and Southeast England
Clinical commissioning groups in Greater London pilot subscription-based procurement models that transfer volume risk to manufacturers for GLP-1 therapy access. Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trusts anchor specialist referral pathways for gestational diabetes and complex Type 2 cases. The Southeast ICS regions lead formulary restriction lists excluding non-cardioprotective options from prescribing budgets.
United Kingdom (UK) Diabetes Drugs Market Competitive Landscape
On the supply side, the industry is consolidated around a handful of multinational pharmaceutical developers with integrated manufacturing footprints and established NHS procurement relationships. Danish and US-based innovators anchor the premium tier through patented incretin mimetics, while European and American incumbents compete on basal insulin analog pricing within statutory rebate frameworks. Strategic archetypes include vertically integrated biologic manufacturers, diversified pharma conglomerates with diabetes portfolios, and biosimilar specialists targeting margin-compressed insulin categories. Dominant competitive moves encompass subscription-based procurement partnerships with integrated care systems and multi-indication value assessments spanning diabetes, heart failure, and chronic kidney disease.
Among Denmark-based biologic specialists, Novo Nordisk A/S occupies a position exemplifying vertical integration from active pharmaceutical ingredient production through pen-device manufacturing. US-based innovators Eli Lilly and Company and Sanofi represent contrasting archetypes within the incretin and insulin segments respectively, with the former anchoring sustained R&D investment in next-generation GLP-1 pathways and the latter competing aggressively on pricing within NHS England's national insulin tariff. These three entities collectively represent the supply-side concentration shaping formulary access and procurement negotiation dynamics across UK integrated care systems.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Boehringer Ingelheim |
| Takeda Pharmaceutical Company Limited |
| Merck & Co., Inc |
| Pfizer |
| Janssen Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Cold-chain capacity utilization across Denmark and Germany determines how biologic insulin manufacturers calibrate UK pricing posture and inventory commitments. NHS England's national insulin tariff compresses margins when utilization runs high, while undercapacity in regional distribution hubs forces premium positioning for temperature-assured delivery.
Pricing Analysis
NICE cost-effectiveness thresholds create the primary spread between premium GLP-1 agonists and economy-tier biosimilar insulins. Subscription-based procurement models for incretin mimetics operate alongside per-unit transactional pricing for mature analog formulations. Cost compression in basal insulin runs through statutory rebate mechanics that claw back revenue regardless of clinical differentiation. Primary care networks demonstrate highest price sensitivity, while teaching hospitals with early access programs tolerate premium positioning for novel molecular entities.
Supply Chain Analysis
Danish and German contract manufacturers hold concentrated capacity for active pharmaceutical ingredient synthesis and pen-device assembly. UK distribution draws from these northern European hubs while sourcing oral small-molecule APIs from India and Ireland. Single-source vulnerability concentrates in cold-chain logistics providers serving Midlands and Greater Manchester regional hubs. Distribution runs through NHS distribution hubs into integrated care system formularies, with last-mile pharmacy contracting completing patient access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar insulin substitution threatens originator pricing power, forcing incumbents to defend formulary position through outcome-based contracting and integrated service bundling.
For Market Incumbents: Insulate premium GLP-1 franchises by embedding continuous glucose monitoring data streams into NICE submission packages. Deepen backward integration into pen-device manufacturing to offset biosimilar margin compression. Secure preferred supplier status within integrated care system framework agreements before formulary consolidation completes. For New Entrants and Emerging Players: Build out cardiometabolic outcome datasets for SGLT2 inhibitor extensions into chronic kidney disease populations. Target Scottish Medicines Consortium accelerated access schemes where unmet need in Type 1 diabetes creates formulary openness. Pursue hospital trust partnerships for inpatient glycemic control protocols as a gateway to chronic therapy adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated biologic specialists with captive manufacturing and device ecosystems. Five-to-ten year viability favors entities with multi-indication pipelines spanning diabetes, heart failure, and renal disease. Monitor MHRA recognition pathway expansion for foreign regulatory approvals as an inflection signal for accelerated market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Indication Value Assessment | NICE methodology evolution rewards cross-disease economic modeling with premium formulary positioning. |
| Integrated Care System Partnership | Preferred supplier arrangements with England's 42 ICS structures concentrate purchasing power and lock out competitors. |
| Cold-Chain Infrastructure Investment | Regional hub expansion in Midlands and Greater Manchester reduces spoilage rates and secures supply continuity. |
| Digital Therapeutic Companion Development | Algorithm-driven insulin dosing paired with continuous glucose monitoring generates real-world evidence for submissions. |
| Biosimilar Manufacturing Scale-Up | Originator pricing power erosion within NHS England's national insulin tariff creates volume opportunity for lower-cost entrants. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with formulary directors, diabetes specialist nursing leads, MHRA regulatory affairs officers, and integrated care system procurement managers; and secondary validation through NICE technology appraisal documentation, MHRA approval databases, NHS England medicines optimisation programme reports, and integrated care system framework agreement disclosures. Bottom-up prescribing volume modeling triangulated against top-down NHS expenditure data.
Forecast inputs incorporated therapy area segmentation by diabetes type, product class stratification across insulin, GLP-1 agonist, DPP-4 inhibitor, and SGLT2 inhibitor categories, and delivery mode differentiation between injectable and oral formulations across the projection horizon. CAGRs derived from epidemiological prevalence trajectories, guideline evolution assumptions, and formulary budget allocation shifts. Pricing dynamics reflected statutory rebate mechanics and NICE cost-effectiveness threshold constraints.
Stress conditions across MHRA approval timeline variability, biosimilar entry velocity, and integrated care system consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cardiometabolic outcome data publication schedules and workforce capacity expansion in diabetes specialist nursing. Quarterly review of NICE technology appraisal queue depth and Scottish Medicines Consortium accelerated access decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Valganciclovir Market