
 Middle-East and Africa Diabetes Drugs Market | 2026-2036
Middle-East and Africa Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Diabetes Drugs Market Foresight
The EU Green Deal's extraterritorial pharmaceutical sustainability standards are decoupling supply chain certification from pure price competition across Middle-East and Africa diabetes drug imports. Novo Nordisk leverages its vertically integrated insulin production to maintain cold-chain integrity across Gulf distribution corridors. Sanofi anchors its regional position through established manufacturing partnerships in Morocco and Egypt. Eli Lilly and Company differentiates via concentrated R&D investment in GLP-1 receptor agonist formulations suited to heat-stressed storage environments.
Diabetes drugs encompass pharmacological agents engineered to modulate blood glucose homeostasis through exogenous insulin replacement, incretin pathway enhancement, or renal glucose reabsorption inhibition, with formulations requiring precise bioactivity stability across 2-8°C storage parameters. Insulin products retain dominant volume share due to established reimbursement pathways and clinician familiarity, while SGLP2 inhibitors represent the fastest-expanding category driven by cardiovascular outcome benefits and once-daily oral dosing convenience. Subcutaneous administration maintains structural precedence in hospital and home care settings, though oral DPP-4 inhibitors capture expanding share in clinic-based type 2 diabetes management across price-sensitive African markets.
Saudi Arabia's SFDA enforces bioequivalence protocols that elevate manufacturing quality barriers for biosimilar entrants, while South Africa's SAHPRA governs registration timelines that directly shape product availability in the continent's largest public procurement system. The UAE's MOHAP accelerates approval pathways for therapies addressing documented national diabetes prevalence, creating regulatory asymmetry across Gulf Cooperation Council jurisdictions. Stakeholders must monitor divergence between Gulf state harmonization initiatives and sub-Saharan national regulatory autonomy to optimize portfolio allocation and partnership structures.
Market Dynamics
The EU Green Deal's extraterritorial pharmaceutical sustainability standards are forcing supply chain reconfiguration across Middle-East and Africa diabetes drug imports, decoupling certification requirements from pure price competition and elevating cold-chain infrastructure investment as a competitive barrier.
Growth Catalysts
- SFDA Bioequivalence Mandates:Saudi Arabia's tightened protocols for biosimilar insulins are filtering substandard manufacturers and concentrating procurement among qualified suppliers with validated stability data.
- Cardiovascular Outcome Integration:SGLT2 inhibitors are displacing older oral agents in Gulf hospital formularies as cardiometabolic bundled protocols gain clinical traction.
- Private Clinic Networks:Nigeria's emerging specialist diabetes centers are creating direct-to-patient channels that bypass fragmented wholesale distribution.
Market Restraints
- API Import Concentration:Active pharmaceutical ingredient sourcing for regional insulin fill-finish operations depends heavily on Indian and Chinese bulk manufacturers, exposing margins to shipping cost volatility.
- Cold-Chain Infrastructure Gaps:Last-mile temperature control failures in sub-Saharan distribution corridors degrade bioactivity of heat-sensitive biologics before patient administration.
- Reimbursement Misalignment:South Africa's public sector tender system prioritizes lowest-unit-cost oral generics, delaying patient access to newer therapeutic classes with superior outcome profiles.
Strategic Opportunities
- Heat-Stable Formulation Development:GLP-1 receptor agonist variants engineered for ambient storage tolerance address the Gulf's extreme climate distribution challenges without refrigerated transport.
- MOHAP Accelerated Pathways:The UAE's streamlined approval for therapies targeting documented national diabetes prevalence creates first-mover positioning for novel mechanism sponsors.
- Public-Private Partnership Models:Kenya's county health devolution is opening integrated diabetes management contracts combining diagnostics, drugs, and patient monitoring.
Industry Challenges
- Multinational Quality System Harmonization:Manufacturers must maintain simultaneous compliance with Gulf Cooperation Council technical harmonization initiatives and sub-Saharan national regulatory autonomy, duplicating audit and documentation burdens.
- Specialized Biologics Handling Workforce:Pharmacist and nursing cadres across the region lack standardized training in injectable therapy administration and cold-chain stewardship, limiting product uptake in community settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Diabetes Drugs Market |
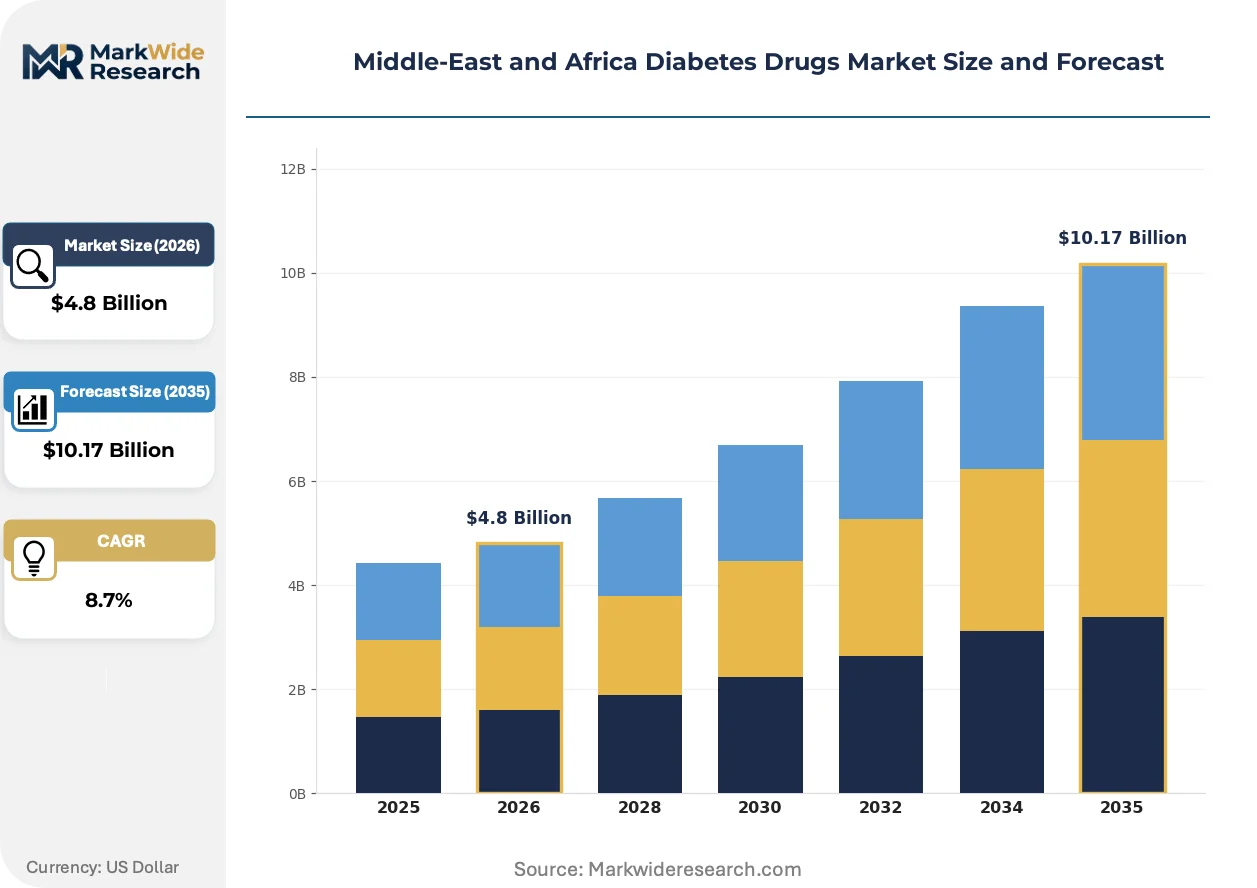
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Home Care, Laboratories Administration Route: Subcutaneous, Oral, Intravenous, Inhalation Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Merck & Co., AstraZeneca, Boehringer Ingelheim, Pfizer, Takeda, Hikma Pharmaceuticals, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Diabetes Drugs Market Shifts & Advancements
Formulation science and distribution technology are converging to address the fundamental tension between biologic potency requirements and ambient climate stress across Middle-East and Africa markets.
Continuous glucose monitoring integration with insulin delivery systems is unifying data capture and dosing decisions into closed-loop architectures. Private endocrinology clinics in Dubai and Riyadh are piloting these connected platforms for affluent patient segments. The technology is compressing the gap between diagnostic insight and therapeutic response, shifting competitive advantage toward ecosystem providers with software capabilities.
Saudi Arabia's SFDA has implemented bioequivalence study requirements for biosimilar insulins that exceed prior Gulf standards, elevating manufacturing quality barriers for market entry. Regional fill-finish operations must now demonstrate validated cold-chain integrity from active pharmaceutical ingredient receipt through patient administration. Sub-Saharan manufacturers without access to European reference product bridging studies face extended registration timelines.
Hospital procurement committees across the Gulf are consolidating insulin purchasing into multi-year framework agreements with incumbent suppliers, reducing tender frequency and locking out new entrants. South Africa's public sector tender system maintains annual competitive bidding, preserving price pressure but fragmenting supply security. The divergence in purchasing cadence is most visible in injectable therapy categories where switching costs and clinician familiarity create sticky relationships.
Middle-East and Africa Diabetes Drugs Market Segmentation
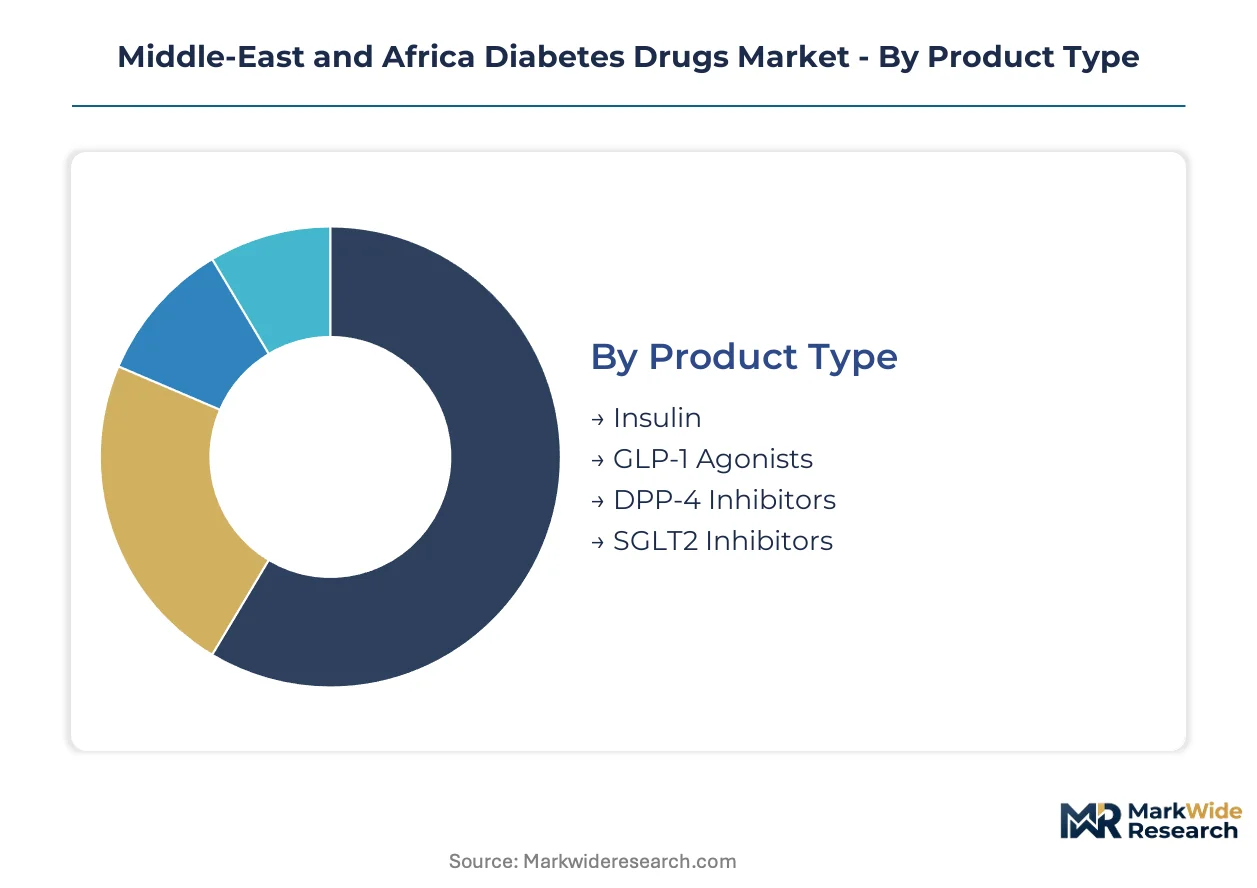
Segmentation in the Middle-East and Africa diabetes drugs market reveals distinct procurement behaviors across Gulf hospital systems, sub-Saharan public tenders, and emerging private clinic networks. Each category exposes different technical requirements, reimbursement constraints, and distribution infrastructure needs that shape competitive positioning.
Product Type:
Purchasing decisions diverge sharply between Gulf states with established biologic reimbursement pathways and sub-Saharan markets where cost containment dominates formulary design.
- Insulin:Human and analog insulin formulations remain the clinical backbone across the region, with Saudi Arabia's SFDA mandating bioequivalence documentation that filters substandard biosimilar entrants. Hospital procurement committees in Riyadh and Dubai favor multi-year framework agreements with incumbent suppliers, creating sticky relationships that resist price-driven switching.
- SGLT2 Inhibitors:Oral sodium-glucose cotransporter-2 inhibitors are displacing older oral agents in Gulf hospital formularies as cardiometabolic bundled protocols gain traction among endocrinology departments. The UAE's MOHAP accelerates approval pathways for therapies addressing documented national diabetes prevalence, creating regulatory asymmetry favoring novel mechanism sponsors.
- GLP-1 Agonists:Glucagon-like peptide-1 receptor agonists require cold-chain integrity that strains last-mile distribution in sub-Saharan corridors.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors capture expanding share in clinic-based type 2 diabetes management across price-sensitive African markets.
Insulin leads volumes today; SGLT2 inhibitors are gaining share fastest.
End User:
Site-of-care economics determine formulary access, with hospital procurement wielding concentrated purchasing power against fragmented retail channels.
- Hospitals:Gulf state hospital systems command volume discounts through consolidated tender processes, with procurement committees consolidating insulin purchasing into multi-year agreements that reduce supplier churn. South Africa's public sector tender system maintains annual competitive bidding, preserving price pressure but fragmenting supply security across provinces.
- Clinics:Nigeria's emerging specialist diabetes centers are creating direct-to-patient channels that bypass fragmented wholesale distribution, capturing affluent urban patients seeking continuous glucose monitoring integration.
- Home Care:Subcutaneous self-administration depends on patient education programs that remain underdeveloped outside major metropolitan areas.
- Laboratories:Diagnostic facilities support therapeutic monitoring but lack integrated care coordination with prescribing clinicians.
Hospitals dominate procurement value; clinics are expanding most quickly as private networks proliferate.
Administration Route:
Delivery mechanism selection reflects the tension between biologic potency requirements and ambient climate stress across regional distribution corridors.
- Subcutaneous:Injectable administration maintains structural precedence in hospital and home care settings, though pharmacist and nursing cadres across the region lack standardized training in cold-chain stewardship. Temperature excursions during last-mile delivery in sub-Saharan corridors degrade bioactivity before patient administration.
- Oral:Once-daily oral dosing convenience drives DPP-4 and SGLT2 inhibitor uptake in clinic-based type 2 management, eliminating refrigeration dependencies that constrain biologic penetration.
- Intravenous:Hospital-confined delivery limits application to acute metabolic complications.
- Inhalation:Pulmonary insulin delivery remains marginal due to limited reimbursement and clinician familiarity gaps.
Subcutaneous routes anchor current volumes; oral formulations are climbing the fastest as heat-stable alternatives gain preference.
Distribution Channel:
Channel structure maps directly to regulatory sophistication and cold-chain infrastructure maturity across national boundaries.
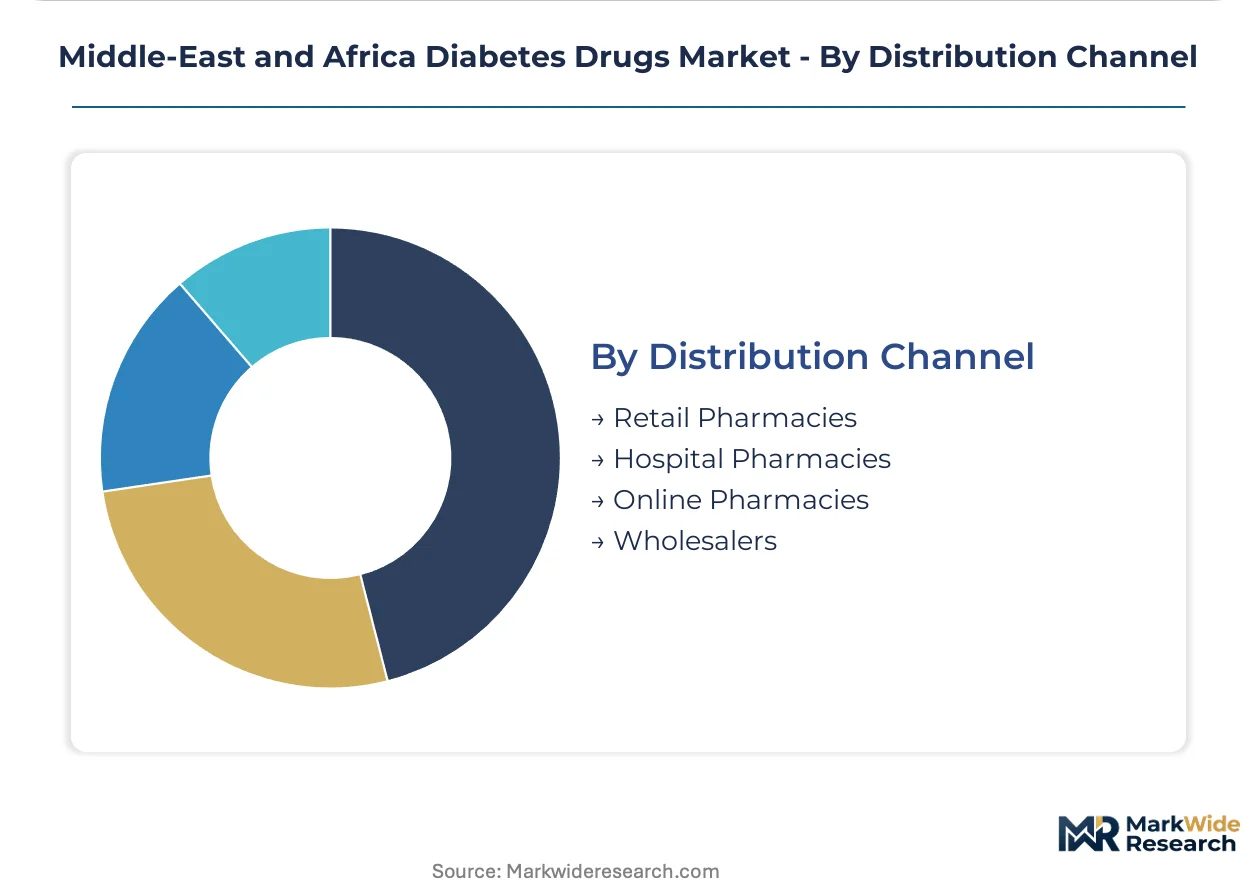
- Hospital Pharmacies:Captive dispensing within Gulf medical cities ensures cold-chain integrity from receipt through patient handoff, with vertically integrated supply chains limiting parallel trade exposure.
- Retail Pharmacies:Community pharmacy networks in South Africa and Nigeria face temperature control failures that compromise biologic stability, driving demand toward oral generics with ambient storage tolerance.
- Online Pharmacies:Digital dispensing platforms are emerging in UAE and Saudi urban centers, though last-mile cold-chain verification remains inconsistent.
- Wholesalers:Fragmented wholesale distribution in sub-Saharan Africa creates margin pressure and counterfeit infiltration risks.
Hospital pharmacies command premium biologic volumes; retail channels are expanding fastest as generic oral penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes drug distribution in the Middle-East and Africa originated from colonial-era pharmaceutical import networks centered in Cairo and Casablanca, later shifting toward Gulf-based procurement hubs as oil revenues expanded hospital infrastructure.
Saudi Arabia
Hospital procurement committees in Riyadh and Jeddah consolidate insulin purchasing into multi-year framework agreements, reducing supplier churn. SFDA bioequivalence mandates for biosimilar insulins now exceed prior Gulf standards, filtering substandard manufacturers. The King Faisal Specialist Hospital anchors regional clinical trial activity for heat-stable formulations.
United Arab Emirates
Dubai's private endocrinology clinics pilot continuous glucose monitoring integration for affluent patient segments. MOHAP accelerates approval pathways for therapies addressing documented national diabetes prevalence, creating regulatory asymmetry favoring novel mechanism sponsors. Abu Dhabi's medical cities deploy vertically integrated cold-chain corridors from port to patient.
South Africa
SAHPRA governs registration timelines that directly shape product availability in the continent's largest public procurement system. The public sector tender system maintains annual competitive bidding for oral generics, delaying access to newer therapeutic classes. Gauteng province's hospital networks concentrate specialist diabetes care capacity.
Nigeria
Emerging specialist diabetes centers in Lagos and Abuja create direct-to-patient channels that bypass fragmented wholesale distribution. Private clinic networks capture affluent urban patients seeking continuous glucose monitoring integration. The national pharmaceutical regulator struggles with counterfeit infiltration risks in retail pharmacy channels.
Egypt
Established manufacturing partnerships in Cairo and Alexandria anchor regional fill-finish operations for multinational sponsors. The domestic market depends heavily on Indian and Chinese active pharmaceutical ingredient sourcing, exposing margins to shipping cost volatility. Public hospital formularies prioritize lowest-unit-cost human insulin over analog formulations.
Middle-East and Africa Diabetes Drugs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-chain infrastructure investment and bioequivalence certification depth. The supplier base concentrates among vertically integrated insulin producers with validated stability data and regional fill-finish partnerships. Three archetypes dominate: multinational biologic originators with Gulf hospital framework agreements, regional generic manufacturers with SAHPRA registration expertise, and emerging biosimilar sponsors navigating SFDA bridging study requirements. Dominant competitive moves include strategic partnerships with local fill-finish operators and portfolio diversification into heat-stable GLP-1 formulations.
Among the multinational originators, Novo Nordisk and Sanofi exemplify the premium-tier archetype through established manufacturing partnerships and vertically integrated production systems. Eli Lilly and Company occupies a position emphasizing concentrated R&D investment in formulation science. Hikma Pharmaceuticals represents the regional generic specialist tier with SAHPRA registration capabilities and sub-Saharan distribution reach.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Merck & Co. |
| AstraZeneca |
| Boehringer Ingelheim |
| Pfizer |
| Takeda |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient costs from Indian and Chinese bulk manufacturers cascade through three distinct pricing tiers before reaching end-users across Middle-East and Africa markets. Gulf hospital procurement committees leverage multi-year framework agreements to compress margins at the premium tier, while sub-Saharan tender systems amplify price sensitivity for human insulin and oral generics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs diabetes drug procurement across the region. Premium-tier analog insulins and GLP-1 agonists command higher price points through SFDA bioequivalence certification and validated cold-chain documentation, while standard-tier biosimilars compete on manufacturing quality credentials. Economy-tier human insulin and oral DPP-4 inhibitors face intense price compression in South Africa's annual tender system and Nigeria's fragmented retail channels. Price differentiation stems from certification grade and volume scale, with Gulf hospital systems extracting steep discounts through consolidated purchasing power. Pricing pressure intensifies as Egyptian and Moroccan fill-finish operations absorb shipping cost volatility from API sourcing.
Supply Chain Analysis
Dual-sourcing requirements for cold-chain biologics mandate that Gulf hospital systems qualify at least two insulin suppliers per therapeutic class, preventing single-source dependency. Geographic supply concentration centers on India and China for active pharmaceutical ingredients, with regional fill-finish operations in Egypt, Morocco, and Saudi Arabia completing final formulation. Raw material dependencies include recombinant DNA cell lines, chromatography resins, and pharmaceutical-grade excipients. Supply chain risk manifests as temperature excursion vulnerability during last-mile distribution through sub-Saharan corridors lacking verified cold-chain infrastructure. Distribution runs through hospital pharmacy captives in Gulf medical cities, retail pharmacy networks in South Africa and Nigeria, and emerging direct-to-patient channels in private Lagos and Abuja clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in heat-stable formulation development and Gulf hospital framework agreement renewal cycles, as premium-tier products displace commodity insulins in cardiometabolic bundled protocols.
For Market Incumbents: Deepen backward integration into API sourcing to buffer margin compression from Indian and Chinese shipping cost volatility. Secure multi-year framework agreement renewals with Riyadh and Dubai hospital procurement committees before SFDA bioequivalence mandates tighten further. Invest in heat-stable GLP-1 formulation R&D to capture ambient storage tolerance premiums across Gulf distribution corridors. For New Entrants and Emerging Players: MOHAP accelerated approval pathways in the UAE open a window for novel mechanism sponsors targeting documented national diabetes prevalence with SGLT2 inhibitor or GLP-1 agonist portfolios. Kenya's county health devolution presents white-space integrated diabetes management contracts combining diagnostics, drugs, and patient monitoring. Prioritize SAHPRA registration expertise to penetrate South Africa's public sector tender system with cost-competitive biosimilar offerings. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-Saharan distribution networks lack cold-chain verification capabilities and Gulf hospital systems demand vertically integrated supply security. Long-term viability favors regional fill-finish operators with validated stability data and established manufacturing partnerships in Egypt or Morocco. Watch for SFDA bridging study requirement expansions as the inflection indicator for biosimilar sponsor attrition and incumbent market share consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stable Formulation Development | GLP-1 agonist variants engineered for ambient storage tolerance address Gulf climate distribution challenges without refrigerated transport. |
| SFDA Bioequivalence Certification | Validated stability data and bridging studies filter substandard biosimilar entrants and concentrate procurement among qualified suppliers. |
| County Health Devolution Partnerships | Kenya's integrated diabetes management contracts combine diagnostics, drugs, and monitoring into single-vendor arrangements. |
| Multi-Year Framework Agreement Renewal | Gulf hospital procurement committees lock in incumbent suppliers and reduce competitive tender frequency for insulin purchasing. |
| Direct-to-Patient Channel Development | Nigeria's specialist diabetes centers in Lagos and Abuja bypass fragmented wholesale distribution for affluent urban segments. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative insights in operational reality across Middle-East and Africa markets. Secondary validation drew from SFDA guidance documents, SAHPRA registration databases, MOHAP accelerated pathway announcements, ClinicalTrials.gov entries for regional diabetes trials, and Gulf hospital procurement tender records. Bottom-up patient population modeling and top-down pharmaceutical trade flow analysis enabled cross-verification of volume estimates.
Bottom-up segmentation modeling tracked insulin, SGLT2 inhibitors, GLP-1 agonists, and DPP-4 inhibitors across administration route, end-user site of care, and distribution channel dimensions over the projection horizon. Treatment line positioning, regional regulatory cluster alignment, and cold-chain infrastructure maturity informed patient access assumptions. CAGRs emerged from iterative reconciliation of historical prescription volume trends, reimbursement pathway evolution, and clinician adoption curve dynamics for novel therapeutic classes.
Revisions become necessary when SFDA bioequivalence requirements expand beyond current biosimilar insulin scope, when MOHAP accelerates novel mechanism approvals faster than modeled, or when sub-Saharan cold-chain infrastructure investments materially outpace baseline assumptions. Deviation in Gulf hospital procurement consolidation timelines or API shipping cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Propofol Market