
 Global Primary Biliary Cirrhosis Drug Market | 2026-2036
Global Primary Biliary Cirrhosis Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Biliary Cirrhosis Drug Market Foresight
Hepatology centers and specialty clinics are unwinding historical reliance on general gastroenterology practices for PBC diagnosis and treatment. Intercept Pharmaceuticals anchors the obeticholic acid segment through sustained investment in hepatology specialist education and payer engagement. Gilead Sciences competes in adjacent liver disease portfolios, leveraging its commercial infrastructure across transplant and fibrosis centers. AbbVie extends its immunology footprint into autoimmune hepatology, positioning its pipeline for overlap populations.
Primary biliary cholangitis drugs comprise pharmaceutical agents targeting autoimmune destruction of intrahepatic bile ducts, with formulations ranging from bile acid modulators at 13-15 mg/kg daily dosing to selective farnesoid X receptor agonists titrated from 5 mg to 10 mg based on tolerability. These therapies slow histological progression and manage pruritus and fatigue in patients with alkaline phosphatase elevation. Ursodeoxycholic acid dominates volume due to decades of clinical validation and generic availability, while obeticholic acid commands premium positioning in inadequate responders. Fibrates represent the fastest-growing adjunct class as off-label and emerging on-label use expands in combination protocols.
The FDA maintains orphan drug exclusivity provisions and breakthrough therapy designation pathways that compress development timelines for PBC innovators. EMA parallel scientific advice and Japan's PMDA sakigake designation create synchronized access opportunities across the three largest reimbursed markets. Stakeholders must monitor how evolving nonalcoholic steatohepatitis treatment paradigms reshape hepatology resource allocation and payer budget impact assessments for autoimmune liver indications.
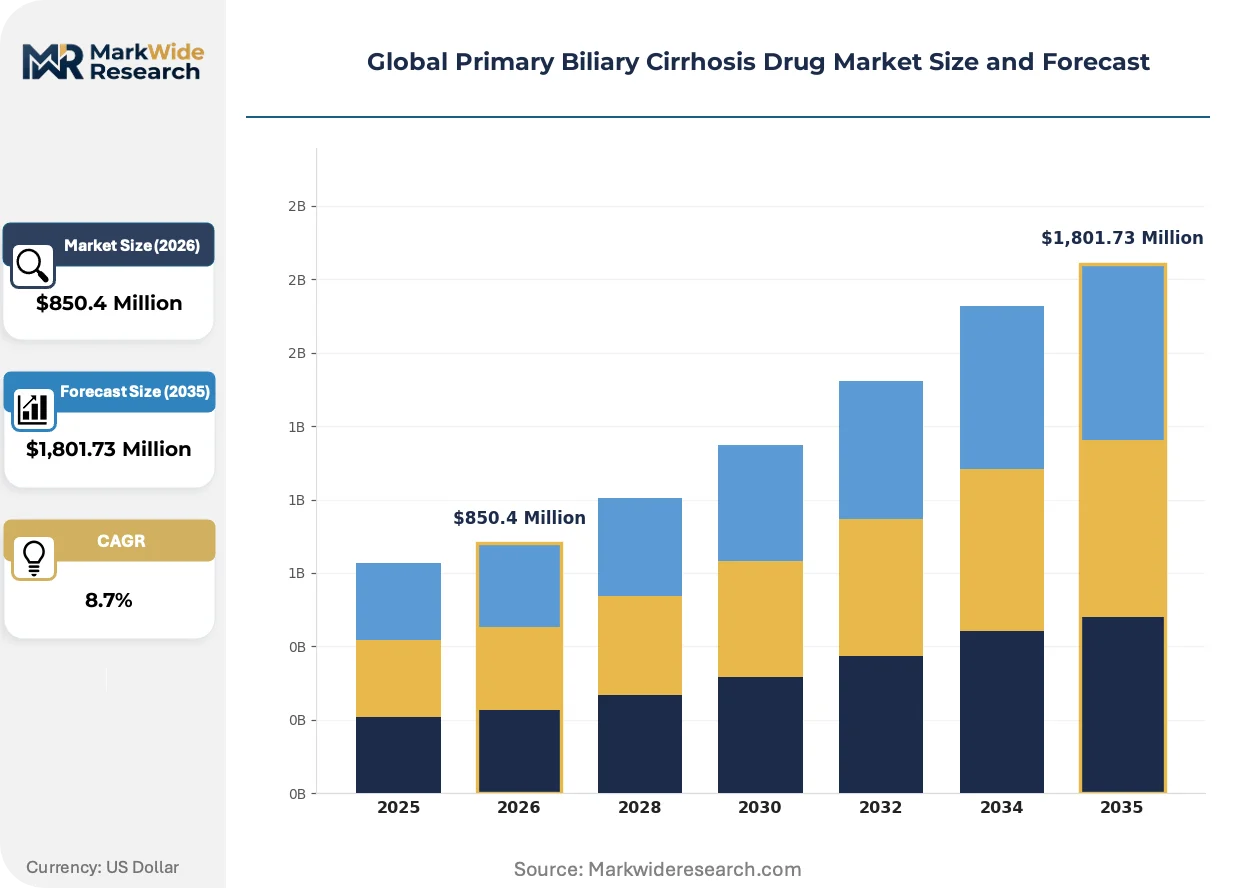
Market Dynamics
FDA's accelerated approval pathway for breakthrough therapies in rare liver diseases is compressing clinical trial timelines and reshaping how sponsors design Phase II/III programs for autoimmune hepatology indications.
Growth Catalysts
- Orphan drug exclusivity provisions:The FDA maintains 7-year market exclusivity and tax credits for clinical trial costs, incentivizing development in inadequately treated PBC populations.
- Specialist care infrastructure expansion:Hepatology centers in the United States, Germany, and Japan are establishing dedicated autoimmune liver disease clinics with embedded clinical trial units.
- Biomarker-guided patient stratification:Alkaline phosphatase response algorithms are enabling precision enrollment in second-line therapy protocols.
Market Restraints
- Bile acid raw material concentration:Ursodeoxycholic acid API synthesis depends on concentrated livestock sourcing regions, exposing supply to veterinary health policy volatility.
- Reimbursement fragmentation:Germany's G-BA benefit assessment processes create 12-18 month access delays for novel farnesoid X receptor modulators versus first-line generics.
- Diagnostic latency:General gastroenterology practices average 2.3 years from symptom onset to PBC diagnosis, compressing addressable patient pools.
Strategic Opportunities
- Japan's sakigake designation:The PMDA's priority review pathway offers synchronized EMA-FDA-Japan filing coordination for breakthrough hepatology therapies.
- Overlap syndrome populations:Autoimmune hepatitis-PBC combination presentations represent an emerging prescriber segment with unmet need.
- Pruritus management adjacents:G protein-coupled bile acid receptor antagonists are converging with existing PBC portfolios to address quality-of-life endpoints.
Industry Challenges
- Hepatology trialist scarcity:Qualified principal investigators with autoimmune liver disease expertise concentrate at 40-50 academic medical centers globally.
- Histological endpoint standardization:Ludwig staging system variability across pathology networks complicates regulatory submission consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Biliary Cirrhosis Drug Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,801.73 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Ursodeoxycholic Acid, Obeticholic Acid, Fibrates, Immunosuppressants, Antioxidants Therapy Stage: Initial Treatment, Maintenance Therapy, Symptom Management, Advanced Therapy, Adjunct Therapy Patient Age Group: Pediatric, Adult, Geriatric, Female, Male Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Clinics, Home Care Services |
| Companies Covered | Intercept Pharmaceuticals, Gilead Sciences, AbbVie, Takeda Pharmaceutical, Novartis, Sanofi, Merck & Co., Ipsen, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Biliary Cirrhosis Drug Market Shifts & Advancements
Drug-device combination approaches and digital biomarker integration are redefining how PBC progression gets monitored outside conventional liver biopsy protocols.
Non-invasive fibrosis assessment technologies incorporating magnetic resonance elastography and enhanced liver fibrosis scores are miniaturizing patient monitoring burdens. Hepatology centers in Germany and Japan are adopting these platforms for routine alkaline phosphatase responder stratification. The shift is compressing reliance on repeated invasive staging procedures.
EMA parallel scientific advice procedures are synchronizing development pathways across the United States, European Union, and Japan. Sponsors receive coordinated feedback on pivotal trial designs before protocol finalization. This regulatory convergence is accelerating market access timelines for farnesoid X receptor agonists.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for high-cost second-line therapies. United States payers are mandating limited distribution networks with embedded adherence monitoring. This channel consolidation is visible in Medicare Part D and commercial formulary management for orphan hepatology indications.
Global Primary Biliary Cirrhosis Drug Market Segmentation
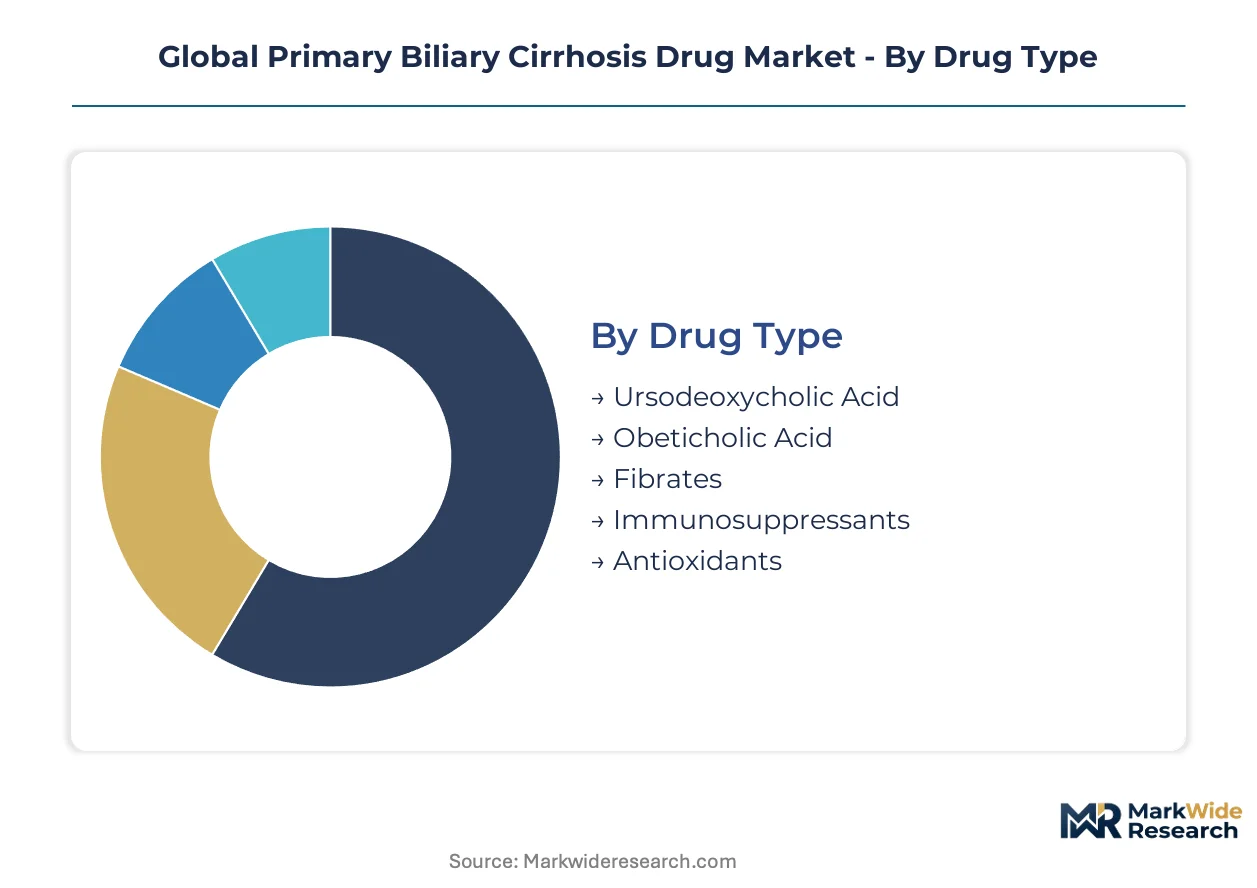
PBC drug procurement patterns diverge sharply across prescriber settings and reimbursement tiers. Manufacturers calibrate portfolio investments around where formulary access concentrates versus where volume accumulates.
Drug Type:
Margin pools concentrate in second-line therapies where orphan pricing mechanisms apply and generic competition remains absent.
- Ursodeoxycholic Acid:Bile acid modulator dosed at 13-15 mg/kg daily, synthesized from livestock-derived cholic acid precursors. Demand concentrates in Germany and Japan where first-line guidelines mandate UDCA before any second-line escalation, though pricing pressure from multi-source generic entry compresses manufacturer margins.
- Obeticholic Acid:Selective farnesoid X receptor agonist titrated from 5 mg to 10 mg based on pruritus tolerability. United States hepatology centers drive demand through FDA breakthrough therapy recognition and Medicare Part D orphan drug reimbursement, capturing premium positioning in alkaline phosphatase inadequate responders.
- Fibrates:Peroxisome proliferator-activated receptor alpha agonists deployed off-label and increasingly on-label in combination protocols.
- Immunosuppressants:Azathioprine and mycophenolate mofetil reserved for overlap syndrome presentations with autoimmune hepatitis features.
- Antioxidants:N-acetylcysteine and vitamin E formulations addressing oxidative stress adjunctively.
The dominant share belongs to Ursodeoxycholic Acid, while Fibrates are gaining share fastest through expanding combination protocol adoption.
Therapy Stage:
Prescription volume distributes unevenly across treatment phases, with initial and maintenance stages anchoring volume while advanced therapy stages anchor value.
- Initial Treatment:First-line UDCA initiation following alkaline phosphatase elevation confirmation and AMA-M2 antibody positivity. United States gastroenterology practices concentrate volume here, though diagnostic latency of 2.3 years from symptom onset compresses addressable patient identification.
- Maintenance Therapy:Long-term UDCA continuation with six-monthly alkaline phosphatase monitoring. Germany's G-BA benefit assessment framework mandates sustained biochemical response documentation for continued reimbursement, creating adherence measurement infrastructure that other European markets are adopting.
- Symptom Management:Pruritus and fatigue-directed interventions including bile acid sequestrants and G protein-coupled receptor antagonists.
- Advanced Therapy:Second-line obeticholic acid or fibrate addition following Paris-II criteria failure.
- Adjunct Therapy:Osteoporosis prophylaxis, fat-soluble vitamin replacement, and hepatocellular carcinoma surveillance coordination.
Maintenance Therapy captures the largest prescription volume, though Advanced Therapy generates the steepest per-patient revenue trajectory.
Patient Age Group:
Clinical presentation and reimbursement pathways diverge across demographic strata, with adult female patients representing the historical core market.
- Pediatric:Rare presentations requiring specialized hepatology center management and modified dosing protocols.
- Adult:Peak incidence demographic with established UDCA response algorithms and employment-maintaining treatment goals.
- Geriatric:Growing segment with comorbidity burden complicating polypharmacy and tolerability assessments.
- Female:Dominant epidemiological profile with disease-modifying therapy decisions intersecting family planning considerations.
- Male:Smaller absolute numbers with historically delayed diagnosis and more aggressive histological progression patterns.
Female patients retain the dominant disease prevalence share, while Geriatric classification is expanding most quickly as incident age distribution shifts.
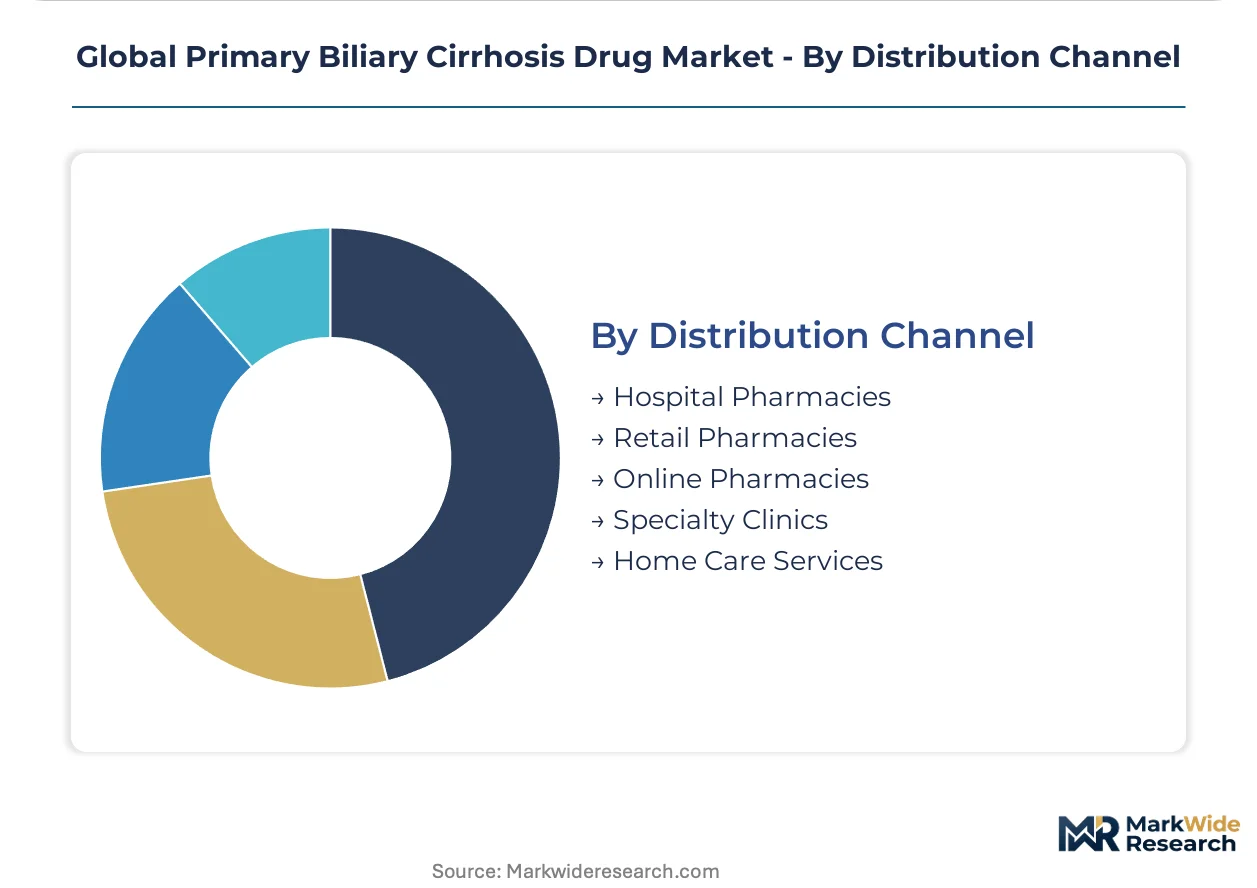
Distribution Channel:
Channel economics are restructuring around specialty pharmacy consolidation for high-cost orphan therapies versus retained hospital dispensing for monitored initiations.
- Hospital Pharmacies:Inpatient and outpatient dispensing for de novo diagnoses and acute pruritus management. Japan's hepatology centers maintain concentrated hospital pharmacy reliance due to PMDA adverse event reporting integration requirements.
- Retail Pharmacies:Generic UDCA volume and maintenance prescription fulfillment. Germany's Apotheken network handles significant first-line volume through statutory health insurance reimbursement.
- Online Pharmacies:Emerging channel for maintenance refill convenience, particularly in United States Medicare Part D plans with mail-order incentives.
- Specialty Clinics:Embedded pharmacy services in hepatology centers with direct clinician oversight.
- Home Care Services:Infrequent utilization limited to severe disability or transplant evaluation periods.
Hospital Pharmacies retain the dominant dispensing share for monitored therapies, while Specialty Clinics are expanding most quickly through limited distribution network mandates for second-line agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for ursodeoxycholic acid concentrates in livestock-dependent regions, while finished formulation manufacturing and clinical development cluster near specialist hepatology infrastructure. Patient access patterns diverge sharply across reimbursement regimes.
United States
Medicare Part D orphan drug reimbursement anchors premium pricing for second-line therapies. The FDA's breakthrough therapy designation compresses development timelines for farnesoid X receptor modulators. Hepatology centers in Boston, New York, and San Francisco maintain embedded clinical trial units for autoimmune liver disease protocols.
Germany
Statutory health insurance mandates G-BA benefit assessment for novel agents, creating documented adherence infrastructure. The country's Apotheken network handles substantial first-line generic volume. Hepatology clusters in Munich and Hamburg coordinate alkaline phosphatase responder stratification with non-invasive fibrosis assessment platforms.
Japan
PMDA sakigake designation offers priority review synchronization with FDA and EMA pathways. Hospital pharmacy dispensing dominates due to adverse event reporting integration requirements. Tokyo and Osaka hepatology centers lead adoption of magnetic resonance elastography for routine patient monitoring.
Switzerland
Swissmedic maintains aligned review procedures with EMA for hepatology indications. The country's cantonal hospital networks concentrate specialist autoimmune liver disease management in Zurich and Geneva. Premium pricing acceptance for orphan therapies exceeds neighboring European markets.
United Kingdom
NICE technology appraisal processes evaluate cost-effectiveness for NHS England formulary inclusion. London teaching hospitals anchor national referral pathways for complex overlap syndrome presentations. Scotland's separate health technology assessment creates regional access variation for novel fibrate combinations.
Global Primary Biliary Cirrhosis Drug Market Competitive Landscape
Concentration sits with specialty hepatology-focused developers rather than diversified pharmaceutical conglomerates. The competitive terrain splits between established bile acid modulator franchises and emerging farnesoid X receptor agonist entrants. Three archetypes dominate: orphan disease specialists with regulatory acceleration expertise, immunology portfolio players extending into autoimmune hepatology, and generic manufacturers capturing first-line volume erosion. Competitive moves center on hepatology specialist education investment and payer engagement infrastructure rather than manufacturing scale expansion.
Within the orphan disease specialist tier, Intercept Pharmaceuticals exemplifies sustained commitment to hepatology specialist network cultivation. Gilead Sciences occupies a position bridging transplant and fibrosis center commercial infrastructure. AbbVie represents the immunology portfolio extension archetype, targeting overlap syndrome populations with autoimmune hepatitis-PBC combination presentations. These three anchors illustrate divergent strategic postures toward the same prescriber base.
| Leading Market Players |
|---|
| Intercept Pharmaceuticals |
| Gilead Sciences |
| AbbVie |
| Takeda Pharmaceutical |
| Novartis |
| Sanofi |
| Merck & Co. |
| Ipsen |
| Viatris |
| Others |
Supply & Pricing Matrix
Livestock-derived cholic acid precursors replacing synthetic bile acid feedstocks are redrawing API sourcing maps toward veterinary-intensive regions while compressing margin structures for finished dose manufacturers dependent on stable input costs.
Pricing Analysis
Volume-discount tiering structures separate originator farnesoid X receptor agonists from multi-source generic ursodeoxycholic acid and economy-grade regional manufacturers. Price differentiation rests on FDA breakthrough therapy designation and orphan drug exclusivity versus statutory health insurance reimbursement ceilings in Germany and Japan. Cost compression in first-line generics is intensifying because multi-source entry erodes manufacturer margins below sustainable R&D recovery thresholds. Hospital procurement committees exhibit highest price sensitivity for maintenance therapy volumes, while specialty hepatology centers demonstrate lowest sensitivity for second-line inadequate responder protocols.
Supply Chain Analysis
China and India anchor ursodeoxycholic acid API production through concentrated livestock processing infrastructure, while Germany and Japan specialize in finished dose formulation and quality certification. Raw material dependencies center on bovine and ovine bile extraction, synthetic cholic acid chemistry, and specialized fermentation capacity for farnesoid X receptor agonist synthesis. Single-source vulnerability concentrates in veterinary health policy disruptions affecting livestock herd availability. Distribution runs through specialty pharmacy networks for orphan-priced second-line therapies and hospital outpatient dispensing for monitored treatment initiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in adherence monitoring and biochemical response tracking are expanding faster than pharmaceutical product margins, creating recurring revenue layers that offset pricing pressure on core drug formulations.
For Market Incumbents: Secure embedded pharmacy services within hepatology centers to control patient initiation pathways and capture real-world evidence generation. Deepen backward integration into bile acid API supply through captive livestock sourcing partnerships or synthetic chemistry investments. Defend against fibrate combination protocol erosion by expanding biomarker-guided patient stratification infrastructure. For New Entrants and Emerging Players: FDA accelerated approval and PMDA sakigake designation fast-tracks compress regulatory timelines for breakthrough hepatology therapies, enabling earlier revenue recognition. White-space targets concentrate in overlap syndrome populations with autoimmune hepatitis features and pruritus-directed G protein-coupled receptor antagonist adjacencies. The most penetrable segment spans Germany's G-BA benefit assessment-delayed patient pools awaiting second-line access. Go-to-market execution should prioritize hepatology specialist education investment over primary care outreach. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors orphan disease specialists with regulatory acceleration expertise and established payer engagement infrastructure. Long-term viability over a 5-10 year window hinges on portfolio diversification beyond single-molecule dependence toward combination protocol positioning. Acquisition targets should demonstrate embedded clinical trial unit relationships with academic medical centers. The signal to watch is histological endpoint standardization progress across EMA-FDA-Japan regulatory convergence initiatives.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Non-invasive fibrosis assessment platforms enable patient stratification without repeated liver biopsy burdens. |
| Regulatory Approval Pathway | EMA parallel scientific advice synchronizes FDA and PMDA submissions for farnesoid X receptor modulators. |
| Licensing Agreement | G protein-coupled bile acid receptor antagonist partnerships address quality-of-life endpoints in pruritus management. |
| Manufacturing Scale-Up | Synthetic cholic acid chemistry investments reduce livestock-dependent API concentration risks. |
| Pipeline Diversification | Overlap syndrome targeting extends autoimmune hepatitis-PBC combination presentation coverage. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across patient epidemiology, treatment algorithm penetration, and reimbursement framework constraints.
Sensitivity analysis tested forecast robustness across alkaline phosphatase responder rate assumptions, diagnostic latency compression scenarios, and second-line therapy escalation thresholds. The analytical framework segmented by drug type, therapy stage, patient age group, and distribution channel across the projection horizon. CAGRs derived from log-linear trend fitting adjusted for regulatory approval timing and formulary access delays. Forecast inputs incorporated hepatology center capacity expansion rates and specialty pharmacy network consolidation patterns.
Underlying assumptions cover sustained orphan drug exclusivity provisions, stable livestock sourcing for bile acid precursors, and continued G-BA benefit assessment frameworks, with deviation risk concentrated in veterinary health policy shifts and non-alcoholic steatohepatitis resource reallocation. Recalibration cycles align with material shifts in regulatory pathway convergence, diagnostic technology adoption, and payer budget impact assessment methodologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market