
 Urinary Catheters Market | 2026-2036
Urinary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Catheters Market Analysis
A capital-intensity divergence between automated extrusion lines and manual assembly floors is redrawing competitive boundaries in urinary catheter manufacturing. Coloplast leverages vertical integration across silicone polymer sourcing to sustain margin control in premium segments. B. Braun Melsungen AG anchors European supply through its catheter molding complexes in Germany. Teleflex Incorporated competes in North American acute care channels with specialized neurourology portfolios.
Urinary catheters are hollow, flexible tubes manufactured from latex, silicone, or hydrogel composites, typically 6-18 French in diameter, designed to drain urine from the bladder through urethral or suprapubic insertion. These devices serve critical functions in urinary retention management, post-surgical recovery, and chronic neurological conditions where voluntary voiding is impaired. Foley catheters occupy the largest revenue pool due to their indwelling design and higher per-unit pricing in hospital procurement contracts. Intermittent catheters represent the fastest-expanding category as home care protocols and patient self-catheterization training programs reduce infection risks and facility costs. Silicone material formulations command premium positioning over latex alternatives where biocompatibility and allergen avoidance drive clinical selection.
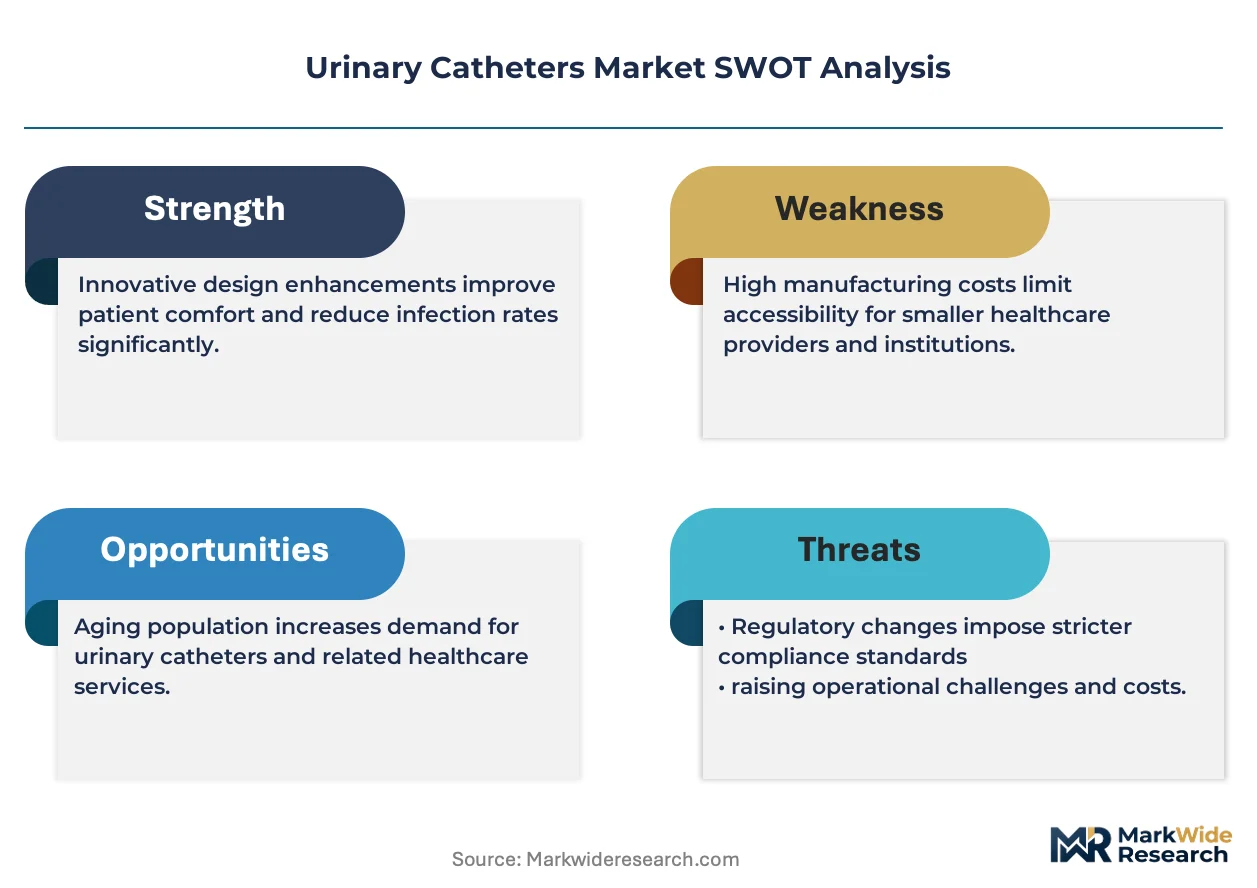
The FDA enforces 510(k) premarket notification requirements for urinary catheters, while the EU Medical Device Regulation mandates clinical evidence and notified body oversight for CE marking in European markets. These frameworks elevate barriers for new entrants and reward manufacturers with established quality management systems and predicate device portfolios. Stakeholders must monitor evolving reimbursement thresholds in home care settings and antimicrobial coating standards that will determine next-generation product viability.
Market Dynamics
The migration of urinary catheter utilization from acute care facilities toward home-based settings is restructuring procurement volumes, reimbursement pathways, and product specifications across developed healthcare systems.
Growth Catalysts
- Germany's reimbursement reforms:Outpatient coverage expansions for single-use intermittent catheters are accelerating patient transitions from hospital-based care to self-managed regimens.
- Silicone polymer transitions:The FDA's streamlined 510(k) pathway for silicone-based devices is compressing approval timelines and enabling faster material substitution away from latex alternatives.
- Aging demographic concentration:Home care providers in Japan and Italy are scaling catheter procurement as elderly populations with chronic retention conditions seek treatment outside institutional settings.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer production clusters in Germany and the United States create input vulnerability for manufacturers dependent on just-in-time sourcing.
- Antimicrobial coating technical limitations:Silver-alloy and nitrofurazone formulations face diminishing efficacy against resistant biofilm formations, constraining premium positioning for coated devices.
- EU MDR compliance friction:The Medical Device Regulation's clinical evidence requirements for Class IIa devices are extending certification timelines and elevating documentation burdens.
Strategic Opportunities
- Underpenetrated home care channels in France:Regional reimbursement disparities create whitespace for catheter suppliers establishing direct-to-patient distribution networks outside hospital procurement.
- Closed-system intermittent catheter convergence:Integration of pre-lubricated surfaces with touch-free insertion sleeves is opening premium positioning for infection-prevention-focused protocols.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are attracting catheter assembly investments targeting price-sensitive emerging demand.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of optimizing silicone durometer and tensile properties for catheter applications command premium compensation and limited availability.
- ISO 13485 certification timeline compression:Quality management system audits for new manufacturing facilities are experiencing backlogs at notified bodies, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Catheters Market |
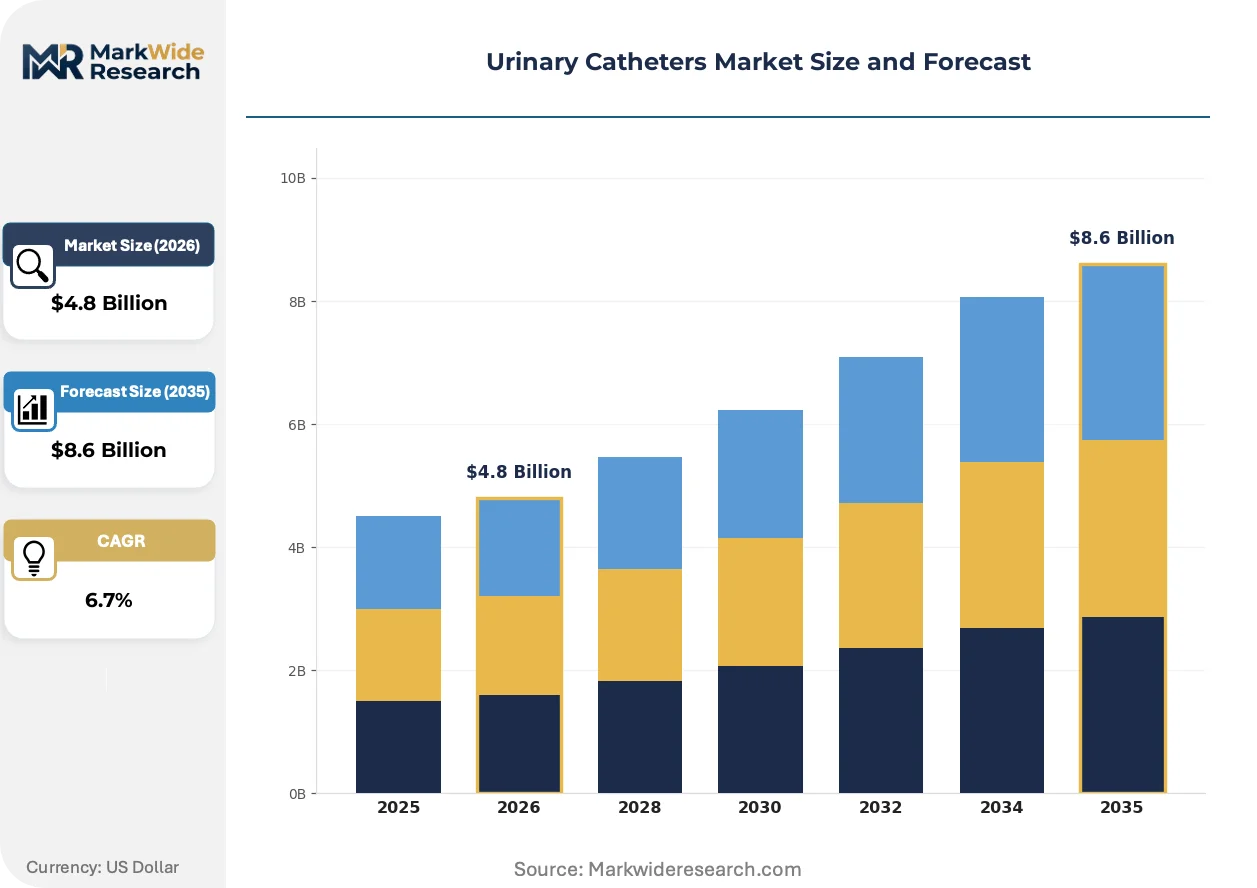
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheters, Foley Catheters, Suprapubic Catheters, Condom Catheters End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Material: Latex, Silicone, PVC, Hydrogel Application: Urinary Retention, Post-operative Care, Neurourology, Palliative Care |
| Companies Covered | ConvaTec Inc., Hollister Incorporated, B. Braun Melsungen AG, Cardinal Health, Cook Medical, Boston Scientific Corporation, Coloplast, Medtronic, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Catheters Market Emerging Trajectories
Material science advances and regulatory pathway adaptations are converging to redefine product differentiation strategies, with coating technologies and polymer formulations emerging as primary battlegrounds for competitive positioning.
Silicone elastomer formulations with optimized shore hardness and reduced surface friction are supplanting latex and PVC alternatives in premium catheter segments. Home care distributors in the United States and Germany are prioritizing silicone inventory based on patient allergy profiles and extended indwelling duration requirements. This material transition is compressing margins for manufacturers lacking backward integration into polymer sourcing.
The FDA's updated 510(k) premarket notification framework for silicone-based urinary devices is accelerating predicate device referencing and reducing review cycles. Manufacturers with established quality management systems are leveraging this regulatory efficiency to compress time-to-market for next-generation formulations. Acute care procurement channels in the United States are responding with faster contract onboarding for cleared silicone portfolios.
Hospital supply chain managers are unbundling catheter procurement from bundled payment contracts and negotiating direct manufacturer agreements. This purchasing behavior shift is disintermediating traditional distributor relationships in North American and Western European markets. The trend is most pronounced in integrated delivery networks managing high-volume urology service lines.
Urinary Catheters Market Segmentation
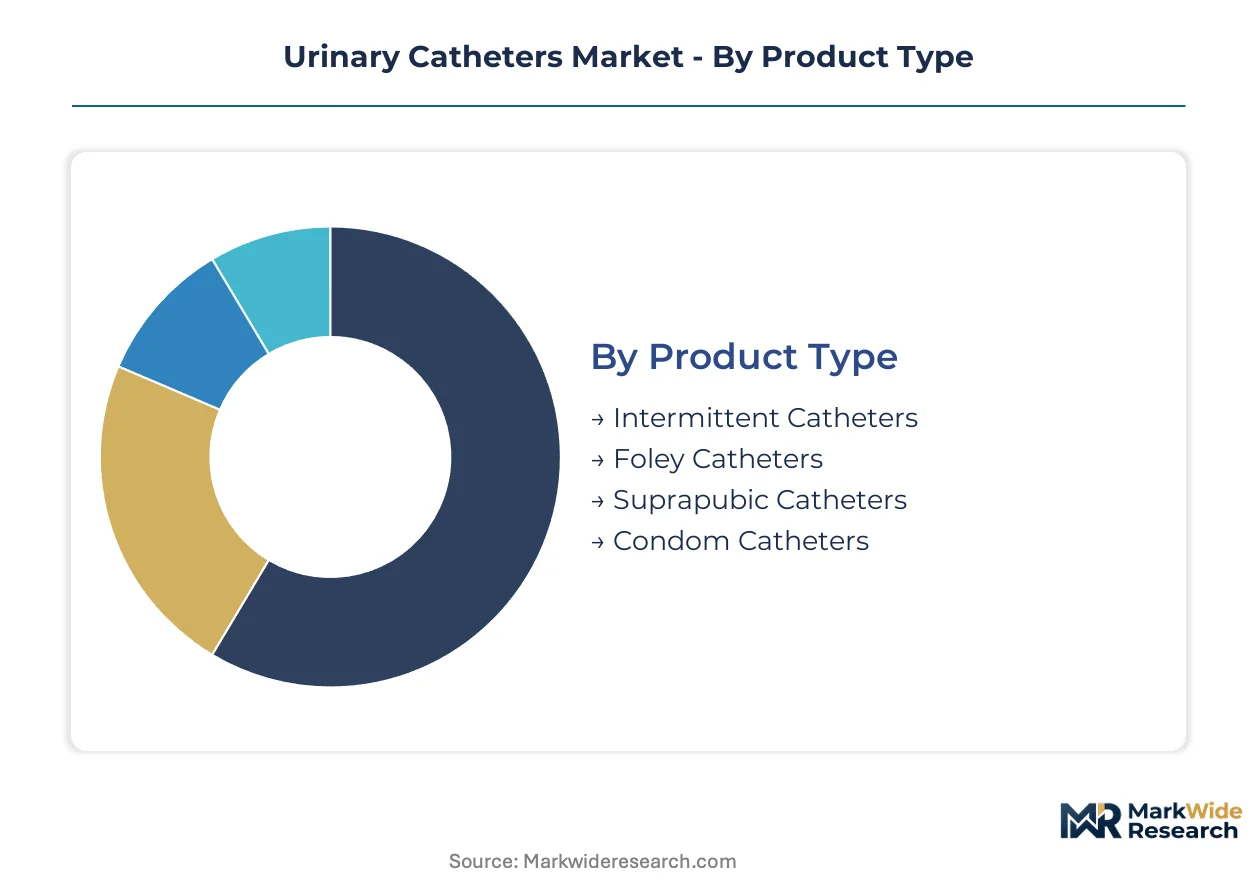
Channel configuration varies sharply across urinary catheter segments. Hospital procurement favors indwelling systems with higher per-unit value, while home care distributors prioritize compact, patient-operated formats that reduce infection liability and logistics costs.
Product Type:
Channel mix splits between acute care contracts for indwelling devices and retail pharmacy or direct-to-patient distribution for intermittent formats.
- Foley Catheters:Balloon-retention indwelling tubes manufactured in 2-way and 3-way configurations for continuous bladder drainage. Hospital supply chains in Germany and the United States concentrate procurement here due to higher reimbursement ceilings and extended dwell-time protocols.
- Intermittent Catheters:Single-use straight or coudé-tip designs for patient self-catheterization. Home care channels in Japan and Italy are scaling inventory fastest as aging populations transition from institutional to self-managed voiding regimens.
- Suprapubic Catheters:Percutaneous insertion tubes for patients with urethral trauma or obstruction.
- Condom Catheters:External sheath systems for male patients with functional incontinence.
Foley catheters dominate installed base. Intermittent catheters are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive acute facilities from price-sensitive home settings.
- Hospitals:Integrated delivery networks negotiate multi-year contracts for coated indwelling devices with antimicrobial specifications. Procurement volume concentrates in tertiary centers managing complex urology and post-surgical caseloads.
- Home Care:Direct-to-patient distributors in France and the United States are building intermittent catheter inventories as reimbursement shifts toward outpatient coverage. Self-catheterization training programs reduce readmission penalties for payers.
- Clinics:Outpatient urology practices source mid-volume intermittent and Foley supplies.
- Long-term Care Facilities:Nursing homes balance infection control protocols against per-patient supply budgets.
Hospitals anchor revenue concentration. Home care is climbing the fastest as site-of-care migration accelerates.
Material:
Margin structure diverges between premium silicone formulations and commodity latex alternatives.
- Silicone:Biocompatible elastomer with optimized shore hardness for extended indwelling duration. FDA's streamlined 510(k) pathway is compressing approval timelines for silicone predicate devices, accelerating substitution away from latex in United States acute care channels.
- Latex:Natural rubber formulations facing allergen liability and material transition pressure.
- PVC:Cost-driven polymer for price-sensitive institutional procurement.
- Hydrogel:Surface-modified coatings for reduced friction and biofilm resistance.
Silicone commands premium positioning. Latex retains volume in emerging markets where cost sensitivity dominates.
Application:
Volume concentration aligns with chronic condition prevalence and surgical procedure rates.
- Urinary Retention:Obstructive and neurogenic voiding dysfunction requiring catheterization. Germany's outpatient reimbursement reforms are expanding intermittent catheter coverage for benign prostatic hyperplasia and diabetic neuropathy patients.
- Post-operative Care:Temporary drainage following abdominal, pelvic, or spinal procedures.
- Neurourology:Spinal cord injury and multiple sclerosis populations requiring specialized catheter protocols.
- Palliative Care:Comfort-focused drainage for terminal patients with limited mobility.
Urinary retention drives procedure volume. Neurourology shows steepest expansion trajectory as spinal cord injury survival rates improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for urinary catheters diverges sharply across healthcare systems. German and Japanese buyers exhibit low price sensitivity where reimbursement coverage is comprehensive, while Indian and Brazilian procurement channels prioritize cost efficiency over material sophistication.
United States
Hospital supply chains and home care distributors drive silicone catheter procurement as patient allergy profiles shift clinical preference. The FDA's streamlined 510(k) pathway compresses approval timelines for predicate silicone devices. Minnesota and Massachusetts host catheter molding operations serving integrated delivery networks with high-volume urology contracts.
Germany
Outpatient reimbursement reforms accelerate single-use intermittent catheter adoption among benign prostatic hyperplasia patients. The EU Medical Device Regulation elevates clinical evidence requirements for Class IIa devices. Melsungen anchors European supply through catheter molding complexes serving hospital procurement across the continent.
Japan
Aging demographics with neurogenic voiding dysfunction expand home care catheter volumes faster than institutional channels. The PMDA enforces quality management system standards for imported medical devices. Tokyo and Osaka metropolitan areas concentrate distributor networks building direct-to-patient intermittent catheter inventories.
India
Production-linked incentive schemes attract catheter assembly investments targeting price-sensitive emerging demand. The CDSCO regulates medical device imports and domestic manufacturing licensing. Gujarat and Karnataka industrial corridors host new manufacturing facilities serving South Asian and Middle Eastern export markets.
Italy
Elderly populations with chronic retention conditions transition from hospital-based care to self-managed regimens. REACH compliance requirements govern silicone polymer imports from German suppliers. Lombardy and Emilia-Romagna cluster home care distributors scaling intermittent catheter logistics for northern Italian regions.
Urinary Catheters Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in urinary catheter manufacturing. The upper tier commands premium positioning through captive silicone sourcing and established FDA predicate portfolios. The specialist tier competes on intermittent catheter formats and regional home care channel access. Strategic moves concentrate on backward integration into polymer compounding and direct-to-patient distribution network expansion.
Within the integrated multinational tier, Coloplast and B. Braun Melsungen AG exemplify archetypes combining polymer sourcing control with European manufacturing scale. Teleflex Incorporated occupies a position in North American acute care channels. Hollister Incorporated and ConvaTec Inc. sit within the specialist tier with concentrated portfolios in catheter surface technologies and home care logistics. Cardinal Health represents the distributor-manufacturer hybrid model leveraging hospital supply chain relationships.
| Leading Market Players |
|---|
| ConvaTec Inc. |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| Cardinal Health |
| Cook Medical |
| Boston Scientific Corporation |
| Coloplast |
| Medtronic |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
FDA's 510(k) predicate device requirements gate both supplier qualification and price tier separation in urinary catheter procurement. The regulatory barrier simultaneously filters out commodity producers and enables premium positioning for silicone-based portfolios with established clearance pathways.
Pricing Analysis
After-sales service contracts for catheterization training and infection management drive lifetime value capture in home care channels. Three-tier pricing structure across premium silicone, standard PVC, and economy latex levels stratifies procurement decisions. Price differentiation rests on FDA clearance tier and antimicrobial coating certification. Cost compression in latex segments intensifies as Indian manufacturers scale assembly capacity. Home care distributors exhibit highest price sensitivity; integrated delivery networks in tertiary urology centers show lowest.
Supply Chain Analysis
Germany and the United States anchor medical-grade silicone polymer production for catheter manufacturing. Specialty elastomer compounding draws from petrochemical feedstocks and platinum-catalyst formulations. Single-source vulnerability concentrates in German polymer suppliers serving European molding operations. Distribution runs through hospital GPO contracts, home care direct-to-patient networks, and retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urinary catheter demand is accelerating through regulatory tailwinds for silicone materials and reimbursement expansion into outpatient settings. FDA's streamlined 510(k) pathway for predicate devices compresses approval timelines and rewards established quality systems.
For Market Incumbents: Consolidate backward integration into silicone polymer sourcing to defend margin erosion from Asian assembly competitors. Expand catheter molding capacity in Germany to anchor EU MDR-compliant supply. Prioritize ISO 13485 certification maintenance as notified body audit backlogs delay rival market entry. For New Entrants and Emerging Players: Direct-to-patient distribution gaps in French home care channels offer whitespace for intermittent catheter suppliers. Target underpenetrated self-catheterization training programs as the most penetrable entry point. Pursue reimbursement strategy partnerships with regional payers ahead of hospital procurement contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated extrusion line deployments versus manual assembly floors. Long-term viability favors targets with captive silicone supply and established FDA predicate portfolios. Watch antimicrobial coating efficacy data against resistant biofilms as the inflection signal for next-generation product viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined pathway for silicone predicate devices accelerates United States market entry timelines. |
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIa devices elevate documentation barriers for competitors. |
| Hospital System Partnership | Direct contracts with integrated delivery networks disintermediate traditional distributor relationships. |
| Backward Integration | Captive silicone polymer sourcing insulates margin control from specialty elastomer supply concentration. |
| Reimbursement Strategy | Outpatient coverage expansion in Germany and Japan shifts procurement volume toward home care channels. |
Methodological Framework
The analysis maps Foley catheter, intermittent catheter, and suprapubic catheter sub-sectors, each validated through hospital purchasing committees, home care distributors, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement contracts. Bottom-up and top-down triangulation cross-checked manufacturer capacity disclosures against distributor inventory data.
Consistency checks validated volume and value outputs against catheter utilization rates in tertiary urology centers and self-catheterization training program enrollments. The analytical framework segments by product type, material formulation, end-user channel, and regional reimbursement regime across the projection horizon. CAGRs derived from procedure volume elasticity to aging demographic shifts and site-of-care migration patterns. Forecast inputs include antimicrobial coating adoption curves and silicone substitution rates from latex alternatives.
Underlying assumptions cover reimbursement stability in German outpatient settings and FDA regulatory pathway continuity, with deviation risk concentrated in EU MDR audit backlogs and medical-grade silicone supply disruptions. Recalibration cycles align with material shifts in antimicrobial coating standards and predicate device clearance velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Pyelonephritis Treatment Market
Urology
Ureteral Catheters Market
Urology
Urology Robotic Surgery Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Uropathy Treatment Market
Urology
Global Bladder Cancer Market
Urology
Self-Intermittent Catheters Market
Urology
Botulinum Toxin in Urology Market
Urology
Varicocele Treatment Market
Urology
Hematuria Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Urology Disposables Market
Urology
North America Bladder Disorders Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
LAMEA Transrectal Ultrasound Market