
 Ureteral Catheters Market | 2026-2036
Ureteral Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Ureteral Catheters Market Outlook
Asset-light manufacturing partnerships and third-party sterilization leasing is reconfiguring capital requirements for mid-sized entrants in the ureteral catheter space. Teleflex Incorporated leverages its integrated vascular access platform to sustain cross-selling momentum into urology suites. Cook Medical LLC anchors its competitive position through vertically controlled nitinol processing capabilities. Coloplast A/S differentiates via specialized hydrophilic coating technologies that reduce tissue trauma during placement.
Ureteral catheters are hollow, flexible tubes manufactured from medical-grade silicone, polyurethane, or thermoplastic elastomers, typically ranging 4-8 French in diameter, designed to establish temporary drainage pathways between the renal pelvis and bladder. Double-J stents command the dominant product position due to their biocompatible curl geometry that resists proximal and distal migration. Silicone and polyurethane materials capture the fastest-growing material segment as manufacturers phase out latex formulations in response to allergy protocols. Postoperative care applications generate concentrated margin pools through higher replacement frequencies and bundled reimbursement structures.
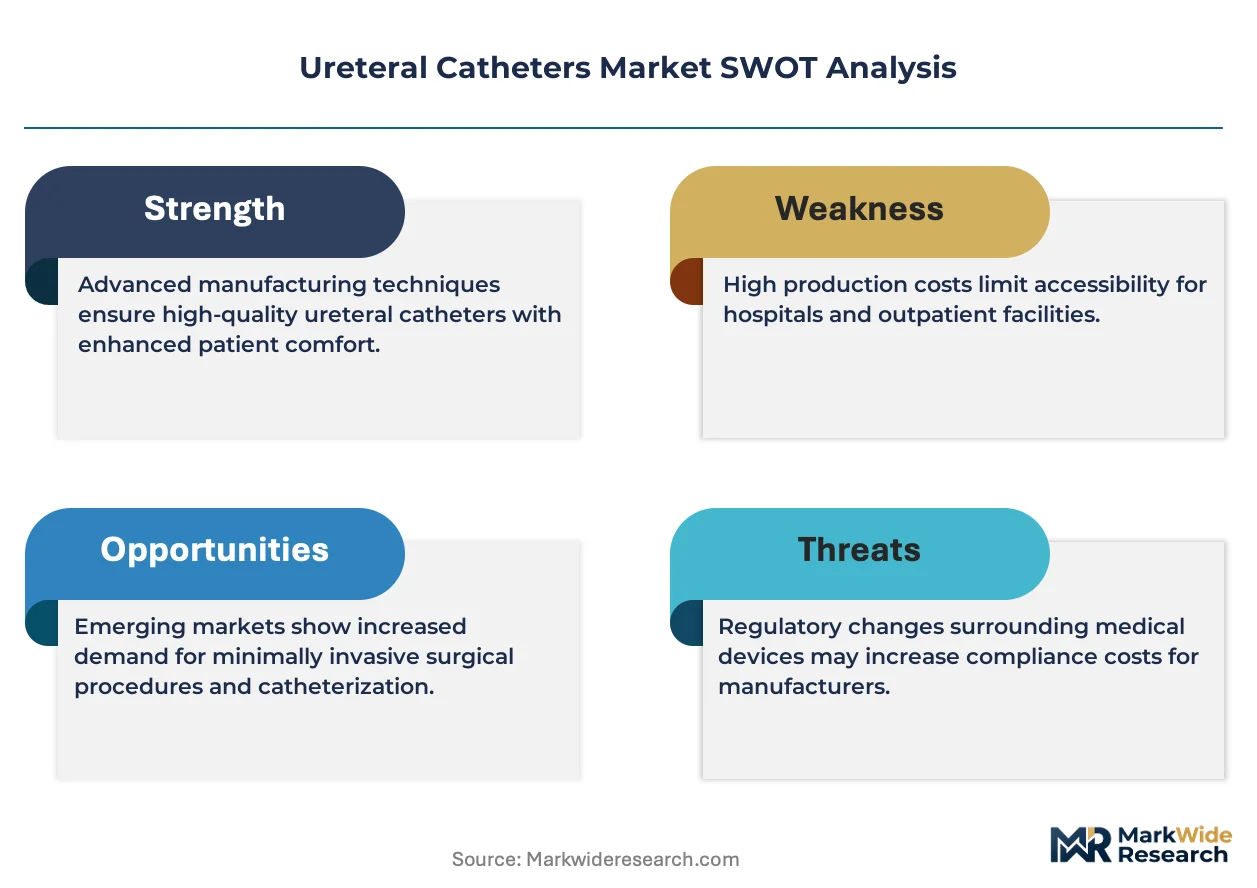
The FDA 510(k) clearance framework governs market entry for Class II ureteral devices in the United States, while the EU MDR imposes strengthened clinical evidence requirements for CE marking in European markets. ISO 10993 biocompatibility testing and USP Class VI certification function as baseline qualification standards that filter out undercapitalized suppliers. Stakeholders must monitor evolving sterilization validation requirements and single-use device reprocessing restrictions that threaten to alter cost structures and competitive positioning.
Market Dynamics
The ureteral catheter market is consolidating around hydrophilic coating technologies that reduce tissue trauma and enable same-day discharge protocols, compressing replacement cycles while elevating performance standards for mid-tier manufacturers.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined Class II device clearances accelerate commercialization timelines for silicone-based stent innovations, reducing regulatory friction for domestic entrants targeting ambulatory surgical centers.
- Stone Disease Prevalence:Rising incidence of urolithiasis in aging populations sustains procedural volumes across hospital systems and outpatient clinics, particularly in regions with expanding minimally invasive surgery infrastructure.
- Polyurethane Material Advances:Enhanced biocompatibility profiles and extended indwell times of thermoplastic elastomer formulations are displacing latex alternatives in allergy-sensitive patient cohorts.
Market Restraints
- Nitinol Supply Concentration:Controlled access to shape-memory alloy processing capabilities limits stent curl geometry optimization for non-vertically integrated manufacturers, constraining product differentiation.
- EU MDR Clinical Evidence Burden:Strengthened post-market surveillance and clinical data requirements for CE marking extend approval timelines and elevate documentation costs for European market entry.
- Reusable Scope Disinfection Standards:Stringent sterilization validation protocols for cystoscopy equipment create capital intensity barriers for ambulatory facilities considering in-house ureteral procedures.
Strategic Opportunities
- Telehealth-Enabled Remote Monitoring:Integration of patient-reported outcome platforms with catheter management protocols opens subscription revenue streams for postoperative care providers.
- Single-Use Device Mandates:Reprocessing restrictions in tertiary care systems are accelerating demand for pre-sterilized, individually packaged stent kits with embedded tracking identifiers.
- India's Surgical Infrastructure Expansion:Government-backed urology center development under national health mission programs creates first-mover advantages for coating-technology licensors.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization study backlogs at certified laboratories extend product qualification timelines by six to nine months.
- Sterilization Validation Complexity:Ethylene oxide residue compliance and alternative sterilization method transitions require dedicated regulatory affairs capacity that strains emerging manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ureteral Catheters Market |
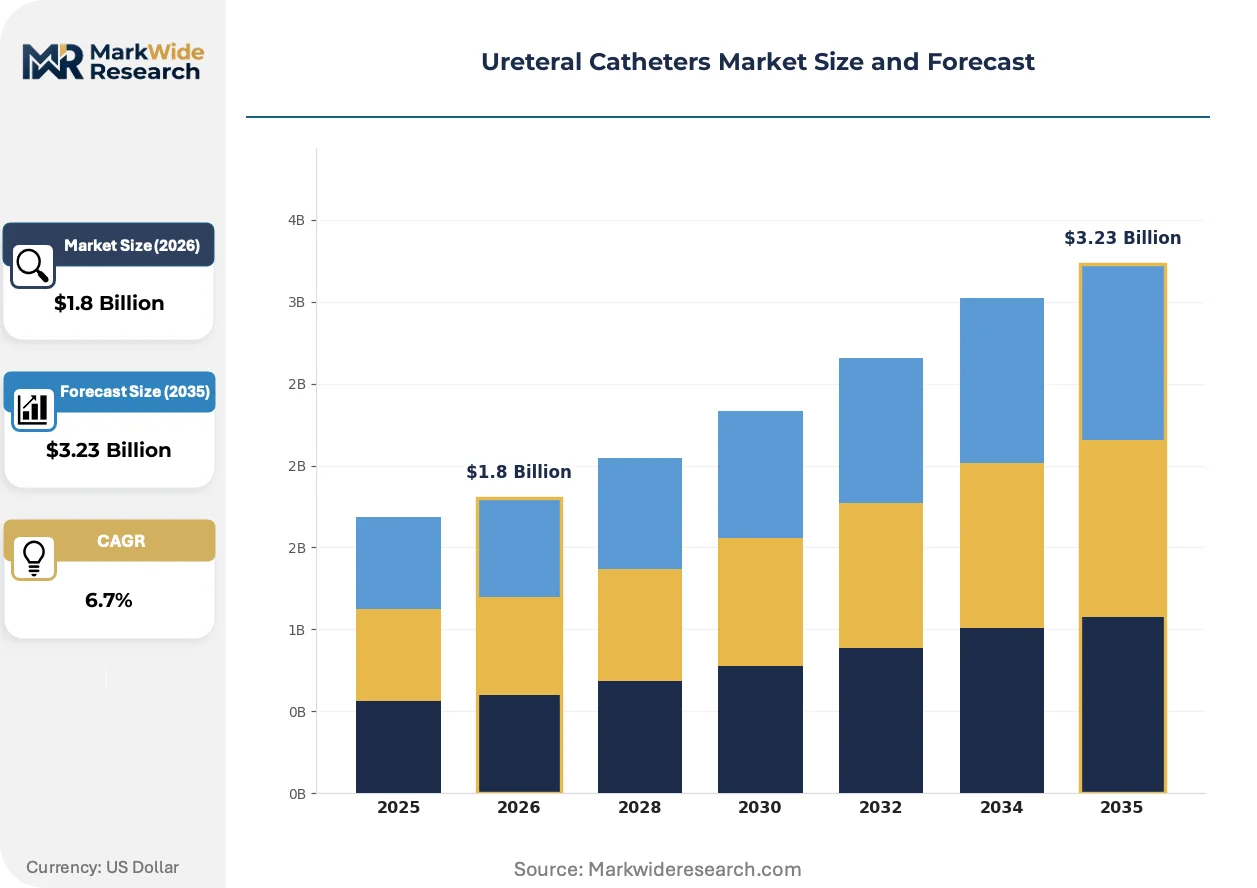
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-J Stents, Pigtail Catheters, Drainage Catheters, Other Catheters Material: Silicone, Polyurethane, Latex, Thermoplastic Application: Urinary Obstruction, Postoperative Care, Diagnostic Procedures, Other Applications End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care |
| Companies Covered | Teleflex Incorporated, B. Braun Melsungen AG, Boston Scientific Corporation, BD, Porges GmbH, Cook Medical LLC, Olympus Corporation, Applied Medical Resources, Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ureteral Catheters Market Strategic Shifts
Active innovation in ureteral catheter design centers on material science convergence with digital health integration, reshaping how manufacturers capture value beyond the initial device sale.
Drug-eluting stent coatings are migrating from experimental protocols to standard-of-care expectations in tertiary referral centers, with dexamethasone and triclosan formulations reducing stent-related symptom scores and enabling extended indwell protocols that compress replacement revenue for traditional models.
EU MDR post-market clinical follow-up requirements are forcing systematic patient registry participation for CE-marked devices, with notified bodies demanding real-world evidence on migration rates and encrustation patterns that reshape R&D prioritization toward longitudinal performance data collection.
Hospital procurement committees are consolidating vendor relationships through dual-source frameworks that bundle ureteral stents with complementary urology disposables, compressing standalone catheter margins while rewarding integrated supply contracts with volume guarantees and preferred formulary placement.
Ureteral Catheters Market Segmentation
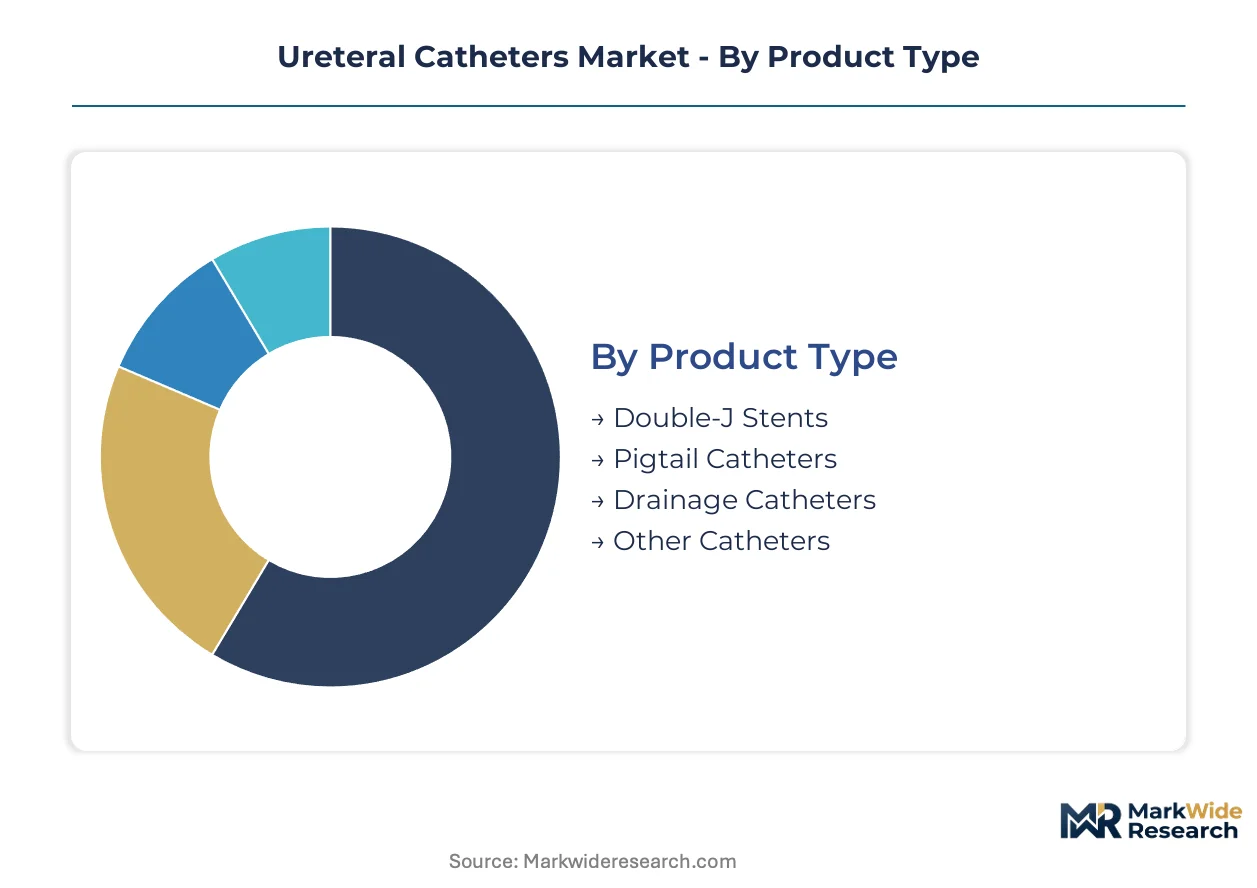
Ureteral catheter purchasing patterns diverge sharply across clinical settings, with replacement frequency and material specifications varying by procedure type and care venue. Understanding segment-level turnover economics enables suppliers to align inventory positioning with reimbursement cycles and sterilization protocols.
Product Type:
Replacement cycles stretch from weeks for temporary drainage devices to months for indwelling stents, creating distinct margin profiles and customer lock-in dynamics across the portfolio.
- Double-J Stents:Biocompatible curl geometry at proximal and distal ends resists migration in the renal pelvis and bladder. Demand concentrates in tertiary hospital systems managing complex stone disease cases, where extended indwell protocols reduce replacement frequency but elevate performance expectations for encrustation resistance.
- Pigtail Catheters:Coiled retention loops enable percutaneous nephrostomy drainage without internal stenting. Ambulatory surgical centers in the United States favor these for temporary post-lithotripsy drainage, driven by same-day discharge mandates and simplified retrieval procedures.
- Drainage Catheters:Large-bore designs accommodate hematuria and pyonephrosis cases requiring high-flow evacuation.
- Other Catheters:Specialty configurations including single-J and straight designs serve niche anatomical variations and pediatric applications.
Double-J Stents anchors the volume base while Pigtail Catheters gains share at the steepest rate.
Material:
Cost tiers separate premium formulations with proprietary coatings from commodity thermoplastics, with allergy protocols and indwell duration requirements driving specification decisions at the point of care.
- Silicone:Inert polymer chains minimize protein adhesion and encrustation during extended indwell periods. United States hospital procurement committees specify silicone for oncology patients requiring months-long drainage, constrained by premium pricing relative to polyurethane alternatives.
- Polyurethane:Thermoplastic elastomer formulations balance tensile strength with thinner wall construction for larger internal lumens. Fastest-expanding adoption in allergy-sensitive patient cohorts as manufacturers phase out latex production lines.
- Latex:Natural rubber formulations persist in cost-constrained settings despite declining regulatory tolerance for allergen exposure.
- Thermoplastic:Injection-molded alternatives offer design flexibility for complex catheter geometries at intermediate price points.
Silicone commands the premium tier while Polyurethane expands most quickly across mid-market accounts.
Application:
Procedure reimbursement codes bundle device costs differently across diagnostic, therapeutic, and postoperative categories, shaping whether catheters are treated as pass-through supplies or profit-center SKUs.
- Urinary Obstruction:Acute decompression of hydronephrosis from stone, stricture, or malignancy represents the core therapeutic indication. United States emergency departments drive spot demand for universal stent inventory, with stone disease prevalence sustaining consistent procedural volume.
- Postoperative Care:Scheduled replacement protocols following ureteroscopy and percutaneous nephrolithotomy generate recurring revenue streams. Bundled payment models in ambulatory settings compress margins while elevating service requirements for logistics and patient education.
- Diagnostic Procedures:Retrograde pyelography and pressure-flow studies utilize temporary catheter placement.
- Other Applications:Fistula management and urinary diversion cases employ specialized catheter configurations.
Postoperative Care generates the highest replacement frequency while Urinary Obstruction delivers the most stable baseline volume.
End User:
Customer type determines sterilization burden, inventory carrying costs, and clinical training requirements, with facility size and procedure specialization creating distinct purchasing workflows.
- Hospitals:Integrated supply chains and in-house sterilization infrastructure support broad product portfolios. United States health systems leverage volume commitments across multiple urology SKUs to extract formulary placement concessions from manufacturers.
- Ambulatory Surgical Centers:Lean inventory models and third-party sterilization leasing favor pre-packaged, single-use kits. Regulatory pressure on reusable scope reprocessing accelerates shift toward disposable catheter systems.
- Clinics:Office-based urology practices prioritize compact inventory with rapid turnover.
- Home Care:Self-catheterization training and direct-to-patient distribution models serve chronic drainage patients.
Hospitals retain the dominant volume position while Ambulatory Surgical Centers climbs the fastest as procedure migration continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where bundled reimbursement and premium material specifications sustain margin premiums, while European markets face compressed returns under EU MDR compliance cost absorption.
United States
Aging demographics and stone disease prevalence drive procedural volumes across hospital systems and ambulatory surgical centers. The FDA 510(k) clearance pathway accelerates commercialization timelines for Class II device innovations. Minneapolis and Boston anchor concentrated medical device clusters where nitinol processing and hydrophilic coating R&D facilities cluster near major urology referral centers.
Germany
Integrated hospital procurement networks and stringent quality protocols sustain demand for premium silicone formulations. The EU MDR imposes strengthened clinical evidence requirements for CE marking that extend approval timelines. Baden-Württemberg hosts specialized thermoplastic elastomer manufacturing facilities serving central European distribution networks.
Japan
Super-aging population demographics and universal health coverage sustain consistent stent replacement protocols. The PMDA maintains rigorous biocompatibility testing standards aligned with ISO 10993 frameworks. Tokyo-Osaka medical device corridors concentrate coating technology development and sterile packaging operations.
India
Government-backed urology center expansion under national health mission programs creates procedural infrastructure growth. The CDSCO regulates medical device imports and domestic manufacturing licensure. Maharashtra and Karnataka host emerging catheter assembly operations targeting cost-optimized export markets.
Brazil
Expanding private health insurance penetration and minimally invasive surgery adoption sustain import-dependent supply chains. ANVISA governs medical device registration with phased convergence toward international standards. São Paulo state concentrates distribution logistics and clinical training centers for Latin American market access.
Ureteral Catheters Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling material science and coating IP. The vendor base organizes around three archetypes: diversified medtech conglomerates with cross-selling infrastructure, mid-sized urology-focused manufacturers with captive nitinol capabilities, and coating-technology licensors monetizing surface chemistry patents. Consolidation pressure intensifies through dual-source procurement mandates from hospital systems and sterilization validation partnerships that favor scaled operators.
Within the diversified conglomerate tier, Teleflex Incorporated and Boston Scientific Corporation exemplify platform leverage strategies that bundle ureteral catheters with complementary urology disposables. Cook Medical LLC anchors the mid-sized specialist archetype through vertically controlled supply chains. Coloplast A/S represents the coating-technology differentiation vector, with hydrophilic surface IP licensing emerging as a secondary revenue stream.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| BD |
| Porges GmbH |
| Cook Medical LLC |
| Olympus Corporation |
| Applied Medical Resources |
| Coloplast A/S |
| Others |
Value Chain & Pricing Dynamics
Single-source nitinol wire dependency from United States and Japanese specialty alloy producers compresses margin flexibility for non-vertically integrated stent manufacturers while simultaneously enforcing three-tier pricing stratification across premium silicone, mid-grade polyurethane, and residual latex formulations.
Pricing Analysis
Hospital procurement committees anchor contract-based pricing structures that bundle ureteral stents with complementary urology disposables, extracting volume guarantees through dual-source frameworks. Price differentiation hinges on hydrophilic coating certification tiers and indwell duration performance, with ambulatory surgical centers exhibiting acute price sensitivity due to lean inventory models and third-party sterilization leasing costs. Cost compression in standard polyurethane tiers is intensifying as manufacturers phase out latex production lines and absorb EU MDR compliance documentation expenses.
Supply Chain Analysis
Medical-grade silicone feedstock draws from Germany, Japan, and United States specialty chemical producers with ISO 10993 biocompatibility certification. Nitinol shape-memory alloy, hydrophilic coating polymers, and ethylene oxide sterilization services constitute critical input dependencies. Single-source vulnerability concentrates in shape-memory wire processing capabilities controlled by vertically integrated competitors. Distribution runs through hospital GPO contracts, ambulatory surgical center third-party logistics partnerships, and regional distributor networks serving outpatient urology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ureteral catheter market sits at a platform-economics inflection where digital health integration and patient-reported outcome ecosystems are redefining value capture beyond device sales.
For Market Incumbents: Pre-empt coating-technology commoditization by deepening in-house nitinol processing capabilities and securing exclusive hydrophilic polymer supply agreements. Lock in ambulatory surgical center formulary placement through pre-sterilized kit bundling before single-use device mandates fully crystallize. For New Entrants and Emerging Players: Establish a beachhead in India's government-backed urology center expansion under national health mission programs, licensing surface coating IP from established European or Japanese technology holders rather than building proprietary R&D infrastructure from inception. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-sized manufacturers with captive material processing capabilities and established CE-marked device portfolios. Watch EU notified body backlog resolution as the signal indicating whether MDR compliance costs accelerate acquisition premiums or trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined Class II clearances accelerate commercialization timelines for silicone-based stent innovations targeting ambulatory surgical centers. |
| Hospital System Partnership | Dual-source procurement frameworks reward integrated supply contracts with formulary placement and volume guarantee concessions. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements demand systematic patient registry participation that reshapes R&D prioritization toward longitudinal data collection. |
| Software Companion Development | Telehealth-enabled remote monitoring platforms open subscription revenue streams for postoperative catheter management protocols. |
| Reimbursement Strategy Alignment | Bundled payment models in United States ambulatory settings compress standalone margins while elevating logistics and patient education service requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with urology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Forecast inputs considered product type segmentation across Double-J stents, pigtail catheters, and drainage configurations; material tiers spanning silicone, polyurethane, and phased latex alternatives; and end-user dynamics across hospital systems, ambulatory surgical centers, and office-based urology practices. CAGRs were derived from procedure migration trends, replacement frequency economics, and reimbursement code bundling evolution across the projection horizon. Stone disease prevalence demographics and minimally invasive surgery infrastructure expansion served as volume drivers.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or ambulatory surgical center construction financing would shift the trajectory. Forecasts assume current FDA 510(k) pathway efficiency and EU MDR implementation timelines. Material shifts in nitinol alloy pricing volatility or ethylene oxide sterilization capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Penile Cancer Market
Urology
Single Use Cystoscope Market
Urology
Varicocele Treatment Market
Urology
North America Transrectal Ultrasound Market
Urology
Suprapubic Catheters Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Global Prostate Health Market
Urology
Hematuria Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Uropathy Treatment Market
Urology
Uraemia Treatment Market
Urology
Urology Disposables Market
Urology
Ureteral Obstruction Market
Urology
Urology Laser Fibers Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market