
 Acquired Cystic Kidney Disease Treatment Market | 2026-2036
Acquired Cystic Kidney Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acquired Cystic Kidney Disease Treatment Market Analytics
Aftermarket service revenue from dialysis machine maintenance and consumable replenishment is narrowing toward original equipment manufacturers with captive supply chains. Novartis International AG leverages its transplant immunosuppression portfolio to sustain recurring prescription volumes in post-transplant care. Teva Pharmaceutical Industries Ltd. competes on generic equivalents of phosphate binders and erythropoiesis-stimulating agents, anchoring its position in cost-sensitive hospital formularies.
Acquired cystic kidney disease treatment encompasses pharmacological management of cyst progression, renal replacement therapy, and surgical intervention for complications arising in native or transplanted kidneys affected by cystic transformation; dialysis modalities remove uremic toxins while maintaining electrolyte balance through semipermeable membrane exchange. Medications dominate current prescribing patterns, though surgical interventions command premium reimbursement due to procedure complexity and specialized nephrology surgical staffing requirements. The home care delivery mode is expanding fastest among end-user categories as payers push for peritoneal dialysis and remote monitoring to reduce inpatient bed utilization.
FDA renal drug guidance and EMA's MDR framework for implantable dialysis access devices both elevate clinical evidence requirements, extending development timelines but raising barriers against inferior competitors. The EU AI Act's risk classification for diagnostic algorithms will reshape how machine-learning tools for cyst monitoring gain market access across European member states. Stakeholders must decide whether to prioritize backward integration into dialysis consumable manufacturing or partner with established device suppliers as service bundling accelerates.
Market Dynamics
Hospital-based dialysis programs are expanding intake capacity faster than nephrology staffing pipelines can fill, creating a structural bottleneck where capital investment outpaces clinical workforce availability. This mismatch between equipment deployment and human capital formation is compressing treatment throughput and forcing payers to accelerate home-based alternatives.
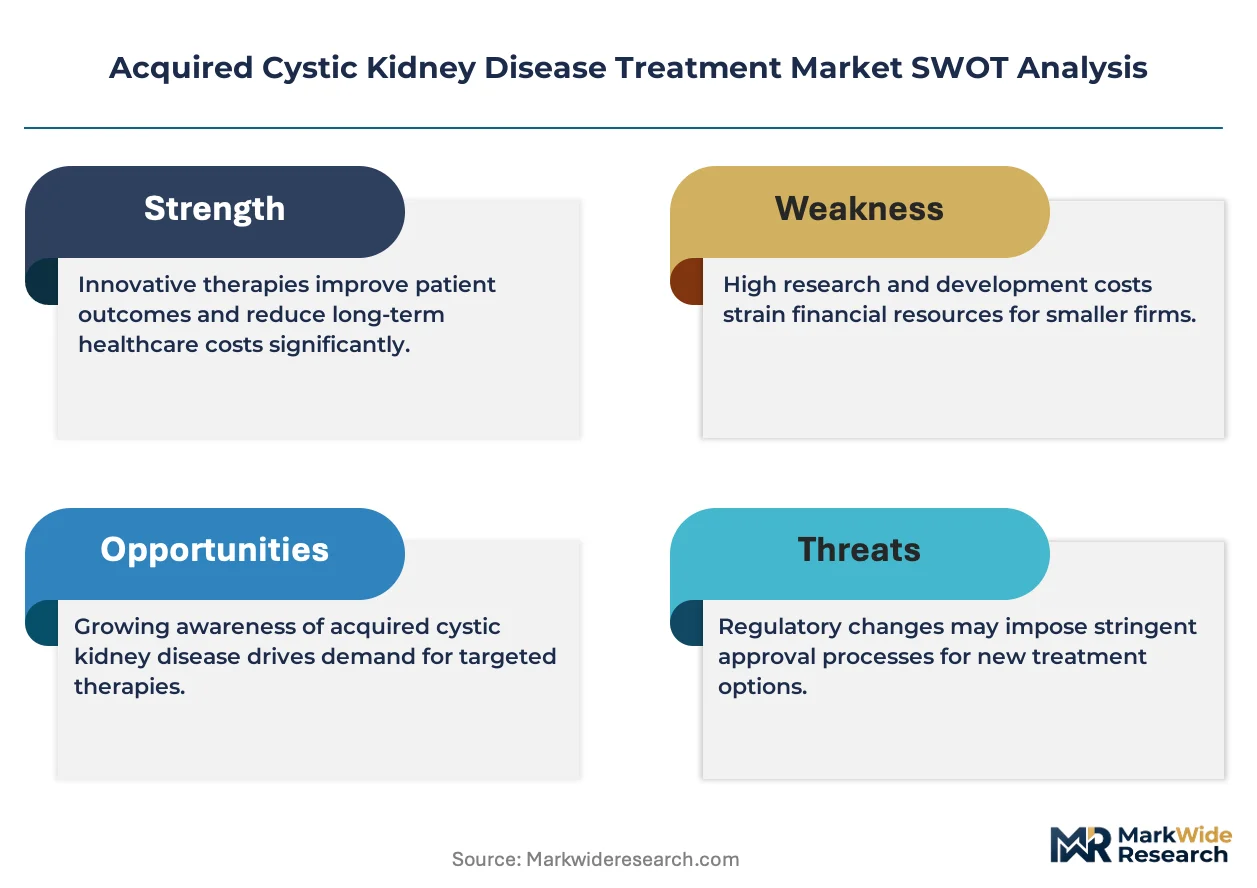
Growth Catalysts
- Medicare reimbursement expansion:Outpatient dialysis reimbursement policies in the United States favor peritoneal and home hemodialysis modalities, redirecting patient volumes away from inpatient beds.
- AI-enabled cyst monitoring:Machine-learning diagnostic algorithms for renal cyst surveillance are gaining accelerated regulatory pathways under the EU AI Act's risk classification framework.
- Transplant immunosuppression protocols:Post-transplant care regimens sustain recurring prescription demand for cyst management in graft kidneys, anchoring pharmaceutical revenue streams.
Market Restraints
- Dialyzer membrane supply concentration:Captive supply chains for semipermeable membranes concentrate among original equipment manufacturers, limiting third-party servicing options.
- FDA evidence requirements:Renal drug guidance elevates clinical trial burdens for novel therapeutics, extending development timelines and capital lockup periods.
- Generic phosphate binder substitution:Cost-sensitive hospital formularies substitute branded mineral metabolism agents with generic equivalents, compressing branded pricing power.
Strategic Opportunities
- Remote patient monitoring infrastructure:Telehealth platforms for home dialysis oversight create new service revenue streams outside traditional clinic billing codes.
- EMA MDR framework alignment:Implantable dialysis access devices face elevated clinical evidence requirements that favor established manufacturers with regulatory dossier depth.
- Surgical nephrology specialization:Cyst complication interventions command premium reimbursement due to procedure complexity and limited specialist availability.
Industry Challenges
- Peritoneal dialysis catheter placement expertise:Interventional nephrology training programs produce insufficient operators to match home dialysis expansion targets.
- Legacy EMR integration:Remote monitoring platforms require costly interface development with entrenched hospital information systems.
- ISO 13485 certification timelines:Dialysis device manufacturers face extended quality management system audits that delay product market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acquired Cystic Kidney Disease Treatment Market |
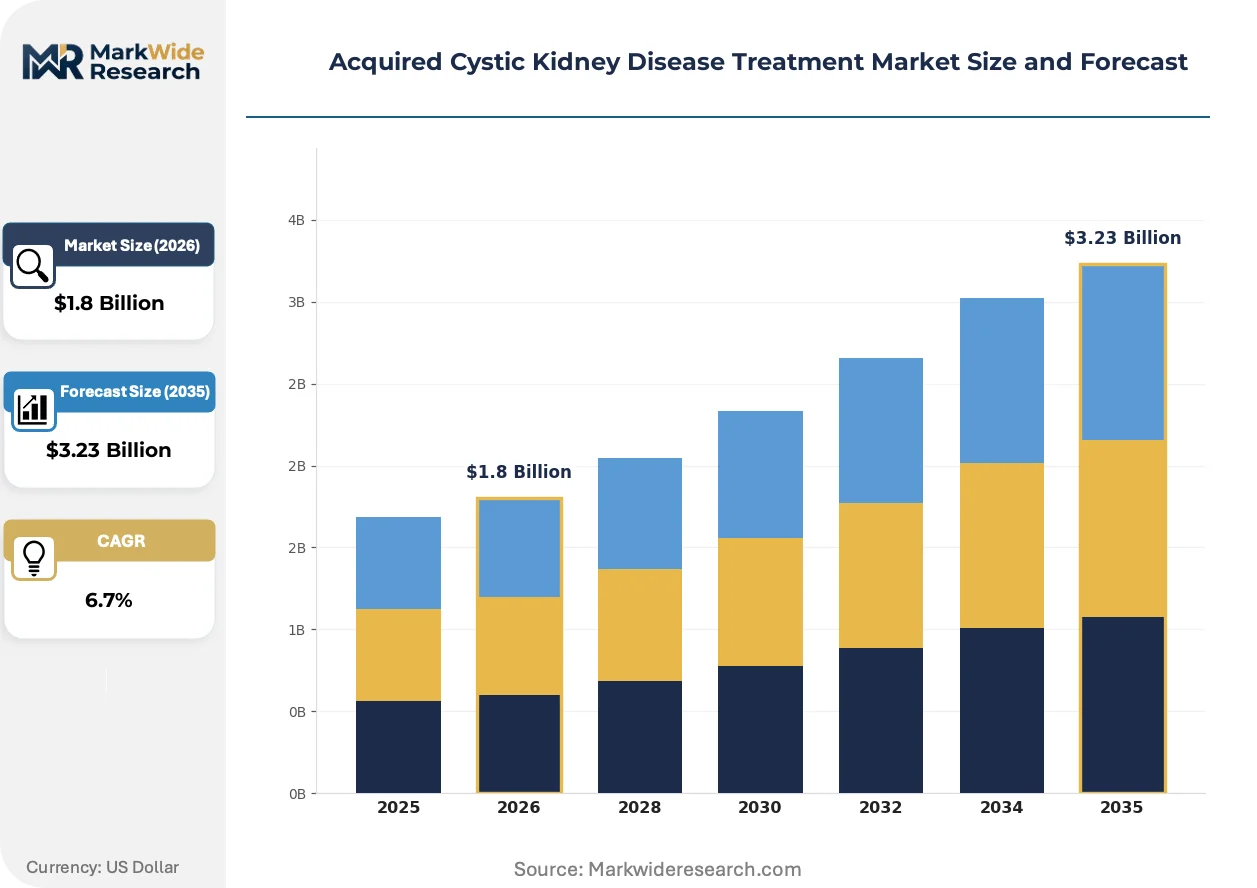
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Dialysis, Surgical Interventions, Dietary Supplements Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Treatment Stage: Acute Phase, Chronic Phase, Pre-transplant, Post-transplant |
| Companies Covered | Novartis International AG, Teva Pharmaceutical Industries Ltd., Otsuka Pharmaceutical Co., Ltd., Vertex Pharmaceuticals Incorporated, Johnson & Johnson, Sanofi, Merck & Co., Inc., Boston Scientific Corporation, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acquired Cystic Kidney Disease Treatment Market Evolving Landscape
Digital infrastructure is virtualizing cyst surveillance workflows, compressing the interval between imaging acquisition and clinical decision. Regulatory frameworks on both sides of the Atlantic are rewriting market access rules for algorithmic diagnostics.
Cloud-based image analysis platforms are virtualizing traditional radiologist interpretation of renal cyst progression. Nephrology departments in integrated delivery networks deploy these tools to triage surveillance intervals. The technology is virtualizing geographic constraints on specialist availability, enabling centralized reading services to cover dispersed dialysis populations.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on machine-learning diagnostic algorithms. Developers must demonstrate clinical validation commensurate with patient harm potential. High-risk cyst monitoring applications face notified body scrutiny that delays European market entry relative to less regulated jurisdictions.
Service unbundling is separating dialysis machine maintenance from capital equipment procurement. Hospital purchasing departments negotiate aftermarket contracts independently of initial device acquisitions. This shift is most pronounced in United States markets where group purchasing organizations leverage volume aggregation to displace manufacturer service monopolies.
Acquired Cystic Kidney Disease Treatment Market Segmentation
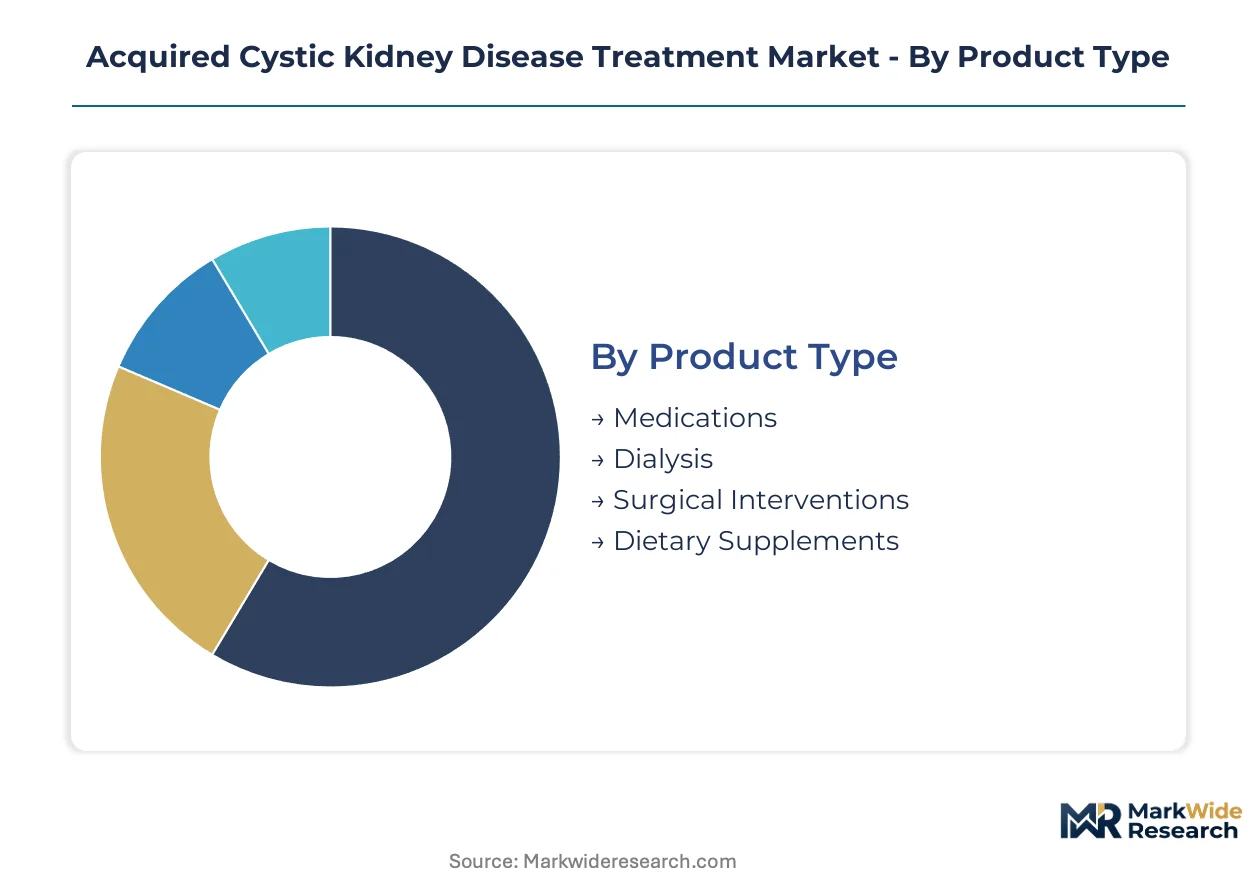
Segmentation in acquired cystic kidney disease treatment reveals how reimbursement pathways and care settings fragment demand across modalities. Each dimension—product, delivery, end user, and treatment phase—carries distinct regulatory and commercial logic that shapes vendor positioning.
Product Type:
Mature pharmaceutical categories coexist with emerging device technologies across this spectrum.
- Medications:Pharmacological agents span phosphate binders, erythropoiesis-stimulating agents, and calcimimetics that modulate mineral metabolism. Hospital formularies in the United States concentrate demand for branded therapies where Medicare Part D reimbursement supports premium pricing.
- Dialysis:Hemodialysis and peritoneal dialysis modalities remove uremic toxins through semipermeable membrane exchange. Home-based peritoneal dialysis is climbing the fastest as CMS reimbursement incentives redirect patient volumes from inpatient facilities.
- Surgical Interventions:Cyst fenestration, nephrectomy, and transplant procedures command specialized nephrology surgical staffing.
- Dietary Supplements:Vitamin D analogs and nutritional adjuncts support mineral balance in pre-dialysis populations.
Medications handle the majority of throughput; Dialysis is gaining share fastest on modality shift incentives.
Delivery Mode:
Cost tiers separate acute inpatient administration from ambulatory and self-managed alternatives.
- Intravenous:Direct vascular delivery of iron replacement, vitamin D, and antibiotics occurs in dialysis suites and infusion centers. United States hospital outpatient departments bill these under Medicare's composite rate, bundling drug cost into treatment reimbursement.
- Oral:Phosphate binders and calcimimetics in tablet or capsule form enable patient self-administration. Retail pharmacy dispensing in the United States dominates volume as Medicare Part D coverage expands oral therapy access.
- Subcutaneous:Erythropoiesis-stimulating agents and immunosuppressants deploy via injection for sustained release.
- Topical:Localized agents address dermatological complications of uremia and immunosuppression.
Oral formulations handle the majority of throughput; Subcutaneous delivery is expanding most quickly on home administration trends.
End User:
Patient acuity and reimbursement environment concentrate volume across facility types.
- Hospitals:Inpatient nephrology units and hospital-based dialysis centers manage acute complications and surgical interventions. United States integrated delivery networks are consolidating these services under centralized quality metrics.
- Clinics:Outpatient dialysis facilities and nephrology practices deliver maintenance therapy. Freestanding clinics in the United States are capturing share as certificate-of-need restrictions ease in select states.
- Home Care:Peritoneal dialysis and remote monitoring shift treatment into residential settings. CMS reimbursement parity with in-center hemodialysis is driving steepest expansion trajectory in this category.
- Rehabilitation Centers:Post-acute facilities manage transitional care for transplant recipients.
Hospitals handle the majority of throughput; Home Care is climbing the fastest on payer cost-containment priorities.
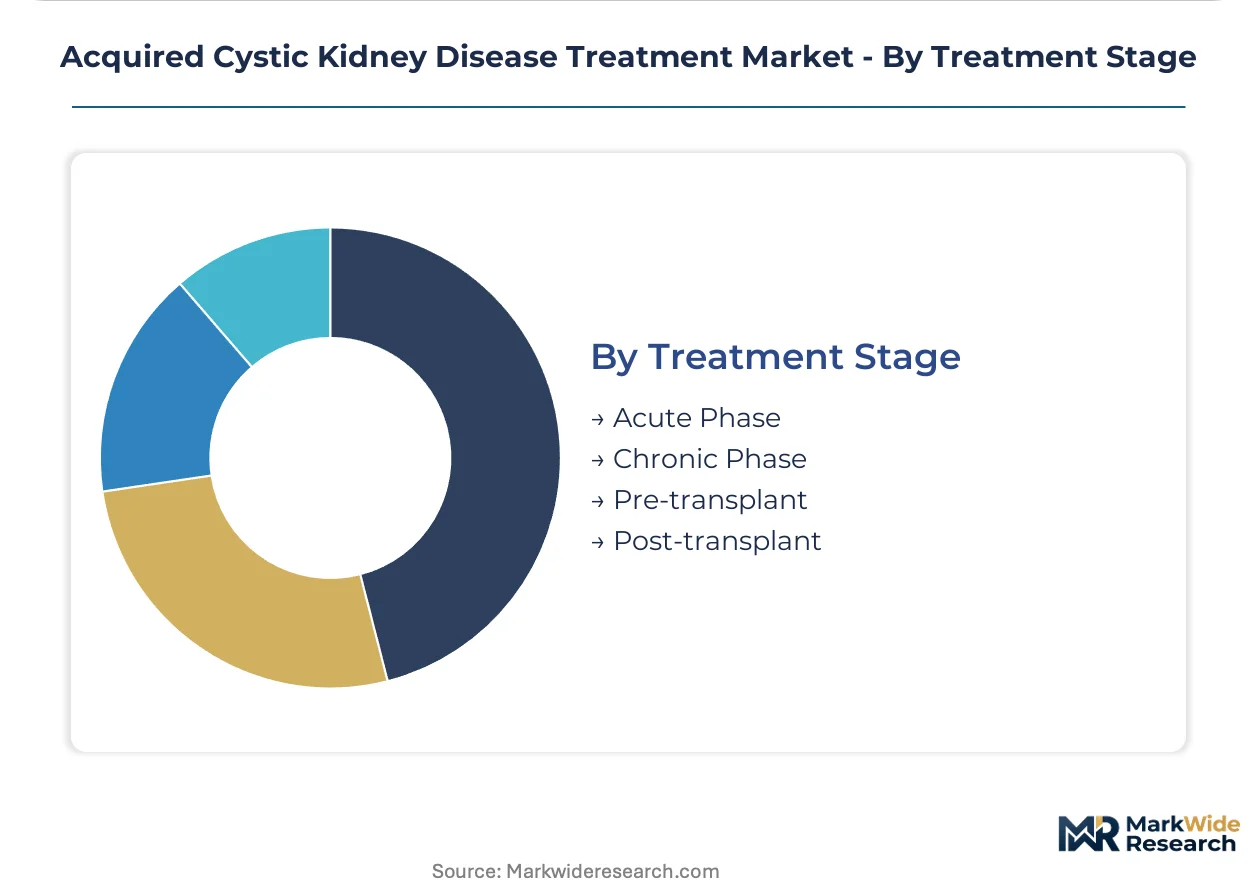
Treatment Stage:
Disease progression and transplant status create distinct therapeutic windows with specialized protocols.
- Acute Phase:Rapid cyst progression and uremic crisis management require immediate intervention. United States emergency departments and observation units concentrate this volume under bundled payment models.
- Chronic Phase:Long-term dialysis dependency and complication prevention dominate ongoing care. Medicare ESRD benefit structures in the United States sustain recurring revenue across years of treatment.
- Pre-transplant:Dialysis bridge therapy and immunological preparation precede graft placement.
- Post-transplant:Immunosuppression maintenance and graft cyst surveillance extend pharmaceutical demand.
Chronic Phase handles the majority of throughput; Post-transplant care is gaining share fastest on extended survival and graft longevity improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes home-based dialysis modalities, while Germany and Japan maintain hospital-centric delivery, and India concentrates on cost-optimized pharmaceutical management.
United States
Medicare reimbursement parity for peritoneal dialysis is redirecting patient volumes from inpatient facilities toward home-based care. FDA accelerated approval pathways for renal therapies compress development timelines for novel therapeutics. The Southeast region, particularly Florida and Georgia, hosts expanding dialysis clinic networks serving retiree populations with elevated chronic kidney disease prevalence.
Germany
Hospital-based dialysis programs retain dominance due to integrated care mandates under statutory health insurance. EMA MDR framework requirements for implantable dialysis access devices elevate clinical evidence standards. The North Rhine-Westphalia industrial corridor concentrates medical device manufacturing for dialyzer membranes and filtration systems.
Japan
Aging demographics sustain demand for chronic phase management and extended post-transplant immunosuppression protocols. PMDA regulatory harmonization with FDA standards streamlines market entry for multinational pharmaceutical sponsors. The Kansai region around Osaka anchors domestic production of erythropoiesis-stimulating agents and mineral metabolism therapies.
India
Cost-sensitive hospital formularies drive substitution toward generic phosphate binders and calcimimetics. CDSCO streamlined approval processes for fixed-dose combination therapies accelerate local manufacturing scale-up. Maharashtra and Gujarat host contract manufacturing organizations supplying active pharmaceutical ingredients to multinational renal therapy developers.
United Kingdom
NHS bundled payment models for renal services incentivize peritoneal dialysis adoption to reduce acute bed utilization. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for AI-enabled cyst monitoring algorithms. The Greater Manchester integrated care system pilots remote patient monitoring infrastructure for home dialysis oversight.
Acquired Cystic Kidney Disease Treatment Market Competitive Landscape
Capability concentration sits with specialty pharmaceutical developers possessing transplant immunosuppression expertise; scale advantage sits with diversified healthcare conglomerates leveraging hospital supply chain relationships. The market structures around three archetypes: integrated nephrology device-pharma hybrids, generic-focused cost leaders, and precision therapy specialists pursuing orphan indications. Dominant competitive moves include backward integration into dialysis consumable manufacturing and strategic partnerships with telehealth platforms for remote monitoring service bundling.
Within the integrated pharmaceutical tier, Novartis International AG and Johnson & Johnson exemplify players leveraging immunosuppression portfolios to sustain recurring prescription volumes in post-transplant care. Teva Pharmaceutical Industries Ltd. occupies a position representing generic-focused competition, anchoring hospital formulary presence through cost-equivalent mineral metabolism agents. Vertex Pharmaceuticals Incorporated sits within the precision therapy archetype, pursuing novel mechanisms for cystic disease modification.
| Leading Market Players |
|---|
| Novartis International AG |
| Teva Pharmaceutical Industries Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Vertex Pharmaceuticals Incorporated |
| Johnson & Johnson |
| Sanofi |
| Merck & Co., Inc. |
| Boston Scientific Corporation |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in United States hospital-based dialysis suites is compressing per-treatment reimbursement rates and forcing suppliers toward captive consumable bundling to defend margins. This utilization-driven pressure reshapes both procurement negotiations and supplier consolidation strategies across the treatment continuum.
Pricing Analysis
Long-term offtake contracts dominate dialysis machine and consumable procurement, with United States group purchasing organizations aggregating hospital system volume to extract price concessions from original equipment manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared devices from CE-marked alternatives and unbranded generics, with price differentiation anchored in regulatory tier and after-sales service bundling. Cost compression in oral phosphate binders is intensifying because Indian contract manufacturers are flooding hospital formularies with generic equivalents. Cost-sensitive hospital systems exhibit highest price sensitivity; post-transplant immunosuppression protocols show lowest sensitivity due to clinical protocol rigidity and graft survival stakes.
Supply Chain Analysis
Upstream feedstock for semipermeable dialyzer membranes concentrates in Germany's North Rhine-Westphalia industrial corridor and Japan's Kansai region around Osaka, with active pharmaceutical ingredient synthesis anchored in Maharashtra and Gujarat, India. Polysulfone and polyethersulfone resins, cellulose derivatives, and synthetic polymer substrates constitute critical material inputs. Single-source vulnerability runs through German membrane suppliers holding proprietary spinning technology for high-flux dialyzers. Distribution runs through hospital supply chains and specialized dialysis service companies with direct-to-clinic logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in this market rest on regulatory entrenchment: FDA and EMA approval dossiers for renal therapies create switching costs that lock hospital formularies and transplant protocols against displacement.
For Market Incumbents: Entrench position through backward integration into dialyzer membrane manufacturing and captive supply of peritoneal dialysis catheters, neutralizing generic substitution threats from Indian API suppliers while building regulatory dossier depth against EMA MDR scrutiny. Expand capacity in Southeast United States dialysis clinic networks serving retiree populations with elevated chronic kidney disease prevalence. For New Entrants and Emerging Players: Build out remote patient monitoring infrastructure for home dialysis oversight, exploiting the penetrable home care delivery segment where CMS reimbursement parity has created service revenue white space outside traditional clinic billing codes. Target telehealth platform partnerships and ISO 13485 certification investment as primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated device-pharma hybrids with transplant immunosupposition portfolios and captive dialysis consumable supply chains. Long-term viability across the analysis window favors manufacturers with regulatory dossier depth and hospital GPO contract penetration. Monitor FDA accelerated approval pathway utilization rates as inflection indicator for pipeline velocity and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dialysis Consumables | Captive membrane supply locks hospital formularies against generic substitution from Indian manufacturers. |
| Telehealth Platform Partnership | Remote monitoring infrastructure captures CMS-reimbursed home dialysis revenue outside clinic billing codes. |
| EMA MDR Framework Alignment | Notified body dossier depth raises barriers against inferior competitors in implantable access devices. |
| Transplant Immunosuppression Portfolio Expansion | Post-transplant protocols sustain recurring prescription volumes with graft survival-driven pricing power. |
| FDA Accelerated Approval Pathway Utilization | Compressed renal therapy timelines enable first-mover positioning in cyst progression modification. |
Research Methodology
Desk research of FDA renal drug guidance documents, EMA MDR technical files, CMS Medicare reimbursement databases, and ClinicalTrials.gov registries preceded structured interviews with dialysis clinic medical directors, hospital nephrology department heads, transplant center procurement managers, and group purchasing organization contract specialists. Secondary validation drew from SEC 10-K filings of listed renal therapy developers, hospital procurement databases, and GPO contract disclosure records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Assumptions held fixed across the projection horizon include Medicare reimbursement parity maintenance for home dialysis modalities and EMA MDR enforcement timelines for implantable devices; variables stress-tested included generic substitution rates in hospital formularies and AI diagnostic algorithm regulatory pathway speeds. Segmentation modeling spanned product type, delivery mode, end-user facility category, and treatment phase progression. CAGRs were derived from patient population epidemiology, treatment modality shift elasticities, and pharmaceutical pricing trajectory synthesis.
Stress conditions across FDA approval timeline variability, dialyzer membrane supply disruption scenarios, and CMS reimbursement policy revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions alongside evolving competitive dynamics in renal therapy development. Cross-checking against CMS Medicare cost report benchmarks and hospital system capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
North America Transrectal Ultrasound Market
Urology
India Urology Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Hydronephrosis Market
Urology
Primary Aldosteronism Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Urology Surgery Supplies Market
Urology
Urology Lasers Market
Urology
Obstructive Uropathy Treatment Market
Urology
Uraemia Treatment Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urology Disposables Market
Urology
Disposable Ureteroscope Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Voiding Cystourethrogram Market