
 Self-Intermittent Catheters Market | 2026-2036
Self-Intermittent Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Intermittent Catheters Market Analytics
Hospital procurement networks is reconfiguring as home care channels gain volume share in catheter distribution. Coloplast leverages its hydrophilic coating expertise to sustain premium positioning across European and North American markets. B. Braun anchors its competitive stance through integrated manufacturing scale that spans raw polymer sourcing to finished sterile packaging. Hollister Incorporated differentiates via specialized pediatric and geriatric catheter formats that command clinician loyalty.
Self-intermittent catheters are single-use sterile tubes, typically 12-18 Fr in diameter, constructed from PVC, silicone, or hydrophilic-coated polymers, designed for periodic bladder drainage by patients with neurogenic or obstructive voiding dysfunction. Hydrophilic catheters dominate value contribution because their pre-lubricated surfaces reduce urethral trauma and infection risk, while standard PVC catheters occupy the high-volume economy tier where cost sensitivity shapes procurement. Home care end users represent the fastest-growing demand pool as reimbursement frameworks shift toward outpatient management and patient self-catheterization training programs expand.
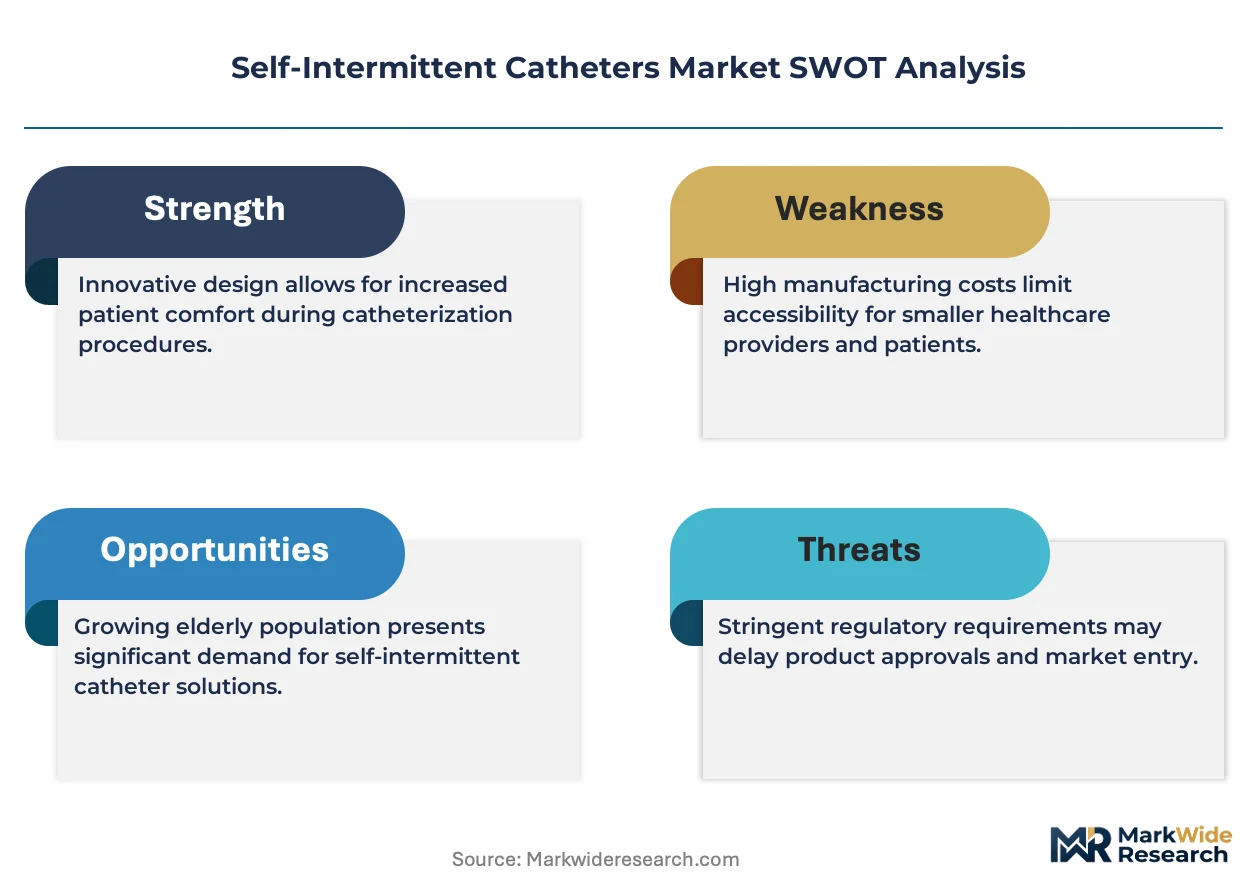
The FDA enforces Class II medical device controls requiring sterility validation and biocompatibility testing under 21 CFR 876.5130, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for catheter CE marking. Japan's PMDA applies QMS ordinances that align with ISO 13485 but impose additional localized sterilization audits, creating compliance complexity for multinational suppliers. Stakeholders must monitor reimbursement code revisions and sterility standard updates as the primary variables that will reshape market access and margin structures.
Market Dynamics
The home care channel is capturing catheter volume as institutional reimbursement contracts and remote patient monitoring infrastructure enable safe self-catheterization outside clinical settings. This demand migration compresses hospital purchasing power while elevating sterile packaging and patient training requirements.
Growth Catalysts
- EU Medical Device Regulation (MDR):Post-market surveillance mandates for CE-marked catheters are accelerating quality differentiation, rewarding manufacturers with robust clinical evidence portfolios.
- Hydrophilic coating chemistry:Pre-lubricated polymer surfaces reduce urethral trauma incidence, expanding adoption among first-time self-catheterizers and pediatric populations.
- Japan's aging demographic:Expanding neurogenic bladder prevalence among elderly populations is driving PMDA-registered catheter procurement through home medical equipment channels.
Market Restraints
- PVC resin price volatility:Standard catheter margins compress when petrochemical feedstock costs spike, squeezing economy-tier producers without polymer backward integration.
- Sterile packaging concentration:Tyvek and medical-grade film supply clusters in Southeast Asia create single-source vulnerability for finished device sterilization.
- Antibiotic-impregnated catheter substitution:Silver-alloy and nitrofurazone-coated indwelling alternatives compete for hospital contracts in infection-prone patient cohorts.
Strategic Opportunities
- Germany's outpatient reimbursement expansion:The G-DRG system is broadening catheter coverage for home-based intermittent catheterization, opening volume capture for trained patient support services.
- Pediatric hydrophilic formats:6-10 Fr diameter catheters with color-coded insertion aids address an underserved neurogenic bladder segment in congenital spinal conditions.
- Telehealth-integrated training platforms:Video-guided self-catheterization protocols reduce clinical visit dependency and expand addressable rural patient populations.
Industry Challenges
- ISO 13485 auditor capacity:Sterile medical device quality management certification backlogs delay new market entrants by 8-14 months in key manufacturing regions.
- Legacy ERP integration:Home care distributors struggle to merge catheter lot-traceability systems with hospital procurement platforms for seamless reimbursement documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Intermittent Catheters Market |
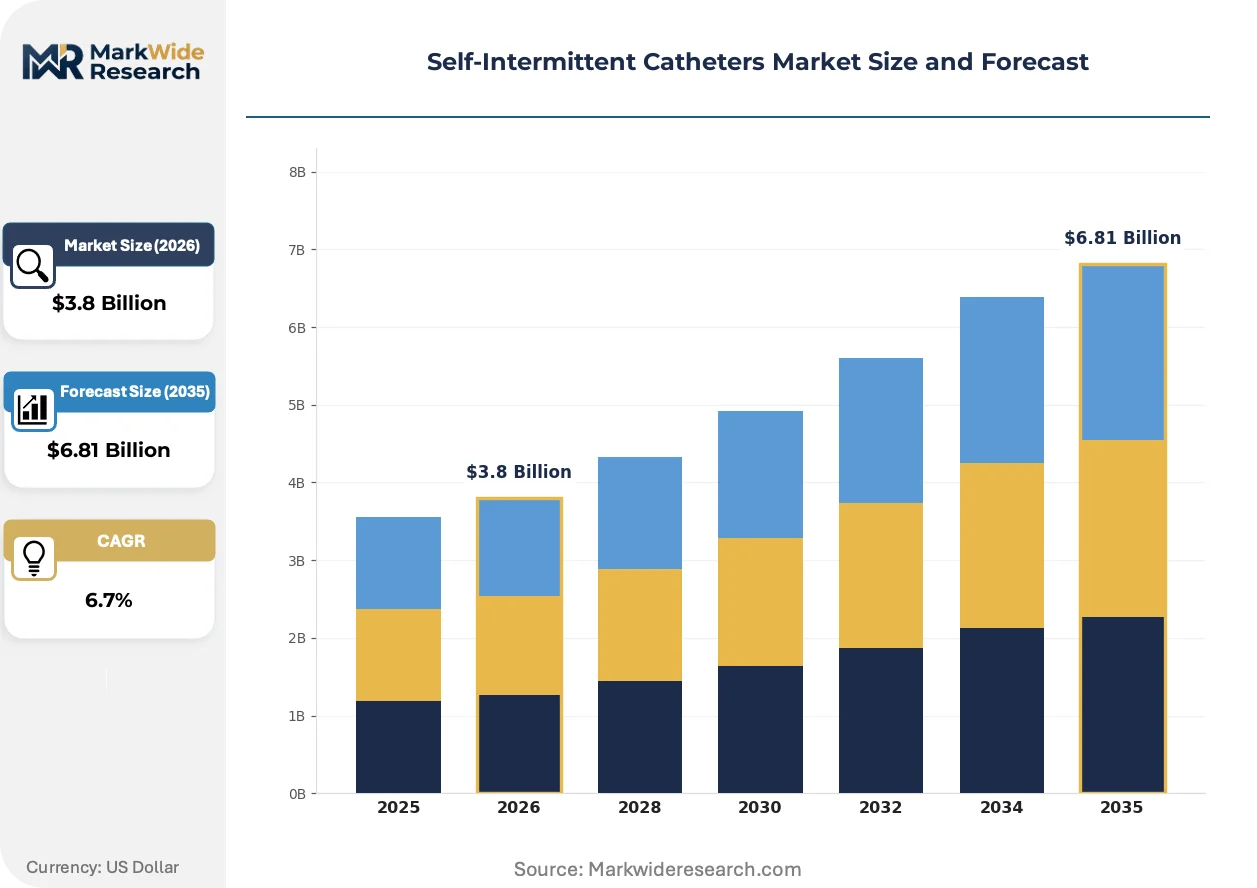
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-System Catheters, Hydrophilic Catheters, Standard Catheters, Digital Catheters End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Material: Latex, PVC, Silicone, Teflon Sizes: 12 Fr, 14 Fr, 16 Fr, 18 Fr |
| Companies Covered | Coloplast, B. Braun, Hollister Incorporated, ConvaTec, Teleflex Incorporated, Becton Dickinson and Company, Cook Medical, Wellspect HealthCare, Cure Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Intermittent Catheters Market Evolving Landscape
Catheter technology is converging around patient safety and procedural simplicity, with coating science and connected health infrastructure reshaping competitive differentiation. Regulatory evidence requirements and channel economics are accelerating material and format innovation cycles.
Smart catheter systems embedding pressure sensors and Bluetooth connectivity are hybridizing traditional drainage hardware with remote monitoring platforms. Urology clinics in the United States are piloting these devices for spinal cord injury patients requiring adherence tracking. This convergence is compressing the boundary between disposable supplies and digital therapeutics, forcing manufacturers to build software validation capabilities alongside polymer expertise.
The FDA's 21 CFR 876.5130 sterility validation updates are tightening biocompatibility documentation for hydrophilic-coated polymers. Manufacturers must now submit expanded cytotoxicity and sensitization data for pre-lubricated surfaces. European suppliers with existing MDR clinical evidence portfolios are responding faster than US-centric competitors, capturing early mover advantage in premium catheter segments.
Patient direct-purchasing through durable medical equipment (DME) channels is fragmenting traditional hospital-centric distribution. Medicare Part B reimbursement for self-catheterization supplies now flows through home health agencies rather than acute care purchasing consortia. This reconfiguration is most visible in Florida and Arizona retirement corridors, where urology practices are establishing captive DME affiliates to capture catheter margin.
Self-Intermittent Catheters Market Segmentation
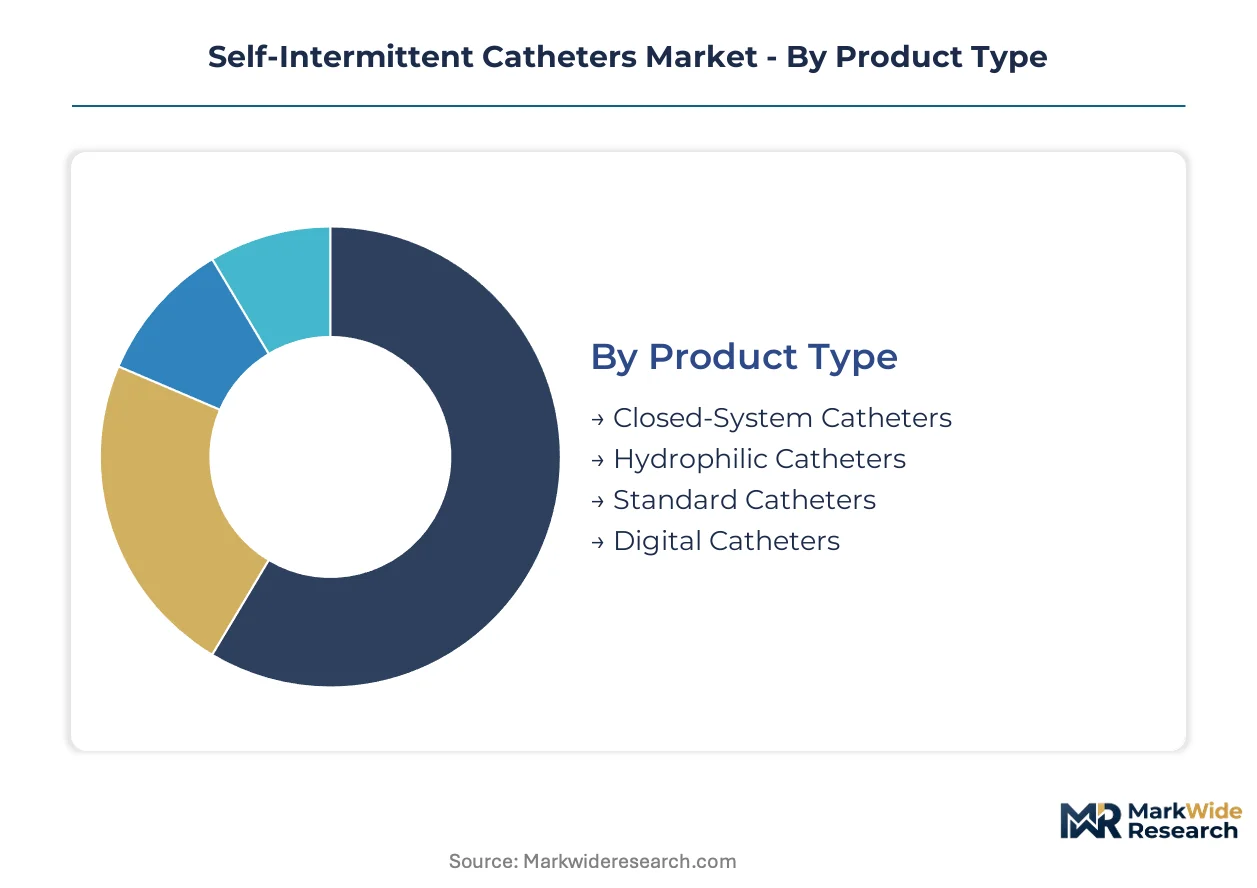
Self-intermittent catheter purchasing patterns fragment sharply across clinical versus home settings, with product format and material specifications determining reimbursement eligibility and patient adherence rates. Understanding segment turnover velocity helps suppliers align sterile packaging investments with actual consumption rhythms across institutional and retail channels.
Product Type:
Cycle times vary dramatically by sterility assurance level and lubrication chemistry, with pre-lubricated formats turning over faster in home care while closed-system units linger in hospital consignment inventory.
- Hydrophilic Catheters:Pre-lubricated polymer surfaces eliminate separate gel application, reducing urethral trauma incidence in spinal cord injury patients across United States and German home care programs. Demand concentrates in pediatric and first-time self-catheterizer populations where friction reduction drives adherence.
- Closed-System Catheters:Integrated collection bags and sterile insertion sheaths target infection-prone hospital inpatients and nursing home residents with limited hand dexterity. United States acute care networks specify these for CAUTI-reduction protocols despite per-unit cost premiums.
- Standard Catheters:Unlubricated PVC tubes requiring manual gel application dominate price-sensitive institutional tenders in developing markets and veteran administration facilities.
- Digital Catheters:Bluetooth-enabled pressure sensors and flow meters embedded in catheter lumens serve spinal cord injury monitoring programs in Japanese university hospitals and United States veterans affairs telehealth pilots.
Standard catheters anchor the volume base while digital catheters gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital purchasing from patient-directed home care procurement, with reimbursement mechanism determining format selection and brand loyalty intensity.
- Home Care:Medicare Part B and German statutory health insurance reimbursement for self-catheterization supplies drives fastest volume expansion, with patients selecting hydrophilic formats through durable medical equipment dealers in Florida and Arizona retirement corridors.
- Hospitals:Group purchasing organization contracts favor closed-system units for inpatient urology and neurosurgical wards, with CAUTI penalty exposure justifying premium procurement in United States acute care networks.
- Long-Term Care Facilities:Medicaid-funded nursing homes balance infection control mandates against per-diem reimbursement constraints, standardizing on mid-tier hydrophilic catheters with bulk packaging.
- Rehabilitation Centers:Spinal cord and stroke recovery programs in German neurological clinics and Japanese rehabilitation hospitals train patients on technique-specific formats before discharge to home care.
Hospitals retain the highest per-patient spend while home care expands most quickly.
Material:
Application-specific biocompatibility requirements and sterilization method compatibility shape material selection, with latex sensitivity screening and hydrophilic coating chemistry driving substitution patterns.
- PVC:Rigid polymer construction supports standard catheter economics, with phthalate-plasticized formulations dominating high-volume tenders in United States veteran administration and Indian public hospital procurement.
- Silicone:Soft, thermoset elastomer reduces urethral irritation in long-term intermittent users and latex-allergic patients, commanding premium positioning in German and Japanese home medical equipment channels.
- Latex:Natural rubber construction persists in cost-minimized emerging market segments despite Type I hypersensitivity liability, with powder-free processing mandated by FDA device labeling requirements.
- Teflon:Polytetrafluoroethylene coating applied to stainless steel or nylon substrates enables low-friction insertion in specialized urological procedures, occupying niche hospital urology suite applications.
PVC anchors the volume base while silicone gains share at the steepest rate.
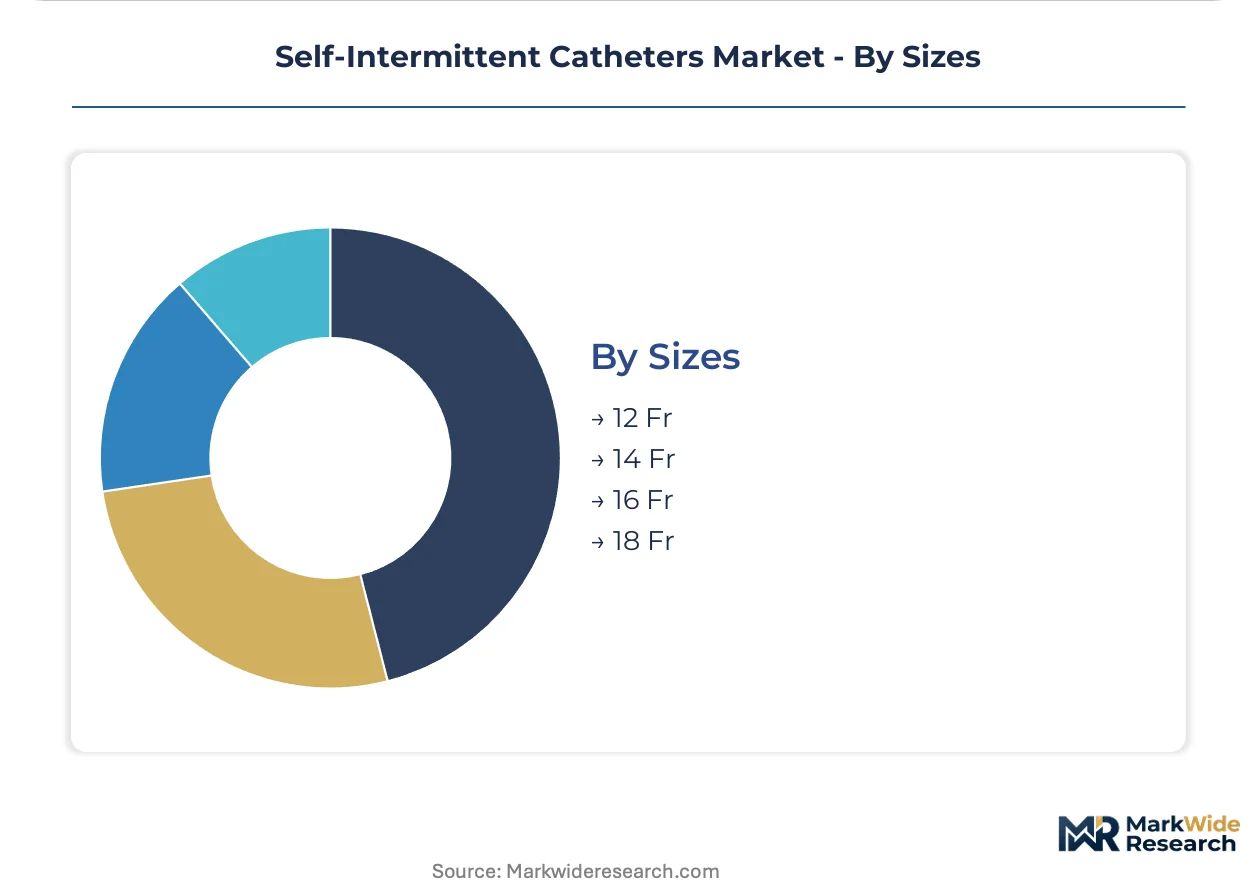
Sizes:
Volume concentration tracks anatomical variation and clinical indication, with pediatric and bariatric extremes commanding manufacturing complexity premiums against standardized adult formats.
- 14 Fr:Mid-range diameter suits adult male and female urethral anatomy in routine neurogenic bladder management, representing the procurement default for United States Medicare Part B reimbursement catalogs.
- 16 Fr:Larger lumen accommodates higher viscosity urine and mild prostatic obstruction in elderly male populations, with German urology practices specifying this format for benign prostatic hyperplasia patients transitioning to self-catheterization.
- 12 Fr:Smaller diameter serves pediatric populations and adult females with urethral stricture history, requiring specialized hydrophilic coating formulations to maintain flow rates.
- 18 Fr:Maximum standard diameter addresses hematuria management and post-surgical irrigation needs in hospital urology wards, with limited home care applicability due to insertion discomfort.
14 Fr anchors the volume base while 12 Fr gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German home medical equipment channels command premium catheter pricing power that United States Medicare Part B reimbursement frameworks cannot match, creating a transatlantic margin asymmetry that shapes manufacturer geographic prioritization.
United States
Medicare Part B reimbursement for self-catheterization supplies drives volume through Florida and Arizona retirement corridors, where urology practices establish captive durable medical equipment affiliates. The FDA enforces Class II device controls under 21 CFR 876.5130 requiring sterility validation and biocompatibility testing. Minnesota and Massachusetts host catheter manufacturing clusters where suppliers integrate hydrophilic coating chemistry with sterile packaging operations.
Germany
The G-DRG system broadens catheter coverage for home-based intermittent catheterization, expanding the addressable patient base beyond acute care settings. EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking, accelerating quality differentiation among suppliers. Baden-Württemberg and Bavaria concentrate catheter distribution networks serving neurological rehabilitation clinics that train patients before discharge.
Japan
Expanding neurogenic bladder prevalence among elderly populations drives PMDA-registered catheter procurement through home medical equipment channels. The PMDA applies QMS ordinances aligning with ISO 13485 but imposes additional localized sterilization audits, creating compliance complexity. Tokyo and Osaka metropolitan areas concentrate urology specialty practices piloting Bluetooth-enabled catheter monitoring for spinal cord injury patients.
United Kingdom
NHS England procurement frameworks favor closed-system catheters for infection reduction in hospital settings, while community continence services expand hydrophilic format access. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UKCA marking pathways. The Oxford-Cambridge corridor hosts medical device innovation clusters developing pediatric catheter formats for congenital spinal conditions.
India
Phthalate-plasticized PVC catheters dominate public hospital tenders where cost sensitivity shapes procurement decisions for neurogenic bladder management. The CDSCO regulates medical device imports under the Drugs and Cosmetics Act, with quality management system requirements intensifying for sterile device registration. Ahmedabad and Mumbai host polymer processing clusters supplying catheter raw materials to domestic and export markets.
Self-Intermittent Catheters Market Competitive Landscape
Integrated polymer-to-device manufacturers and specialized coating technology firms split the market into distinct capability tiers. The vendor base concentrates around sterile packaging expertise and hydrophilic surface chemistry, with three archetypes dominating: backward-integrated polymer processors, coating technology specialists, and distribution-anchored brand aggregators. Competitive moves center on M&A targeting sterile packaging capacity and strategic partnerships with home care distributors.
Within the integrated manufacturing tier, Coloplast and B. Braun exemplify archetypes that span raw material sourcing through finished sterile packaging. Hollister Incorporated occupies a position among specialized format developers serving pediatric and geriatric segments. These three anchors represent distinct strategic postures: European coating-chemistry leadership, German manufacturing scale, and North American clinical-format specialization.
| Leading Market Players |
|---|
| Coloplast |
| B. Braun |
| Hollister Incorporated |
| ConvaTec |
| Teleflex Incorporated |
| Becton Dickinson and Company |
| Cook Medical |
| Wellspect HealthCare |
| Cure Medical |
| Others |
Value Network & Pricing Analysis
Ahmedabad and Mumbai polymer processing clusters anchor global catheter raw material supply, with their PVC resin and medical-grade compound capacity directly conditioning margin structures for finished device manufacturers across premium and economy tiers.
Pricing Analysis
The customization-premium spread separates hydrophilic-coated catheters from standard PVC formats by a substantial multiple, with coating chemistry sophistication and sterile packaging assurance as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA sterility validation tiers and ISO 13485 certification depth. Cost compression in the PVC economy tier is intensifying because petrochemical feedstock volatility squeezes converters without backward integration into polymer sourcing. Hospital group purchasing organizations exhibit the lowest price sensitivity due to CAUTI penalty exposure, while Medicaid-funded nursing homes face acute per-diem constraints that favor bulk-packaged mid-tier procurement.
Supply Chain Analysis
Contract manufacturing concentration for sterile catheter finishing rests with specialized medical device EMS providers in Malaysia, Costa Rica, and Ireland that hold FDA-registered and ISO 13485-certified cleanroom capacity. Raw material dependencies center on medical-grade PVC resin, hydrophilic polymer coatings, and Tyvek sterilization packaging sourced from concentrated Southeast Asian suppliers. Single-source vulnerability in medical-grade film and sterilization barrier supply creates exposure to regional logistics disruption or regulatory hold. Distribution runs through durable medical equipment dealers and hospital group purchasing organization contracts, with home care channel expansion fragmenting traditional acute care procurement concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics integration is transforming catheter hardware into connected health platforms, with Bluetooth-enabled adherence monitoring and telehealth-integrated training protocols creating new interoperability requirements that reshape competitive economics.
For Market Incumbents: Insulate premium positioning by deepening captive hydrophilic coating chemistry capabilities and securing sterile packaging capacity through strategic supplier partnerships or in-house production expansion. Antibiotic-impregnated indwelling catheter substitutes threaten intermittent catheter hospital contracts, requiring accelerated clinical evidence generation for infection prevention outcomes. Certification investment in MDR-compliant post-market surveillance systems represents the critical defensive lever for European market retention.
For New Entrants and Emerging Players: Build out pediatric hydrophilic catheter formats in the 6-10 Fr diameter range, an underserved segment where congenital spinal condition prevalence creates specialized demand with limited incumbent focus. Telehealth-integrated self-catheterization training platforms offer the most penetrable white-space entry point, reducing clinical visit dependency for rural patient populations. A direct-to-patient subscription model through durable medical equipment dealer partnerships provides the optimal go-to-market angle bypassing hospital purchasing consortium gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with underoptimized catheter divisions lacking hydrophilic coating R&D integration or home care channel infrastructure. Long-term viability over the next decade hinges on software validation capabilities alongside polymer expertise as smart catheter systems hybridize hardware with digital therapeutics. Acquisition target archetypes include coating technology specialists with existing MDR clinical evidence portfolios. The signal to watch is FDA 21 CFR 876.5130 sterility validation update timing, which will accelerate compliance cost burdens favoring scaled players.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrophilic Coating R&D Expansion | Pre-lubricated surfaces reduce urethral trauma and expand pediatric adoption in spinal cord injury populations. |
| Sterile Packaging Capacity Acquisition | Tyvek and medical-grade film supply concentration in Southeast Asia creates single-source vulnerability for finished device sterilization. |
| Telehealth Training Platform Development | Video-guided self-catheterization protocols reduce clinical visit dependency and expand rural patient access. |
| Pediatric Format Portfolio Extension | 6-10 Fr diameter catheters with color-coded insertion aids address underserved congenital spinal condition segments. |
| MDR Clinical Evidence Investment | Post-market surveillance mandates accelerate quality differentiation rewarding manufacturers with robust evidence portfolios. |
Research Methodology
A spread of perspectives from urology clinicians, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and durable medical equipment distributors converged on the working assumptions underlying volume and value estimates. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored the analytical framework.
Demand-supply-balance framing structured the forecast approach across the analysis window, with segmentation dimensions spanning product type, end user channel, material composition, and diameter specification. Hydrophilic coating adoption curves, home care reimbursement expansion rates, and sterile packaging capacity constraints served as industry-specific forecast inputs. CAGRs derived from fitted growth curves applied to addressable patient populations and per-patient consumption intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital therapeutics entrants or major polymer backward integration plays would shift outcomes beyond modeled ranges. Regulatory timeline acceleration, particularly FDA sterility validation updates or EU MDR enforcement intensity, represents the primary revision risk. Quarterly review of reimbursement code revisions, sterile packaging supply indicators, and coating chemistry patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Botulinum Toxin in Urology Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Uropathy Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Ureterorenoscopes Market
Urology
Disposable Ureteroscope Market
Urology
Nocturia Market
Urology
Europe Bladder Disorders Market
Urology
Penile Cancer Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Pyelonephritis Treatment Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Bladder Scanner Market