
 Pyelonephritis Treatment Market | 2026-2036
Pyelonephritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pyelonephritis Treatment Market Analytics
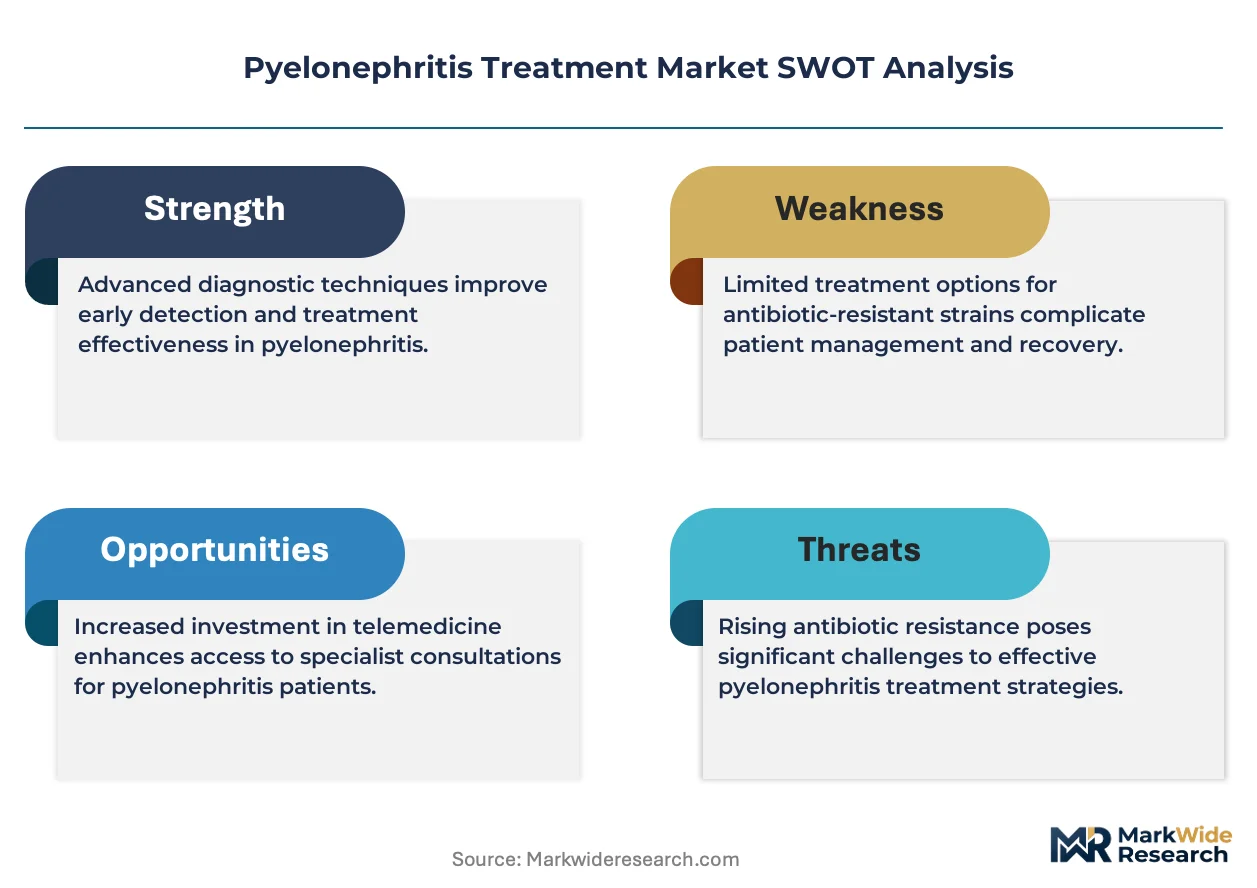
Hospital formulary contracting is rewriting how pyelonephritis therapies capture value across the acute care chain. GlaxoSmithKline leverages its established anti-infective infrastructure to sustain broad institutional access. Spero Therapeutics anchors its position through oral beta-lactam development for resistant pathogens. Shionogi competes on the strength of its fluorocycline platform targeting multidrug-resistant gram-negative infections.
Pyelonephritis treatment encompasses antimicrobial and adjunctive therapeutic interventions directed at renal parenchyma and upper urinary tract infection, typically requiring agents with adequate renal tissue penetration and activity against Enterobacterales, Pseudomonas, and enterococcal species. The primary purpose is eradication of causative organisms, prevention of renal abscess or sepsis progression, and reduction of recurrent infection burden. Antibiotics dominate the product landscape, with oral formulations gaining structural ground against intravenous-only regimens as outpatient parenteral therapy programs expand. Injectable delivery modes retain margin concentration in severe or complicated cases requiring hospitalization, while home healthcare channels represent the fastest-growing end-user segment as payers push for site-of-care migration.
The FDA's Qualified Infectious Disease Product designation and the EMA's priority medicines scheme create accelerated review pathways that shape development investment and commercial sequencing for novel agents. BIS pharmacovigilance requirements in India and CDSCO manufacturing standards further condition market access across production and distribution stages. Stakeholders must monitor resistance surveillance data and reimbursement policy shifts to align portfolio priorities with evolving pathogen epidemiology and treatment guidelines.
Market Dynamics
Hospital formulary contracting is compressing commercial timelines for novel pyelonephritis agents, forcing developers to secure institutional access before FDA approval rather than after launch.
Growth Catalysts
- Qualified Infectious Disease Product designation:The FDA's accelerated review pathway shortens development cycles for agents targeting carbapenem-resistant Enterobacterales. Developers secure priority vouchers that transfer at premium valuations.
- Outpatient parenteral therapy expansion:United States payers are reimbursing home infusion for complicated urinary tract infections. This channel shift expands addressable volume beyond traditional inpatient settings.
- Resistance surveillance integration:The CDC's National Healthcare Safety Network feeds real-time pathogen data into hospital stewardship protocols. Prescribers demand agents aligned with local resistance profiles.
Market Restraints
- Active pharmaceutical ingredient concentration:Carbapenem and cephalosporin raw materials concentrate among Chinese and Indian manufacturers. Geopolitical friction threatens supply continuity for Western formulators.
- Reimbursement compression:Medicare's diagnosis-related group payments cap inpatient antibiotic spend. Hospitals resist premium-priced novel agents within fixed reimbursement envelopes.
- Generic ciprofloxacin substitution:Oral fluoroquinolone availability at sub-dollar per-dose pricing limits uptake of newer beta-lactam alternatives in uncomplicated cases.
Strategic Opportunities
- Oral beta-lactam penetration:Underdeveloped markets in Brazil and Mexico lack outpatient intravenous infrastructure. Oral agents with gram-negative coverage capture site-of-care migration.
- Companion diagnostic pairing:Rapid resistance phenotyping at point-of-care enables targeted therapy selection. Integrated test-and-treat protocols command formulary preference.
- EMA priority medicines scheme:Accelerated assessment for multidrug-resistant infection therapies opens European access ahead of standard timelines. Early rapporteur engagement shapes development.
Industry Challenges
- Specialized infectious disease trial infrastructure:Phase III pyelonephritis studies require renal tissue penetration validation and microbiological endpoint expertise. Contract research organizations with proven gram-negative trial execution command scarcity premiums.
- Pharmacovigilance signal management:Nephrotoxicity and neurotoxicity surveillance for beta-lactam agents demands dedicated safety databases. Post-marketing commitment timelines extend regulatory resource drain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyelonephritis Treatment Market |
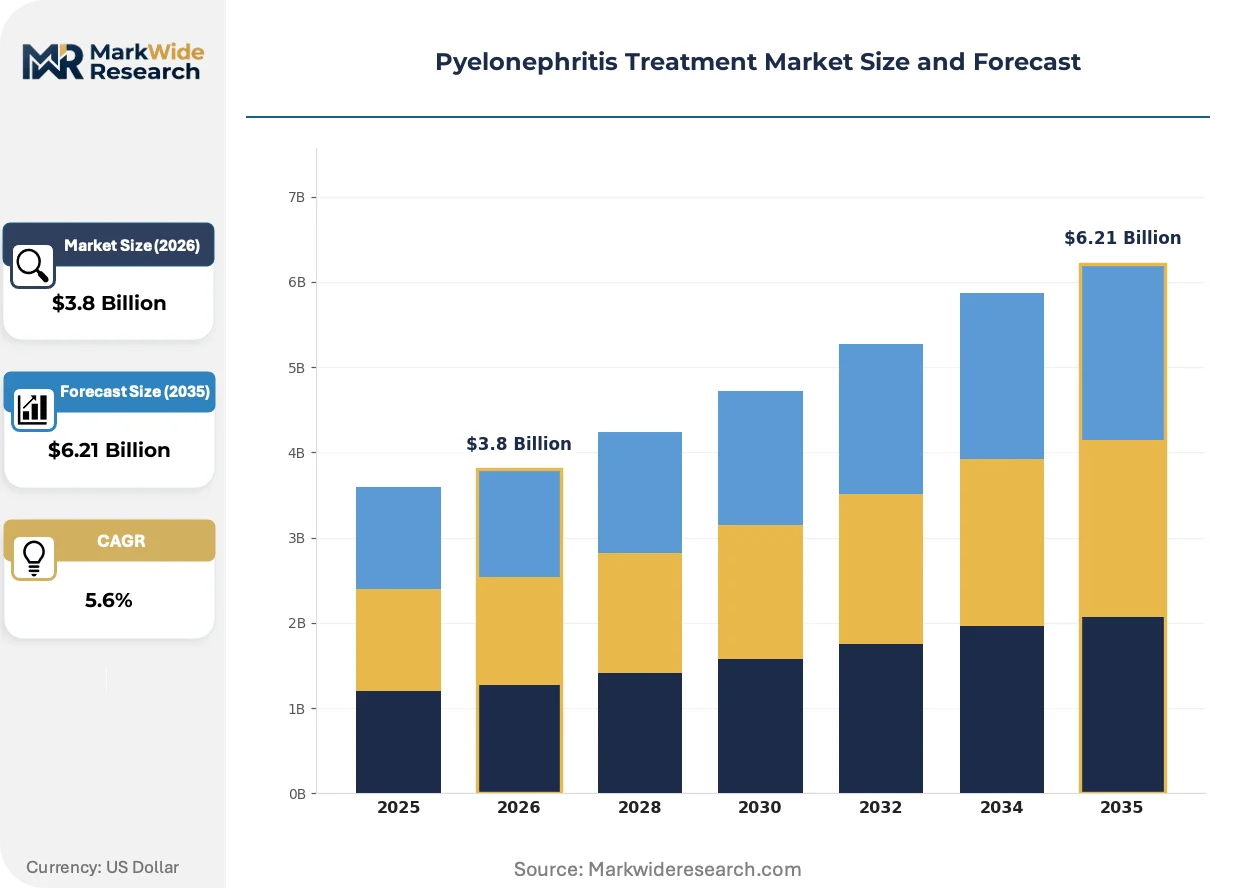
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antipyretics, Analgesics, Supportive Care Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Treatment Stage: Acute, Chronic, Preventive, Post-treatment |
| Companies Covered | Venatorx Pharmaceuticals, MerLion Pharmaceuticals, Spero Therapeutics, Evopoint Biosciences, Shionogi, Wockhardt, Allecra Therapeutics, GlaxoSmithKline, Iterum Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyelonephritis Treatment Market Evolving Landscape
Novel renal-penetrating formulations and site-of-care economics are restructuring how pyelonephritis therapies capture value across the acute-to-ambulatory continuum.
Extended-infusion beta-lactam dosing algorithms are optimizing time-above-MIC pharmacokinetics for resistant gram-negative eradication. Critical care pharmacists at major academic medical centers are adopting software-guided infusion protocols. Continuous renal replacement therapy compatibility is rendering obsolete traditional intermittent bolus administration in septic patients.
The EMA's revised clinical trial guidance for complicated urinary tract infections now mandates renal tissue concentration data alongside standard plasma pharmacokinetics. European developers are integrating microdialysis substudies into Phase II protocols. This requirement compresses development timelines for agents with documented parenchymal penetration.
Integrated pharmacy-benefit carve-outs for specialty anti-infectives are separating reimbursement from medical benefit budgets. Large United States health systems are contracting directly with manufacturers for outpatient parenteral therapy bundles. This channel restructuring concentrates purchasing influence among pharmacy executives rather than infectious disease physicians.
Pyelonephritis Treatment Market Segmentation
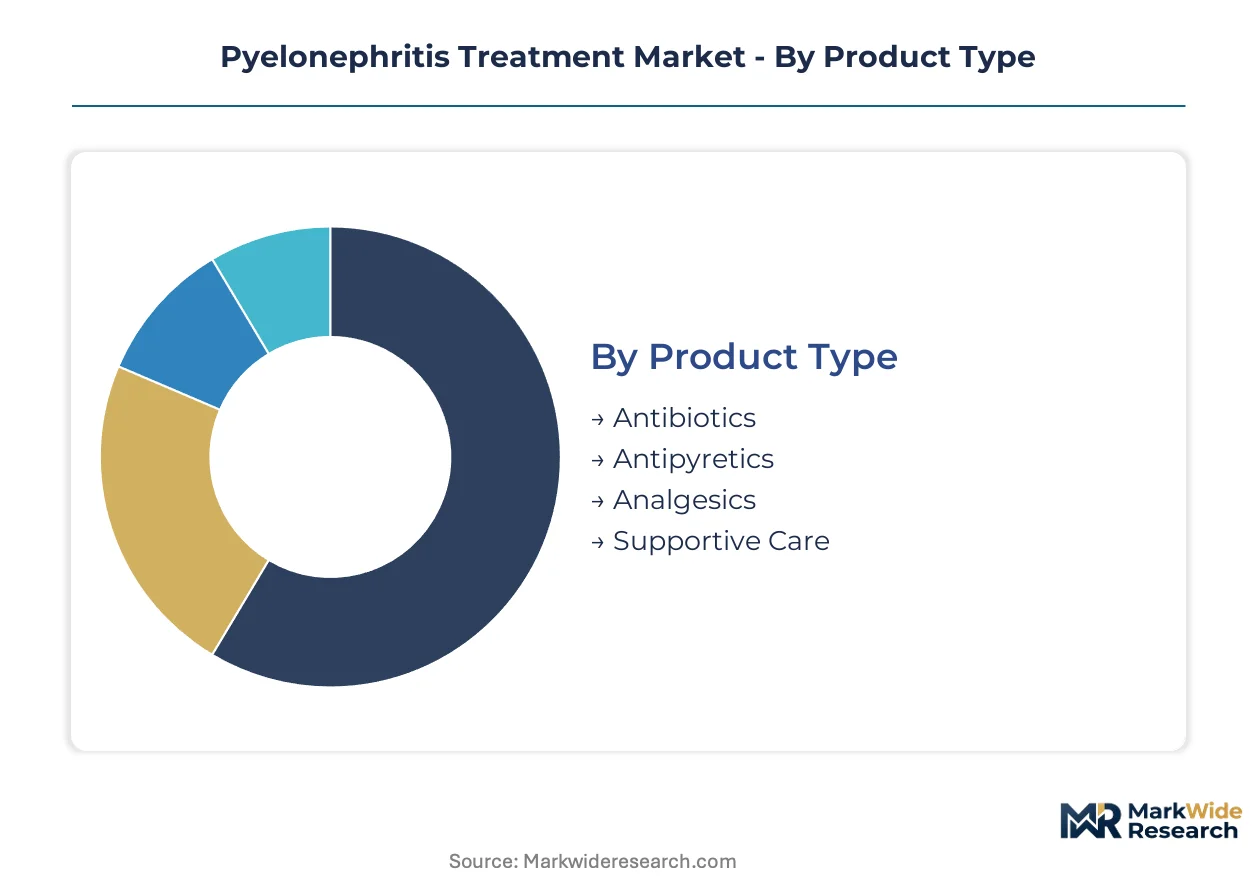
Pyelonephritis treatment segmentation reflects divergent clinical workflows across acute hospitalization and ambulatory migration. Product and delivery mode choices hinge on infection severity, resistance profiles, and payer site-of-care incentives rather than physician preference alone.
Product Type:
Cycle times vary sharply: antibiotics turn over quarterly as resistance shifts, while supportive care products maintain year-long formulary positions.
- Antibiotics:Beta-lactams, fluoroquinolones, and carbapenems constitute the therapeutic backbone, with renal tissue penetration determining agent selection. Hospital formularies in the United States prioritize FDA Qualified Infectious Disease Product-designated agents as carbapenem-resistant Enterobacterales prevalence climbs.
- Antipyretics:Acetaminophen and NSAID formulations manage fever control as adjunctive therapy. Outpatient parenteral therapy programs in United States home healthcare channels bundle these with antibiotic infusions for complete episode management.
- Analgesics:Opioid-sparing multimodal pain protocols favor NSAIDs and acetaminophen combinations.
- Supportive Care:Intravenous hydration and electrolyte replacement support hemodynamic stability.
Antibiotics dominate installed base. Supportive Care is where expansion concentrates as site-of-care migration demands complete outpatient bundles.
Delivery Mode:
Cost tiers separate premium intravenous hospital administration from economy oral outpatient regimens, with reimbursement differentials driving channel selection.
- Oral:Bioavailable beta-lactam and fluoroquinolone formulations enable discharge readiness and home completion. Spero Therapeutics and Shionogi compete on oral gram-negative coverage for resistant pathogens in United States outpatient markets.
- Injectable:Intramuscular cephalosporins bridge hospital-to-home transitions. Brazil and Mexico lack outpatient intravenous infrastructure, making injectable depot formulations critical for site-of-care migration in Latin American markets.
- Intravenous:Extended-infusion beta-lactam dosing optimizes time-above-MIC pharmacokinetics in critical care.
- Topical:Limited applicability for pyelonephritis given renal parenchyma infection depth.
Intravenous dominates installed base. Oral is climbing the fastest as payer pressure accelerates ambulatory shift.
End User:
Volume concentration follows reimbursement architecture, with Medicare diagnosis-related group payments anchoring hospital procurement and pharmacy-benefit carve-outs reshaping home healthcare purchasing.
- Hospitals:Academic medical centers and community hospitals manage complicated pyelonephritis requiring intravenous antibiotics and sepsis protocols. The CDC's National Healthcare Safety Network resistance surveillance directly shapes hospital stewardship and formulary decisions in United States institutions.
- Clinics:Urgent care and infectious disease clinics handle uncomplicated cases and post-discharge follow-up. United States outpatient parenteral therapy expansion channels complicated urinary tract infection volume into clinic-based infusion centers.
- Home Healthcare:Nurse-administered antibiotic infusion and monitoring services capture payer-driven site-of-care migration.
- Long-term Care Facilities:Skilled nursing facilities manage recurrent infection prophylaxis and post-acute antibiotic completion.
Hospitals dominate installed base. Home Healthcare represents the steepest expansion trajectory as integrated pharmacy-benefit contracting concentrates purchasing influence.
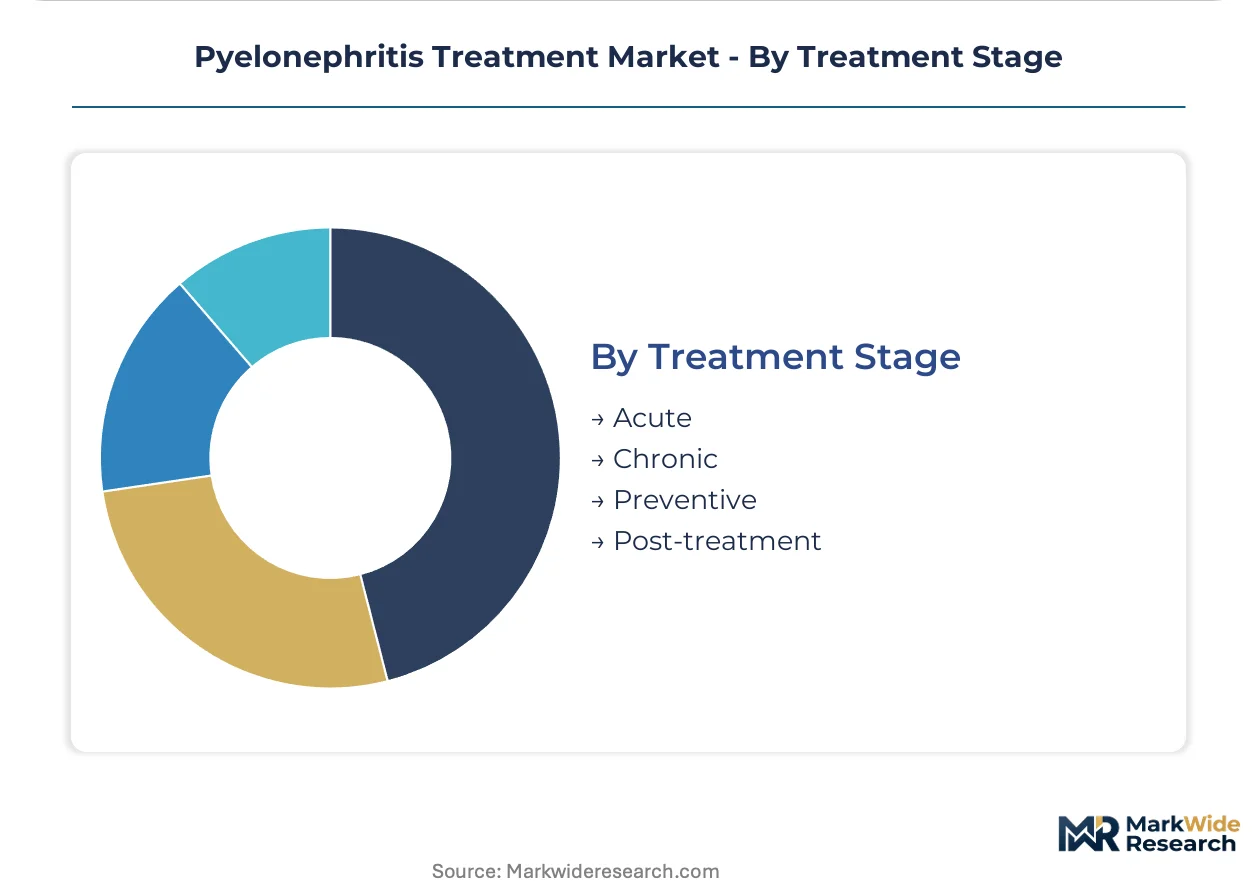
Treatment Stage:
Margin structure inverts across stages: acute therapy commands premium pricing while preventive protocols face generic substitution pressure.
- Acute:Empiric antibiotic initiation targets Enterobacterales, Pseudomonas, and enterococcal coverage before culture results. EMA revised guidance for complicated urinary tract infections now mandates renal tissue concentration data alongside plasma pharmacokinetics for acute-stage agents.
- Chronic:Suppressive antibiotic regimens manage recurrent pyelonephritis and renal abscess sequelae. Extended-duration oral beta-lactam therapy in United States home healthcare settings addresses refractory infections without recurrent hospitalization.
- Preventive:Post-coital prophylaxis and behavioral modification reduce recurrence burden.
- Post-treatment:Microbiological cure confirmation and renal function monitoring complete the care episode.
Acute dominates installed base. Chronic is gaining share fastest as resistant pathogen prevalence extends treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit acute price sensitivity to generic fluoroquinolone substitution, while United States hospitals absorb premium novel agents under diagnosis-related group carve-outs. European procurement operates through centralized tender mechanisms that compress margins. Japanese reimbursement favors domestic manufacturers with established pharmacovigilance infrastructure.
United States
Carbapenem-resistant Enterobacterales prevalence drives FDA Qualified Infectious Disease Product uptake at academic medical centers. Medicare diagnosis-related group payments anchor hospital formulary contracting for intravenous antibiotics. The Boston-Cambridge corridor concentrates Phase III trial execution for renal tissue penetration studies.
Germany
EMA priority medicines scheme accelerates market access for multidrug-resistant gram-negative therapies ahead of standard timelines. The national pharmaceutical regulator mandates resistance surveillance integration into hospital stewardship protocols. The Rhine-Main biotech cluster hosts microbiological endpoint expertise for complicated urinary tract infection trials.
India
CDSCO manufacturing standards condition market access for active pharmaceutical ingredient suppliers to Western formulators. BIS pharmacovigilance requirements extend post-marketing commitment timelines for beta-lactam agents. The Hyderabad-Visakhapatnam corridor concentrates carbapenem and cephalosporin raw material production.
Japan
PMDA accelerated assessment pathways favor domestic developers with established nephrotoxicity surveillance databases. METI industrial policy supports novel oral beta-lactam development for resistant pathogen coverage. The Kansai region anchors pharmacokinetic modeling expertise for renal tissue concentration validation.
Brazil
ANVISA streamlined registration for qualified infectious disease products reduces development-to-commercial timelines for novel agents. Outpatient intravenous infrastructure gaps create demand for oral gram-negative coverage in site-of-care migration. The São Paulo-Rio de Janeiro axis concentrates infectious disease trial enrollment for Latin American expansion.
Pyelonephritis Treatment Market Competitive Landscape
Capability concentration sits with specialized infectious disease developers possessing microbiological endpoint expertise; scale advantage sits with diversified pharmaceutical conglomerates leveraging established anti-infective infrastructure. The market structures around three archetypes: large-cap institutional access players, mid-cap oral formulation specialists, and emerging resistance-focused biotechs. Dominant competitive moves include hospital formulary pre-approval contracting and integrated pharmacy-benefit carve-out negotiations.
Among resistance-focused developers, Venatorx Pharmaceuticals and Spero Therapeutics exemplify the oral beta-lactam specialization archetype, while GlaxoSmithKline occupies a position representing institutional scale advantage through anti-infective infrastructure leverage. Shionogi anchors the fluorocycline platform tier targeting multidrug-resistant gram-negative infections.
| Leading Market Players |
|---|
| Venatorx Pharmaceuticals |
| MerLion Pharmaceuticals |
| Spero Therapeutics |
| Evopoint Biosciences |
| Shionogi |
| Wockhardt |
| Allecra Therapeutics |
| GlaxoSmithKline |
| Iterum Therapeutics |
| Others |
Value Network & Pricing Analysis
Undercapacity in carbapenem active pharmaceutical ingredient manufacturing across the Hyderabad-Visakhapatnam corridor is elevating supplier pricing power while compressing formulator margins. This utilization squeeze forces Western developers to accept extended payment terms or pre-pay for supply security, embedding working capital costs into final therapy pricing.
Pricing Analysis
After-sales revenue from outpatient parenteral therapy bundles drives lifetime value capture for pyelonephritis agents. Three-tier pricing structure across premium novel beta-lactams, standard branded generics, and economy fluoroquinolones segments the United States hospital market. Price differentiation hinges on FDA Qualified Infectious Disease Product designation and renal tissue penetration documentation. Cost compression in the standard tier is intensifying because Medicare diagnosis-related group payments cap inpatient antibiotic spend. Community hospitals exhibit acute price sensitivity; academic medical centers with stewardship mandates absorb premium novel agents.
Supply Chain Analysis
Extended payment terms from Indian and Chinese active pharmaceutical ingredient suppliers are straining formulator cash conversion cycles. Carbapenem and cephalosporin raw materials concentrate among manufacturers in India, China, and select European facilities. Production draws from fermentation-derived beta-lactam cores, specialized chemical intermediates, and sterile fill-finish capacity. Single-source vulnerability in carbapenem API supply threatens continuity for Western developers amid geopolitical friction. Distribution runs through hospital group purchasing organizations and integrated pharmacy-benefit managers in United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic ciproflox substitution at sub-dollar per-dose pricing threatens novel beta-lactam uptake, forcing incumbents to defend on resistance coverage and renal penetration data.
For Market Incumbents: Build regulatory data moats through renal tissue concentration studies that satisfy EMA revised guidance and FDA Qualified Infectious Disease Product requirements. Secure hospital formulary pre-approval contracting ahead of launch to lock out generic substitution in complicated cases. Backward integration into active pharmaceutical ingredient supply buffers margin pressure from Indian and Chinese supplier concentration. For New Entrants and Emerging Players: Latin American outpatient infrastructure gaps present the most penetrable entry point for oral gram-negative coverage agents. Brazil and Mexico lack home infusion networks, making bioavailable beta-lactam formulations critical for site-of-care migration. Target infectious disease clinics in São Paulo and Rio de Janeiro with depot injectable formulations that bridge hospital-to-home transitions without intravenous infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with outpatient parenteral therapy pharmacy-benefit carve-out contracts. Long-term viability over the projection horizon favors firms with FDA priority voucher assets and demonstrated carbapenem-resistant Enterobacterales coverage. Monitor CDC National Healthcare Safety Network resistance surveillance data as the inflection indicator for novel agent demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Renal tissue penetration studies satisfy EMA guidance and accelerate European market access timelines. |
| Regulatory Approval Pathway | FDA Qualified Infectious Disease Product designation unlocks priority review vouchers transferable at premium valuations. |
| Manufacturing Scale-Up | Captive active pharmaceutical ingredient production insulates against Indian and Chinese supply concentration risks. |
| Hospital System Partnership | Pre-approval formulary contracting secures institutional access before generic competitors enter the market. |
| Pipeline Diversification | Oral beta-lactam development for resistant pathogens captures site-of-care migration beyond intravenous-only regimens. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with infectious disease physicians, hospital formulary directors, pharmacy procurement managers, and regulatory affairs specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CDC resistance surveillance databases. Bottom-up and top-down triangulation cross-checked patient volume estimates against antibiotic consumption data and reimbursement claims patterns.
Forecast inputs considered treatment stage segmentation, delivery mode migration, and end-user channel evolution across the projection horizon. CAGRs were derived from epidemiological trend modeling, resistance surveillance integration, and payer policy trajectory analysis. Patient population demographics, hospital admission patterns for complicated urinary tract infections, and site-of-care economics shaped volume and value outputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oral beta-lactam specialists or carbapenem-resistant Enterobacterales outbreak clusters would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Disposables Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Prostate Cancer Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Cystoscope Market
Urology
Self-Intermittent Catheters Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Urology Lasers Market
Urology
Europe Urology Devices Market
Urology
India Urology Device Market
Urology
Global Lithotripsy Market
Urology
Obstructive Uropathy Treatment Market
Urology
Cystectomy Market