
 Global Foley Catheters Market | 2026-2036
Global Foley Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foley Catheters Market Analysis
Capital-intensity divergence between automated extrusion lines and manual assembly floors is reorganizing competitive tiers in the Global Foley Catheters Market. Coloplast Corp leverages captive silicone compounding to sustain margin structures across European hospital contracts. Becton Dickinson & Company anchors North American volume through integrated sterilization networks that smaller competitors cannot replicate.
A Foley catheter is an indwelling urinary drainage device featuring an inflatable balloon near the tip, typically manufactured from silicone or latex via extrusion and dip-molding processes, designed to maintain bladder decompression over extended dwell times. Silicone variants command premium positioning due to biocompatibility and reduced encrustation rates in long-dwell applications, while latex segments retain cost-sensitive volume in emerging procurement channels. Hospitals dominate absolute consumption, though homecare represents the fastest-expanding end user channel as payors shift reimbursement toward outpatient management.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development cycles and market access timelines for manufacturers serving Western markets. ISO 13485 quality system certification functions as a baseline threshold for supplier qualification across Japanese and Australian procurement frameworks. Stakeholders must monitor antimicrobial coating validation standards and reimbursement code revisions in concentrated demand markets to align portfolio investments with shifting clinical and economic criteria.
Market Dynamics
EU MDR recertification deadlines are compressing supplier qualification windows, forcing accelerated technical documentation submissions for silicone-based Foley catheter portfolios while hospital procurement consolidates around infection-prevention validated suppliers.
Growth Catalysts
- Homecare Reimbursement Expansion:CMS and Japanese MHLW outpatient codes now cover extended-dwell catheter supplies, redirecting patient volume from acute facilities toward reimbursed home management protocols.
- Antimicrobial Coating Mandates:German hospital procurement frameworks now require validated infection-prevention surfaces on indwelling devices, creating specification pull for silver-alloy and nitrofurazone-impregnated variants.
- Silicone Compounding Scale:Captive resin production in medical-grade silicone hubs reduces raw material lead times and stabilizes supply security for long-dwell catheter manufacturers serving aging patient populations.
Market Restraints
- Medical-Grade Silicone Concentration:Five specialized compounders control 70% of implantable-grade silicone supply, creating input vulnerability for catheter extruders without backward integration.
- Latex Allergy Liability Exposure:Natural rubber protein sensitization risk constrains latex catheter penetration in US and EU acute settings, despite cost advantages in price-sensitive procurement channels.
- EU MDR Technical Documentation Burden:Clinical evidence requirements for Class IIa devices extend recertification timelines to 18-24 months, freezing new product introductions for mid-tier suppliers.
Strategic Opportunities
- Brazil Ambulatory Surgery Expansion:ANVISA streamlined 510(k)-equivalent pathways for urological devices, opening private hospital procurement to imported infection-prevention catheters.
- Digital Remote Monitoring Integration:Sensor-embedded Foley systems combining urine output telemetry with cloud-based alerting are penetrating post-surgical recovery wards in Japanese university hospitals.
- Sustainable Material Substitution:Bio-based polyurethane development programs target petroleum-derived silicone displacement in short-dwell applications, aligning with NHS England net-zero procurement mandates.
Industry Challenges
- ISO 13485 Auditor Capacity Bottleneck:Notified body queue times for quality system surveillance audits extend to 14 months, delaying certificate renewals required for EU market access.
- Ethylene Oxide Sterilization Constraints:EPA facility closures in the US Midwest compress terminal sterilization capacity, forcing catheter manufacturers toward gamma irradiation validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foley Catheters Market |
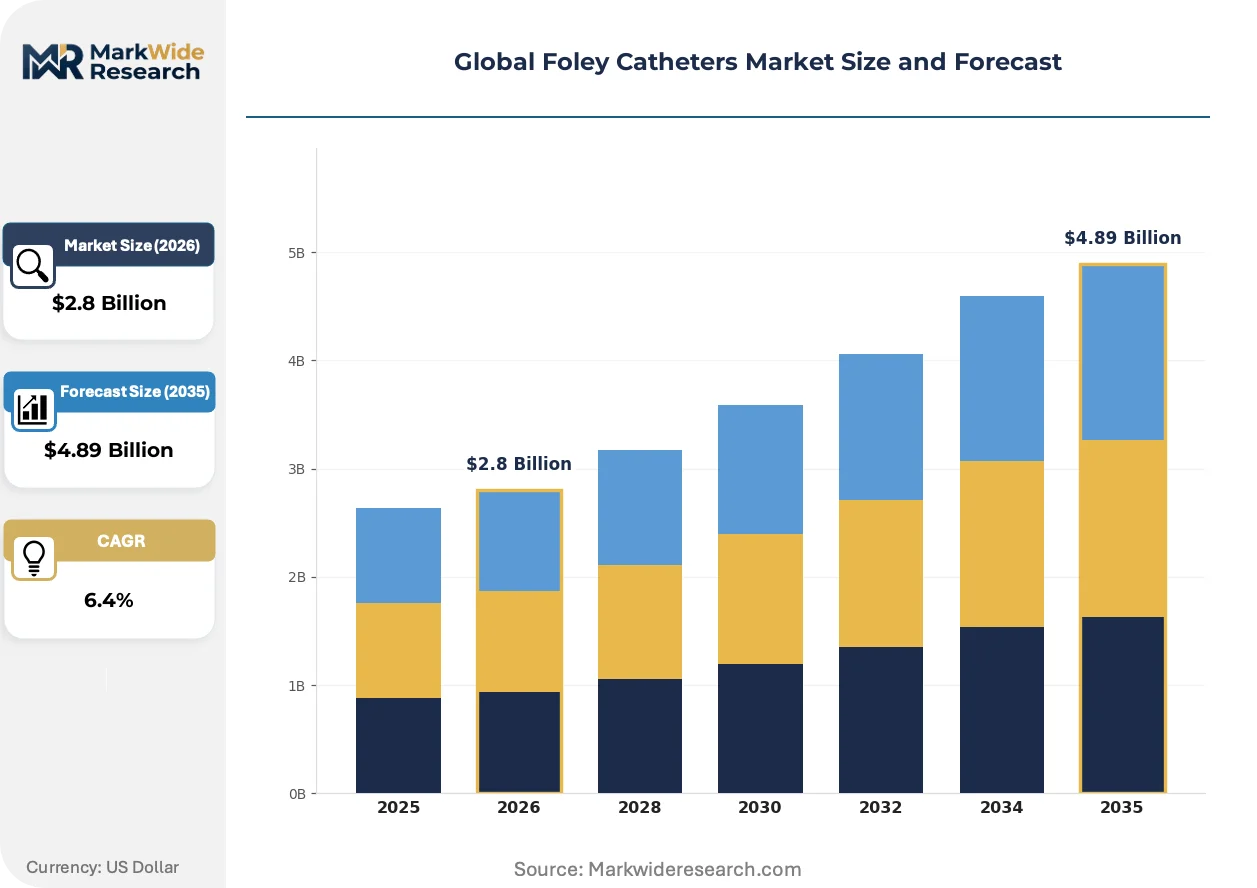
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Standard, Silicone, Latex End User: Hospitals, Homecare, Clinics, Long-Term Care Facilities Application: Urinary Retention, Surgery, Diagnostics, Palliative Care Size: 12 Fr, 14 Fr, 16 Fr, 18 Fr |
| Companies Covered | Coloplast Corp, B. Braun SE, Teleflex Incorporated, Cardinal Health, Medtronic, Becton Dickinson & Company, Bactiguard AB, Sterimed Group, Hollister Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foley Catheters Market Emerging Trajectories
Material science advances and regulatory documentation automation are compressing product development cycles while reshaping competitive differentiation around validated clinical outcomes rather than commodity specifications.
Silver-alloy and nitrofurazone-impregnated catheter surfaces are displacing standard silicone in US hospital purchasing agreements, with infection-prevention committees mandating coated variants for ICU and long-term acute care placements. Premier and Vizient GPO contracts now exclude uncoated latex options from tier-one formulary status. This specification shift is compressing margins for manufacturers lacking validated antimicrobial platforms.
EU MDR Article 10 technical documentation requirements are forcing catheter suppliers to reconstruct clinical evidence packages for legacy products, with notified bodies demanding fresh biocompatibility testing under ISO 10993-5 cytotoxicity protocols. German and French hospital procurement frameworks now screen supplier MDR certificate validity dates, excluding devices with recertification pending beyond 2026. Mid-tier manufacturers without dedicated regulatory affairs infrastructure are exiting the EU market entirely.
Japanese long-term care insurers now reimburse catheter supply on a bundled monthly basis rather than per-unit dispensing, compressing homecare pharmacy margins and consolidating purchasing through regional medical cooperatives. This payment reform concentrates procurement volume among distributors offering inventory management and patient education services alongside product supply. Rural prefectures exhibit the fastest consolidation as independent pharmacies exit the urological supply category.
Global Foley Catheters Market Segmentation
Foley catheter procurement channels fragment sharply across acute and extended-care settings, with reimbursement codes and infection-prevention mandates steering volume toward specific material and coating specifications. Understanding how segments map to purchasing hierarchies reveals where specification power concentrates.
Product Type:
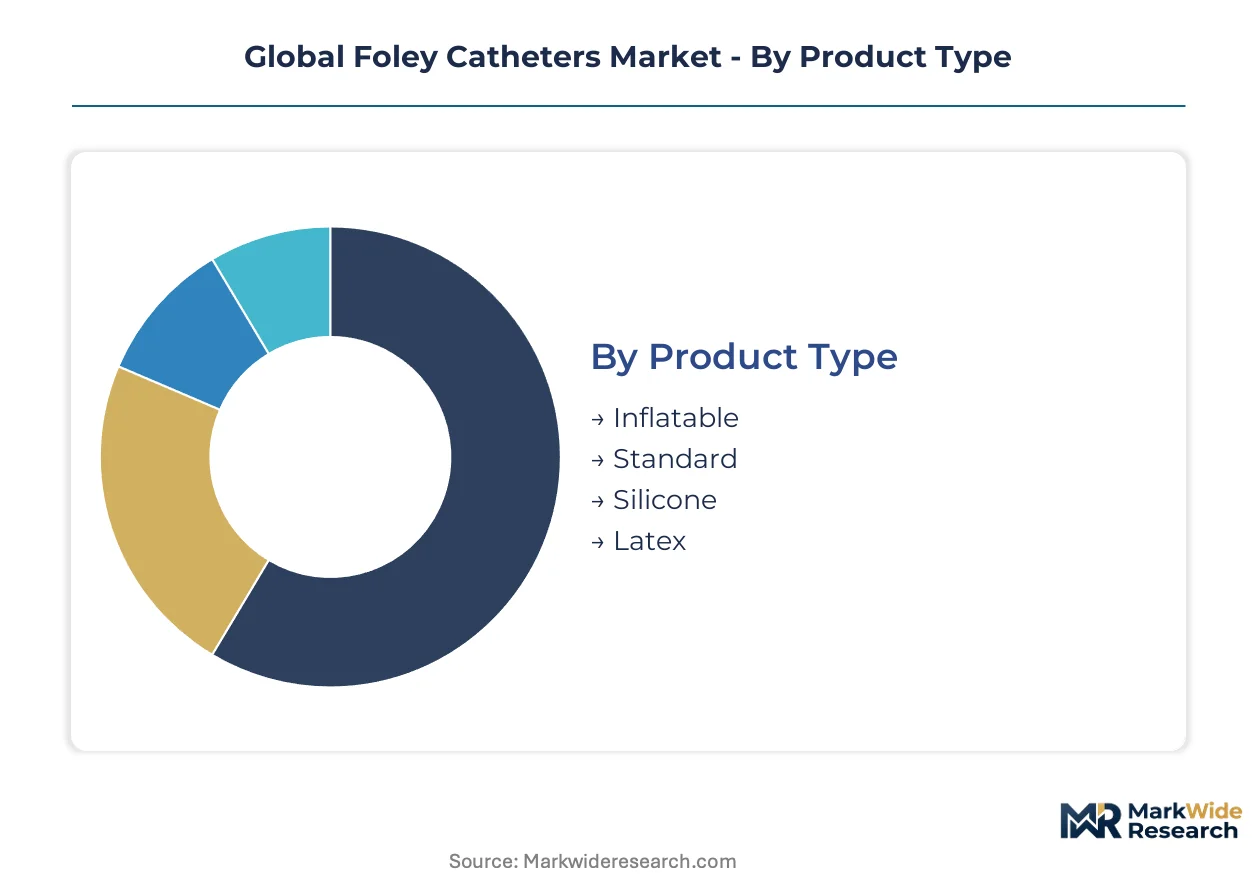
Channel mix splits between hospital formulary committees demanding validated antimicrobial surfaces and homecare distributors prioritizing cost-efficient latex volume for reimbursed monthly bundles.
- Inflatable:Retention balloon design enables secure bladder decompression across ICU and post-surgical recovery wards. German hospital procurement frameworks now mandate infection-prevention validated variants for all indwelling placements, concentrating demand with suppliers holding silver-alloy coating certifications.
- Silicone:Biocompatible extrusion with reduced protein adhesion resists encrustation during extended dwell periods. Japanese long-term care insurers reimburse silicone premiums for patients exceeding 14-day dwell protocols, channeling volume toward regional medical cooperatives with inventory management capabilities.
- Standard:Basic two-way or three-way configurations without antimicrobial impregnation serve price-sensitive emerging markets and short-dwell diagnostic applications.
- Latex:Natural rubber construction retains cost advantage in bulk procurement channels, though US and EU acute settings increasingly exclude uncoated variants from tier-one formularies due to protein sensitization liability.
By volume, Latex leads. By growth pace, Silicone is ahead.
End User:
Customer-type concentration reflects reimbursement migration from per-procedure acute billing toward bundled chronic management payments.
- Hospitals:Absolute consumption anchor with infection-prevention committees mandating coated variants for ICU placements. Premier and Vizient GPO contracts now exclude uncoated latex from tier-one formulary status.
- Homecare:Fastest-expanding channel as CMS and Japanese MHLW outpatient codes cover extended-dwell supplies. Regional medical cooperatives consolidate purchasing as independent pharmacies exit urological categories.
- Clinics:Ambulatory surgical centers drive short-dell diagnostic volume through streamlined ANVISA-equivalent pathways in Brazil.
- Long-Term Care Facilities:Aging patient acuity rises across German and Japanese institutional settings, expanding silicone procurement for residents requiring chronic bladder management.
Hospitals dominate absolute spend. Homecare climbs the fastest.
Application:
Clinical use-case segmentation aligns with dwell-time requirements and reimbursement coding specificity across acute versus chronic management protocols.
- Urinary Retention:Chronic decompression indication drives long-dwell silicone demand with encrustation-resistant specifications. Japanese bundled reimbursement favors premium materials for retention cases exceeding monthly monitoring thresholds.
- Surgery:Perioperative bladder drainage requires sterile single-use configurations. Post-surgical recovery wards in Japanese university hospitals pilot sensor-embedded systems with urine output telemetry.
- Diagnostics:Short-dwell voiding studies and urodynamic assessments utilize cost-efficient standard catheters without antimicrobial coatings.
- Palliative Care:Comfort-focused management in hospice settings prioritizes soft silicone construction with minimal tissue irritation for terminal patients.
Surgery generates the highest unit volume. Palliative Care is expanding most quickly.
Size:
French catheter scale specifications correlate with patient demographics and procedural indication across pediatric, adult, and bariatric populations.
- 14 Fr:Mid-range diameter serves adult male and female populations across general medical-surgical wards, representing the procurement default for non-specialized placements.
- 16 Fr:Slightly larger bore accommodates drainage with higher viscosity or post-operative hematuria, common in urological and gynecological surgical services.
- 12 Fr:Pediatric and geriatric frail populations with urethral stricture risk utilize smaller diameter construction to minimize tissue trauma.
- 18 Fr:Bariatric patients and hematuria management require maximum lumen diameter, with silicone variants preferred for reduced friction in enlarged anatomy.
14 Fr dominates procurement volume. 12 Fr gains share fastest in aging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward specialized silicone compounders in Germany and Japan while the United States absorbs premium-coated volumes. Brazil and India represent net import dependency for infection-prevention devices.
United States
CMS outpatient reimbursement expansion redirects acute volume toward homecare channels. FDA 510(k) clearance pathways compress market access timelines for antimicrobial-coated submissions. Minneapolis and Boston corridor hospitals anchor tier-one formulary consolidation around silver-alloy validated suppliers.
Germany
Hospital procurement frameworks mandate infection-prevention surfaces on all indwelling placements. EU MDR recertification deadlines compress supplier qualification windows through 2026. Tübingen and Munich medical technology clusters concentrate silicone extrusion capacity for European hospital contracts.
Japan
MHLW bundled reimbursement for long-term care insurers consolidates purchasing through regional medical cooperatives. PMDA quality system surveillance aligns with ISO 13485 certification thresholds. Osaka and Nagoya prefectures exhibit fastest pharmacy consolidation as independent distributors exit urological categories.
Brazil
ANVISA streamlined pathways for urological devices open private hospital procurement to imported infection-prevention catheters. Ambulatory surgery expansion in São Paulo and Rio de Janeiro drives short-dwell diagnostic volume. Domestic manufacturers face raw material import dependency for medical-grade silicone.
India
CDSCO medical device rules converge with ISO 13485 for supplier qualification in tertiary hospital procurement. Price-sensitive volume retains latex preference in bulk public health programs. Ahmedabad and Chennai manufacturing corridors scale standard catheter output for domestic and export markets.
Global Foley Catheters Market Vendor Landscape
Concentration sits with diversified medical device conglomerates and specialized urological manufacturers. Three-tier supplier structure separates premium silicone compounders from mid-scale latex processors and regional distributors. Strategic moves center on backward integration into resin production and sterilization network consolidation.
Among European medical technology specialists, Coloplast Corp and B. Braun SE exemplify archetype positioning through captive material capabilities and integrated quality systems. Teleflex Incorporated anchors North American presence alongside hospital-focused distributors. Becton Dickinson & Company represents scale-driven sterilization infrastructure that smaller competitors cannot replicate.
| Leading Market Players |
|---|
| Coloplast Corp |
| B. Braun SE |
| Teleflex Incorporated |
| Cardinal Health |
| Medtronic |
| Becton Dickinson & Company |
| Bactiguard AB |
| Sterimed Group |
| Hollister Incorporated |
| Others |
Supply Flow & Price Mechanics
Forty-five-day raw material lead times for medical-grade silicone resin compress procurement flexibility and anchor pricing power with compounders in Germany and Japan. Hospital formulary committees exploit this concentration to extract coating-validation guarantees, while distributors absorb inventory risk in reimbursed homecare channels.
Pricing Analysis
Configured-to-order pricing for silver-alloy coated variants commands a 40-60% premium over standard silicone specifications in US hospital contracts. Pricing stratifies across antimicrobial-validated premium tiers, standard silicone mid-market positions, and economy latex segments for emerging procurement channels. Cost compression in the uncoated latex tier intensifies as Brazilian and Indian bulk tenders exclude protein-sensitization liabilities. Homecare distributors exhibit highest price sensitivity due to bundled monthly reimbursement compressing per-unit margins.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone resin dominates procurement strategy among European catheter extruders facing EU MDR recertification deadlines. Supply concentrates in Germany, Japan, and the United States for specialized compounding; Malaysia and Thailand anchor latex processing for cost-sensitive volume. Raw material dependencies include implantable-grade silicone, nitrofurazone antimicrobial agents, and ethylene oxide sterilization capacity. Single-source vulnerability in sterilization infrastructure forces manufacturers toward gamma irradiation validation investments. Distribution runs through hospital GPO contracts in North America and regional medical cooperatives in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification compresses supplier windows while antimicrobial coating mandates rewrite procurement specifications, creating high-growth disruption for validated manufacturers.
For Market Incumbents: Consolidate backward integration into captive silicone compounding to defend margin structures against raw material concentration. Lock hospital system partnerships through infection-prevention committee engagement before recertification deadlines freeze competitor access. Prioritize sterilization network control as EPA facility closures in the US Midwest compress terminal capacity. For New Entrants and Emerging Players: Differentiate on digital remote monitoring integration targeting Japanese university hospital pilot programs for sensor-embedded systems. Exploit ANVISA streamlined pathways to penetrate Brazilian private hospital procurement before domestic manufacturers scale antimicrobial coating capabilities. Lead with patient education and inventory management services bundled with product supply to capture Japanese homecare cooperative consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-qualification play because EU MDR and FDA 510(k) pathways create durable moats around validated suppliers. Target mid-tier manufacturers with incomplete MDR technical documentation facing forced exit. Watch ISO 13485 auditor queue times as the inflection signal—certificate renewal delays beyond 14 months trigger supply concentration and acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Technical documentation completion before 2026 deadlines secures German and French hospital formulary access. |
| Antimicrobial Coating Validation | Silver-alloy certification opens Premier and Vizient GPO tier-one contracts excluding uncoated alternatives. |
| Sterilization Network Consolidation | Gamma irradiation capacity investments offset EPA ethylene oxide facility closures in Midwest manufacturing corridors. |
| Homecare Distribution Partnership | Regional medical cooperative alliances capture Japanese bundled reimbursement volume as independent pharmacies exit. |
| Silicone Compounding Backward Integration | Captive resin production reduces lead time exposure to five specialized compounders controlling implantable-grade supply. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EU MDR technical documentation filings, CMS reimbursement code revisions, and Japanese MHLW bundled payment regulations. Interviews with hospital procurement managers, GPO contracts directors, biomedical engineers, regulatory affairs leads, and long-term care facility administrators informed demand-side validation. Bottom-up unit volume estimates triangulate against top-down expenditure analysis across acute and extended-care settings.
Segmentation dimensions modeled include material type, coating specification, end-user channel, application indication, and French catheter scale across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating aging demographic trajectories and reimbursement migration patterns. Forecast inputs incorporate EU MDR recertification timelines, antimicrobial coating adoption curves in German hospital frameworks, and Japanese pharmacy consolidation rates.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement support for infection-prevention devices or accelerated sterilization capacity constraints would require recalibration. Forecasts reflect assumptions regarding regulatory pathway stability and raw material supply continuity. Revision becomes warranted when ISO 13485 auditor queue times or EPA sterilization facility status crosses thresholds that freeze market access for qualified suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
US Nebulizer Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Phoropters Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Cervical Retractors Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Laser BPH Devices Market