
 Varicocele Treatment Market | 2026-2036
Varicocele Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Varicocele Treatment Market Outlook
The urology device supply chain is reconfiguring around specialty distributors that serve ambulatory surgical centers. Boston Scientific Corporation leverages its interventional portfolio to maintain catheter and embolization coil availability across these channels. Merit Medical Systems anchors its position through in-house manufacturing of access kits and delivery systems used in percutaneous varicocele embolization.
Varicocele treatment encompasses surgical and interventional techniques to correct venous insufficiency within the pampiniform plexus, with sclerosing agents typically comprising sodium tetradecyl sulfate or polidocanol delivered via microcatheter under fluoroscopic guidance. The primary purpose is to restore testicular thermoregulation and improve semen parameters in infertile patients. Percutaneous embolization now leads procedural volume growth due to shorter recovery windows and lower recurrence rates versus open surgical approaches. Radiofrequency ablation occupies a narrower but expanding niche in select European and Asian clinics where thermal ablation training programs have matured.
The FDA governs 510(k) clearance pathways for varicocele embolization devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class III implantable devices. Japan's PMDA maintains separate pharmaceutical and medical device review tracks that delay market entry for combination sclerotherapy products. Stakeholders must monitor reimbursement code consolidation across Medicare and commercial payers as ambulatory migration accelerates.
Market Dynamics
Migration of varicocele procedures from hospital inpatient to ambulatory surgical centers is compressing reimbursement rates while expanding procedural volume, forcing device manufacturers to reconfigure distribution economics around specialty distributors serving same-day discharge facilities.
Growth Catalysts
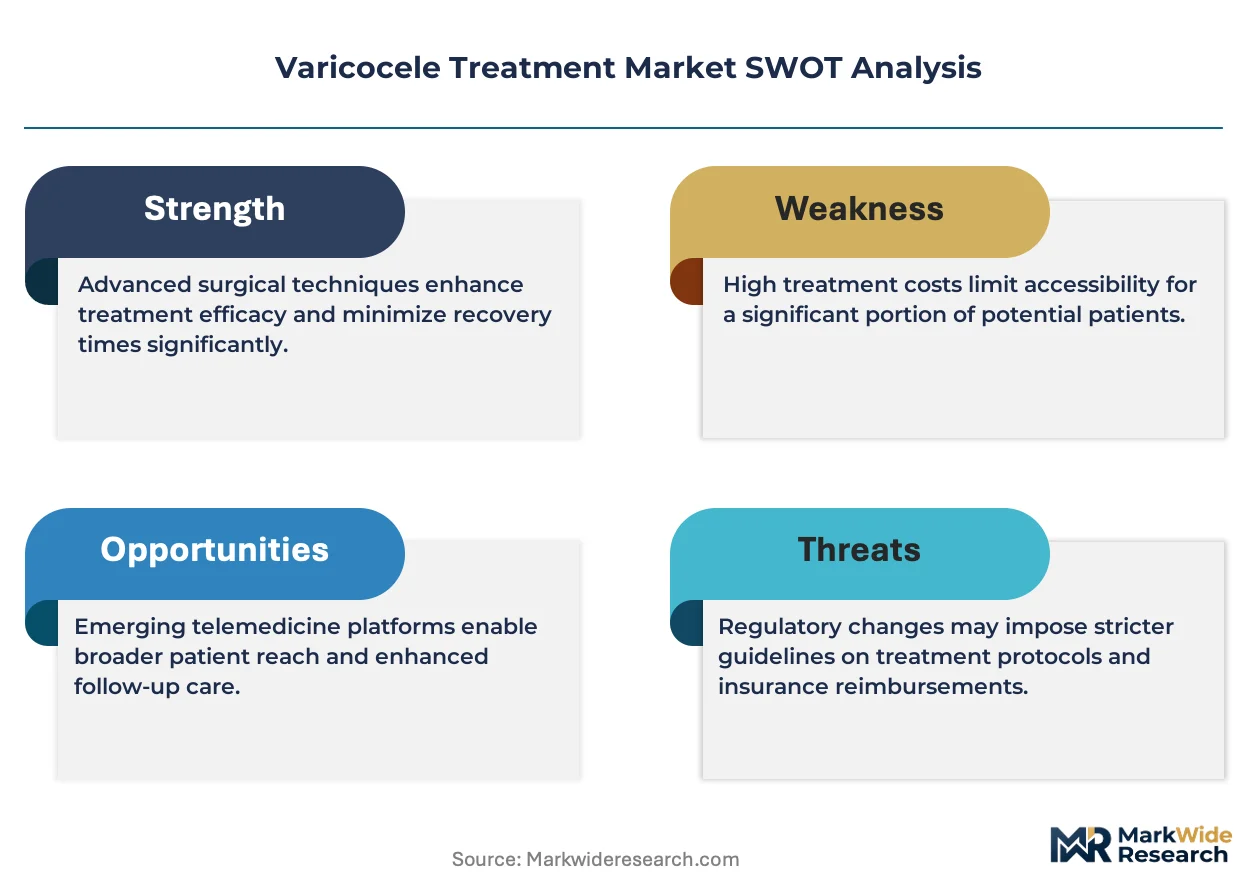
- EU Medical Device Regulation (MDR) clinical evidence pathways:Stricter Class III implantable requirements are accelerating consolidation among device manufacturers with robust clinical data portfolios, advantaging established players with pre-existing trial infrastructure.
- Fertility clinic specialization:Dedicated reproductive urology centers are building in-house embolization capabilities, creating direct procurement relationships that bypass traditional hospital supply chains.
- Microcatheter delivery system refinements:Enhanced steerability and distal access are expanding anatomical treatability for complex venous anatomies previously requiring open surgical correction.
Market Restraints
- Platinum-iridium coil input cost volatility:Precious metal price fluctuations directly impact embolization device margins, with manufacturers absorbing cost swings to maintain hospital contract pricing.
- Fluoroscopy suite capital intensity:Interventional radiology infrastructure requirements limit procedure expansion in resource-constrained settings, particularly secondary and tertiary hospitals.
- Recurrence rate variability:Technical operator dependence creates outcome heterogeneity that complicates payer coverage determinations and physician training standardization.
Strategic Opportunities
- Radiofrequency ablation training maturation:European and Asian thermal ablation certification programs are creating alternative modality adoption pathways outside traditional embolization dominance.
- Japan PMDA combination product review streamlining:Pharmaceutical-medical device convergence pathways for sclerotherapy agents present first-mover advantages for integrated delivery system developers.
- Telemedicine-enabled preoperative screening:Remote scrotal thermography and semen analysis are expanding addressable patient populations in geographically dispersed markets.
Industry Challenges
- Interventional radiology-urology cross-training deficits:Dual-specialty competency requirements create workforce bottlenecks as procedure volume shifts toward minimally invasive techniques.
- 510(k) predicate device erosion:FDA clearance pathway narrowing for incremental device modifications is extending regulatory timelines and increasing clinical evidence burdens.
- Reimbursement code fragmentation:Procedural coding distinctions between surgical and interventional approaches create claims complexity that delays payment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Varicocele Treatment Market |
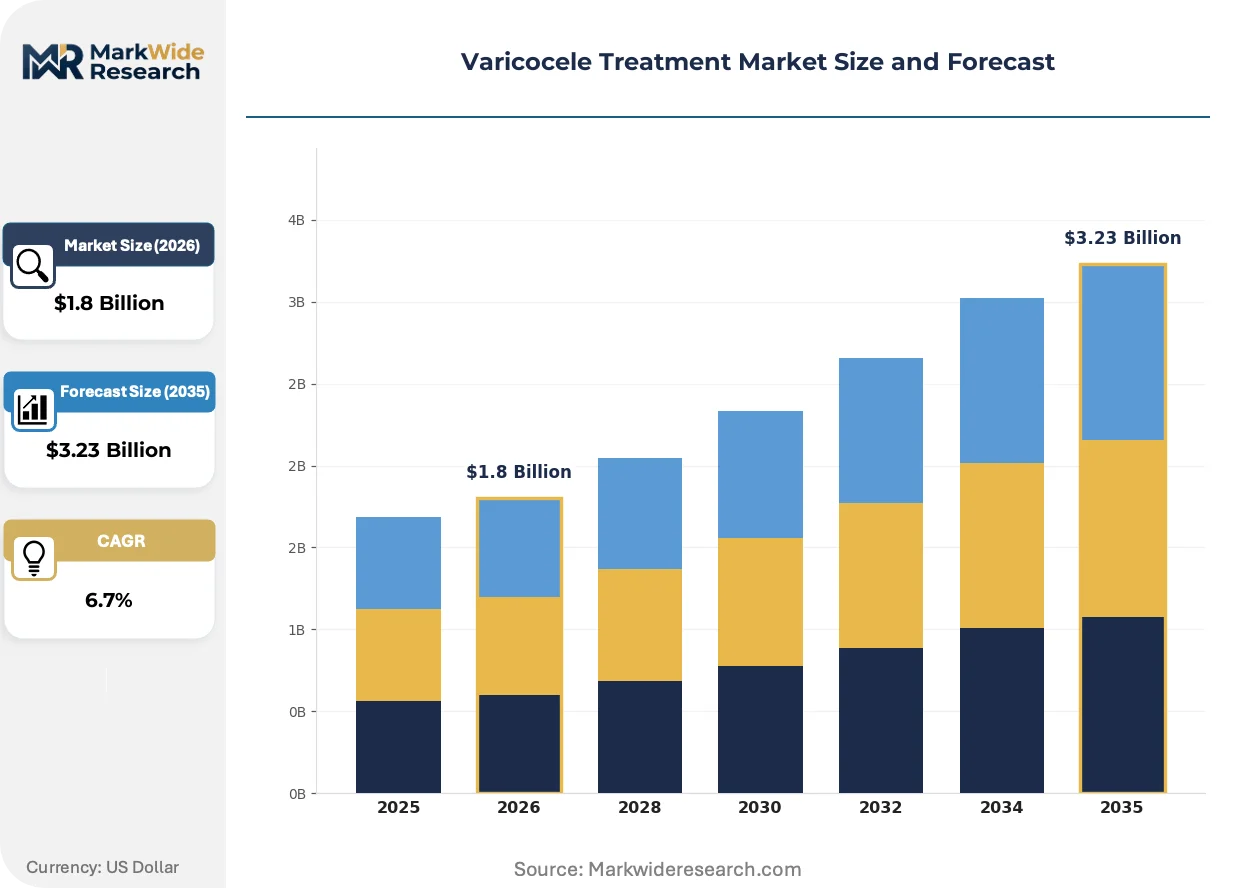
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Surgery, Laparoscopic Surgery, Percutaneous Embolization, Radiofrequency Ablation End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Centers Application: Pain Relief, Fertility Enhancement, Cosmetic Surgery, Routine Check-ups Delivery Mode: Intravenous, Oral, Local, General Anesthesia |
| Companies Covered | Sciton, Boston Scientific Corporation, Medtronic, Dornier MedTech, Quanta System, AngioDynamics, Teleflex Incorporated, Merit Medical Systems, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Varicocele Treatment Market Strategic Shifts
Real-time imaging integration and sclerotherapy agent formulation advances are converging to reduce procedure times and improve technical success rates. These developments are reshaping training curricula and capital allocation across urology and interventional radiology departments.
Contrast-enhanced ultrasound guidance is digitizing varicocele mapping and procedural navigation. Fertility clinics in Germany and Japan are adopting this modality to reduce fluoroscopy exposure and eliminate iodinated contrast requirements. The technology is digitizing preoperative planning workflows and enabling point-of-care feasibility assessments that previously required interventional radiology suite scheduling.
The EU Medical Device Regulation is imposing extended clinical evaluation report requirements on embolization coil manufacturers. Class III device recertification deadlines are forcing portfolio rationalization decisions, with several product lines facing discontinuation rather than costly clinical data generation. Small and mid-sized manufacturers are responding through partnership arrangements with larger entities possessing established quality management systems.
Patient self-referral patterns are altering traditional primary care gatekeeping for male infertility evaluations. Direct-to-fertility-clinic pathways in the United States are compressing diagnostic timelines and shifting initial consultation economics. This behavioral shift is most pronounced in metropolitan markets with established reproductive urology density, where online scheduling platforms now capture substantial initial patient intake.
Varicocele Treatment Market Segmentation
Varicocele treatment modalities span surgical, interventional, and pharmacological approaches with distinct reimbursement profiles and capital requirements. Segmentation clarity enables stakeholders to align portfolio investments with procedural volume migration toward minimally invasive settings.
Product Type:
Percutaneous embolization and radiofrequency ablation turn over fastest as outpatient volumes surge, while open surgical approaches retain slower, inpatient-bound cycles.
- Open Surgery:Conventional inguinal or subinguinal ligation with microscopic or loupe-assisted visualization. Demand concentrates in resource-constrained settings across India and Brazil where fluoroscopy suite capital remains scarce.
- Laparoscopic Surgery:Transperitoneal or retroperitoneal approach with bipolar cautery or clip ligation. Adoption persists in tertiary hospitals across Germany and Japan where surgical training pipelines favor endoscopic competency over interventional radiology cross-training.
- Percutaneous Embolization:Catheter-directed venography with coil or sclerosant deployment via femoral or jugular access. Fertility clinics in the United States are building in-house capabilities, bypassing traditional hospital supply chains and compressing diagnostic-to-treatment timelines.
- Radiofrequency Ablation:Thermal energy delivery via percutaneous probe under ultrasound guidance. European certification programs in France and Spain are maturing operator training pathways outside traditional embolization dominance.
Percutaneous embolization anchors the volume base while radiofrequency ablation gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean ambulatory configurations with minimal fixed overhead.
- Hospitals:Inpatient surgical suites with overnight observation capacity. Reimbursement rate compression under Medicare diagnosis-related group coding limits margin expansion despite case volume retention.
- Clinics:Office-based urology practices with limited procedural capability. Demand concentrates in metropolitan United States markets with established reproductive urology density and direct-to-consumer scheduling platforms.
- Ambulatory Surgical Centers:Same-day discharge facilities with dedicated interventional radiology suites. Specialty distributors are reconfiguring supply chains to serve these channels with compressed delivery cycles.
- Specialty Centers:Dedicated fertility and reproductive urology institutions with integrated diagnostic and therapeutic workflows. Germany and Japan lead adoption of contrast-enhanced ultrasound to reduce fluoroscopy exposure.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly as payer migration accelerates.
Application:
Volume distribution skews heavily toward functional outcomes versus cosmetic indications, with fertility applications commanding premium reimbursement positioning.
- Pain Relief:Scrotal discomfort and heaviness resolution through venous decompression. Demand concentrates in younger patient cohorts across the United States where symptom-driven self-referral bypasses primary care gatekeeping.
- Fertility Enhancement:Semen parameter improvement through testicular thermoregulation restoration. Japanese fertility clinics report the highest procedural density per capita, driven by national infertility coverage expansion.
- Cosmetic Surgery:Scrotal appearance modification for aesthetic concerns. Narrower indication set with limited insurance coverage across all major markets.
- Routine Check-ups:Incidental varicocele detection during physical examination. Low conversion rate to active intervention without symptomatic or fertility-related indication.
Fertility enhancement anchors the volume base while pain relief applications climb the fastest as patient self-advocacy expands.
Delivery Mode:
Margin structure separates high-value interventional anesthesia from commoditized oral and local alternatives with minimal device attachment.
- Intravenous:Conscious sedation or monitored anesthesia care for percutaneous procedures. Required for coil deployment and sclerotherapy administration under fluoroscopy.
- Oral:Analgesic and anxiolytic premedication for minimally invasive office procedures. Limited to select radiofrequency ablation protocols with robust local anesthesia.
- Local:Infiltrative anesthesia at access site or scrotal wall. German clinics are advancing ultrasound-guided local protocols to eliminate anesthesia professional fees.
- General Anesthesia:Endotracheal or laryngeal mask airway for laparoscopic and open surgical approaches. Concentrated in hospital-based settings with overnight observation requirements.
General anesthesia anchors the volume base while local delivery modes expand most quickly as office-based protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The interventional radiology infrastructure underlying metropolitan healthcare networks in the United States, Germany, and Japan underwrites their dominant positions in varicocele treatment procedural volume and device procurement.
United States
Fertility clinic self-referral pathways and ambulatory surgical center expansion drive procedural migration away from hospital settings. FDA 510(k) clearance pathways govern device market entry, with predicate device erosion extending regulatory timelines. Boston Scientific Corporation anchors supply chain reconfiguration through specialty distributors serving same-day discharge facilities across metropolitan markets.
Germany
Contrast-enhanced ultrasound adoption and reproductive urology center density concentrate demand in Bavaria and North Rhine-Westphalia. EU Medical Device Regulation Class III implantable requirements accelerate portfolio rationalization among manufacturers. Munich and Cologne clusters lead operator training standardization for minimally invasive thermal ablation protocols.
Japan
National infertility coverage expansion and PMDA combination product review tracks shape market entry dynamics for sclerotherapy-integrated delivery systems. Tokyo and Osaka fertility clinics report the highest procedural density per capita globally. METI industrial policy supports domestic catheter manufacturing capacity for interventional urology applications.
India
Open surgical approaches retain dominance where fluoroscopy suite capital remains scarce across secondary and tertiary hospitals. CDSCO medical device registration requirements create compliance barriers for imported embolization systems. Mumbai and Delhi medical device clusters concentrate domestic assembly operations for access kits and delivery sheaths.
Brazil
Resource-constrained settings sustain demand for conventional inguinal ligation techniques over percutaneous alternatives. ANVISA medical device approval pathways prioritize established surgical instruments over novel interventional technologies. São Paulo and Rio de Janeiro university hospitals anchor training pipelines for microscopic varicocelectomy techniques.
Varicocele Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in catheter, coil, and energy delivery manufacturing. The vendor base stratifies across three tiers: diversified medical technology conglomerates with interventional portfolios, mid-cap device manufacturers with in-house production capabilities, and regional specialists in sclerotherapy agents or thermal ablation systems. Dominant competitive moves include M&A activity targeting embolization coil technology and strategic partnerships to secure platinum-iridium supply chains.
Among diversified interventional players, Boston Scientific Corporation and Merit Medical Systems exemplify platform integrators with catheter and embolization device portfolios. Medtronic occupies a position spanning surgical energy systems and interventional access technologies. These three entities represent the consolidation pressure that EU MDR clinical evidence requirements impose on smaller manufacturers lacking established trial infrastructure.
| Leading Market Players |
|---|
| Sciton |
| Boston Scientific Corporation |
| Medtronic |
| Dornier MedTech |
| Quanta System |
| AngioDynamics |
| Teleflex Incorporated |
| Merit Medical Systems |
| Lumenis |
| Others |
Value Chain & Pricing Dynamics
Mumbai and Delhi medical device clusters concentrate domestic assembly operations for access kits and delivery sheaths, with their capacity utilization rates directly determining contract pricing power for imported embolization systems across Indian secondary hospitals. Platinum-iridium coil input costs transmit volatility downstream, forcing manufacturers to absorb margin compression to maintain long-term hospital purchasing agreements.
Pricing Analysis
Volume-discount tiering structures separate premium FDA-cleared devices from standard CE-marked alternatives and economy-grade domestic assemblies in India and Brazil. Price differentiation rests on certification grade and after-sales technical support bundling rather than raw device performance. Cost compression in the economy tier is intensifying because CDSCO and ANVISA registration barriers limit import competition. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed reimbursement ceilings, while specialty fertility clinics prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Export-control regimes on advanced catheter manufacturing equipment limit technology transfer to emerging production hubs, constraining supply expansion outside established centers. Manufacturing concentrates in the United States, Germany, and Japan for precision microcatheters, while China and South Korea anchor coil winding and precious metal processing. Raw material dependencies include platinum-iridium alloys, medical-grade polymers, and fluoroscopy-compatible shielding components. Single-source vulnerability in precious metal refining creates supply chain risk. Distribution runs through specialty distributors serving ambulatory surgical centers with compressed delivery cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as fertility clinics build direct procurement relationships and interoperability standards for sclerotherapy-integrated delivery systems consolidate around dominant catheter architectures.
For Market Incumbents: Insulate market position by securing captive platinum-iridium supply agreements and accelerating backward integration into microcatheter tip forming. Radiofrequency ablation certification programs in Europe represent a substitute technology threat requiring pre-emptive training investment. Channel control through exclusive specialty distributor arrangements serves as the priority defensive lever. For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in Brazil and India represent the most penetrable entry point given fluoroscopy suite scarcity that sustains demand for simplified access kits. Contrast-enhanced ultrasound-compatible delivery systems offer a differentiated go-to-market angle in German and Japanese fertility clinics seeking reduced radiation exposure protocols. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR Class III recertification deadlines are forcing portfolio rationalization among mid-cap manufacturers lacking clinical trial infrastructure. Acquisition targets with established quality management systems and pre-existing predicate device clearances offer the most defensible positioning. The signal to watch is PMDA combination product review streamlining for sclerotherapy-integrated systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device erosion extends regulatory timelines for incremental modifications. |
| CE Marking Pathway | EU MDR clinical evaluation reports force costly data generation for coil recertification. |
| Hospital System Partnership | Fertility clinic direct procurement relationships bypass traditional GPO contracts. |
| Software Companion Development | Telemedicine-enabled preoperative screening expands addressable patient populations. |
| Reimbursement Strategy | Medicare code consolidation for ambulatory migration determines pricing flexibility. |
Study Parameters
Initial hypotheses were tested against primary input from interventional radiologists, reproductive urologists, hospital purchasing committee members, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA clinical evaluation reports, CMS Medicare reimbursement databases, and Japanese PMDA approval records. Bottom-up procedural volume estimates triangulated with top-down device procurement data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment modality, end-user facility type, application indication, and anesthesia delivery mode. CAGRs derived from historical procedural migration patterns and reimbursement trajectory analysis. Forecast inputs incorporated fluoroscopy suite capital expenditure cycles and fertility clinic specialization rates.
Macroeconomic conditions sit as an overlay; deviation in precious metal prices or interventional radiology workforce expansion would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and payer migration timelines. Material shifts in EU MDR enforcement intensity or PMDA combination product review streamlining would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Ureterorenoscopes Market
Urology
Urology Disposables Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Prostate Cancer Treatment Market
Urology
Global Bladder Cancer Market
Urology
Pyelonephritis Treatment Market
Urology
Renal Cyst Treatment Market
Urology
Urinary Incontinence Market
Urology
Ureteral Catheters Market
Urology
Urethral Stricture Market
Urology
Transrectal Ultrasound Market
Urology
North America Bladder Disorders Market
Urology
North America Transrectal Ultrasound Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urinary Tract Infection Testing Market